

#fedproposesrulesforbankissuedstablecoins
fedproposesrulesforbankissuedstablecoins
31,105 views
643 Discussing
Hot
Latest
·
--
#fedproposesrulesforbankissuedstablecoins
🏦 Macro Alert: The Fed Enters the Stablecoin Arena with Proposed Issuer Rules! 💵⚖️
The Federal Reserve officially unveiled two major regulatory proposals to implement the GENIUS Act (Guiding and Establishing National Innovation for U.S. Stablecoins), establishing strict reserve, operational, and capital standards for bank-issued payment stablecoins.
📌 Breakdown of Key Proposed Fed Rules
💵 1:1 Reserve Mandate: All Fed-supervised payment stablecoin issuers must fully back every $1 token with high-quality permissible reserve assets, including cash, Federal Reserve balances, short-term U.S. Treasuries (maturities ≤ 93 days), and qualifying repo agreements.
⏱️ Mandatory 2-Day Redemptions: Tokens must generally be redeemable at par value within two business days. If reserves fall short, issuers must notify the Fed and execute a remediation plan or immediately liquidate reserves to redeem token holders.
📊 Operational Risk Capital Charges: The proposal enforces standardized capital charges to guard against credit and operational risks—set at 2% on the first $20 Billion in outstanding stablecoins, 1.5% on the next $30 Billion, and 1% on amounts exceeding $50 Billion.
🏦 Bank Subsidiary Application Process: A separate rule outlines a structured application workflow for state member banks seeking to establish dedicated subsidiaries to issue payment stablecoins, featuring a mandatory 120-day Fed decision window upon complete application submission.
⚖️ Wall Street vs. Crypto Native Stablecoins (USDT & USDC)
Competition for Market Share: As commercial banks roll out yield-compliant or bank-backed stablecoins under federal law, established non-bank issuers like Tether ($USDT) and Circle ($USDC) face tighter compliance benchmarks in U.S. markets.
DeFi Liquidity Shift: While federal backing increases trust for institutional settlement, strict reserve limitations and 2-day redemption rules could bifurcate global crypto liquidity between regulated U.S.
#FedOctoberRateHikeOddsRiseTo69.7%
#fedproposesrulesforbankissuedstablecoins
🏦 Macro Alert: The Fed Enters the Stablecoin Arena with Proposed Issuer Rules! 💵⚖️
The Federal Reserve officially unveiled two major regulatory proposals to implement the GENIUS Act (Guiding and Establishing National Innovation for U.S. Stablecoins), establishing strict reserve, operational, and capital standards for bank-issued payment stablecoins.
📌 Breakdown of Key Proposed Fed Rules
💵 1:1 Reserve Mandate: All Fed-supervised payment stablecoin issuers must fully back every $1 token with high-quality permissible reserve assets, including cash, Federal Reserve balances, short-term U.S. Treasuries (maturities ≤ 93 days), and qualifying repo agreements.
⏱️ Mandatory 2-Day Redemptions: Tokens must generally be redeemable at par value within two business days. If reserves fall short, issuers must notify the Fed and execute a remediation plan or immediately liquidate reserves to redeem token holders.
📊 Operational Risk Capital Charges: The proposal enforces standardized capital charges to guard against credit and operational risks—set at 2% on the first $20 Billion in outstanding stablecoins, 1.5% on the next $30 Billion, and 1% on amounts exceeding $50 Billion.
🏦 Bank Subsidiary Application Process: A separate rule outlines a structured application workflow for state member banks seeking to establish dedicated subsidiaries to issue payment stablecoins, featuring a mandatory 120-day Fed decision window upon complete application submission.
⚖️ Wall Street vs. Crypto Native Stablecoins (USDT & USDC)
Competition for Market Share: As commercial banks roll out yield-compliant or bank-backed stablecoins under federal law, established non-bank issuers like Tether ($USDT) and Circle ($USDC) face tighter compliance benchmarks in U.S. markets.
DeFi Liquidity Shift: While federal backing increases trust for institutional settlement, strict reserve limitations and 2-day redemption rules could bifurcate global crypto liquidity between regulated U.S.
#FedOctoberRateHikeOddsRiseTo69.7%
🏦 Macro Alert: The Fed Enters the Stablecoin Arena with Proposed Issuer Rules! 💵⚖️
The Federal Reserve officially unveiled two major regulatory proposals to implement the GENIUS Act (Guiding and Establishing National Innovation for U.S. Stablecoins), establishing strict reserve, operational, and capital standards for bank-issued payment stablecoins.
📌 Breakdown of Key Proposed Fed Rules
💵 1:1 Reserve Mandate: All Fed-supervised payment stablecoin issuers must fully back every $1 token with high-quality permissible reserve assets, including cash, Federal Reserve balances, short-term U.S. Treasuries (maturities ≤ 93 days), and qualifying repo agreements.
⏱️ Mandatory 2-Day Redemptions: Tokens must generally be redeemable at par value within two business days. If reserves fall short, issuers must notify the Fed and execute a remediation plan or immediately liquidate reserves to redeem token holders.
📊 Operational Risk Capital Charges: The proposal enforces standardized capital charges to guard against credit and operational risks—set at 2% on the first $20 Billion in outstanding stablecoins, 1.5% on the next $30 Billion, and 1% on amounts exceeding $50 Billion.
🏦 Bank Subsidiary Application Process: A separate rule outlines a structured application workflow for state member banks seeking to establish dedicated subsidiaries to issue payment stablecoins, featuring a mandatory 120-day Fed decision window upon complete application submission.
⚖️ Wall Street vs. Crypto Native Stablecoins (USDT & USDC)
Competition for Market Share: As commercial banks roll out yield-compliant or bank-backed stablecoins under federal law, established non-bank issuers like Tether ($USDT) and Circle ($USDC) face tighter compliance benchmarks in U.S. markets.
DeFi Liquidity Shift: While federal backing increases trust for institutional settlement, strict reserve limitations and 2-day redemption rules could bifurcate global crypto liquidity between regulated U.S.
#FedOctoberRateHikeOddsRiseTo69.7%
x mee:
nice place follow me back
1
2
5.3k
·
--
Article
The Fed Just Put Real Rules Behind The Word "Fully Backed"#fedproposesrulesforbankissuedstablecoins
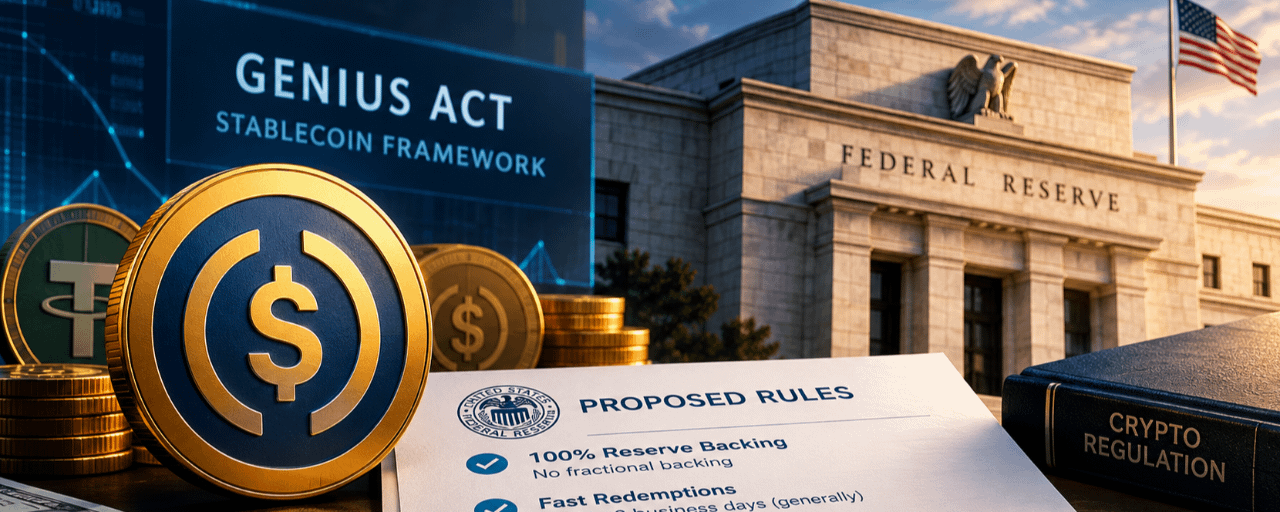
For years, "fully backed" has been a phrase stablecoin issuers used freely — the Federal Reserve just proposed making it a legal requirement with teeth.
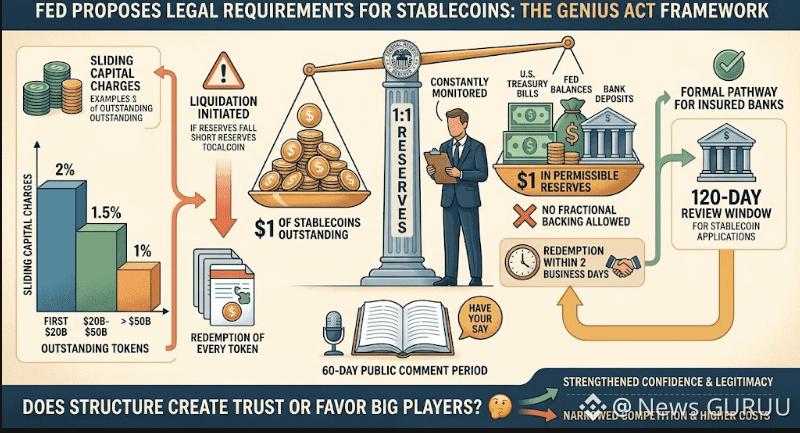
Here's what was announced: on September 24, the Fed unveiled two proposed rules implementing the GENIUS Act framework for payment stablecoins. The first requires Fed-supervised issuers to hold at least $1 in permissible reserves — things like short-term Treasury bills, Fed balances, and certain bank deposits — for every $1 of stablecoins outstanding, with no fractional backing allowed. Redemptions would generally need to be honored within two business days, and issuers would face a sliding capital charge, starting at 2% on their first $20 billion in outstanding tokens and stepping down to 1% above $50 billion. If an issuer's reserves fall short and stay short past a set period, the rule calls for full liquidation of reserves and redemption of every outstanding token — no exceptions built in. A second, companion proposal creates a formal pathway for insured banks to launch stablecoin subsidiaries through the Fed, with a 120-day review window once an application is deemed complete. Both proposals are open for public comment for 60 days before anything is finalized.
Why does this matter? This is regulators translating "stability" from a marketing term into enforceable mechanics — full reserve backing, hard redemption timelines, and a real capital cushion tied directly to issuer size. For an industry still working to earn trust from traditional finance, having a defined rulebook — even a strict one — can be a meaningful step toward legitimacy and broader institutional adoption. At the same time, tighter capital and liquidation requirements could raise the cost of doing business for smaller or newer issuers, potentially reshaping who's able to compete at scale.
Whether these rules end up strengthening confidence in stablecoins or simply narrowing the field to a handful of well-capitalized players is something the 60-day comment period — and beyond — will help clarify.
Does more regulatory structure make stablecoins more trustworthy, or does it just favor the biggest players who can absorb the compliance cost? 🤔
#Stablecoins #GENIUSAct #FederalReserve #CryptoRegulation
$QNT $ONDO $XPL
{future}(XPLUSDT)
{future}(ONDOUSDT)
{future}(QNTUSDT)
The Fed Just Put Real Rules Behind The Word "Fully Backed"
#fedproposesrulesforbankissuedstablecoins
For years, "fully backed" has been a phrase stablecoin issuers used freely — the Federal Reserve just proposed making it a legal requirement with teeth.
Here's what was announced: on September 24, the Fed unveiled two proposed rules implementing the GENIUS Act framework for payment stablecoins. The first requires Fed-supervised issuers to hold at least $1 in permissible reserves — things like short-term Treasury bills, Fed balances, and certain bank deposits — for every $1 of stablecoins outstanding, with no fractional backing allowed. Redemptions would generally need to be honored within two business days, and issuers would face a sliding capital charge, starting at 2% on their first $20 billion in outstanding tokens and stepping down to 1% above $50 billion. If an issuer's reserves fall short and stay short past a set period, the rule calls for full liquidation of reserves and redemption of every outstanding token — no exceptions built in. A second, companion proposal creates a formal pathway for insured banks to launch stablecoin subsidiaries through the Fed, with a 120-day review window once an application is deemed complete. Both proposals are open for public comment for 60 days before anything is finalized.
Why does this matter? This is regulators translating "stability" from a marketing term into enforceable mechanics — full reserve backing, hard redemption timelines, and a real capital cushion tied directly to issuer size. For an industry still working to earn trust from traditional finance, having a defined rulebook — even a strict one — can be a meaningful step toward legitimacy and broader institutional adoption. At the same time, tighter capital and liquidation requirements could raise the cost of doing business for smaller or newer issuers, potentially reshaping who's able to compete at scale.
Whether these rules end up strengthening confidence in stablecoins or simply narrowing the field to a handful of well-capitalized players is something the 60-day comment period — and beyond — will help clarify.
Does more regulatory structure make stablecoins more trustworthy, or does it just favor the biggest players who can absorb the compliance cost? 🤔
#Stablecoins #GENIUSAct #FederalReserve #CryptoRegulation
$QNT $ONDO $XPL
For years, "fully backed" has been a phrase stablecoin issuers used freely — the Federal Reserve just proposed making it a legal requirement with teeth.
Here's what was announced: on September 24, the Fed unveiled two proposed rules implementing the GENIUS Act framework for payment stablecoins. The first requires Fed-supervised issuers to hold at least $1 in permissible reserves — things like short-term Treasury bills, Fed balances, and certain bank deposits — for every $1 of stablecoins outstanding, with no fractional backing allowed. Redemptions would generally need to be honored within two business days, and issuers would face a sliding capital charge, starting at 2% on their first $20 billion in outstanding tokens and stepping down to 1% above $50 billion. If an issuer's reserves fall short and stay short past a set period, the rule calls for full liquidation of reserves and redemption of every outstanding token — no exceptions built in. A second, companion proposal creates a formal pathway for insured banks to launch stablecoin subsidiaries through the Fed, with a 120-day review window once an application is deemed complete. Both proposals are open for public comment for 60 days before anything is finalized.
Why does this matter? This is regulators translating "stability" from a marketing term into enforceable mechanics — full reserve backing, hard redemption timelines, and a real capital cushion tied directly to issuer size. For an industry still working to earn trust from traditional finance, having a defined rulebook — even a strict one — can be a meaningful step toward legitimacy and broader institutional adoption. At the same time, tighter capital and liquidation requirements could raise the cost of doing business for smaller or newer issuers, potentially reshaping who's able to compete at scale.
Whether these rules end up strengthening confidence in stablecoins or simply narrowing the field to a handful of well-capitalized players is something the 60-day comment period — and beyond — will help clarify.
Does more regulatory structure make stablecoins more trustworthy, or does it just favor the biggest players who can absorb the compliance cost? 🤔
#Stablecoins #GENIUSAct #FederalReserve #CryptoRegulation
$QNT $ONDO $XPL
3
2.2k
·
--
#fedproposesrulesforbankissuedstablecoins
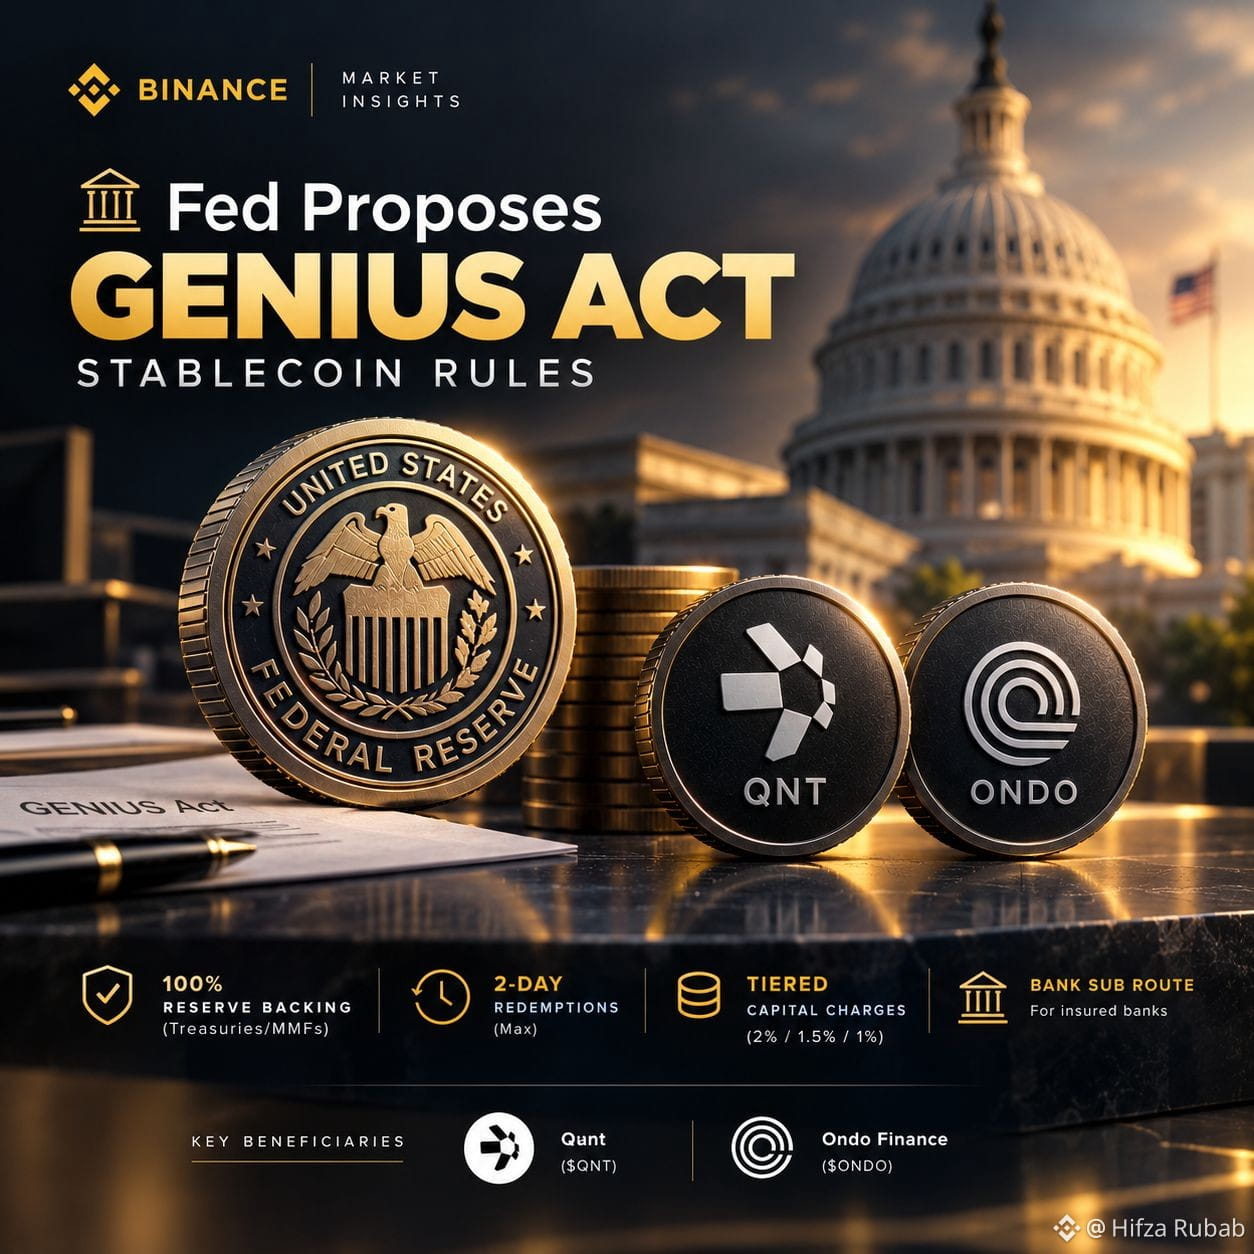
🏛️ Fed Proposes GENIUS Act Stablecoin Rules 💳🌐🚀
The US Federal Reserve 🏛️ has unveiled two major proposed rules under the GENIUS Act 📑:
100% Reserve Backing: Full liquid asset backing 💵 (Treasuries/MMFs) with monthly audits 📊 and CEO/CFO certification 📝.
Max 2-Day Redemptions: Issuers must process redemption requests within two business days ⏱️.
Tiered Capital Charges: 2% capital charge on the first $20B, 1.5% on the next $30B, and 1% above $50B 💰.
Bank Sub Route: Gives insured banks 🏦 a formal approval process to issue payment stablecoins via subsidiaries ⚡.
Key Beneficiaries🪙:
Quant ($QNT ) 🌐: Interoperability layer connecting traditional banks with tokenized assets.
Ondo Finance ($ONDO ) 🏛️: Real-world asset (RWA) protocol benefiting from institutional tokenized Treasuries.
💬 What's your take? Will strict compliance build Wall Street trust 🎯 or block smaller Web3 issuers 🛑? Drop your thoughts below! 👇✨
#FedProposesRulesForBankIssuedStablecoins
#BinanceWillListHyperliquid(HYPE)
#CFTCUpdatesGuidanceOnTokenizedAssets
#BitcoinFallsBelow$83,000
{spot}(ONDOUSDT)
{spot}(QNTUSDT)
#fedproposesrulesforbankissuedstablecoins
🏛️ Fed Proposes GENIUS Act Stablecoin Rules 💳🌐🚀
The US Federal Reserve 🏛️ has unveiled two major proposed rules under the GENIUS Act 📑:
100% Reserve Backing: Full liquid asset backing 💵 (Treasuries/MMFs) with monthly audits 📊 and CEO/CFO certification 📝.
Max 2-Day Redemptions: Issuers must process redemption requests within two business days ⏱️.
Tiered Capital Charges: 2% capital charge on the first $20B, 1.5% on the next $30B, and 1% above $50B 💰.
Bank Sub Route: Gives insured banks 🏦 a formal approval process to issue payment stablecoins via subsidiaries ⚡.
Key Beneficiaries🪙:
Quant ($QNT ) 🌐: Interoperability layer connecting traditional banks with tokenized assets.
Ondo Finance ($ONDO ) 🏛️: Real-world asset (RWA) protocol benefiting from institutional tokenized Treasuries.
💬 What's your take? Will strict compliance build Wall Street trust 🎯 or block smaller Web3 issuers 🛑? Drop your thoughts below! 👇✨
#FedProposesRulesForBankIssuedStablecoins
#BinanceWillListHyperliquid(HYPE)
#CFTCUpdatesGuidanceOnTokenizedAssets
#BitcoinFallsBelow$83,000
🏛️ Fed Proposes GENIUS Act Stablecoin Rules 💳🌐🚀
The US Federal Reserve 🏛️ has unveiled two major proposed rules under the GENIUS Act 📑:
100% Reserve Backing: Full liquid asset backing 💵 (Treasuries/MMFs) with monthly audits 📊 and CEO/CFO certification 📝.
Max 2-Day Redemptions: Issuers must process redemption requests within two business days ⏱️.
Tiered Capital Charges: 2% capital charge on the first $20B, 1.5% on the next $30B, and 1% above $50B 💰.
Bank Sub Route: Gives insured banks 🏦 a formal approval process to issue payment stablecoins via subsidiaries ⚡.
Key Beneficiaries🪙:
Quant ($QNT ) 🌐: Interoperability layer connecting traditional banks with tokenized assets.
Ondo Finance ($ONDO ) 🏛️: Real-world asset (RWA) protocol benefiting from institutional tokenized Treasuries.
💬 What's your take? Will strict compliance build Wall Street trust 🎯 or block smaller Web3 issuers 🛑? Drop your thoughts below! 👇✨
#FedProposesRulesForBankIssuedStablecoins
#BinanceWillListHyperliquid(HYPE)
#CFTCUpdatesGuidanceOnTokenizedAssets
#BitcoinFallsBelow$83,000
区块链球王 777:
Join my live 👇🏻
1
7
4.1k
💵 $1 Backing Gets Focus
New Fed proposals would require covered stablecoin issuers to maintain qualifying reserves.
Short-term Treasury bills and other highly liquid assets are among the proposed reserves.
Banks seeking to issue stablecoins would also face an application process.
$BTC $ETH $SOL and $BNB remain major spot-market assets.
🔎 The next chapter of digital payments is taking shape.
#fedproposesrulesforbankissuedstablecoins
💵 $1 Backing Gets Focus
New Fed proposals would require covered stablecoin issuers to maintain qualifying reserves.
Short-term Treasury bills and other highly liquid assets are among the proposed reserves.
Banks seeking to issue stablecoins would also face an application process.
$BTC $ETH $SOL and $BNB remain major spot-market assets.
🔎 The next chapter of digital payments is taking shape.
#fedproposesrulesforbankissuedstablecoins
New Fed proposals would require covered stablecoin issuers to maintain qualifying reserves.
Short-term Treasury bills and other highly liquid assets are among the proposed reserves.
Banks seeking to issue stablecoins would also face an application process.
$BTC $ETH $SOL and $BNB remain major spot-market assets.
🔎 The next chapter of digital payments is taking shape.
#fedproposesrulesforbankissuedstablecoins
1
580

·
--
Have you noticed how everyone treats bank-regulated stablecoins as the ultimate validation for crypto, while completely ignoring who actually loses in that scenario?
Most retail investors park their capital in liquidity pools and yield protocols without realizing how fast institutional rails can drain that volume once compliance walls go up. Getting caught holding unapproved assets during a sudden regulatory reshuffle is a fast track to getting your yield crushed.
Look at what is unfolding with the latest Fed framework for bank-issued stablecoins. The mainstream assumption is that Wall Street entering the settlement layer lifts the entire ecosystem equally. In reality, traditional banks issuing their own pegged tokens will not integrate with permissionless DeFi; they will build walled gardens that directly siphon market share from crypto-native staples like $USDT and synthetic yield designs like $ENA.
When regulated depository institutions capture stablecoin reserve yield backed directly by short-term Treasuries, the risk-reward equation changes overnight. Capital always migrates toward the path of least legal friction, especially when institutional desks demand ring-fenced collateral over decentralized alternatives.
Where do you think liquidity flows once tier-one banks launch their own pegged assets?
#FedProposesRulesForBankIssuedStablecoins #FedOctoberRateHikeOddsRiseTo69
Have you noticed how everyone treats bank-regulated stablecoins as the ultimate validation for crypto, while completely ignoring who actually loses in that scenario?
Most retail investors park their capital in liquidity pools and yield protocols without realizing how fast institutional rails can drain that volume once compliance walls go up. Getting caught holding unapproved assets during a sudden regulatory reshuffle is a fast track to getting your yield crushed.
Look at what is unfolding with the latest Fed framework for bank-issued stablecoins. The mainstream assumption is that Wall Street entering the settlement layer lifts the entire ecosystem equally. In reality, traditional banks issuing their own pegged tokens will not integrate with permissionless DeFi; they will build walled gardens that directly siphon market share from crypto-native staples like $USDT and synthetic yield designs like $ENA .
When regulated depository institutions capture stablecoin reserve yield backed directly by short-term Treasuries, the risk-reward equation changes overnight. Capital always migrates toward the path of least legal friction, especially when institutional desks demand ring-fenced collateral over decentralized alternatives.
Where do you think liquidity flows once tier-one banks launch their own pegged assets?
#FedProposesRulesForBankIssuedStablecoins #FedOctoberRateHikeOddsRiseTo69
Most retail investors park their capital in liquidity pools and yield protocols without realizing how fast institutional rails can drain that volume once compliance walls go up. Getting caught holding unapproved assets during a sudden regulatory reshuffle is a fast track to getting your yield crushed.
Look at what is unfolding with the latest Fed framework for bank-issued stablecoins. The mainstream assumption is that Wall Street entering the settlement layer lifts the entire ecosystem equally. In reality, traditional banks issuing their own pegged tokens will not integrate with permissionless DeFi; they will build walled gardens that directly siphon market share from crypto-native staples like $USDT and synthetic yield designs like $ENA .
When regulated depository institutions capture stablecoin reserve yield backed directly by short-term Treasuries, the risk-reward equation changes overnight. Capital always migrates toward the path of least legal friction, especially when institutional desks demand ring-fenced collateral over decentralized alternatives.
Where do you think liquidity flows once tier-one banks launch their own pegged assets?
#FedProposesRulesForBankIssuedStablecoins #FedOctoberRateHikeOddsRiseTo69
90
·
--
#fedproposesrulesforbankissuedstablecoins
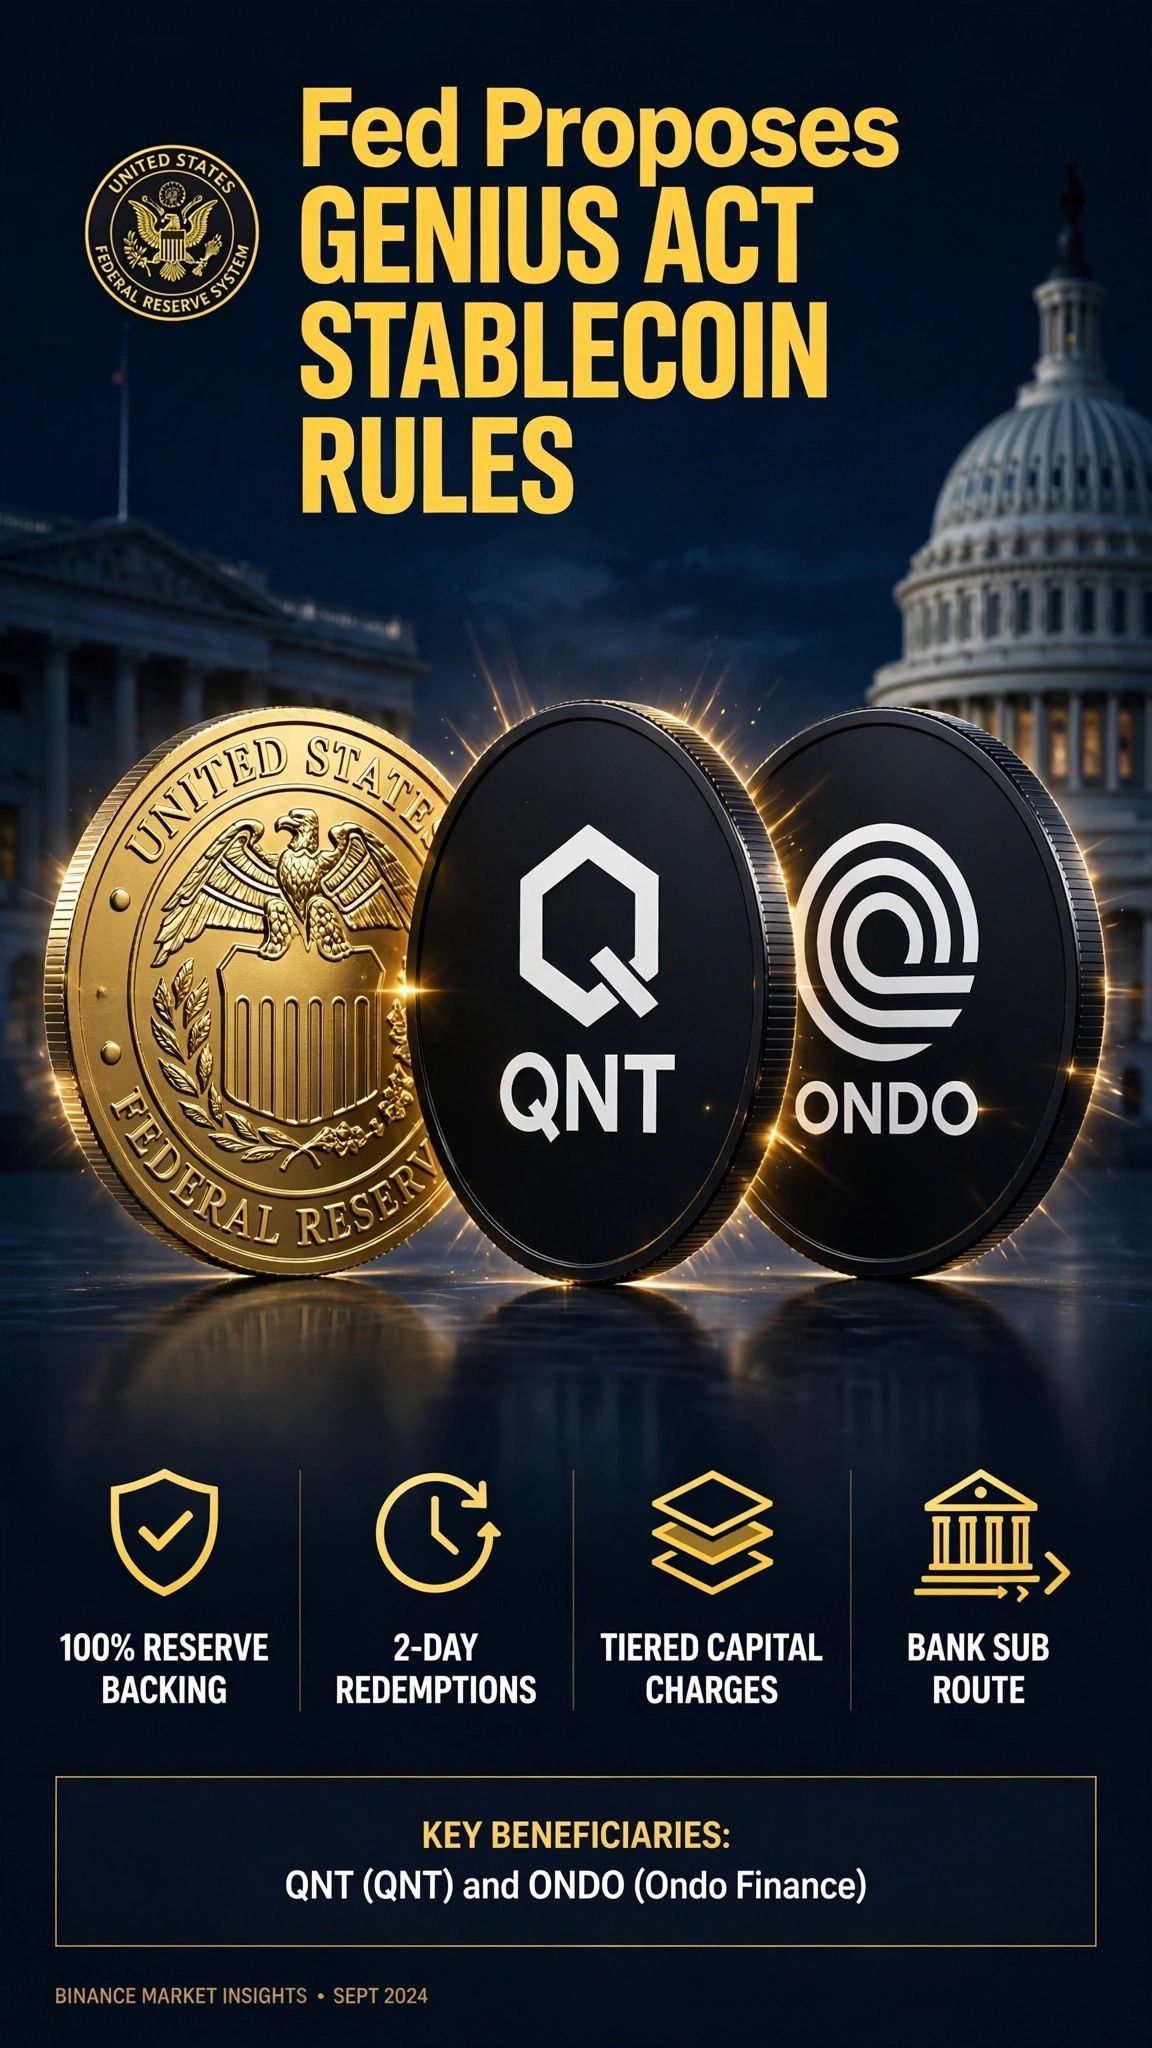
🏛️ Fed Proposes GENIUS ACT Stablecoin Rules
The Fed unveils 2 new rules under GENIUS Act:
✅ 100% Reserve Backing
✅ 2-Day Redemptions
✅ Tiered Capital Charges (2%/1.5%/1%)
✅ Bank Subsidiary Route
🔥 HOT COINS: $QNT & $ONDO
QNT for bank settlements | ONDO for tokenized Treasuries
Biggest step for regulated crypto in US. 60-day comment open.
#GENIUSAct #QNT #ONDO #Stablecoins#GrayscaleZcashETFHits$1BNetAssets #NYAndPolymarketSueEachOther #BrazilOrdersReportingOf$10KSelfCustodyTransfers #FedProposesRulesForBankIssuedStablecoins
#fedproposesrulesforbankissuedstablecoins
🏛️ Fed Proposes GENIUS ACT Stablecoin Rules
The Fed unveils 2 new rules under GENIUS Act:
✅ 100% Reserve Backing
✅ 2-Day Redemptions
✅ Tiered Capital Charges (2%/1.5%/1%)
✅ Bank Subsidiary Route
🔥 HOT COINS: $QNT & $ONDO
QNT for bank settlements | ONDO for tokenized Treasuries
Biggest step for regulated crypto in US. 60-day comment open.
#GENIUSAct #QNT #ONDO #Stablecoins#GrayscaleZcashETFHits$1BNetAssets #NYAndPolymarketSueEachOther #BrazilOrdersReportingOf$10KSelfCustodyTransfers #FedProposesRulesForBankIssuedStablecoins
🏛️ Fed Proposes GENIUS ACT Stablecoin Rules
The Fed unveils 2 new rules under GENIUS Act:
✅ 100% Reserve Backing
✅ 2-Day Redemptions
✅ Tiered Capital Charges (2%/1.5%/1%)
✅ Bank Subsidiary Route
🔥 HOT COINS: $QNT & $ONDO
QNT for bank settlements | ONDO for tokenized Treasuries
Biggest step for regulated crypto in US. 60-day comment open.
#GENIUSAct #QNT #ONDO #Stablecoins#GrayscaleZcashETFHits$1BNetAssets #NYAndPolymarketSueEachOther #BrazilOrdersReportingOf$10KSelfCustodyTransfers #FedProposesRulesForBankIssuedStablecoins
Hassan zaib:
follow me please
4
2
326

·
--
Bullish
#fedproposesrulesforbankissuedstablecoins
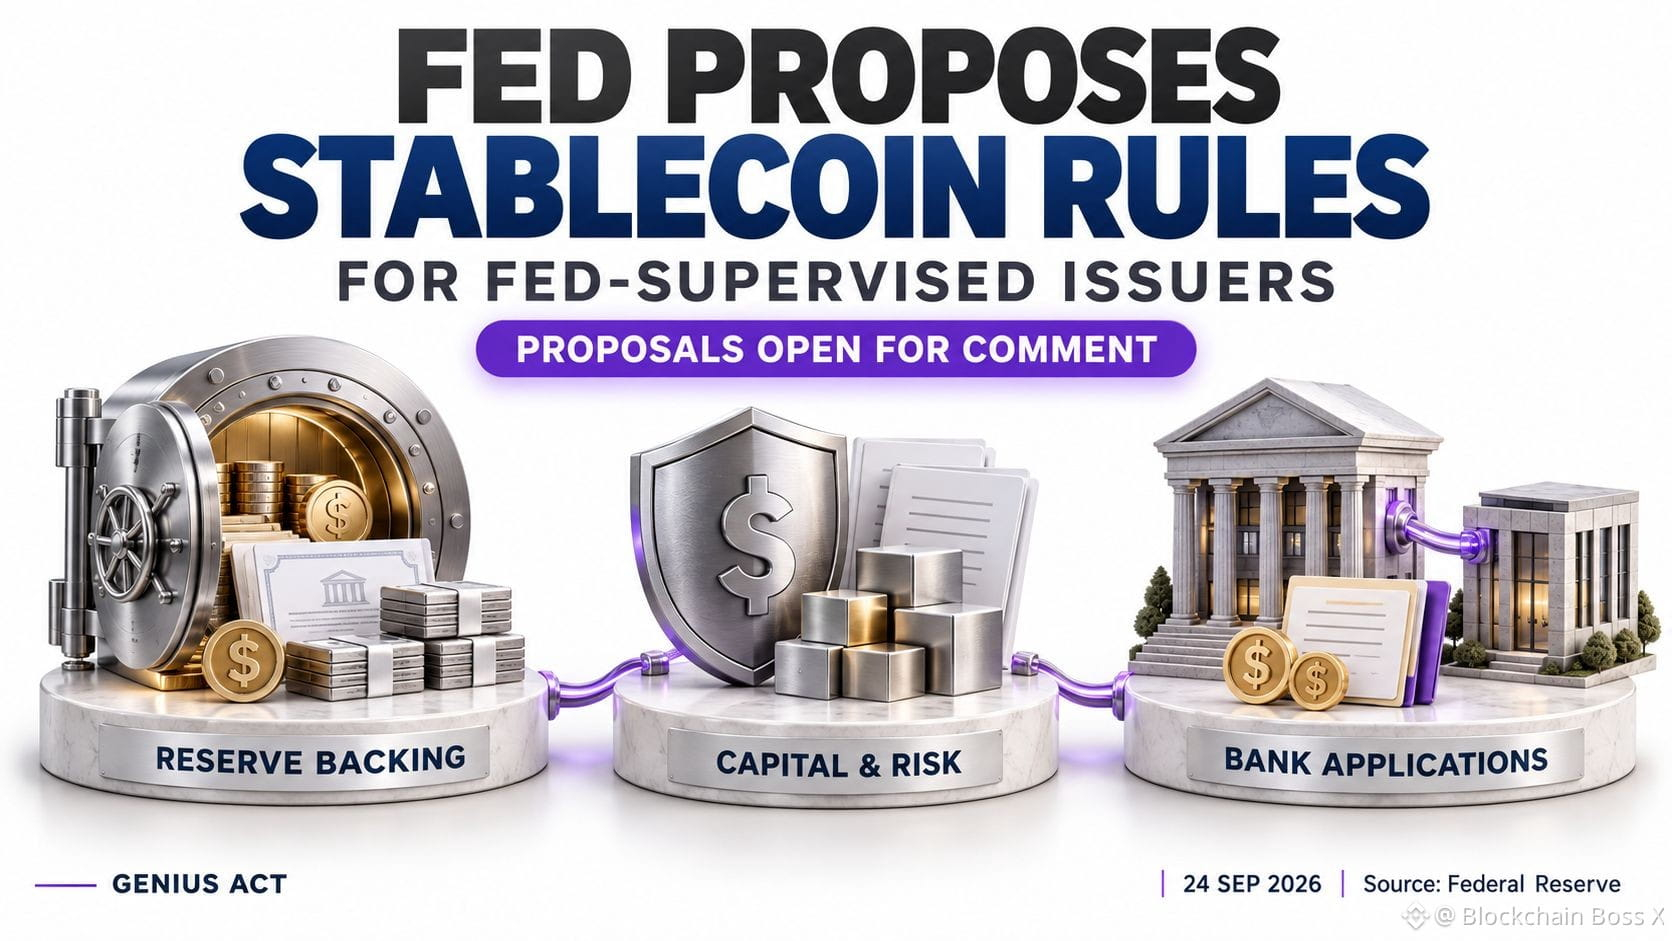
Fed Proposes Stablecoin Rules: What Would Change for Banks?
On September 24, the Federal Reserve released two proposals under the GENIUS Act for payment stablecoin issuers under its supervision.
The first would require full backing with eligible liquid reserves, including short-term Treasury bills. It also outlines capital requirements, risk management standards and rules for safeguarding reserve assets.
The second would establish an application process for supervised banks seeking approval for subsidiaries to issue stablecoins, including submitting business plans and financial information.
These remain proposals. Public comments are due 60 days after publication in the Federal Register.
My take: A clearer approval process could help banks plan stablecoin services with greater confidence. However, reserve and capital requirements would also influence operating costs, product pricing and which institutions find issuance commercially worthwhile.
For users, the practical test is reliable redemption: can they get their money back promptly, including during market stress? Governor Michael Barr specifically emphasized that concern in his response to the proposals.
I’d watch final redemption protections, reserve disclosures and actual bank launches. Clearer rules could support adoption, while payment usage, fees and customer experience would reveal whether these services deliver practical improvements.
Would you choose a bank-issued stablecoin based on the issuer’s reputation, or would redemption terms and fees matter more?
#FedProposesRulesForBankIssuedStablecoins #Stablecoins #GENIUSAct
$BTC $ETH $BNB
{future}(BNBUSDT)
{future}(ETHUSDT)
{future}(BTCUSDT)
#fedproposesrulesforbankissuedstablecoins
Fed Proposes Stablecoin Rules: What Would Change for Banks?
On September 24, the Federal Reserve released two proposals under the GENIUS Act for payment stablecoin issuers under its supervision.
The first would require full backing with eligible liquid reserves, including short-term Treasury bills. It also outlines capital requirements, risk management standards and rules for safeguarding reserve assets.
The second would establish an application process for supervised banks seeking approval for subsidiaries to issue stablecoins, including submitting business plans and financial information.
These remain proposals. Public comments are due 60 days after publication in the Federal Register.
My take: A clearer approval process could help banks plan stablecoin services with greater confidence. However, reserve and capital requirements would also influence operating costs, product pricing and which institutions find issuance commercially worthwhile.
For users, the practical test is reliable redemption: can they get their money back promptly, including during market stress? Governor Michael Barr specifically emphasized that concern in his response to the proposals.
I’d watch final redemption protections, reserve disclosures and actual bank launches. Clearer rules could support adoption, while payment usage, fees and customer experience would reveal whether these services deliver practical improvements.
Would you choose a bank-issued stablecoin based on the issuer’s reputation, or would redemption terms and fees matter more?
#FedProposesRulesForBankIssuedStablecoins #Stablecoins #GENIUSAct
$BTC $ETH $BNB
Fed Proposes Stablecoin Rules: What Would Change for Banks?
On September 24, the Federal Reserve released two proposals under the GENIUS Act for payment stablecoin issuers under its supervision.
The first would require full backing with eligible liquid reserves, including short-term Treasury bills. It also outlines capital requirements, risk management standards and rules for safeguarding reserve assets.
The second would establish an application process for supervised banks seeking approval for subsidiaries to issue stablecoins, including submitting business plans and financial information.
These remain proposals. Public comments are due 60 days after publication in the Federal Register.
My take: A clearer approval process could help banks plan stablecoin services with greater confidence. However, reserve and capital requirements would also influence operating costs, product pricing and which institutions find issuance commercially worthwhile.
For users, the practical test is reliable redemption: can they get their money back promptly, including during market stress? Governor Michael Barr specifically emphasized that concern in his response to the proposals.
I’d watch final redemption protections, reserve disclosures and actual bank launches. Clearer rules could support adoption, while payment usage, fees and customer experience would reveal whether these services deliver practical improvements.
Would you choose a bank-issued stablecoin based on the issuer’s reputation, or would redemption terms and fees matter more?
#FedProposesRulesForBankIssuedStablecoins #Stablecoins #GENIUSAct
$BTC $ETH $BNB
2
1.8k
·
--
Verified
💵 The Fed just drew a line through America's future digital-dollar market...
#fedproposesrulesforbankissuedstablecoins
Its new GENIUS Act proposals would require Board-supervised payment-stablecoin issuers to fully back tokens with permitted assets such as short-term Treasuries, while imposing capital, risk-management and reserve-custody rules.
But here's what gets missed:
This doesn't automatically regulate every “digital dollar” the same way.
The GENIUS Act's payment-stablecoin definition is specific — and Ethena's own filings describe USDe as a synthetic dollar, while ENA is a governance token.
That's important because Ethena is now trying to own the distribution layer too.
Ethena Pay says its balances are USDe and explicitly calls the product a distribution channel for Ethena's dollar ecosystem.
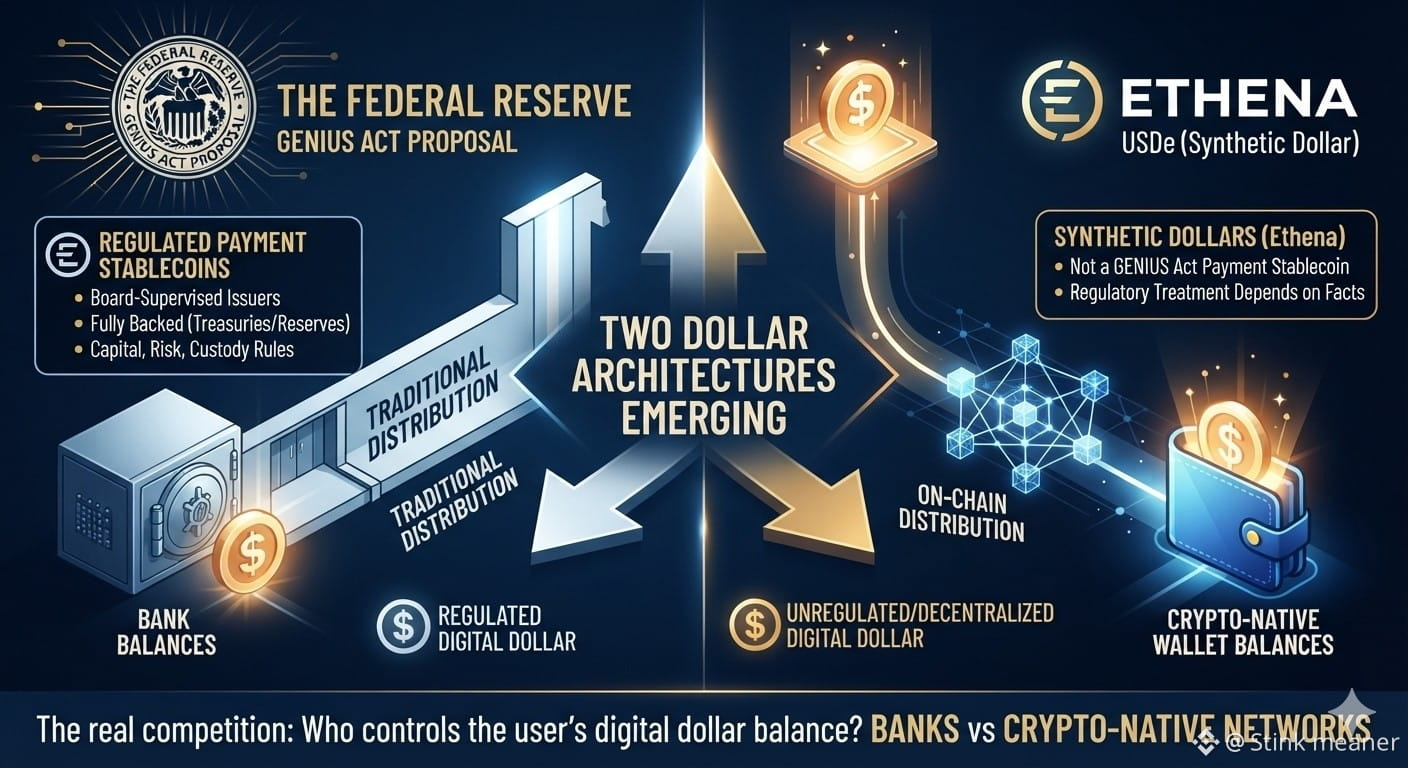
So we could be watching two dollar architectures emerge:
BANKS → regulated payment stablecoins → traditional distribution
CRYPTO-NATIVE → synthetic dollars → on-chain distribution
The real competition may not be “stablecoin vs stablecoin.”
It may be who controls the user's digital dollar balance — banks or crypto-native networks.
Not financial advice. USDe is not being characterized here as a GENIUS Act payment stablecoin; its regulatory treatment can depend on the final rules and facts. A regulatory framework does not guarantee ENA demand or value.
$ENA $QNT $BTC
{future}(ENAUSDT)
#FedProposesRulesForBankIssuedStablecoins #GENIUSActPass #Stablecoins #FederalReserve
💵 The Fed just drew a line through America's future digital-dollar market...
#fedproposesrulesforbankissuedstablecoins
Its new GENIUS Act proposals would require Board-supervised payment-stablecoin issuers to fully back tokens with permitted assets such as short-term Treasuries, while imposing capital, risk-management and reserve-custody rules.
But here's what gets missed:
This doesn't automatically regulate every “digital dollar” the same way.
The GENIUS Act's payment-stablecoin definition is specific — and Ethena's own filings describe USDe as a synthetic dollar, while ENA is a governance token.
That's important because Ethena is now trying to own the distribution layer too.
Ethena Pay says its balances are USDe and explicitly calls the product a distribution channel for Ethena's dollar ecosystem.
So we could be watching two dollar architectures emerge:
BANKS → regulated payment stablecoins → traditional distribution
CRYPTO-NATIVE → synthetic dollars → on-chain distribution
The real competition may not be “stablecoin vs stablecoin.”
It may be who controls the user's digital dollar balance — banks or crypto-native networks.
Not financial advice. USDe is not being characterized here as a GENIUS Act payment stablecoin; its regulatory treatment can depend on the final rules and facts. A regulatory framework does not guarantee ENA demand or value.
$ENA $QNT $BTC
#FedProposesRulesForBankIssuedStablecoins #GENIUSActPass #Stablecoins #FederalReserve
#fedproposesrulesforbankissuedstablecoins
Its new GENIUS Act proposals would require Board-supervised payment-stablecoin issuers to fully back tokens with permitted assets such as short-term Treasuries, while imposing capital, risk-management and reserve-custody rules.
But here's what gets missed:
This doesn't automatically regulate every “digital dollar” the same way.
The GENIUS Act's payment-stablecoin definition is specific — and Ethena's own filings describe USDe as a synthetic dollar, while ENA is a governance token.
That's important because Ethena is now trying to own the distribution layer too.
Ethena Pay says its balances are USDe and explicitly calls the product a distribution channel for Ethena's dollar ecosystem.
So we could be watching two dollar architectures emerge:
BANKS → regulated payment stablecoins → traditional distribution
CRYPTO-NATIVE → synthetic dollars → on-chain distribution
The real competition may not be “stablecoin vs stablecoin.”
It may be who controls the user's digital dollar balance — banks or crypto-native networks.
Not financial advice. USDe is not being characterized here as a GENIUS Act payment stablecoin; its regulatory treatment can depend on the final rules and facts. A regulatory framework does not guarantee ENA demand or value.
$ENA $QNT $BTC
#FedProposesRulesForBankIssuedStablecoins #GENIUSActPass #Stablecoins #FederalReserve
4
3k
·
--
Bearish
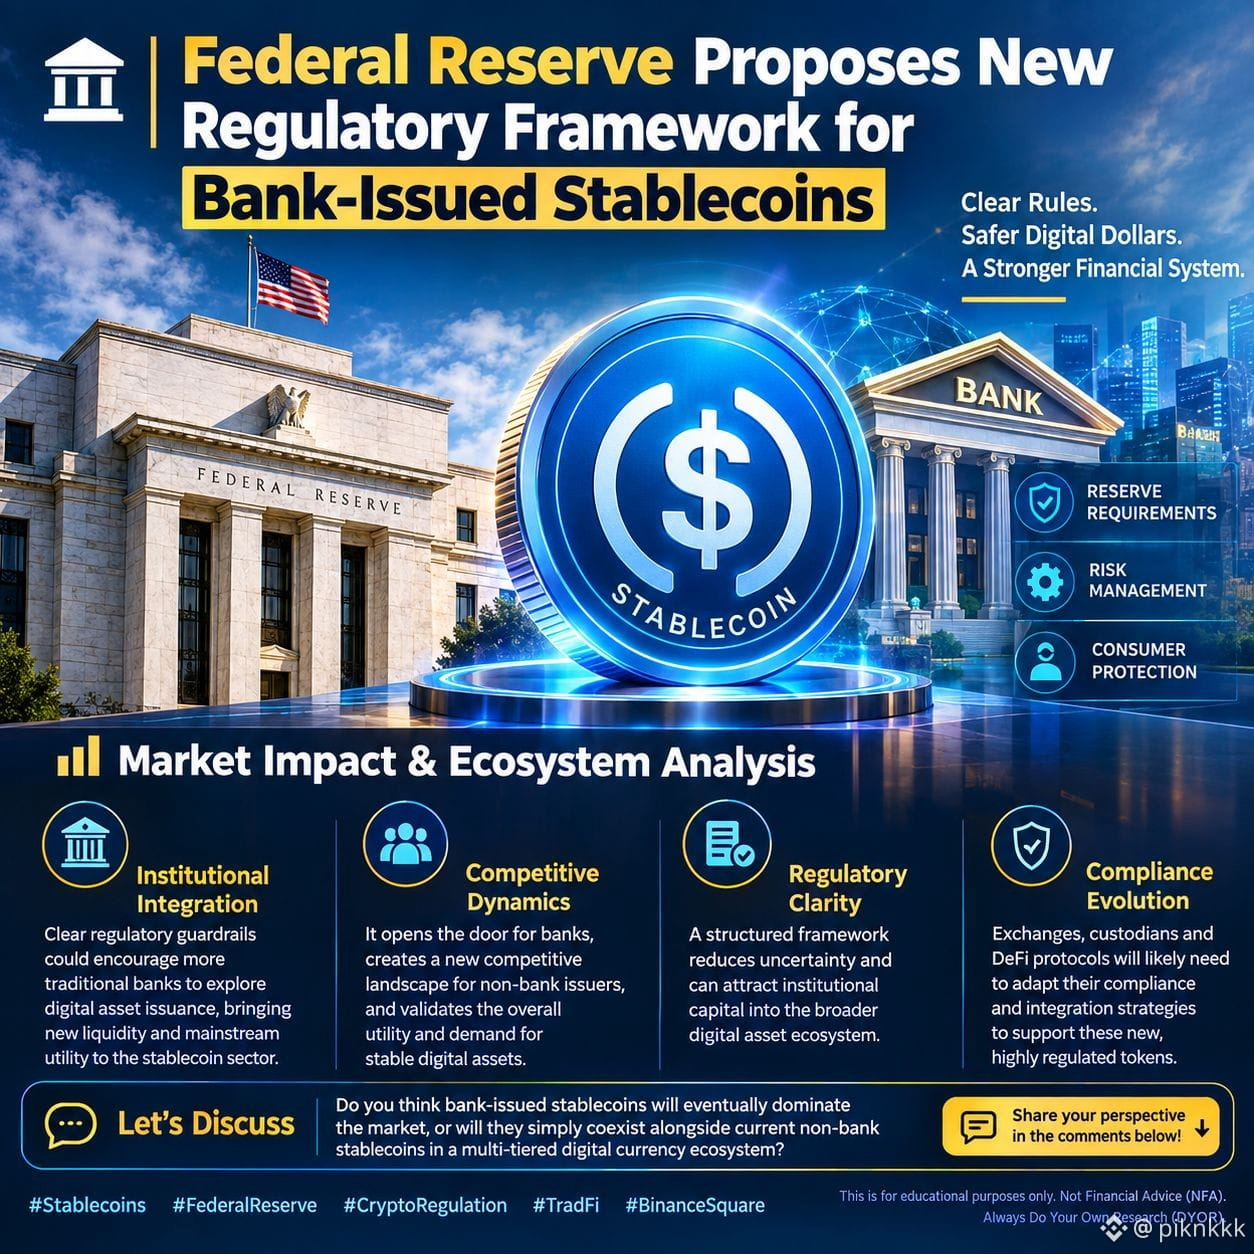
#fedproposesrulesforbankissuedstablecoins 🏦 Federal Reserve Proposes New Regulatory Framework for Bank-Issued Stablecoins
The U.S. Federal Reserve has officially requested public comment on a comprehensive regulatory framework for bank-supervised payment stablecoin issuers. This marks a pivotal step toward institutional clarity in the digital asset space.
Core News
Under the proposed rules tied to the ongoing GENIUS Act implementation the Fed has outlined clear guidelines for regulated stablecoin issuance [10]
1:1 Asset Backing Stablecoins must be fully backed by high-quality liquid assets such as short-term U.S. Treasury bills [10]
📊Tiered Capital Requirements Operational risk capital is scaled based on circulation volume (2% for the first $20B 1.5% for the next $30B and 1% for volumes exceeding $50B) [7]
Strict Redemption & Reporting Issuers must fulfill redemption requests within two business days and provide monthly, auditor verified reserve reports [7]
Tailored Bank Applications A formalized process for Fed-supervised banks to apply for issuing stablecoins through subsidiaries, requiring detailed business plans and financial disclosures [10]
📈 Market Impact
This proposal brings much-needed regulatory clarity to the digital asset ecosystem. By establishing standardized risk management and reserve requirements it is likely to boost institutional confidence in regulated, bank-backed stablecoins. However the high compliance bar may also accelerate market consolidation favoring well capitalized traditional financial institutions while challenging smaller non-bank issuers to adapt.
Join the Discussion
Do you think bank-issued stablecoins will successfully bridge Traditional Finance (TradFi) and Decentralized Finance (DeFi) or will strict regulatory requirements stifle innovation? Share your thoughts below
#Stablecoins #FederalReserve #CryptoRegulation #TradFi #BinanceSquare
This is for educational purposes only. Not Financial Advice (NFA). Always Do Your Own Research (DYOR).
$SAGA $LSK
{future}(LSKUSDT)
{future}(SAGAUSDT)
#fedproposesrulesforbankissuedstablecoins 🏦 Federal Reserve Proposes New Regulatory Framework for Bank-Issued Stablecoins
The U.S. Federal Reserve has officially requested public comment on a comprehensive regulatory framework for bank-supervised payment stablecoin issuers. This marks a pivotal step toward institutional clarity in the digital asset space.
Core News
Under the proposed rules tied to the ongoing GENIUS Act implementation the Fed has outlined clear guidelines for regulated stablecoin issuance [10]
1:1 Asset Backing Stablecoins must be fully backed by high-quality liquid assets such as short-term U.S. Treasury bills [10]
📊Tiered Capital Requirements Operational risk capital is scaled based on circulation volume (2% for the first $20B 1.5% for the next $30B and 1% for volumes exceeding $50B) [7]
Strict Redemption & Reporting Issuers must fulfill redemption requests within two business days and provide monthly, auditor verified reserve reports [7]
Tailored Bank Applications A formalized process for Fed-supervised banks to apply for issuing stablecoins through subsidiaries, requiring detailed business plans and financial disclosures [10]
📈 Market Impact
This proposal brings much-needed regulatory clarity to the digital asset ecosystem. By establishing standardized risk management and reserve requirements it is likely to boost institutional confidence in regulated, bank-backed stablecoins. However the high compliance bar may also accelerate market consolidation favoring well capitalized traditional financial institutions while challenging smaller non-bank issuers to adapt.
Join the Discussion
Do you think bank-issued stablecoins will successfully bridge Traditional Finance (TradFi) and Decentralized Finance (DeFi) or will strict regulatory requirements stifle innovation? Share your thoughts below
#Stablecoins #FederalReserve #CryptoRegulation #TradFi #BinanceSquare
This is for educational purposes only. Not Financial Advice (NFA). Always Do Your Own Research (DYOR).
$SAGA $LSK
The U.S. Federal Reserve has officially requested public comment on a comprehensive regulatory framework for bank-supervised payment stablecoin issuers. This marks a pivotal step toward institutional clarity in the digital asset space.
Core News
Under the proposed rules tied to the ongoing GENIUS Act implementation the Fed has outlined clear guidelines for regulated stablecoin issuance [10]
1:1 Asset Backing Stablecoins must be fully backed by high-quality liquid assets such as short-term U.S. Treasury bills [10]
📊Tiered Capital Requirements Operational risk capital is scaled based on circulation volume (2% for the first $20B 1.5% for the next $30B and 1% for volumes exceeding $50B) [7]
Strict Redemption & Reporting Issuers must fulfill redemption requests within two business days and provide monthly, auditor verified reserve reports [7]
Tailored Bank Applications A formalized process for Fed-supervised banks to apply for issuing stablecoins through subsidiaries, requiring detailed business plans and financial disclosures [10]
📈 Market Impact
This proposal brings much-needed regulatory clarity to the digital asset ecosystem. By establishing standardized risk management and reserve requirements it is likely to boost institutional confidence in regulated, bank-backed stablecoins. However the high compliance bar may also accelerate market consolidation favoring well capitalized traditional financial institutions while challenging smaller non-bank issuers to adapt.
Join the Discussion
Do you think bank-issued stablecoins will successfully bridge Traditional Finance (TradFi) and Decentralized Finance (DeFi) or will strict regulatory requirements stifle innovation? Share your thoughts below
#Stablecoins #FederalReserve #CryptoRegulation #TradFi #BinanceSquare
This is for educational purposes only. Not Financial Advice (NFA). Always Do Your Own Research (DYOR).
$SAGA $LSK
·
--
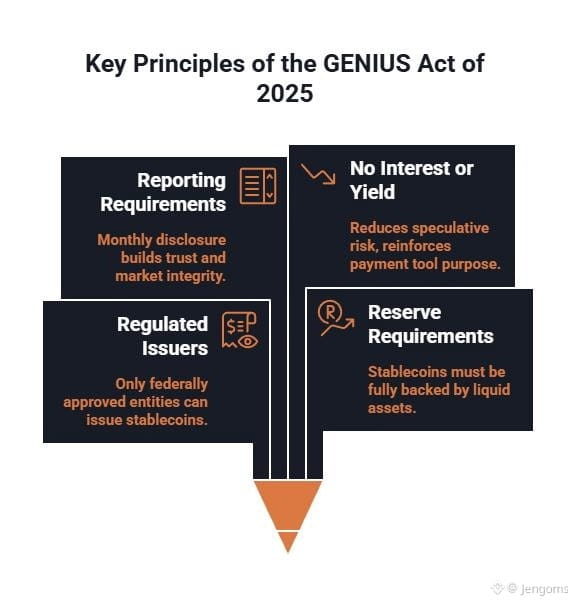
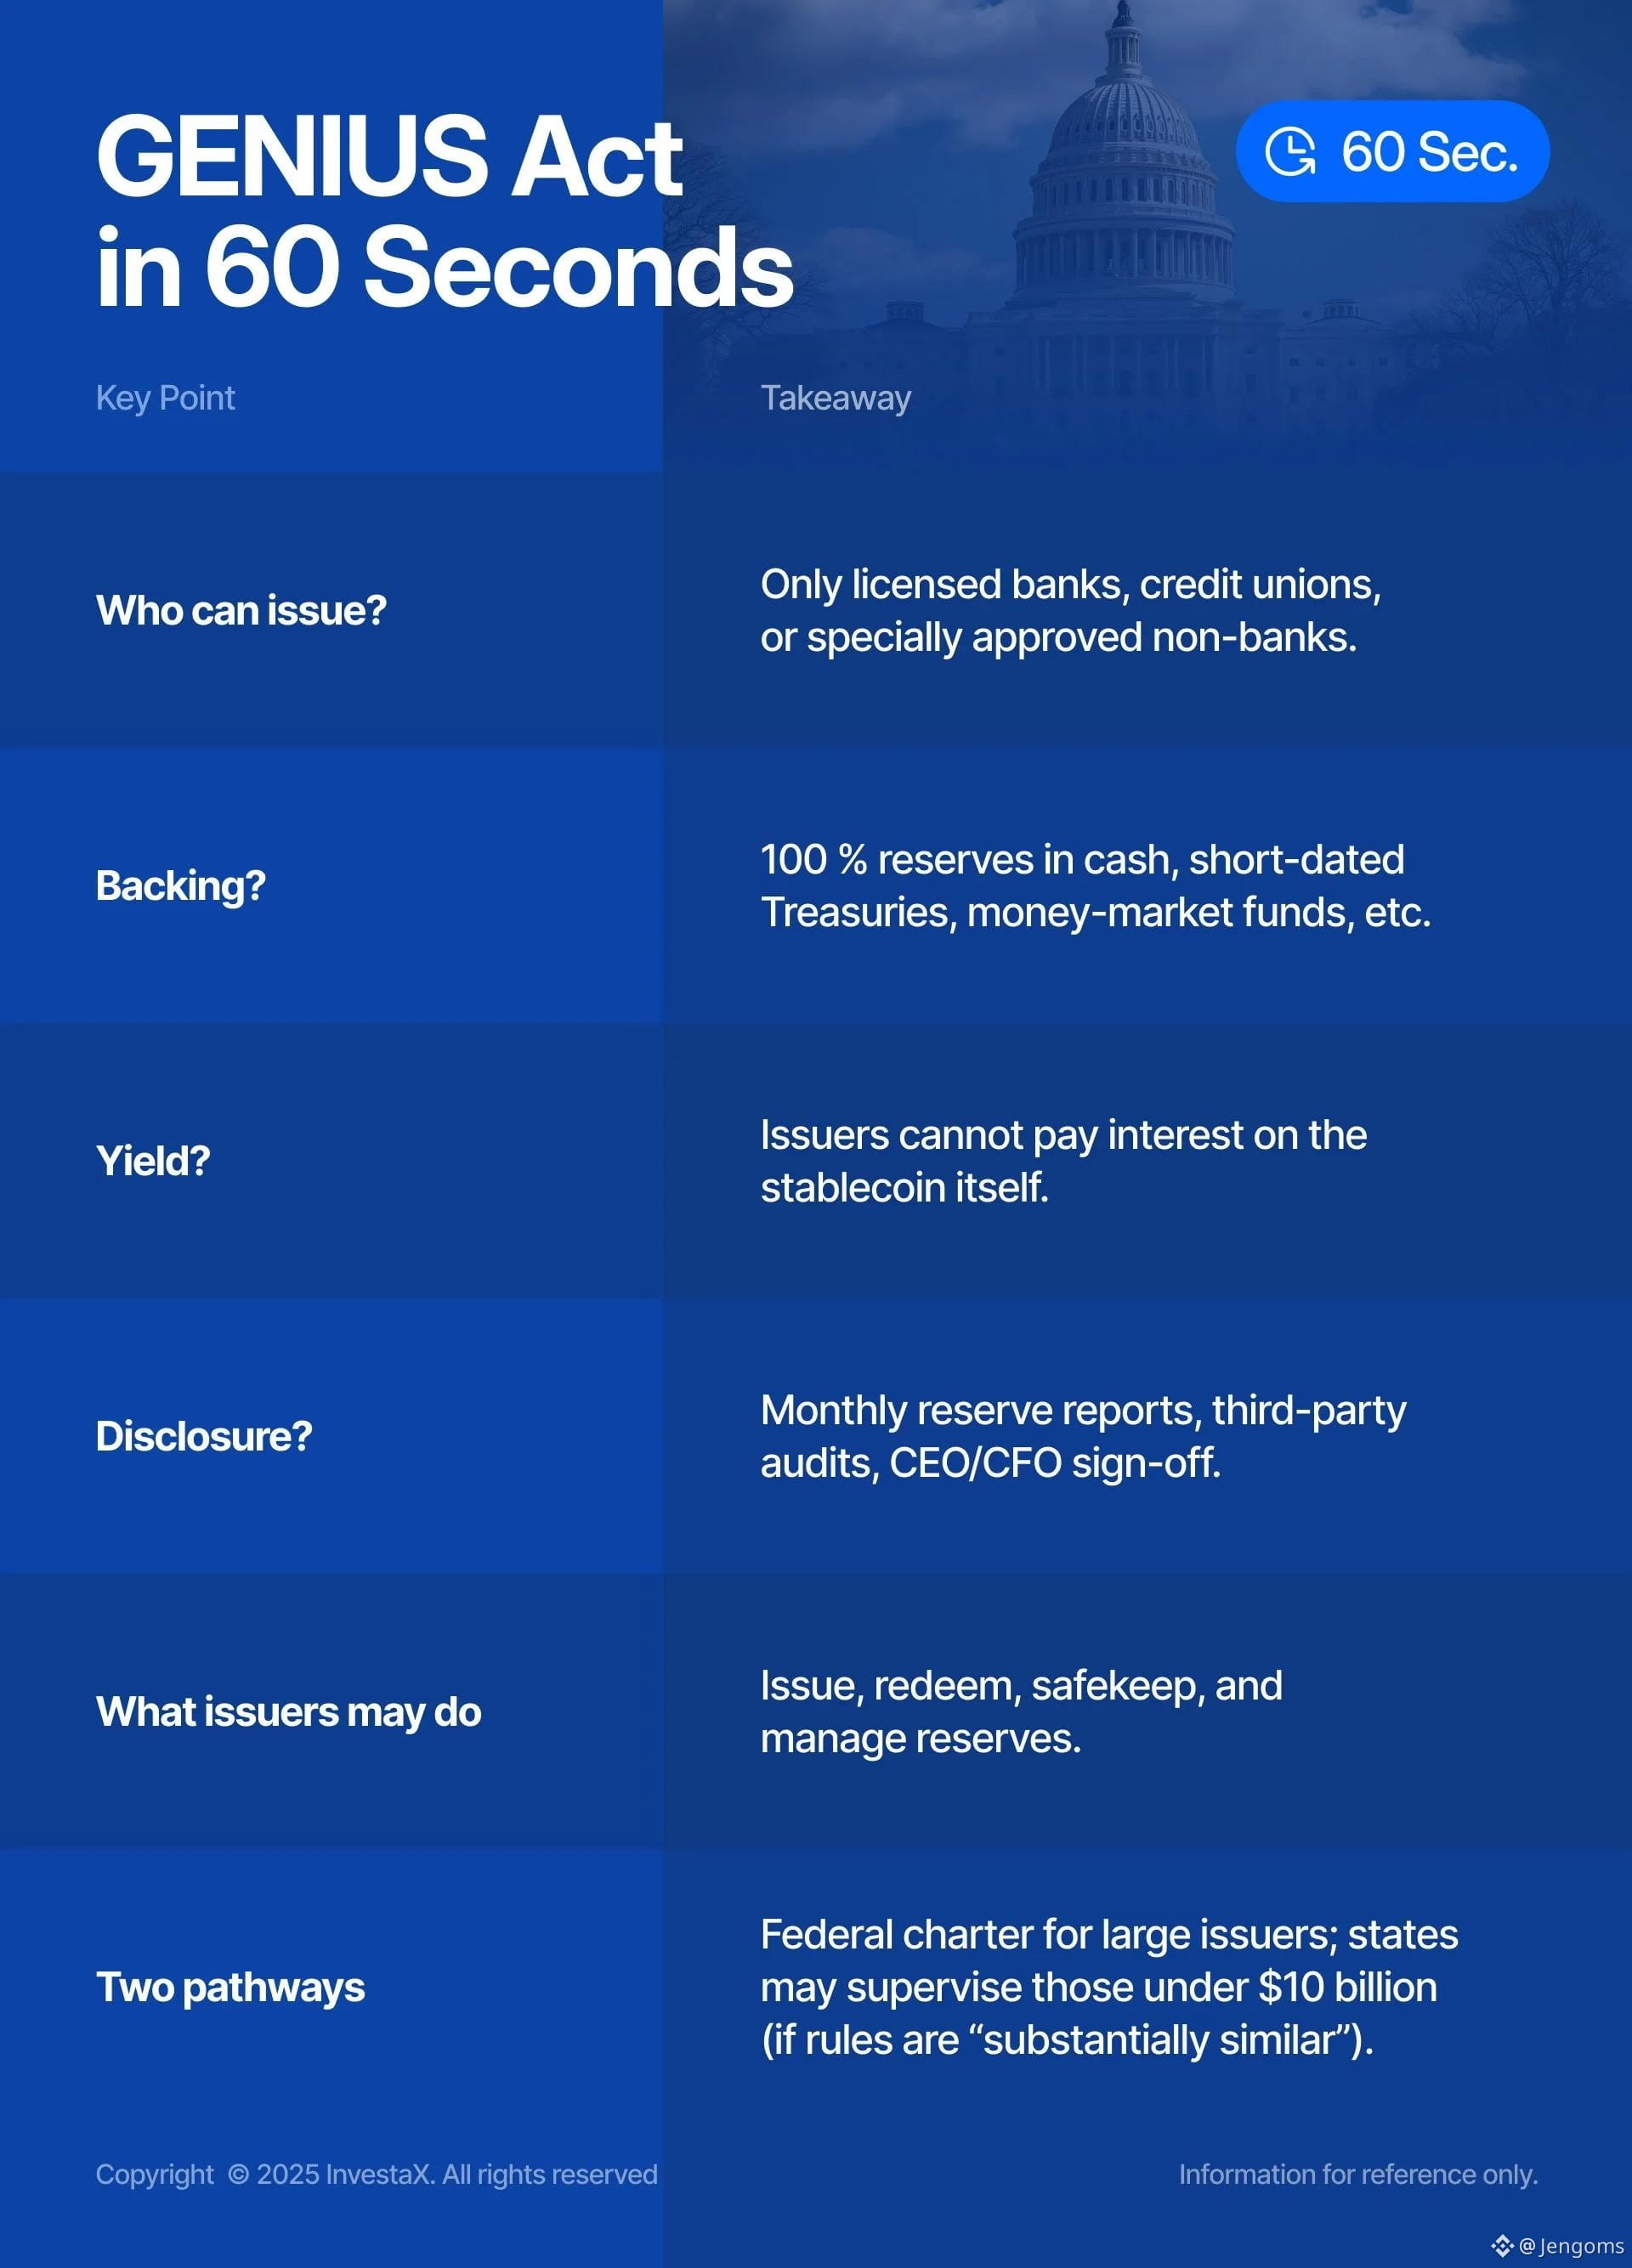
🚨 FED DROPS BIG STABLECOIN RULEBOOK
The U.S. Federal Reserve proposed new rules for Fed-supervised stablecoin issuers, including 1:1 reserve backing, capital requirements, risk-management standards, and a new application process for banks issuing payment stablecoins. The proposal is part of implementing the GENIUS Act. $ONDO
{spot}(ONDOUSDT)
$USDC
{spot}(USDCUSDT)
#FedProposesRulesForBankIssuedStablecoins #BinanceWillListHyperliquid(HYPE)
FED JUST DROPPED A BIG STABLECOIN RULEBOOK
💵 1:1 Reserve Backing
🏦 Bank Issuers Face New Rules
📊 Capital & Risk Requirements
🇺🇸 GENIUS Act Implementation
⏳ Public comments open for 60 days.
🚨 FED DROPS BIG STABLECOIN RULEBOOK
The U.S. Federal Reserve proposed new rules for Fed-supervised stablecoin issuers, including 1:1 reserve backing, capital requirements, risk-management standards, and a new application process for banks issuing payment stablecoins. The proposal is part of implementing the GENIUS Act. $ONDO
$USDC
#FedProposesRulesForBankIssuedStablecoins #BinanceWillListHyperliquid(HYPE)
FED JUST DROPPED A BIG STABLECOIN RULEBOOK
💵 1:1 Reserve Backing
🏦 Bank Issuers Face New Rules
📊 Capital & Risk Requirements
🇺🇸 GENIUS Act Implementation
⏳ Public comments open for 60 days.
The U.S. Federal Reserve proposed new rules for Fed-supervised stablecoin issuers, including 1:1 reserve backing, capital requirements, risk-management standards, and a new application process for banks issuing payment stablecoins. The proposal is part of implementing the GENIUS Act. $ONDO
$USDC
#FedProposesRulesForBankIssuedStablecoins #BinanceWillListHyperliquid(HYPE)
FED JUST DROPPED A BIG STABLECOIN RULEBOOK
💵 1:1 Reserve Backing
🏦 Bank Issuers Face New Rules
📊 Capital & Risk Requirements
🇺🇸 GENIUS Act Implementation
⏳ Public comments open for 60 days.
1
87

Picture this: Wall Street giants have spent years watching offshore stablecoins capture billions in market share, and now the Federal Reserve is finally laying down the blueprint for traditional banks to enter the arena.
Most crypto investors know the constant anxiety of regulatory crackdowns wiping out liquidity or depegging assets overnight. Holding dry powder shouldn't feel like a high-stakes gamble every time policy headlines hit the wire.
Think back to how the stablecoin landscape evolved from early crypto-native experiments to giants like $USDT dominating global volume. For years, authorities responded with enforcement rather than clear frameworks. This new Fed proposal shifts the playbook, offering regulated commercial banks a structured lane to issue digital cash backed by strict reserve audits and direct central bank oversight.
It sets up an interesting split when compared to synthetic and decentralized models like $ENA. Regulated bank tokens will likely bring unmatched institutional safety and direct corporate settlement rails, but they will also carry strict identity compliance and zero native yield. Decentralized alternatives will continue to compete on capital efficiency and permissionless access.
Rather than wiping out crypto liquidity, bank-issued stablecoins might actually validate the settlement technology on a trillion-dollar scale, dividing the market into regulated institutional cash and crypto-native utility tokens.
Where do you think this goes from here once traditional banks officially launch their own tokens?
#FedProposesRulesForBankIssuedStablecoins #FedOctoberRateHikeOddsRiseTo69
Picture this: Wall Street giants have spent years watching offshore stablecoins capture billions in market share, and now the Federal Reserve is finally laying down the blueprint for traditional banks to enter the arena.
Most crypto investors know the constant anxiety of regulatory crackdowns wiping out liquidity or depegging assets overnight. Holding dry powder shouldn't feel like a high-stakes gamble every time policy headlines hit the wire.
Think back to how the stablecoin landscape evolved from early crypto-native experiments to giants like $USDT dominating global volume. For years, authorities responded with enforcement rather than clear frameworks. This new Fed proposal shifts the playbook, offering regulated commercial banks a structured lane to issue digital cash backed by strict reserve audits and direct central bank oversight.
It sets up an interesting split when compared to synthetic and decentralized models like $ENA . Regulated bank tokens will likely bring unmatched institutional safety and direct corporate settlement rails, but they will also carry strict identity compliance and zero native yield. Decentralized alternatives will continue to compete on capital efficiency and permissionless access.
Rather than wiping out crypto liquidity, bank-issued stablecoins might actually validate the settlement technology on a trillion-dollar scale, dividing the market into regulated institutional cash and crypto-native utility tokens.
Where do you think this goes from here once traditional banks officially launch their own tokens?
#FedProposesRulesForBankIssuedStablecoins #FedOctoberRateHikeOddsRiseTo69
Most crypto investors know the constant anxiety of regulatory crackdowns wiping out liquidity or depegging assets overnight. Holding dry powder shouldn't feel like a high-stakes gamble every time policy headlines hit the wire.
Think back to how the stablecoin landscape evolved from early crypto-native experiments to giants like $USDT dominating global volume. For years, authorities responded with enforcement rather than clear frameworks. This new Fed proposal shifts the playbook, offering regulated commercial banks a structured lane to issue digital cash backed by strict reserve audits and direct central bank oversight.
It sets up an interesting split when compared to synthetic and decentralized models like $ENA . Regulated bank tokens will likely bring unmatched institutional safety and direct corporate settlement rails, but they will also carry strict identity compliance and zero native yield. Decentralized alternatives will continue to compete on capital efficiency and permissionless access.
Rather than wiping out crypto liquidity, bank-issued stablecoins might actually validate the settlement technology on a trillion-dollar scale, dividing the market into regulated institutional cash and crypto-native utility tokens.
Where do you think this goes from here once traditional banks officially launch their own tokens?
#FedProposesRulesForBankIssuedStablecoins #FedOctoberRateHikeOddsRiseTo69
72
·
--
Bullish
#FedProposesRulesForBankIssuedStablecoins
🏦 The Fed is putting real rules behind the words “fully backed.”
On September 24, the Federal Reserve proposed two frameworks under the GENIUS Act for payment stablecoins.
The core requirement: eligible issuers would have to fully back outstanding stablecoins with permitted reserve assets, including short-term Treasuries and other qualifying liquid assets. The proposals also introduce capital and risk-management standards and a formal approval process for supervised banks seeking to issue stablecoins.
The proposals are now open for 60 days of public comment before final rules are adopted.
For crypto markets, this could make stablecoin regulation more defined while also increasing compliance requirements for issuers.
🤔 Will stricter rules accelerate institutional stablecoin adoption—or make it harder for smaller issuers to compete?
TRADE $QNT $ONDO $XPL HERE
{spot}(XPLUSDT)
{spot}(ONDOUSDT)
{spot}(QNTUSDT)
#Stablecoins #GENIUSAct
#FedProposesRulesForBankIssuedStablecoins
🏦 The Fed is putting real rules behind the words “fully backed.”
On September 24, the Federal Reserve proposed two frameworks under the GENIUS Act for payment stablecoins.
The core requirement: eligible issuers would have to fully back outstanding stablecoins with permitted reserve assets, including short-term Treasuries and other qualifying liquid assets. The proposals also introduce capital and risk-management standards and a formal approval process for supervised banks seeking to issue stablecoins.
The proposals are now open for 60 days of public comment before final rules are adopted.
For crypto markets, this could make stablecoin regulation more defined while also increasing compliance requirements for issuers.
🤔 Will stricter rules accelerate institutional stablecoin adoption—or make it harder for smaller issuers to compete?
TRADE $QNT $ONDO $XPL HERE
#Stablecoins #GENIUSAct
🏦 The Fed is putting real rules behind the words “fully backed.”
On September 24, the Federal Reserve proposed two frameworks under the GENIUS Act for payment stablecoins.
The core requirement: eligible issuers would have to fully back outstanding stablecoins with permitted reserve assets, including short-term Treasuries and other qualifying liquid assets. The proposals also introduce capital and risk-management standards and a formal approval process for supervised banks seeking to issue stablecoins.
The proposals are now open for 60 days of public comment before final rules are adopted.
For crypto markets, this could make stablecoin regulation more defined while also increasing compliance requirements for issuers.
🤔 Will stricter rules accelerate institutional stablecoin adoption—or make it harder for smaller issuers to compete?
TRADE $QNT $ONDO $XPL HERE
#Stablecoins #GENIUSAct
1
37
🚨 Banks + Stablecoins
The Fed is proposing a framework for banks under its supervision to issue payment stablecoins.
The rules cover reserves, capital, risk management and safeguarding backing assets.
Public comments will remain open for 60 days after Federal Register publication.
$ETH $LINK $BNB and $AVAX are worth researching across the ecosystem.
📊 Bank-issued digital dollars are getting a clearer regulatory framework.
#fedproposesrulesforbankissuedstablecoins
🚨 Banks + Stablecoins
The Fed is proposing a framework for banks under its supervision to issue payment stablecoins.
The rules cover reserves, capital, risk management and safeguarding backing assets.
Public comments will remain open for 60 days after Federal Register publication.
$ETH $LINK $BNB and $AVAX are worth researching across the ecosystem.
📊 Bank-issued digital dollars are getting a clearer regulatory framework.
#fedproposesrulesforbankissuedstablecoins
The Fed is proposing a framework for banks under its supervision to issue payment stablecoins.
The rules cover reserves, capital, risk management and safeguarding backing assets.
Public comments will remain open for 60 days after Federal Register publication.
$ETH $LINK $BNB and $AVAX are worth researching across the ecosystem.
📊 Bank-issued digital dollars are getting a clearer regulatory framework.
#fedproposesrulesforbankissuedstablecoins
122
·
--
#FedProposesRulesForBankIssuedStablecoins 🏦 Fed Proposes Rules for Bank-Issued Stablecoins
The U.S. Federal Reserve has proposed rules to regulate payment stablecoins issued by banks under the GENIUS Act. �
#FedProposesRulesForBankIssuedStablecoins 🏦 Fed Proposes Rules for Bank-Issued Stablecoins
The U.S. Federal Reserve has proposed rules to regulate payment stablecoins issued by banks under the GENIUS Act. �
The U.S. Federal Reserve has proposed rules to regulate payment stablecoins issued by banks under the GENIUS Act. �
1
1
4
🏦 Fed Stablecoin Rules
The Federal Reserve has proposed new rules for bank-supervised payment stablecoin issuers.
Issuers would need to fully back stablecoins with permitted reserves, including short-term Treasuries.
The proposal also adds capital and risk-management requirements.
$BTC $ETH $BNB and $LINK remain key assets in the broader blockchain ecosystem.
💡 Stablecoin regulation is entering a more detailed phase.
#fedproposesrulesforbankissuedstablecoins
🏦 Fed Stablecoin Rules
The Federal Reserve has proposed new rules for bank-supervised payment stablecoin issuers.
Issuers would need to fully back stablecoins with permitted reserves, including short-term Treasuries.
The proposal also adds capital and risk-management requirements.
$BTC $ETH $BNB and $LINK remain key assets in the broader blockchain ecosystem.
💡 Stablecoin regulation is entering a more detailed phase.
#fedproposesrulesforbankissuedstablecoins
The Federal Reserve has proposed new rules for bank-supervised payment stablecoin issuers.
Issuers would need to fully back stablecoins with permitted reserves, including short-term Treasuries.
The proposal also adds capital and risk-management requirements.
$BTC $ETH $BNB and $LINK remain key assets in the broader blockchain ecosystem.
💡 Stablecoin regulation is entering a more detailed phase.
#fedproposesrulesforbankissuedstablecoins
6
#fedproposesrulesforbankissuedstablecoins
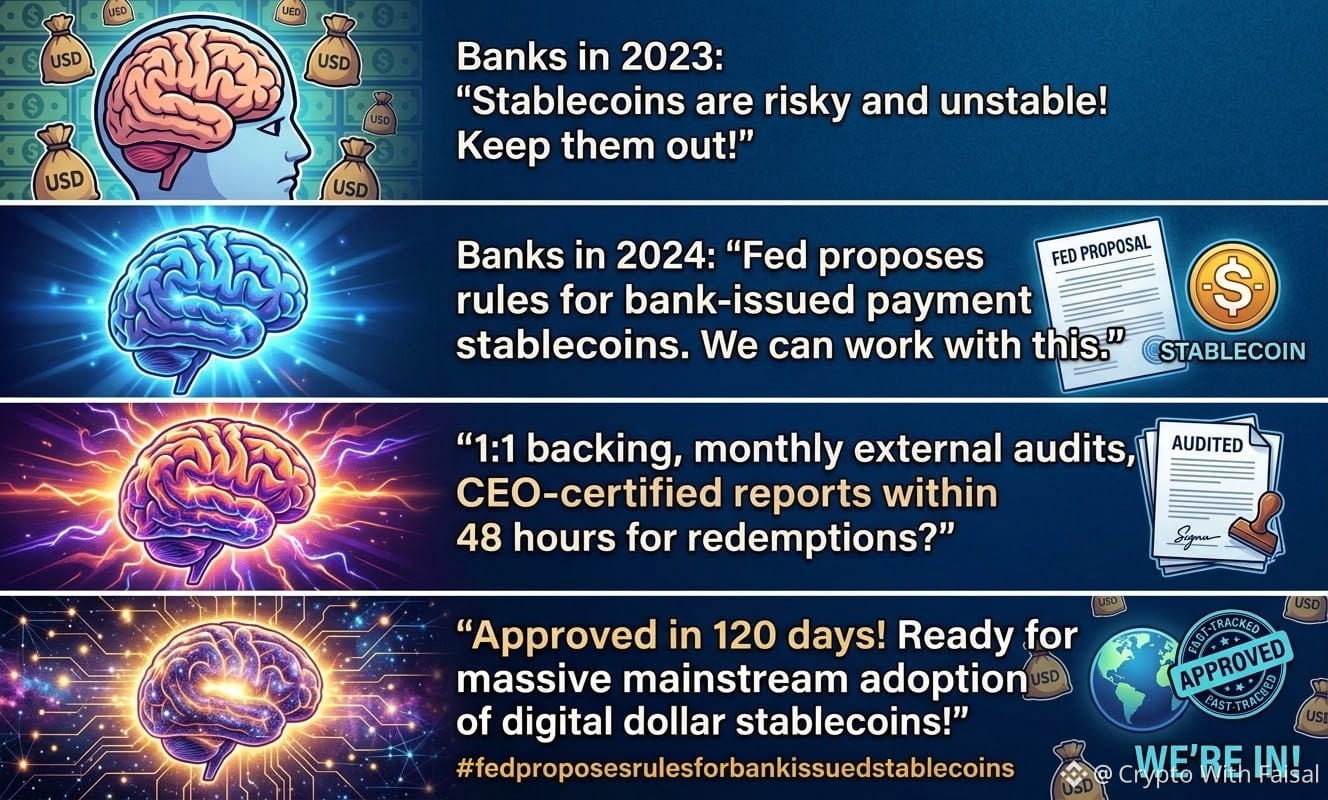
🚨 Fed Drops the Blueprint for Bank-Issued Stablecoins! 🚨
Is the U.S. banking system ready to go full on-chain? The Federal Reserve has proposed its new framework for payment stablecoins under the upcoming GENIUS Act.
Here is what the rulebook looks like:
🔒 1:1 Strict Backing: Every $1 token must be backed 100% by cash, short-term Treasuries (≤93 days), or insured deposits.
⏱️ 48-Hour Cashouts: Redemption requests must be honored within 2 business days. If reserves dip below 1:1, regulators step in immediately to enforce remediation or liquidation.
💰 Capital Buffers: Issuers must hold operational-risk reserve buffers (up to 2% based on volume) to absorb unexpected shocks.
🔎 CEO-Certified Audits: Monthly reserve reports must be audited by external CPAs—and signed off personally by the CEO & CFO.
🏦 Bank Fast-Track: Outlines how state member banks can set up issuance subsidiaries, with the Fed required to rule within 120 days.
This is the bridge connecting TradFi to digital assets ahead of 2027.
👇 Big question: Will bank-issued stablecoins drive true mass adoption, or squeeze out decentralized alternatives? Drop your view!
$BTC
{future}(BTCUSDT)
$BNB
{future}(BNBUSDT)
$SOL
{future}(SOLUSDT)
#Stablecoins #GENIUSAct #FedNews
#fedproposesrulesforbankissuedstablecoins
🚨 Fed Drops the Blueprint for Bank-Issued Stablecoins! 🚨
Is the U.S. banking system ready to go full on-chain? The Federal Reserve has proposed its new framework for payment stablecoins under the upcoming GENIUS Act.
Here is what the rulebook looks like:
🔒 1:1 Strict Backing: Every $1 token must be backed 100% by cash, short-term Treasuries (≤93 days), or insured deposits.
⏱️ 48-Hour Cashouts: Redemption requests must be honored within 2 business days. If reserves dip below 1:1, regulators step in immediately to enforce remediation or liquidation.
💰 Capital Buffers: Issuers must hold operational-risk reserve buffers (up to 2% based on volume) to absorb unexpected shocks.
🔎 CEO-Certified Audits: Monthly reserve reports must be audited by external CPAs—and signed off personally by the CEO & CFO.
🏦 Bank Fast-Track: Outlines how state member banks can set up issuance subsidiaries, with the Fed required to rule within 120 days.
This is the bridge connecting TradFi to digital assets ahead of 2027.
👇 Big question: Will bank-issued stablecoins drive true mass adoption, or squeeze out decentralized alternatives? Drop your view!
$BTC
$BNB
$SOL
#Stablecoins #GENIUSAct #FedNews
🚨 Fed Drops the Blueprint for Bank-Issued Stablecoins! 🚨
Is the U.S. banking system ready to go full on-chain? The Federal Reserve has proposed its new framework for payment stablecoins under the upcoming GENIUS Act.
Here is what the rulebook looks like:
🔒 1:1 Strict Backing: Every $1 token must be backed 100% by cash, short-term Treasuries (≤93 days), or insured deposits.
⏱️ 48-Hour Cashouts: Redemption requests must be honored within 2 business days. If reserves dip below 1:1, regulators step in immediately to enforce remediation or liquidation.
💰 Capital Buffers: Issuers must hold operational-risk reserve buffers (up to 2% based on volume) to absorb unexpected shocks.
🔎 CEO-Certified Audits: Monthly reserve reports must be audited by external CPAs—and signed off personally by the CEO & CFO.
🏦 Bank Fast-Track: Outlines how state member banks can set up issuance subsidiaries, with the Fed required to rule within 120 days.
This is the bridge connecting TradFi to digital assets ahead of 2027.
👇 Big question: Will bank-issued stablecoins drive true mass adoption, or squeeze out decentralized alternatives? Drop your view!
$BTC
$BNB
$SOL
#Stablecoins #GENIUSAct #FedNews
2
243
🌐 Stablecoins Move Deeper Into Banking
The Federal Reserve has opened proposals covering bank-supervised stablecoin issuers.
Covered tokens would need qualifying reserve assets behind them.
The framework also addresses capital requirements and operational risks.
$BTC $ETH $BNB and $SOL remain widely watched crypto assets.
👀 Traditional banking and blockchain payments are moving closer together.
#fedproposesrulesforbankissuedstablecoins
🌐 Stablecoins Move Deeper Into Banking
The Federal Reserve has opened proposals covering bank-supervised stablecoin issuers.
Covered tokens would need qualifying reserve assets behind them.
The framework also addresses capital requirements and operational risks.
$BTC $ETH $BNB and $SOL remain widely watched crypto assets.
👀 Traditional banking and blockchain payments are moving closer together.
#fedproposesrulesforbankissuedstablecoins
The Federal Reserve has opened proposals covering bank-supervised stablecoin issuers.
Covered tokens would need qualifying reserve assets behind them.
The framework also addresses capital requirements and operational risks.
$BTC $ETH $BNB and $SOL remain widely watched crypto assets.
👀 Traditional banking and blockchain payments are moving closer together.
#fedproposesrulesforbankissuedstablecoins
37
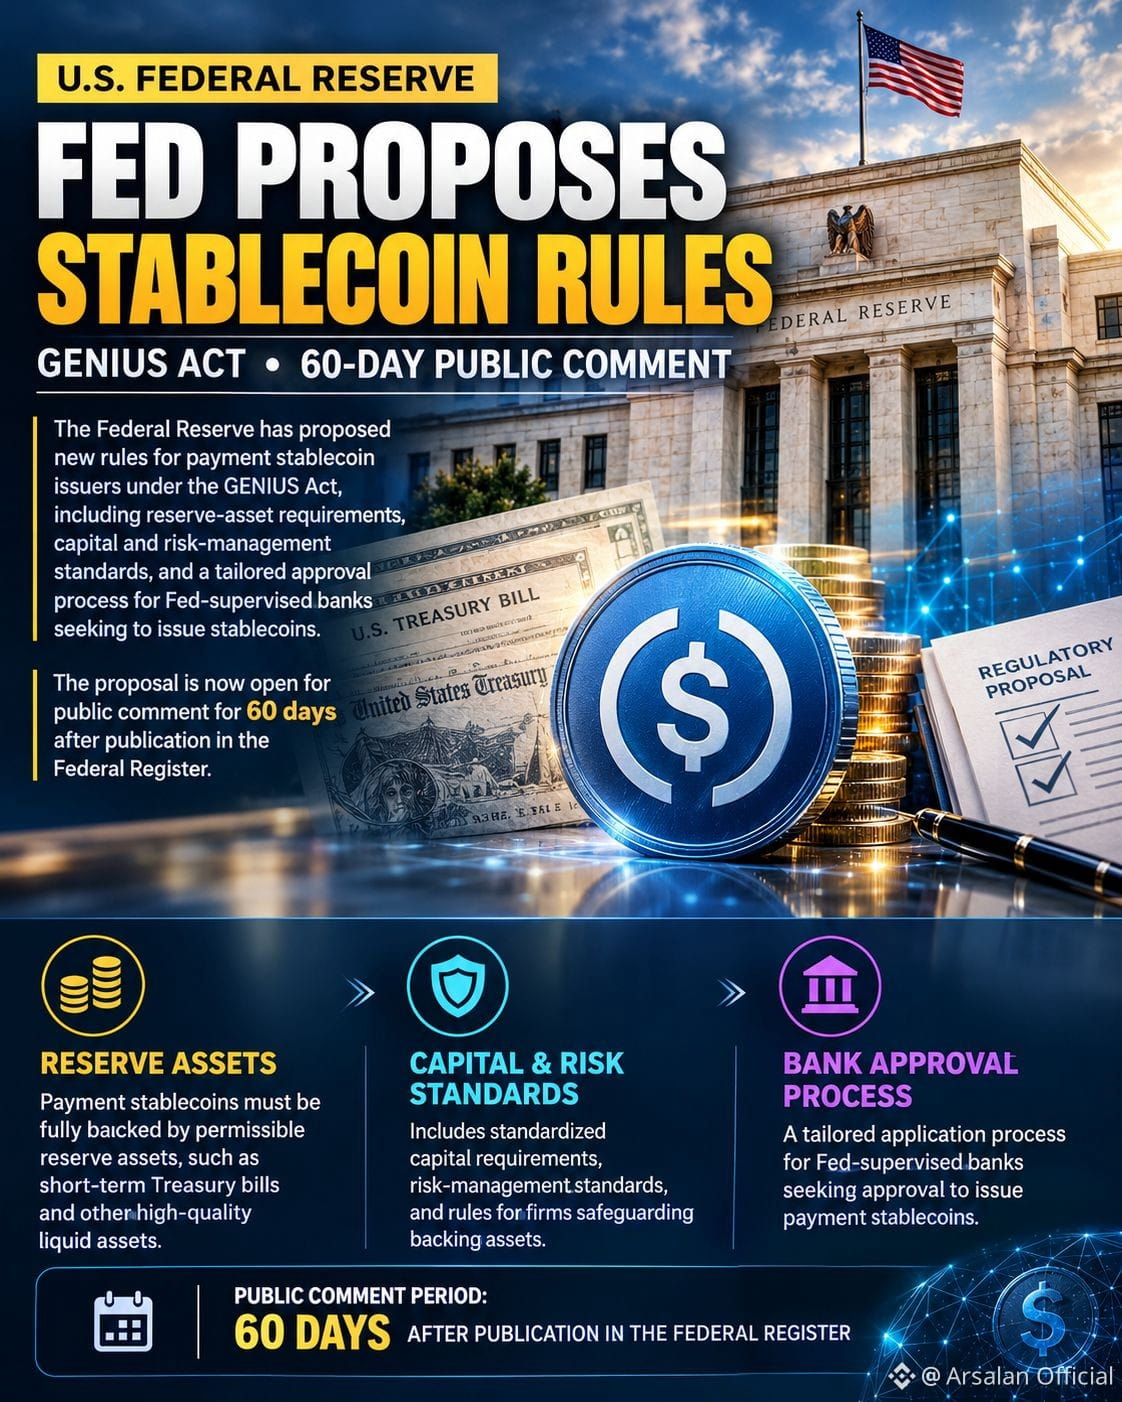
#FedProposesRulesForBankIssuedStablecoins The Federal Reserve has proposed new rules for payment stablecoin issuers under the GENIUS Act, including reserve-asset requirements, capital and risk-management standards, and a tailored approval process for Fed-supervised banks seeking to issue stablecoins.
The proposal is now open for public comment for 60 days after publication in the Federal Register.
#Stablecoins #Fed #FederalReserve #Crypto #CryptoNews #GENIUSAct #Banking #DigitalAssets #Blockchain #Finance $USDC
{spot}(USDCUSDT)
#FedProposesRulesForBankIssuedStablecoins The Federal Reserve has proposed new rules for payment stablecoin issuers under the GENIUS Act, including reserve-asset requirements, capital and risk-management standards, and a tailored approval process for Fed-supervised banks seeking to issue stablecoins.
The proposal is now open for public comment for 60 days after publication in the Federal Register.
#Stablecoins #Fed #FederalReserve #Crypto #CryptoNews #GENIUSAct #Banking #DigitalAssets #Blockchain #Finance $USDC
The proposal is now open for public comment for 60 days after publication in the Federal Register.
#Stablecoins #Fed #FederalReserve #Crypto #CryptoNews #GENIUSAct #Banking #DigitalAssets #Blockchain #Finance $USDC
2
37
·
--
🚨 #FedProposesRulesForBankIssuedStablecoins — banks may be getting a clearer path into the stablecoin race.
The Federal Reserve has proposed a framework for bank-issued payment stablecoins, focusing on reserve quality, redemption rights, liquidity, risk management, and how these products should sit inside the regulated banking system.
This matters because stablecoins are no longer being treated as a crypto-only product.
The bigger shift is:
Banks issue stablecoins → regulated dollar rails expand → more tokenized deposits + onchain settlement → stablecoin adoption moves deeper into traditional finance.
That could strengthen the broader narrative around $USDC, tokenized assets, RWA infrastructure, and bank-backed digital dollars.
The key question now:
Do banks eventually compete with crypto-native stablecoin issuers… or become their biggest distribution partners? 👀
{future}(HYPEUSDT)
{future}(XRPUSDT)
{future}(AKEUSDT)
$HYPE $XRP $AKE
#BinanceWillListHyperliquid(HYPE) #BrazilOrdersReportingOf$10KSelfCustodyTransfers #OndoFinanceSoughtSaleAfterFoundersDeath #FedOctoberRateHikeOddsRiseTo69.7%
🚨 #FedProposesRulesForBankIssuedStablecoins — banks may be getting a clearer path into the stablecoin race.
The Federal Reserve has proposed a framework for bank-issued payment stablecoins, focusing on reserve quality, redemption rights, liquidity, risk management, and how these products should sit inside the regulated banking system.
This matters because stablecoins are no longer being treated as a crypto-only product.
The bigger shift is:
Banks issue stablecoins → regulated dollar rails expand → more tokenized deposits + onchain settlement → stablecoin adoption moves deeper into traditional finance.
That could strengthen the broader narrative around $USDC, tokenized assets, RWA infrastructure, and bank-backed digital dollars.
The key question now:
Do banks eventually compete with crypto-native stablecoin issuers… or become their biggest distribution partners? 👀
$HYPE $XRP $AKE
#BinanceWillListHyperliquid(HYPE) #BrazilOrdersReportingOf$10KSelfCustodyTransfers #OndoFinanceSoughtSaleAfterFoundersDeath #FedOctoberRateHikeOddsRiseTo69.7%
The Federal Reserve has proposed a framework for bank-issued payment stablecoins, focusing on reserve quality, redemption rights, liquidity, risk management, and how these products should sit inside the regulated banking system.
This matters because stablecoins are no longer being treated as a crypto-only product.
The bigger shift is:
Banks issue stablecoins → regulated dollar rails expand → more tokenized deposits + onchain settlement → stablecoin adoption moves deeper into traditional finance.
That could strengthen the broader narrative around $USDC, tokenized assets, RWA infrastructure, and bank-backed digital dollars.
The key question now:
Do banks eventually compete with crypto-native stablecoin issuers… or become their biggest distribution partners? 👀
$HYPE $XRP $AKE
#BinanceWillListHyperliquid(HYPE) #BrazilOrdersReportingOf$10KSelfCustodyTransfers #OndoFinanceSoughtSaleAfterFoundersDeath #FedOctoberRateHikeOddsRiseTo69.7%
1
420

·
--
$BANK is getting overhyped because regulators are finally paying attention.
The Fed doesn’t care about your trades.
They care about systemic risk.
This isn’t a signal for $BANK to pump it’s a signal that bank-issued stablecoins are being pulled into the old system.
Traders think regulation means legitimacy.
I think it means more red tape and slower innovation.
I’m watching.
Not adding exposure.
If $BANK starts moving on actual bank adoption, not headlines, I’ll reconsider.
The moment a major bank announces a live, scaled stablecoin backed by $BANK that’s when I’m wrong.
You think it’s a buy?
#FedProposesRulesForBankIssuedStablecoins #BANK #CryptoNews
$BANK is getting overhyped because regulators are finally paying attention.
The Fed doesn’t care about your trades.
They care about systemic risk.
This isn’t a signal for $BANK to pump it’s a signal that bank-issued stablecoins are being pulled into the old system.
Traders think regulation means legitimacy.
I think it means more red tape and slower innovation.
I’m watching.
Not adding exposure.
If $BANK starts moving on actual bank adoption, not headlines, I’ll reconsider.
The moment a major bank announces a live, scaled stablecoin backed by $BANK that’s when I’m wrong.
You think it’s a buy?
#FedProposesRulesForBankIssuedStablecoins #BANK #CryptoNews
The Fed doesn’t care about your trades.
They care about systemic risk.
This isn’t a signal for $BANK to pump it’s a signal that bank-issued stablecoins are being pulled into the old system.
Traders think regulation means legitimacy.
I think it means more red tape and slower innovation.
I’m watching.
Not adding exposure.
If $BANK starts moving on actual bank adoption, not headlines, I’ll reconsider.
The moment a major bank announces a live, scaled stablecoin backed by $BANK that’s when I’m wrong.
You think it’s a buy?
#FedProposesRulesForBankIssuedStablecoins #BANK #CryptoNews
22
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#QNTRises39%
13,114 views
650 Discussing
2
#EthereumBreaksAbove$2700
1,523 views
72 Discussing
3
#BitgetBreachForgedRequestsNotStolenKeys
11,767 views
514 Discussing
4
#BitcoinSpotETFsTurnNetPositiveYTD
7,427 views
393 Discussing
5
#GrayscaleZcashETFHits$1BNetAssets
1,059 views
38 Discussing
6
#BitcoinSpotETFsNetInflow$191M
6,666 views
172 Discussing
7
#CFTCUpdatesGuidanceOnTokenizedAssets
45,528 views
1,409 Discussing
8
#BitgetSays$352MAffectedInHack
16,967 views
92 Discussing
9
#BinanceWillListHyperliquid(HYPE)
261,802 views
3,968 Discussing
10
#BrazilOrdersReportingOf$10KSelfCustodyTransfers
6,426 views
55 Discussing