

#sofi
sofi
44,998 views
285 Discussing
Hot
Latest
·
--
$161.6M in crypto revenue, but profitability is the real story. 👀
SoFi’s Q3 results highlight an important point about the crypto business: generating revenue is one thing; turning it into profit is another.
The report puts crypto transaction revenue at $161.6 million, while net crypto transaction revenue stood at $1.6 million.
That gap raises an important question: how much does a company actually keep after transaction-related costs?
As traditional finance expands into crypto, investors should look beyond headline numbers and pay attention to margins, costs, and sustainable growth.
👀 Will traditional financial companies become major competitors to crypto-native exchanges?
Keep an eye on how developments in traditional finance influence sentiment around $BTC and $SOL .
#Crypto #SoFi #BTC
1
223

·
--
SoFi gains around 13% after Q3 results and a higher full-year outlook
📈 SOFI shares rose around 13% on October 27 after revenue and earnings exceeded expectations and the company raised its full-year outlook.
📊 Adjusted net revenue reached approximately $1.37 billion, up 44% year over year. Adjusted earnings per share came in at $0.18, above the $0.17 forecast.
🏦 Total loan originations reached $16.9 billion, up 71%. SoFi also added 1.2 million members during the quarter, reflecting continued business expansion.
🔭 The company raised its 2026 adjusted net revenue forecast to $5.04 billion and introduced a 2027 outlook of approximately $6.4 billion, implying 27% growth.
⚖️ However, the Technology Platform segment remained weak. Maintaining credit quality as lending expands will be a key factor in assessing the sustainability of growth.
#SoFi $SOL $FIL
27

🚀 Fintech Spotlight: SoFi Raises Guidance Amid Economic Uncertainty!
Strong demand for lending products is driving major growth! SoFi CEO Anthony Noto announced that the company has raised its full-year net revenue guidance to approximately $5.04 billion, proving that robust fintech platforms can thrive even during shifting market conditions. 📊💡
As traditional banking and digital finance continue to merge, keeping an eye on fintech sector performance is essential for diversified portfolios.
What’s your outlook on fintech stocks this quarter? Drop your thoughts below! 👇💬
$BTC $ETH#BinancePick #Fintech #SoFi #MarketUpdate
{spot}(BTCUSDT)
🚀 Fintech Spotlight: SoFi Raises Guidance Amid Economic Uncertainty!
Strong demand for lending products is driving major growth! SoFi CEO Anthony Noto announced that the company has raised its full-year net revenue guidance to approximately $5.04 billion, proving that robust fintech platforms can thrive even during shifting market conditions. 📊💡
As traditional banking and digital finance continue to merge, keeping an eye on fintech sector performance is essential for diversified portfolios.
What’s your outlook on fintech stocks this quarter? Drop your thoughts below! 👇💬
$BTC $ETH#BinancePick #Fintech #SoFi #MarketUpdate
47
·
--
Bullish
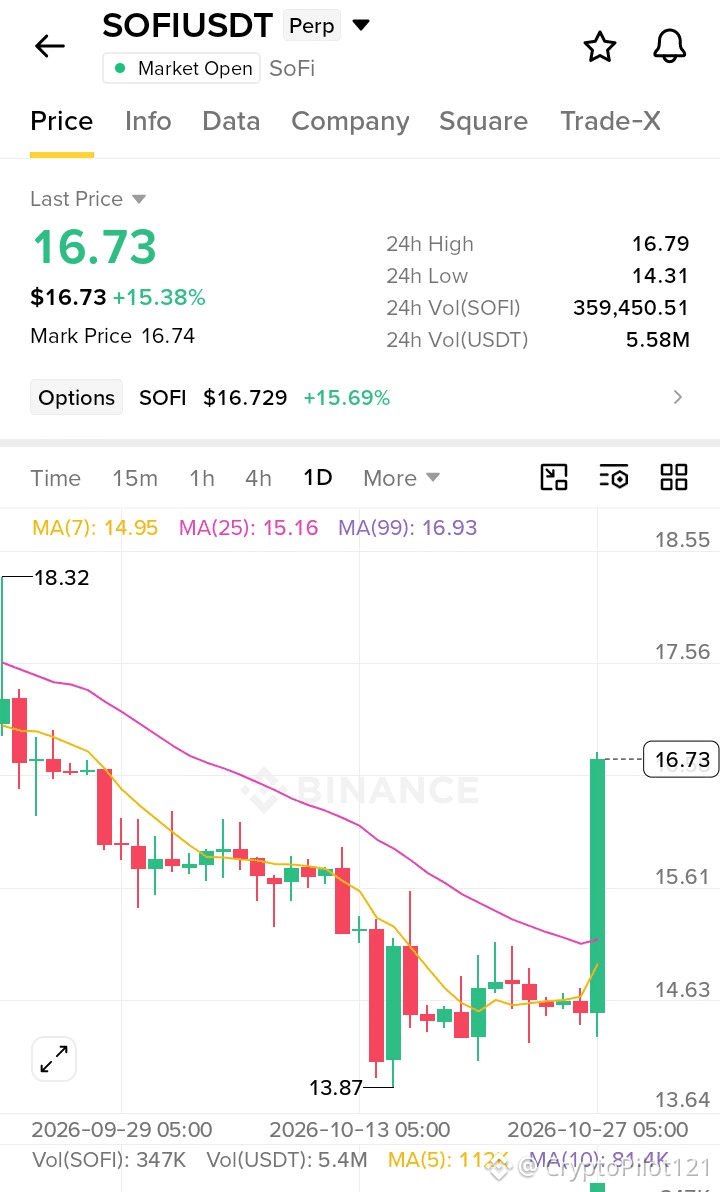
🚀 $SOFI USDT Perp GAINS +🔥
Price: $16.73
**Mark:** $16.74
24h High: $16.79
✅ Bullish Reversal:
Price > MA(7): 14.95 ✅
Price > MA(25): 15.16 ✅
Approaching MA(99): 16.93.
🎯 Long Entry: $16.00 - $16.60
Stop Loss: $14.50
**Targets:** $18.00 → $19.50
📈 Volume rising → Momentum building.
#SOFI #USDT #Trading #Crypto #BinanceSquare
$SOFI
{future}(SOFIUSDT)
🚀 $SOFI USDT Perp GAINS +🔥
Price: $16.73
**Mark:** $16.74
24h High: $16.79
✅ Bullish Reversal:
Price > MA(7): 14.95 ✅
Price > MA(25): 15.16 ✅
Approaching MA(99): 16.93.
🎯 Long Entry: $16.00 - $16.60
Stop Loss: $14.50
**Targets:** $18.00 → $19.50
📈 Volume rising → Momentum building.
#SOFI #USDT #Trading #Crypto #BinanceSquare
$SOFI
41

·
--
🚀 $SOFI CHARGES TOWARD $100M PRODUCTS BY 2030! 💥
📊 The roadmap spells out 15 business lines cranking out $8 B in annual revenue, a runway that forces a ~36% product‑growth cadence through the decade. Smart money is already loading positions, eyeing the liquidity wave that this expansion will unleash. 🌊
⚡ With each new product launch, the balance sheet inflates, tightening the supply‑demand gap and priming a bullish breakout on the chart. 💡 The upside potential is massive, but keep an eye on execution risk and macro sentiment. 💬 How are you positioning for the $SOFI growth surge? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOFI #GrowthPlay #RevenueRamp #LongSetup #Crypto
🔥 💎
2
·
--
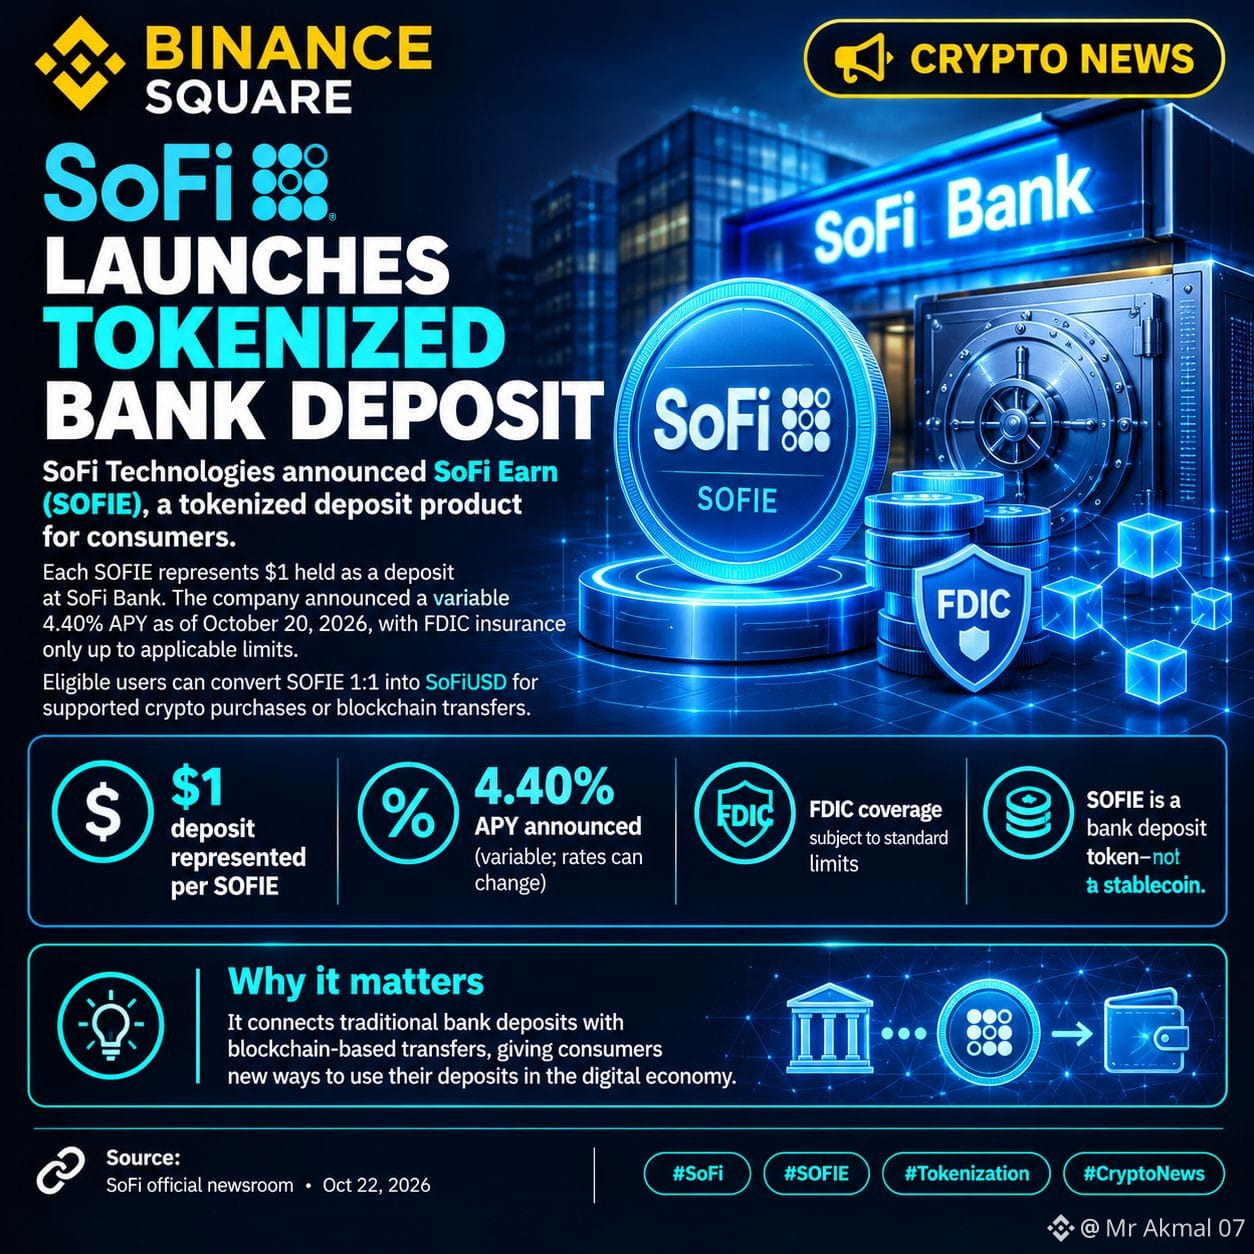
$SOFI 🚨 SoFi LAUNCHES SOFIE: A TOKENIZED BANK DEPOSIT
SoFi Technologies announced SoFi Earn (SOFIE) on October 22, introducing a tokenized bank deposit designed to connect traditional banking with blockchain-based digital payments.
🔍 Key highlights:
🔹 Each SOFIE represents $1 held on deposit at SoFi Bank.
🔹 The announced annual percentage yield (APY) was 4.40%, variable and subject to change.
🔹 Eligible members can convert SOFIE 1:1 into SoFiUSD.
🔹 The deposit is eligible for FDIC insurance up to applicable limits.
🔹 SOFIE is a bank deposit token, not a stablecoin.
🌐 Why it matters: Tokenized deposits could help bridge traditional banking and digital asset infrastructure while retaining the legal structure of a bank deposit.
📌 Important: The product is rolling out to eligible SoFi members. FDIC protection applies to qualifying deposits under standard rules and limits; it does not cover SoFiUSD or other crypto assets.
🔗 Official source: https://www.sofi.com/newsroom/sofi-launches-sofi-earn-sofie-the-first-and-only-national-bank-issued-tokenized-deposit-for-consumers/
What do you think—will tokenized bank deposits become an important part of digital payments? 👇
#SoFi #blockchain #CryptoNews #BinanceSquare
{future}(SOFIUSDT)
$SOFI 🚨 SoFi LAUNCHES SOFIE: A TOKENIZED BANK DEPOSIT
SoFi Technologies announced SoFi Earn (SOFIE) on October 22, introducing a tokenized bank deposit designed to connect traditional banking with blockchain-based digital payments.
🔍 Key highlights:
🔹 Each SOFIE represents $1 held on deposit at SoFi Bank.
🔹 The announced annual percentage yield (APY) was 4.40%, variable and subject to change.
🔹 Eligible members can convert SOFIE 1:1 into SoFiUSD.
🔹 The deposit is eligible for FDIC insurance up to applicable limits.
🔹 SOFIE is a bank deposit token, not a stablecoin.
🌐 Why it matters: Tokenized deposits could help bridge traditional banking and digital asset infrastructure while retaining the legal structure of a bank deposit.
📌 Important: The product is rolling out to eligible SoFi members. FDIC protection applies to qualifying deposits under standard rules and limits; it does not cover SoFiUSD or other crypto assets.
🔗 Official source: https://www.sofi.com/newsroom/sofi-launches-sofi-earn-sofie-the-first-and-only-national-bank-issued-tokenized-deposit-for-consumers/
What do you think—will tokenized bank deposits become an important part of digital payments? 👇
#SoFi #blockchain #CryptoNews #BinanceSquare
48
$SOFI Daily chart is bullish; key indicators confirm
📈 $SOFI | Daily bullish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX(41) indicates a clear trend | MACD DIF breaks above zero, signaling a bullish trend | EMA5 crosses above EMA8, signaling short-term bullishness | Volume surges (4.6x)
Price change: 13.3600%
━━━━━━━━━━━━━━━━━━
#技术分析 #SOFI
📌 The above content is for reference only and does not constitute investment advice
1

·
--
SoFi’s earnings this quarter gave the old saying “fintech just burns cash” another kick 👇
SoFi (NASDAQ: SOFI) reported Q3 2026 results after the U.S. market close on 10/27. Official investor relations data:
1️⃣ Adjusted net revenue of $1.4B, up 44% year over year and a record (LSEG consensus: about $1.25B)
2️⃣ Adjusted EBITDA of about $470M, up 70%, with a 34% margin
3️⃣ 17.1 million members, up 35%; 1.2 million new members added in the quarter, also a record. Products totaled 26.7 million, up 44%
4️⃣ Loan originations hit a record $16.9B; the company said credit performance was in line with expectations
5️⃣ 12th consecutive profitable quarter, with adjusted EPS of $0.18 (vs. $0.16 expected)
Even more impressive was the guidance:
SoFi raised its full-year 2026 revenue outlook to $5.04B (market consensus: about $4.87B), and also laid out 2027 guidance: about $6.4B in revenue, $1.28B in net income, and $0.90 EPS. WSJ reported the stock was up around 13% that day.
My take:
A digital bank with 17 million users and increasingly deep cross-selling across products is now generating consistent profits—and is confident enough to give guidance a year ahead. That’s the appeal of U.S. stocks: good companies let the numbers speak for themselves.
There are lessons here for crypto, too: user scale + compliant licenses + a multi-product loop are the right path for CeFi to enter mainstream finance.
The risks are worth spelling out, too: lending is sensitive to interest rates and the credit cycle, and 2027 guidance is management’s forecast, not a guarantee.
Sources: SoFi Investor Relations / Business Wire earnings release, Reuters, and WSJ
Not investment advice. DYOR.
#SoFi #美股 #财报 #Fintech
36

·
--
SoFi’s 13.42% surge yesterday wasn’t just about “finally going up”—it was an earnings report putting numbers behind the “everything app” story.
At the close of U.S. trading on October 27, SoFi was at $16.40, up $1.94 (+13.42%) for the day. It traded between $15.67 and $16.76, versus a previous close of $14.46, on volume of about 159 million shares—roughly three times its three-month average of 51.4 million. The Nasdaq rose 1.18% that day, so SoFi outperformed by about 12 percentage points. But let’s be clear about the context: this is still a rebound from a deep hole. The stock is still down about 45% year to date and remains roughly halfway below its 52-week high of $32.73. One day’s gains can’t erase a year of losses.
The third-quarter report’s key takeaway is that several metrics hit records at once: adjusted net revenue of $1.37 billion, up 44% year over year; adjusted EPS of $0.18, above the market’s $0.17 estimate; 17.1 million members, up 35% year over year, with a record 1.2 million added during the quarter; and 26.7 million total products, up 44% year over year. Lending remains the engine: total originations reached $16.9 billion, up 71% year over year, comprising $12.6 billion in personal loans, $2.9 billion in student loans, and $1.4 billion in home loans. Adjusted EBITDA was $470 million, up 70% year over year, with a margin of about 34%.
More importantly, management raised its 2026 guidance to $5.04 billion in adjusted net revenue and $0.61 in EPS, and issued guidance for 2027 for the first time: about $6.4 billion in revenue and $0.90 in EPS. What the market is buying is arguably less the third quarter itself than the trajectory suggesting “growth can accelerate again next year.” On October 26, Monness had just initiated coverage with a Buy rating and a $20 price target, adding fuel to the rally.
My take: The report deserves a strong rally, but there are two things to view with caution. First, growth still depends heavily on lending: personal loans make up the bulk of originations, and credit quality is critical. Although the annualized personal loan charge-off rate improved to 2.26% from 2.60% a year earlier, if consumer credit weakens in a high-interest-rate environment, the story could turn around quickly. Second, don’t get carried away by the crypto narrative: third-quarter gross revenue from crypto trading was $161.6 million, but net revenue after costs was only about $1.6 million. For now, crypto is a customer-acquisition draw, not a profit engine.
So this surge looks more like “the start of a valuation recovery” than confirmation of a “trend reversal.” The question to watch is whether fourth-quarter loan growth and member conversion can support the 2027 guidance—not whether to chase a one-day gain.
Personal research; not investment advice.
$SOFI
#SoFi #数字银行 #美股财报 #Fintech
74
·
--
SoFi (Nasdaq: $SOFI) reported its Q3 2026 results (for the period ended September 30): The company reported approximately 503,000 crypto products, gross crypto transaction revenue of approximately $161.6 million for the quarter, and net crypto transaction revenue of approximately $1.6 million after related costs. Total net revenue for the same period was approximately $1.385 billion (up approximately 44% year over year), and net income was approximately $241 million. SoFi Crypto was relaunched in Q4 2025. #SoFi #加密支付 #Web3
SoFi (Nasdaq: $SOFI ) reported its Q3 2026 results (for the period ended September 30): The company reported approximately 503,000 crypto products, gross crypto transaction revenue of approximately $161.6 million for the quarter, and net crypto transaction revenue of approximately $1.6 million after related costs. Total net revenue for the same period was approximately $1.385 billion (up approximately 44% year over year), and net income was approximately $241 million. SoFi Crypto was relaunched in Q4 2025. #SoFi #加密支付 #Web3
1
17

·
--
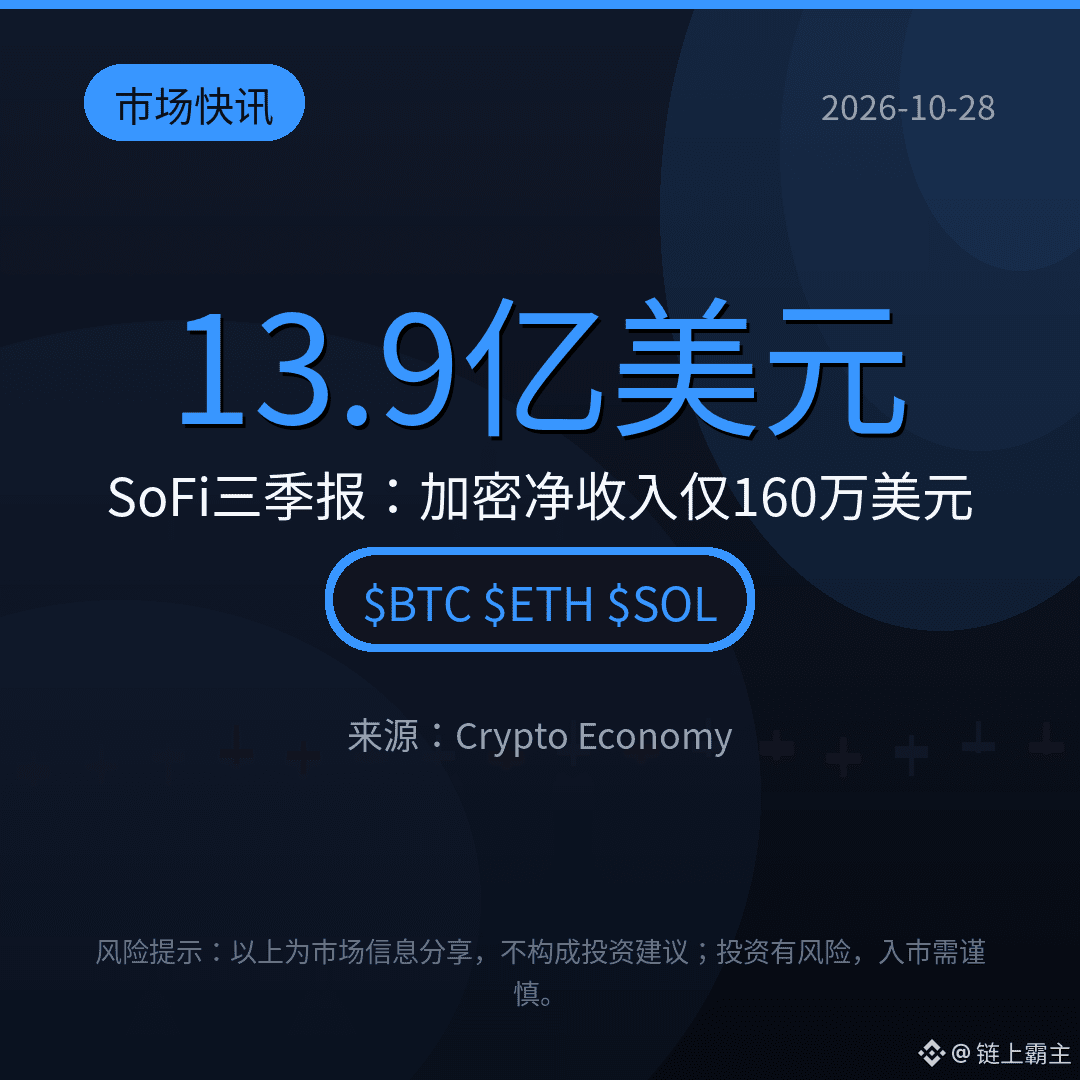
【Market Flash】SoFi’s Q3 results showed a striking contrast: 503,000 crypto products, $161.6 million in crypto gross revenue, up 20% quarter over quarter, but just $1.6 million in net revenue. The company’s total net revenue hit a record $1.39 billion. SoFi Invest products reached 4.18 million, and the stock rose nearly 15% after the earnings report. Its next bets are stablecoins and tokenized deposits—but whether they can generate gross profit is the key question. Are you bullish or bearish? Share your thoughts in the comments.
$BTC $ETH $SOL
#SoFi #加密财报 #Fintech
(Source: Crypto Economy)
⚠️Risk warning: The above is shared for market information purposes only and does not constitute investment advice. Investing involves risks; please exercise caution.
$BTC $ETH $SOL
#SoFi #加密财报 #Fintech
(Source: Crypto Economy)
⚠️Risk warning: The above is shared for market information purposes only and does not constitute investment advice. Investing involves risks; please exercise caution.
12

·
--
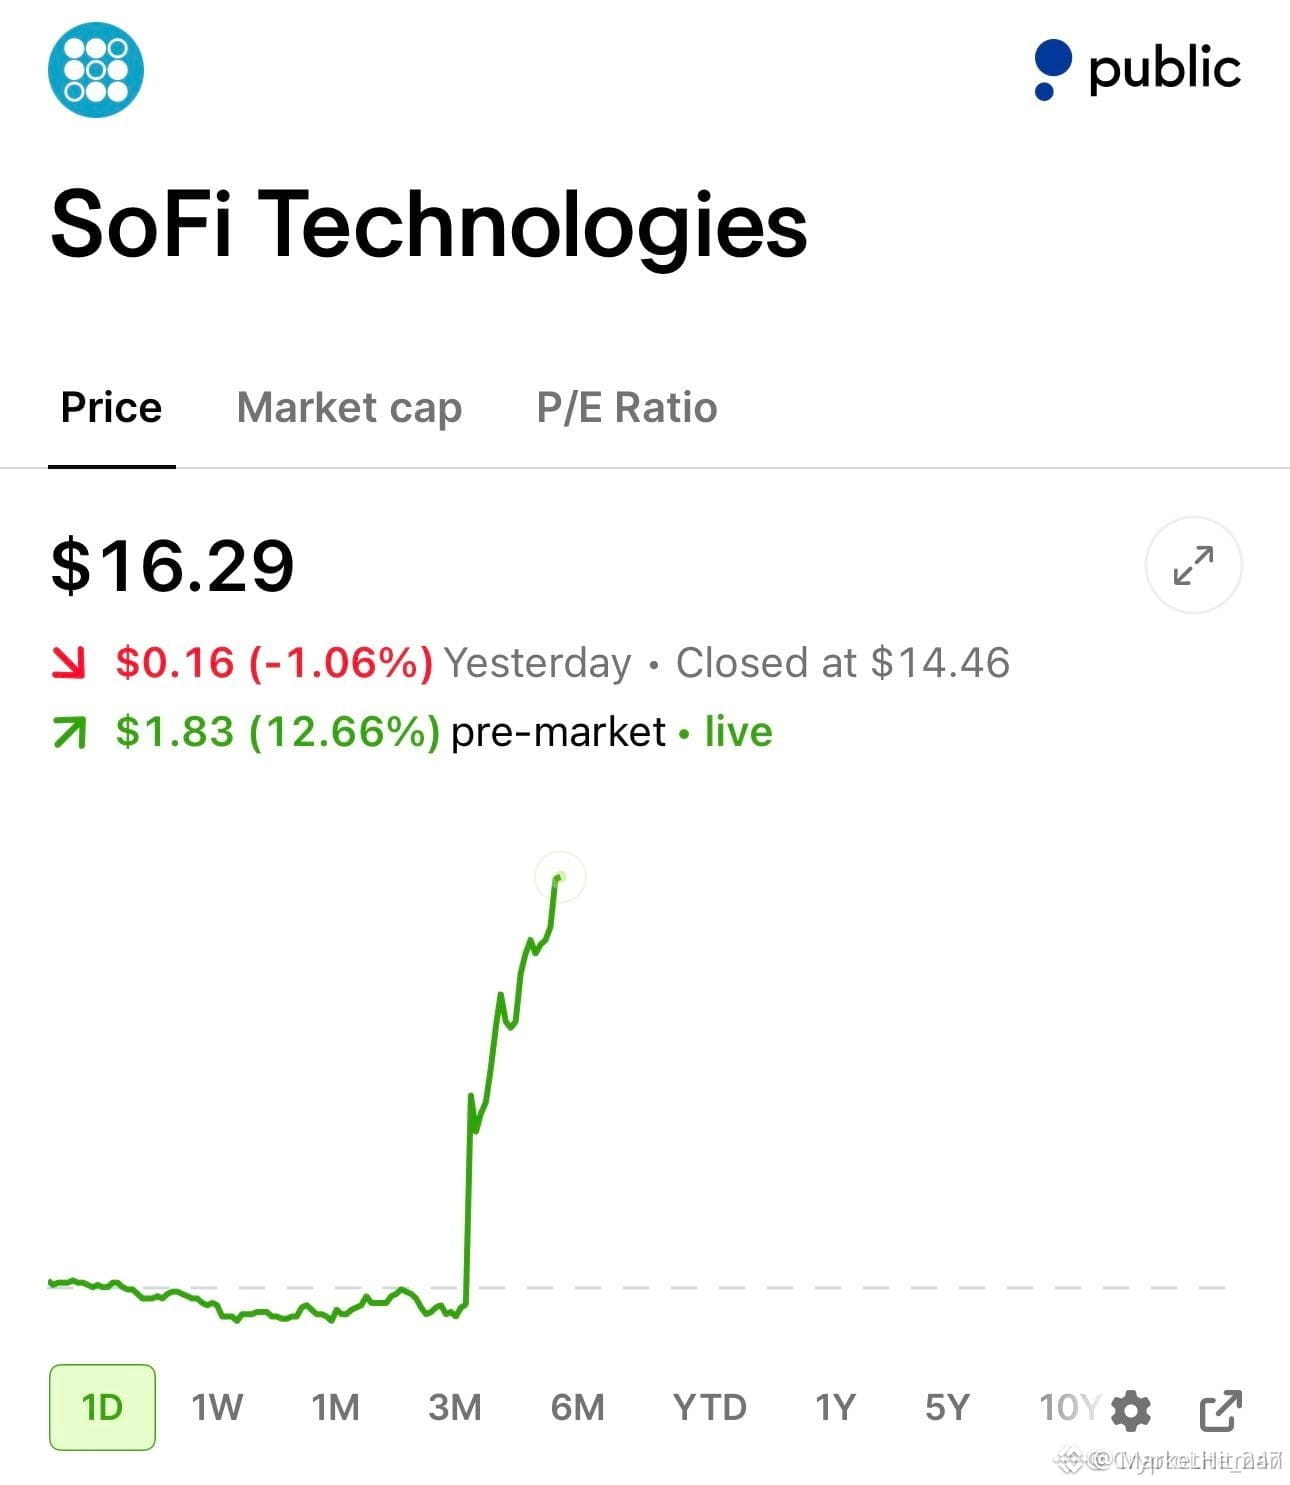
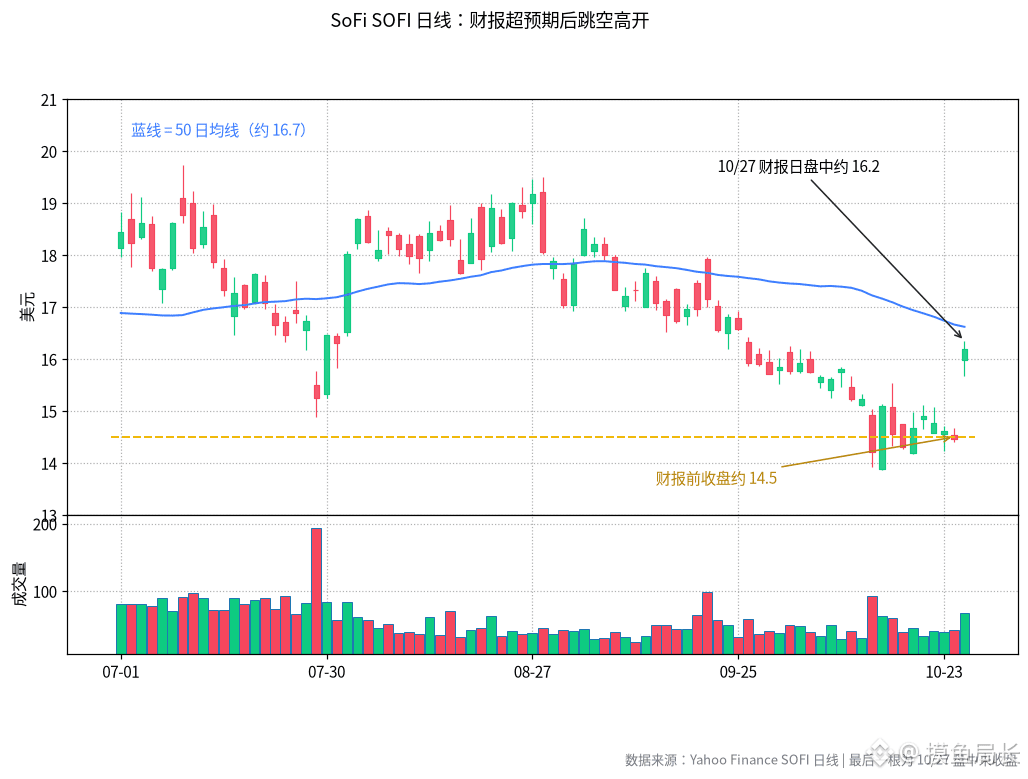
SoFi reported its third-quarter results tonight, and its stock gapped up at the open, surged more than 10% intraday, and climbed back above $16.
The U.S. online bank has had a brutal year, already down more than 40% before earnings.
Revenue and profit both hit records this quarter, and quarterly member additions were the highest ever.
What got the bulls even more excited was the guidance: SoFi raised its full-year outlook and, for the first time, gave targets for next year that were also above Wall Street expectations.
One small detail for crypto readers: crypto trading, which relaunched late last year, now has about 500,000 accounts, though it still contributes very little revenue.
I’m more inclined to see tonight as a sentiment rebound. The stock had fallen so hard that the strong earnings report caught the shorts off guard.
For a stock that gaps up at the open, where it closes matters more than how much it rises intraday.
On the upside, watch whether it can hold above the 50-day moving average near $16.7. On the downside, watch whether the gap around $14.5 from before earnings gets filled.
Do you think this is a genuine reversal or just an oversold bounce?
$SOFI
#SoFi #U.S. Stocks Earnings
285

·
--
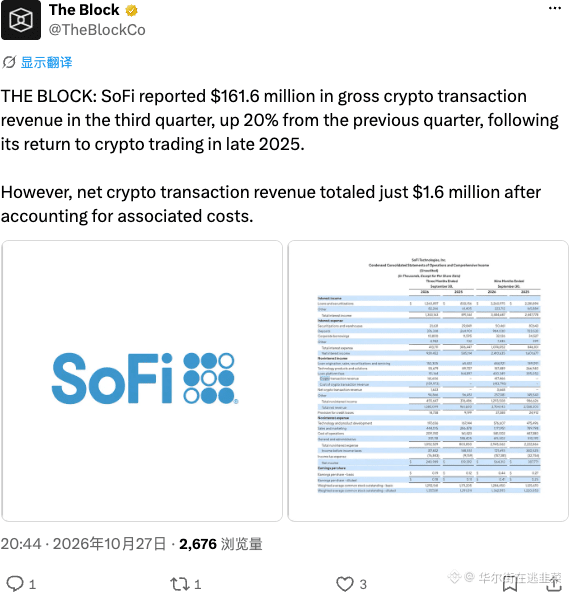
SoFi financial report: crypto trading revenue was $160 million, up 20% quarter over quarter, while net profit was only $1.6 million.
All the gross profit came from fees, and costs burned more than it earned.
When institutions enter the market, you can’t just look at the size of the pie; you also have to look at the actual net inflow of real money, which is the hard truth.
#SoFi #Crypto #Macro
All the gross profit came from fees, and costs burned more than it earned.
When institutions enter the market, you can’t just look at the size of the pie; you also have to look at the actual net inflow of real money, which is the hard truth.
#SoFi #Crypto #Macro
27
·
--
SOFI Binance TradFi perpetual (traditional finance), 5-minute close at 19:05 Beijing time on 2026-10-27: +6.51%. At 19:05:02 Beijing time on 2026-10-27, the current price was 15.38, 24h trading value was 2.3131 million, price was above VWAP 14.8456, and RSI was 85.7. The key short-term divergence to watch: will the move continue, or will buyers step in after a pullback?
Can price hold VWAP at 14.8456 on a retest? Would you wait for confirmation of continuation, or first guard against a pullback after the spike?
Note: This is a traditional-finance perpetual. Liquidity is lower and gap risk is higher outside trading hours. 24h trading value is below $5 million, and the order book is thin, so beware of slippage.
#SOFI #Unusual Move Alert
22
·
--
【Market Flash】If bank deposits themselves can become tokens, is putting money away still called a deposit? SoFi’s tokenized deposits can be converted into stablecoins, with an annualized yield of 4.40%. The key isn’t the number itself, but that a boundary has been crossed: banking products are beginning to exist in token form, potentially changing how they’re held and exchanged. For depositors, it’s important to understand what this changes—and what it doesn’t. Would you convert your deposit into this form? Let’s talk in the comments.
$BTC $ETH $USDT
#SoFi #代币化存款 #Stablecoins
(Source: Unchained)
⚠️Risk disclaimer: The above is shared for informational purposes only and does not constitute investment advice. Investing involves risk; please exercise caution.
$BTC $ETH $USDT
#SoFi #代币化存款 #Stablecoins
(Source: Unchained)
⚠️Risk disclaimer: The above is shared for informational purposes only and does not constitute investment advice. Investing involves risk; please exercise caution.
514

·
--
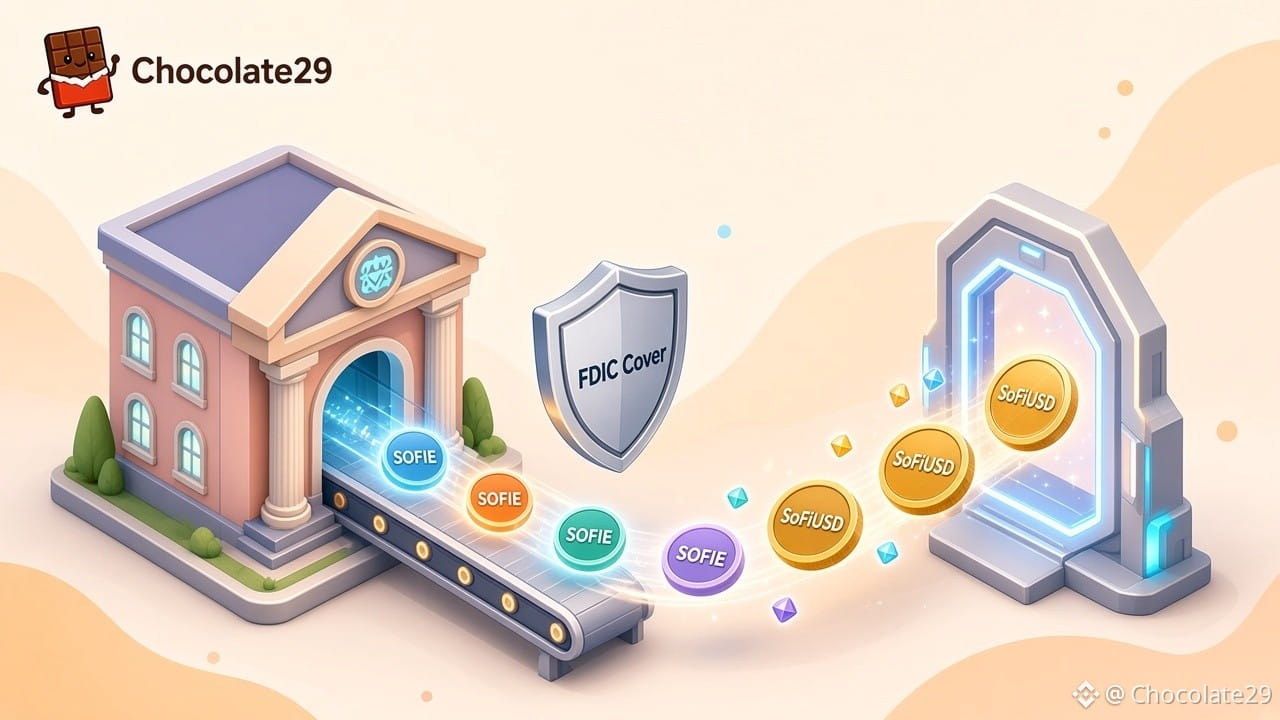
SoFi just put a bank deposit on-chain for everyday customers — with FDIC cover and a yield.
On October 22, 2026, SoFi Technologies launched SoFi Earn (SOFIE), calling it the first national bank-issued tokenized deposit for U.S. consumers. Each SOFIE represents one U.S. dollar held on deposit at SoFi Bank, earns a variable 4.40% APY (rate as of October 20, 2026), and is FDIC-insured up to standard limits. SoFi frames the launch as its fifth crypto-related product in less than a year.
SOFIE is not a payment stablecoin. Members can convert it 1:1 into SoFiUSD when they want to buy crypto in-app or move funds over blockchain rails around the clock; once converted, those dollars leave the insured deposit product. SoFi expects the rollout to crypto customers to finish in November 2026. Tokenized bank deposits sit in a different risk box than exchange stablecoins — read the disclosures before parking cash.
#SoFi #SOFIE #TokenizedDeposits #Stablecoins #Crypto
DYOR. Not financial advice.
{future}(SOFIUSDT)
SoFi just put a bank deposit on-chain for everyday customers — with FDIC cover and a yield.
On October 22, 2026, SoFi Technologies launched SoFi Earn (SOFIE), calling it the first national bank-issued tokenized deposit for U.S. consumers. Each SOFIE represents one U.S. dollar held on deposit at SoFi Bank, earns a variable 4.40% APY (rate as of October 20, 2026), and is FDIC-insured up to standard limits. SoFi frames the launch as its fifth crypto-related product in less than a year.
SOFIE is not a payment stablecoin. Members can convert it 1:1 into SoFiUSD when they want to buy crypto in-app or move funds over blockchain rails around the clock; once converted, those dollars leave the insured deposit product. SoFi expects the rollout to crypto customers to finish in November 2026. Tokenized bank deposits sit in a different risk box than exchange stablecoins — read the disclosures before parking cash.
#SoFi #SOFIE #TokenizedDeposits #Stablecoins #Crypto
DYOR. Not financial advice.

·
--
Banks are starting to compete for the money flowing around stablecoins.
SoFi has launched SOFIE, a tokenized deposit marketed with an annualized yield of around 4.4%, aiming to combine the yield appeal of bank deposits with on-chain liquidity. The stablecoin market is growing, and banks don’t want to be mere bystanders.
The yield looks attractive, but it’s worth checking the redemption rules, reserves, and regulatory treatment—there’s a licensing gap between “deposit-like” and “actual deposits.” In the RWA and stablecoin sectors, regulatory compliance will increasingly become a competitive moat.
#SoFi #稳定币 #RWA #Tokenization
SOFIUS-2.33%
34
·
--
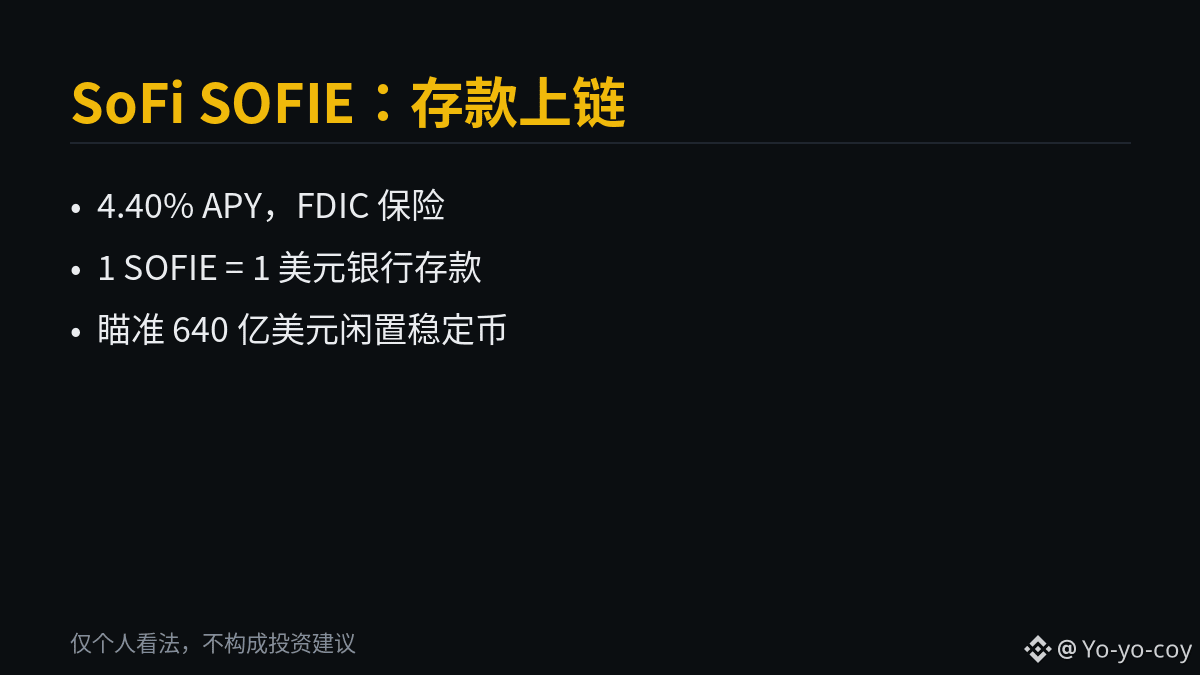
A U.S. bank has, for the first time, tokenized deposits for retail customers—with a 4.40% APY and FDIC insurance.
SoFi launched SoFi Earn (SOFIE) on October 22. Each SOFIE represents a $1 deposit at SoFi Bank. Holders earn 4.40% APY, with FDIC deposit insurance applying (up to $250,000 per person in eligible deposits). SOFIE can be redeemed 1:1 at any time for SoFi’s own SoFiUSD stablecoin, which can then be used to buy crypto or transferred on-chain 24/7. This marks the first time a nationally chartered U.S. bank has directly issued tokenized deposits to retail customers. It is also SoFi’s fifth crypto product in less than a year, with a full rollout to crypto users planned for November.
The business is targeting stablecoins’ “dead money”: research cited by SoFi estimates that about $64 billion—21.2% of the stablecoin supply—is sitting in inactive wallets long-term, earning no interest. Legally, it is a byproduct of the GENIUS Act (signed in July 2025): the law bars stablecoin issuers from paying interest to holders, but that restriction does not apply to bank “deposits.” The FDIC’s proposed implementation rules also confirm that tokenized deposits remain ordinary bank deposits.
The takeaway: After legislation took away the interest-bearing business from stablecoins, banks stepping in under the guise of deposits is just the first move. In September, 21 financial institutions—including Goldman Sachs, Bank of America, Citi, and Deutsche Bank—announced plans to form a company and jointly issue a dollar-pegged cryptocurrency in the first half of 2027. The RWA market for compliant yield-bearing assets is the next table banks will sit down to after stablecoins.
Sources: Reuters, 10/22; official Business Wire press release, 10/22; The Block, 10/22.
These are my personal views only and do not constitute investment advice.
#SoFi #代币化存款 #RWA $USDC
1

𝚈𝙸𝙴𝙻𝙳 𝙼𝙴𝙴𝚃𝚂 𝚂𝙴𝙲𝚄𝚁𝙸𝚃𝚈.
SoFi is bridging the gap between traditional banking and crypto by launching the SOFIE token. This tokenized deposit offers a competitive 4.4 percent APY backed by FDIC insurance which provides a level of safety that most decentralized stablecoins cannot match. For traders this represents a significant step in the institutional adoption of real world assets and could drive more liquidity into regulated fintech ecosystems.
#SoFi #TokenizedDeposits ⠀
4

The GENIUS Act just shut down the channel for paying interest on stablecoins, and SoFi opened a front door that same day: SoFi Earn (SOFIE), the first tokenized deposit from a U.S. national bank offered directly to retail customers, is now live. It offers 4.40% APY and FDIC deposit insurance, with 1 SOFIE equal to $1 in a SoFi bank account. Convert it to the SoFiUSD stablecoin at a 1:1 rate anytime to buy crypto or make on-chain transfers, 24/7—and interest keeps accruing until the very second you convert. It will be available to all SoFi Crypto users by the end of November. The Fed estimates that around $64 billion (21.2%) of the stablecoin market is sitting in idle wallets earning nothing. Banks are openly going after crypto’s money. The irony: SOFI shares fell 2.4% on the announcement day—Wall Street simply doesn’t believe banks can take business away from crypto. #SoFi #代币化存款 #GENIUS Act
The GENIUS Act just shut down the channel for paying interest on stablecoins, and SoFi opened a front door that same day: SoFi Earn (SOFIE), the first tokenized deposit from a U.S. national bank offered directly to retail customers, is now live. It offers 4.40% APY and FDIC deposit insurance, with 1 SOFIE equal to $1 in a SoFi bank account. Convert it to the SoFiUSD stablecoin at a 1:1 rate anytime to buy crypto or make on-chain transfers, 24/7—and interest keeps accruing until the very second you convert. It will be available to all SoFi Crypto users by the end of November. The Fed estimates that around $64 billion (21.2%) of the stablecoin market is sitting in idle wallets earning nothing. Banks are openly going after crypto’s money. The irony: SOFI shares fell 2.4% on the announcement day—Wall Street simply doesn’t believe banks can take business away from crypto. #SoFi #代币化存款 #GENIUS Act
35
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#CanMicrosoftDeliverOnAI
651,069 views
4,309 Discussing
2
#CanGoogleDefindItsCore
400,950 views
3,044 Discussing
3
#FedWatch
16.1M views
37,361 Discussing
4
#BitcoinCore32.1RaisesPeerConnectionLimit
5,484 views
183 Discussing
5
#RussiaPlansStandardizedTestForCryptoInvestors
394 views
60 Discussing
6
#EarningsSeason
6.1M views
30,437 Discussing
7
#BitcoinCoreIdentifiesThreeVulnerabilities
15,411 views
316 Discussing
8
#RippleExpects$900MAnnualizedProductRevenueRunRate
1,655 views
11 Discussing
9
#GoogleToPreviewCryptoCustodySecuritySystem
4,955 views
117 Discussing
10
#FedToBeginShrinkingRateSettingCalendarIn2027
5,873 views
75 Discussing