

#earningsseason
earningsseason
Hot
Latest


Article
Earnings Season: Micron Q4 Earnings — Bullish or Bearish?Binance Square is launching the Earnings Season! Join us as we breakdown the market data before and after earnings from the hottest stocks.
Micron's FY2026 Q4 earnings are about to drop this week. The results aren't just about $MU prices, it becomes a key test of whether the whole memory supercycle narrative can hold up.
Stay tuned to Binance Square Earnings Season — be the first to know and act around the biggest earnings!
What's on the Agenda?
Sep 28 — [Micron FY2026 Q4 earnings preview](https://www.binance.com/en/square/post/09-28-2026-micron-heads-into-fiscal-q4-earnings-with-the-bar-and-the-stock-already-high-371493333095967): a quick look at what to watch this quarterSep 29 — [Micron Earnings Season preview livestream ](https://www.binance.com/en/square/post/371454388222161)(Chinese)Sep 30 — [Micron Earnings Season preview livestream](https://www.binance.com/en/square/post/371563664770726) (English)Oct 1 — Micron FY2026 Q4 earnings recap: digging into the market insights behind dataOct 1 — [Post-earnings analysts livestream](https://www.binance.com/en/square/audio?_ul=aHR0cHM6Ly9hcHAuYmluYW5jZS5jb20vdW5pLXFyL2NzcGEvNDY0NzY2NzcxODI5NTQ_cj1NSjZMSTFVSiZsPXpoLUNOJnNvdXJjZT1ob3N0X3NoYXJlJnVjPWFwcF9zcXVhcmVfc2hhcmVfbGluayZ1cz1jb3B5bGluaw&id=46476677182954&ref=MJ6LI1UJ&utm_campaign=app_square_share_link&utm_source=copylink) (Chinese)Oct 2 — [Post-earnings analysts livestream](https://www.binance.com/en/square/audio?_ul=aHR0cHM6Ly9hcHAuYmluYW5jZS5jb20vdW5pLXFyL2NzcGEvNDY0NzkxNTE2Njg1NDU_c291cmNlPWhvc3Rfc2hhcmUmdWM9d2ViX3NxdWFyZV9zaGFyZV9saW5rJnVzPWNvcHlsaW5rJmw9ZW4mcj1VQ0lQWjRMMA&id=46479151668545&ref=UCIPZ4L0&utm_campaign=web_square_share_link&utm_source=copylink) (English)
#EarningsSeason Topic Challenge
How to join:
Publish a short post or article with hashtag #EarningsSeason How will you adjust your trades/positions before/after the report? Use trade-sharing cards to share your $MU trades/positions for a higher chance to earn a traffic boost.Back up your view with data or charts, and avoid AI-generated images/views.Try to answer one of the following questions in your post:Are you bullish or bearish on $MU price once Q4 earnings are out?Read [Micron FY2026 Q4 earnings preview](https://www.binance.com/en/square/post/09-28-2026-micron-heads-into-fiscal-q4-earnings-with-the-bar-and-the-stock-already-high-371493333095967), and share your take: will Micron really be able to push its gross margin past 86% in Q4? How much longer do you think the memory super cycle can run?
Submission window:
Sep 29, 2026, 10:00 – Oct 1, 2026, 10:00 (UTC)
Rewards:
Qualified posts that comply with the above guidelines will be reviewed and may receive a random traffic boost in views. Use trade-sharing cards to share your $MU trades/positions for a higher chance to earn a traffic boost. You will receive a notification from your feed secretary if your post is selected. Get a chance to have your views featured on Binance Square Official.
Need ideas for your post? Visit #EarningsSeason or the [Square Guide on How to Post for Better Reach](https://www.binance.com/en/square/post/364505922663952).
Earnings Season: Micron Q4 Earnings — Bullish or Bearish?
Binance Square is launching the Earnings Season! Join us as we breakdown the market data before and after earnings from the hottest stocks.
Micron's FY2026 Q4 earnings are about to drop this week. The results aren't just about $MU prices, it becomes a key test of whether the whole memory supercycle narrative can hold up.
Stay tuned to Binance Square Earnings Season — be the first to know and act around the biggest earnings!
What's on the Agenda?
Sep 28 — Micron FY2026 Q4 earnings preview: a quick look at what to watch this quarterSep 29 — Micron Earnings Season preview livestream (Chinese)Sep 30 — Micron Earnings Season preview livestream (English)Oct 1 — Micron FY2026 Q4 earnings recap: digging into the market insights behind dataOct 1 — Post-earnings analysts livestream (Chinese)Oct 2 — Post-earnings analysts livestream (English)
#EarningsSeason Topic Challenge
How to join:
Publish a short post or article with hashtag #EarningsSeason How will you adjust your trades/positions before/after the report? Use trade-sharing cards to share your $MU trades/positions for a higher chance to earn a traffic boost.Back up your view with data or charts, and avoid AI-generated images/views.Try to answer one of the following questions in your post:Are you bullish or bearish on $MU price once Q4 earnings are out?Read Micron FY2026 Q4 earnings preview, and share your take: will Micron really be able to push its gross margin past 86% in Q4? How much longer do you think the memory super cycle can run?
Submission window:
Sep 29, 2026, 10:00 – Oct 1, 2026, 10:00 (UTC)
Rewards:
Qualified posts that comply with the above guidelines will be reviewed and may receive a random traffic boost in views. Use trade-sharing cards to share your $MU trades/positions for a higher chance to earn a traffic boost. You will receive a notification from your feed secretary if your post is selected. Get a chance to have your views featured on Binance Square Official.
Need ideas for your post? Visit #EarningsSeason or the Square Guide on How to Post for Better Reach.
BcryptexBTC:
$MU Q4 earnings this week will move not just stocks but crypto AI tokens too Memory supercycle holding means bullish for AI sector I am positioning long before report using trade sharing card #EarningsSeason
64
40
314
580.5k

Verified
Article
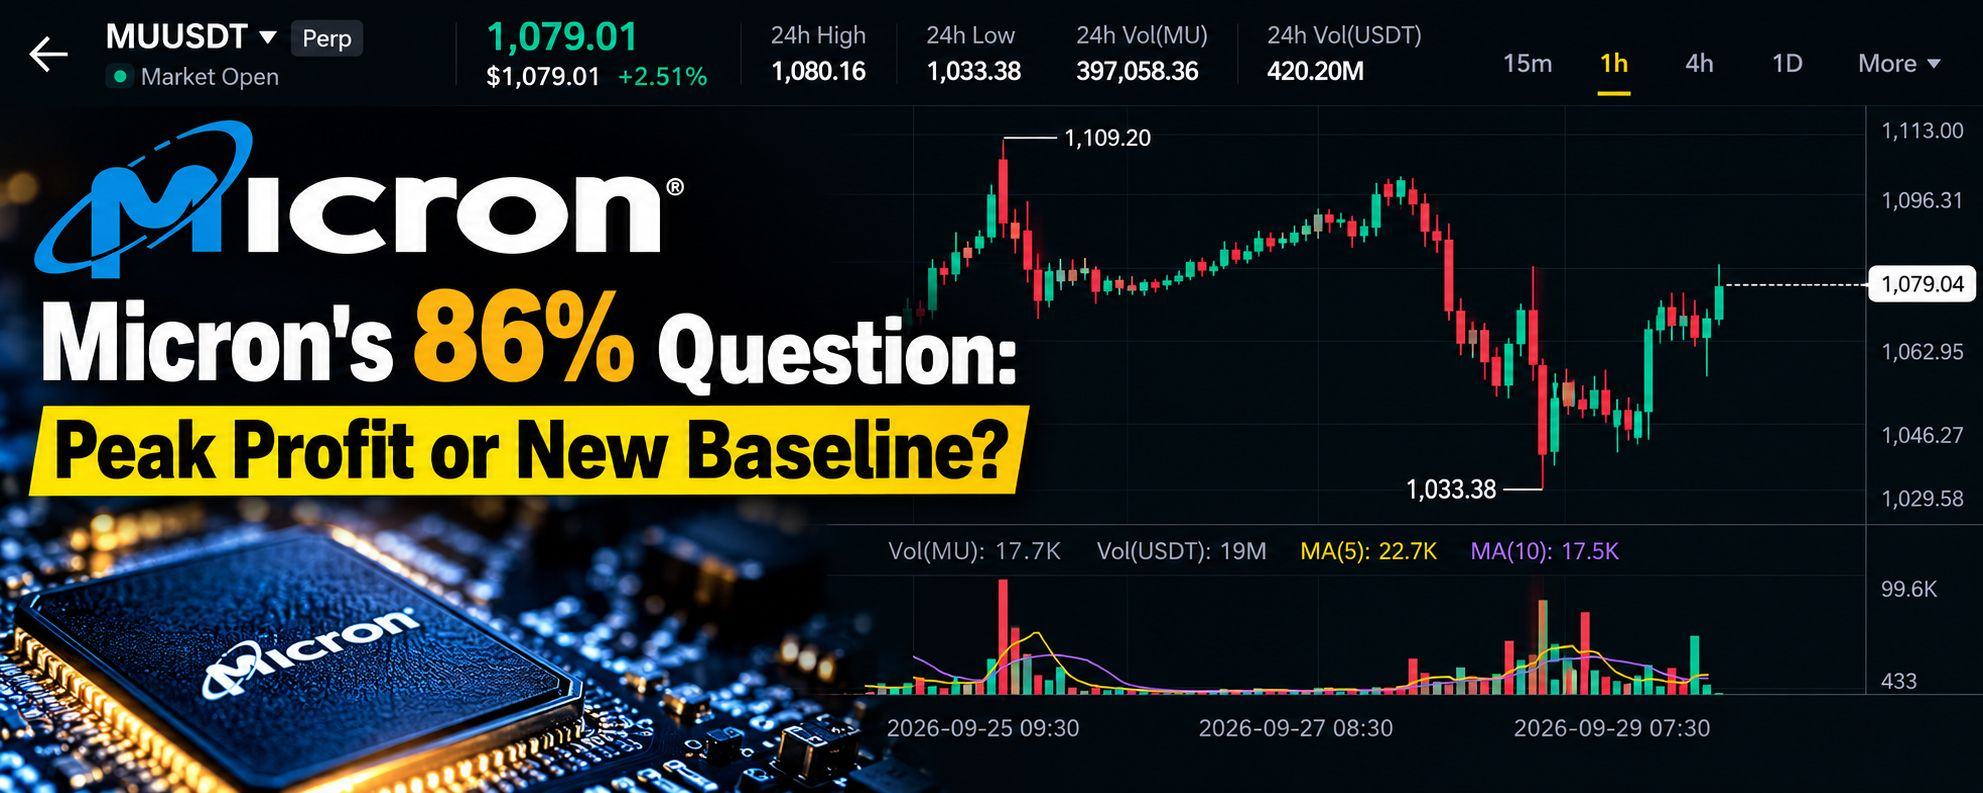
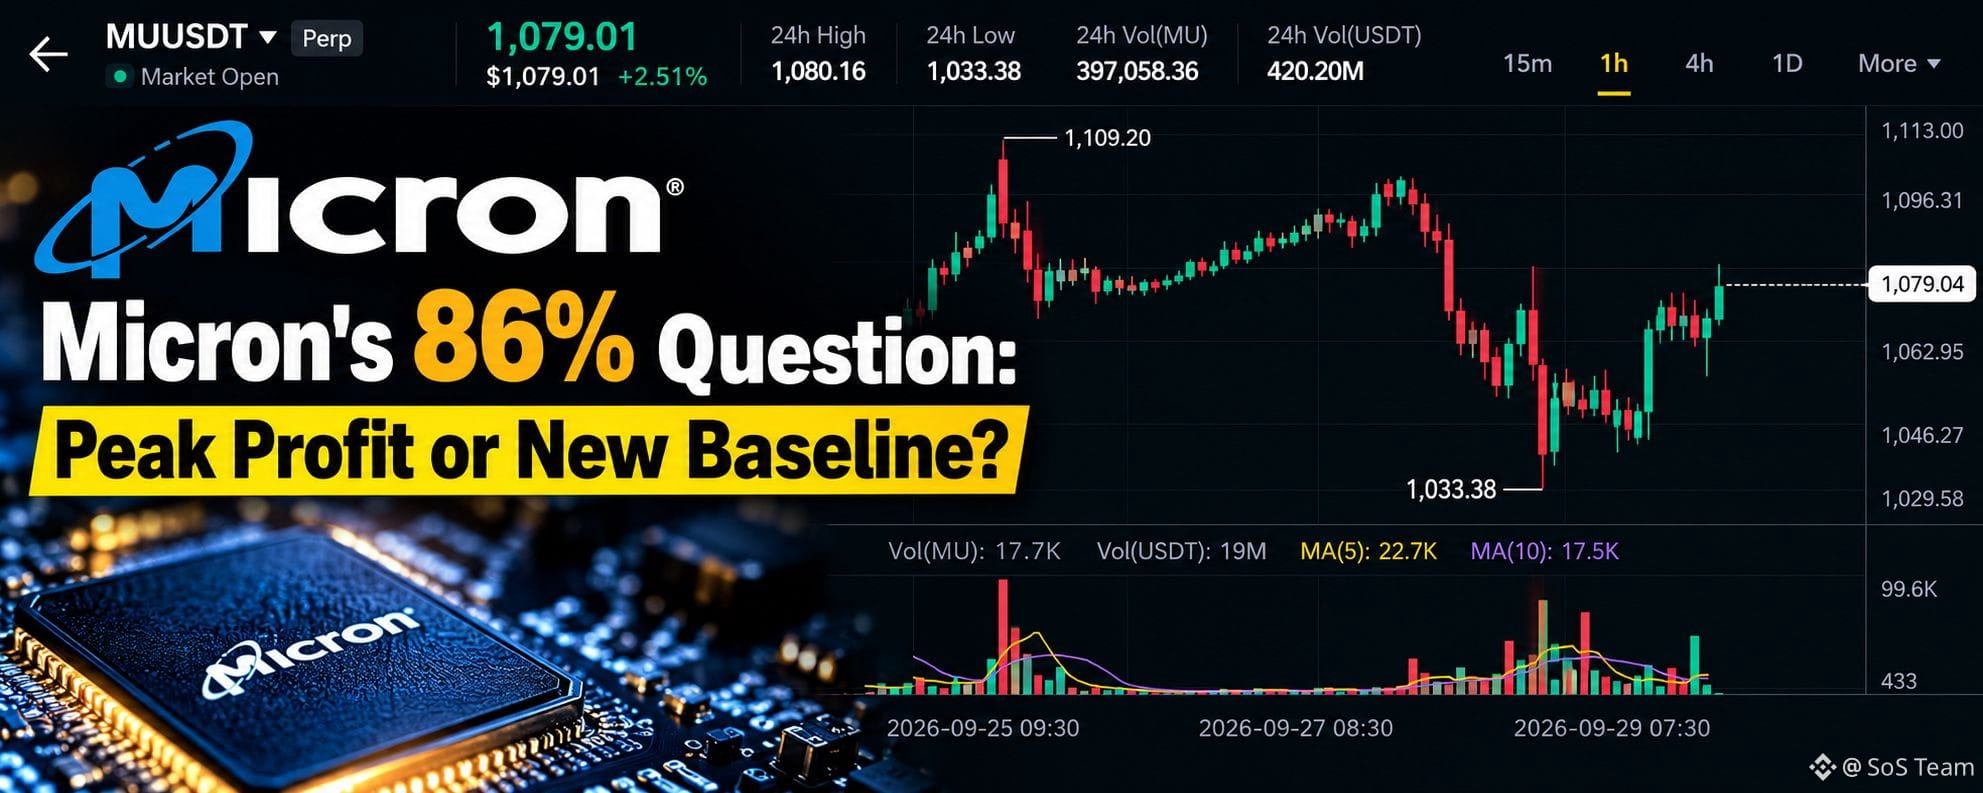
Micron's 86% Question: Peak Profit or New Baseline?Micron Technology $MU is approaching its FY2026 Q4 earnings report, and one number has caught my attention: 86% gross margin.
For me, the bigger question isn't simply whether Micron can meet its forecast. It's whether the company can maintain such high profitability as the memory market evolves.
What the official numbers tell us
Micron reported $41.456 billion in revenue and an 84.9% non-GAAP gross margin in fiscal Q3 2026. For Q4, management guided for revenue of $50 billion, plus or minus $1 billion, and gross margin of approximately 86%.
That is an ambitious target, but it is important to separate guidance from actual results. The company has not confirmed its Q4 performance until it releases the report.
Why the bullish case still matters
AI infrastructure requires advanced memory, including high-bandwidth memory (HBM). If demand remains strong and supply stays tight, Micron could continue to benefit from favorable pricing and a product mix that supports profitability.
That is the part of the story I will be watching closely. Can demand translate into sustainable earnings growth rather than just another strong quarter?
What could go wrong?
I don't think the risks should be ignored. Memory is a cyclical industry, and supply conditions can change as manufacturers expand production.
There is also the question of expectations. Even if Micron reports strong numbers, the stock could react negatively if investors were expecting even more. Slower memory price increases or weaker forward guidance could also challenge the bullish case.
A good earnings report and a good stock entry are not necessarily the same thing.
What I will watch before considering $MU
I don't currently hold a position in Micron, so my approach is to wait for the actual results rather than make a rushed decision before earnings.
I want to see whether the company delivers its margin outlook, what management says about HBM demand and pricing, and whether its next-quarter guidance supports the current growth story.
For me, confirmation matters more than excitement. I would rather reassess the opportunity after seeing the numbers than assume that strong AI demand guarantees further upside.
Final thoughts
Micron's Q4 report could provide important clues about the health of the memory supercycle. The approximately 86% gross-margin outlook gives investors a clear benchmark, but sustaining that profitability may be just as important as achieving it once.
What do you think: can Micron maintain margins around 86%, or could slower price increases signal that the memory cycle is approaching a turning point?
#EarningsSeason $MU
{future}(MUUSDT)
Micron's 86% Question: Peak Profit or New Baseline?
Micron Technology $MU is approaching its FY2026 Q4 earnings report, and one number has caught my attention: 86% gross margin.
For me, the bigger question isn't simply whether Micron can meet its forecast. It's whether the company can maintain such high profitability as the memory market evolves.
What the official numbers tell us
Micron reported $41.456 billion in revenue and an 84.9% non-GAAP gross margin in fiscal Q3 2026. For Q4, management guided for revenue of $50 billion, plus or minus $1 billion, and gross margin of approximately 86%.
That is an ambitious target, but it is important to separate guidance from actual results. The company has not confirmed its Q4 performance until it releases the report.
Why the bullish case still matters
AI infrastructure requires advanced memory, including high-bandwidth memory (HBM). If demand remains strong and supply stays tight, Micron could continue to benefit from favorable pricing and a product mix that supports profitability.
That is the part of the story I will be watching closely. Can demand translate into sustainable earnings growth rather than just another strong quarter?
What could go wrong?
I don't think the risks should be ignored. Memory is a cyclical industry, and supply conditions can change as manufacturers expand production.
There is also the question of expectations. Even if Micron reports strong numbers, the stock could react negatively if investors were expecting even more. Slower memory price increases or weaker forward guidance could also challenge the bullish case.
A good earnings report and a good stock entry are not necessarily the same thing.
What I will watch before considering $MU
I don't currently hold a position in Micron, so my approach is to wait for the actual results rather than make a rushed decision before earnings.
I want to see whether the company delivers its margin outlook, what management says about HBM demand and pricing, and whether its next-quarter guidance supports the current growth story.
For me, confirmation matters more than excitement. I would rather reassess the opportunity after seeing the numbers than assume that strong AI demand guarantees further upside.
Final thoughts
Micron's Q4 report could provide important clues about the health of the memory supercycle. The approximately 86% gross-margin outlook gives investors a clear benchmark, but sustaining that profitability may be just as important as achieving it once.
What do you think: can Micron maintain margins around 86%, or could slower price increases signal that the memory cycle is approaching a turning point?
#EarningsSeason $MU
6
811
·
--
Bearish
Holding $BTC 0.1 USDT
#earningsseason 🔥 Wall Street’s Report Card is About to Shock the Crypto Market! 🚨 Are You Ready for the Volatility? 💥📈
Let’s be real—crypto doesn’t trade in a vacuum anymore. The days of ignoring traditional finance are officially dead. When Wall Street sneezes, liquidity shifts, and crypto moves at lightspeed. ⚡
As a new #EarningsSeason kicks off, traditional financial health is directly fueling our charts. Here is why every trader needs to pay attention right now:
💼 1. Corporate Treasuries Under the Microscope
Giants holding massive digital asset reserves on their balance sheets are putting institutional conviction to the test. These reports give us a raw, transparent look at corporate acquisition power and potential upcoming buy pressure for $BTC.
🤖 2. The Big Tech & AI Ripple Effect
When tech powerhouses report earnings, they dictate the entire global "risk-on" mood. Strong numbers expand liquidity, and that institutional money flows straight into high-beta altcoins and AI-linked crypto ecosystems faster than you can blink.
🏦 3. Spot ETF Inflows & Wall Street Appetite
Asset management heavyweights releasing earnings are exposing the real numbers behind institutional adoption, custody revenues, and sustained spot ETF inflows. Wall Street isn't just watching anymore—they're fully invested.
⚠️ The Bottom Line: Macro volatility is locked in. When earnings beat or miss, liquidity moves fast, setting the stage for massive, violent breakouts across BTC andETH. Are you positioned for the wave, or are you getting caught off guard? 🌊
Drop your thoughts below—bullish breakout or bear trap incoming? Let’s talk strategy! 👇💬
Make sure to Like, Repost 🔄, and Follow to stay ahead of the game! ❤️🔥
#BinanceSquare #CryptoNews #Marketupdates #WallStreet #CryptoTrading $B $BR $BTC
{future}(BUSDT)
#earningsseason 🔥 Wall Street’s Report Card is About to Shock the Crypto Market! 🚨 Are You Ready for the Volatility? 💥📈
Let’s be real—crypto doesn’t trade in a vacuum anymore. The days of ignoring traditional finance are officially dead. When Wall Street sneezes, liquidity shifts, and crypto moves at lightspeed. ⚡
As a new #EarningsSeason kicks off, traditional financial health is directly fueling our charts. Here is why every trader needs to pay attention right now:
💼 1. Corporate Treasuries Under the Microscope
Giants holding massive digital asset reserves on their balance sheets are putting institutional conviction to the test. These reports give us a raw, transparent look at corporate acquisition power and potential upcoming buy pressure for $BTC .
🤖 2. The Big Tech & AI Ripple Effect
When tech powerhouses report earnings, they dictate the entire global "risk-on" mood. Strong numbers expand liquidity, and that institutional money flows straight into high-beta altcoins and AI-linked crypto ecosystems faster than you can blink.
🏦 3. Spot ETF Inflows & Wall Street Appetite
Asset management heavyweights releasing earnings are exposing the real numbers behind institutional adoption, custody revenues, and sustained spot ETF inflows. Wall Street isn't just watching anymore—they're fully invested.
⚠️ The Bottom Line: Macro volatility is locked in. When earnings beat or miss, liquidity moves fast, setting the stage for massive, violent breakouts across BTC andETH. Are you positioned for the wave, or are you getting caught off guard? 🌊
Drop your thoughts below—bullish breakout or bear trap incoming? Let’s talk strategy! 👇💬
Make sure to Like, Repost 🔄, and Follow to stay ahead of the game! ❤️🔥
#BinanceSquare #CryptoNews #Marketupdates #WallStreet #CryptoTrading $B $BR $BTC
5
3.1k

·
--
Bullish
#earningsseason
📊 Wall Street Meets Crypto: How Key Q3 Earnings Could Trigger the Next Big Market Move!
📰Corporate Balance Sheets Matter: Treasury giants like Strategy (MSTR) and Bitcoin mining companies are reporting quarterly results. Strong numbers signal continued corporate buy pressure for BTC.
Tech & AI Correlation: Key reports from Big Tech (Nvidia, AMD, Apple) directly impact broader risk-on sentiment, spilling liquidity straight into major altcoins and AI-linked crypto tokens.
Spot ETF Revenue Signals: Wall Street asset managers (BlackRock, Fidelity) releasing earnings will highlight spot ETF inflows, custody revenue, and growing institutional appetite for digital assets.
Macro Volatility Ahead: When Wall Street beats or misses earnings expectations, liquidity shifts fast—setting the stage for violent market moves in BTC and ETH.
🚀As Wall Street kicks off another #EarningsSeason, traditional financial metrics are spilling over into digital asset markets faster than ever. The days of crypto trading in a vacuum are officially over—Wall Street’s financial health is now a direct catalyst for digital asset liquidity.
1. Corporate Bitcoin Treasuries Under the Spotlight 💼
Public companies holding massive crypto reserves are testing Wall Street’s thesis. Earnings from major corporate holders provide a transparent look into corporate acquisition power, institutional balance sheet health, and potential future buy pressure for Bitcoin.
2. Big Tech Earnings & The "Risk-On" Ripple Effect 🤖
Tech earnings—especially across AI, hardware, and chip manufacturing—dictate overall equity market health. Strong earnings boost investor confidence and expand risk-on liquidity, which historically flows straight into high-beta crypto assets and AI-adjacent crypto ecosystems.
#JapanFSABacksFourthStablecoinTradeSettlementPilot #CryptoNews #BinanceSquare #Marketupdates
1
4
2.1k
·
--
Verified
$MU FY2026 Q4 Earnings - My Bullish Setup
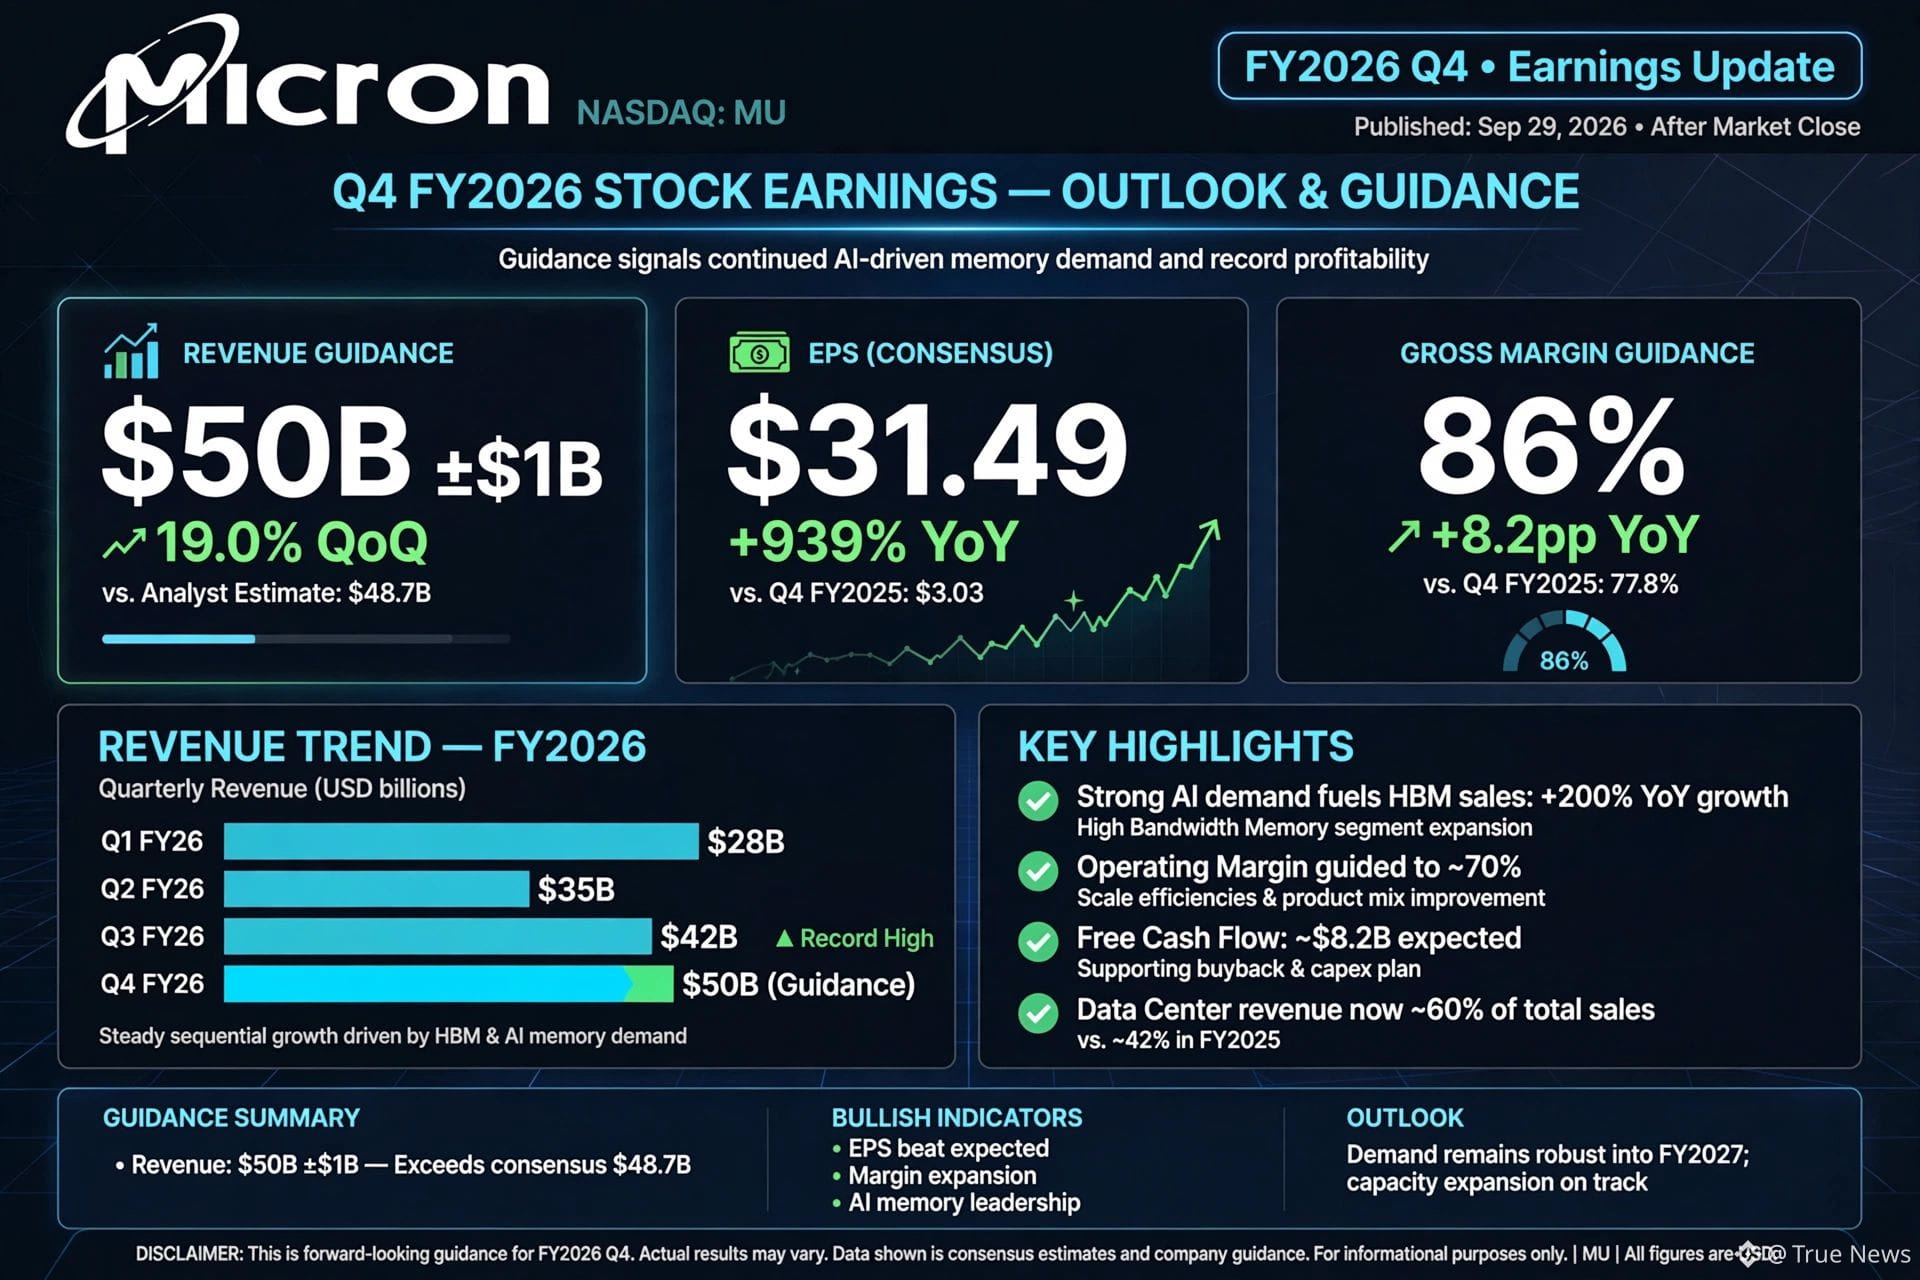
Micron reports Sep 30 after close. Guidance: $50B ± $1B revenue, ∼86% gross margin, ∼$31 EPS. Consensus: $31.49 EPS vs $3.03 YoY.
Wall Street is above guidance - UBS $52.4B / 87.6% GM, Goldman $51.9B / 87.3% GM.
I'm tactically BULLISH. Why? $100B in contracted obligations + HBM4 pricing power. But I won't chase ATH blindly.
Trade Plan: 50% long before earnings, take profit on gap if GM >87%, hold rest for forward guidance. Tight risk management.
What's your call post-earnings? Bullish or bearish?
$MU#earningsseason
$MU FY2026 Q4 Earnings - My Bullish Setup
Micron reports Sep 30 after close. Guidance: $50B ± $1B revenue, ∼86% gross margin, ∼$31 EPS. Consensus: $31.49 EPS vs $3.03 YoY.
Wall Street is above guidance - UBS $52.4B / 87.6% GM, Goldman $51.9B / 87.3% GM.
I'm tactically BULLISH. Why? $100B in contracted obligations + HBM4 pricing power. But I won't chase ATH blindly.
Trade Plan: 50% long before earnings, take profit on gap if GM >87%, hold rest for forward guidance. Tight risk management.
What's your call post-earnings? Bullish or bearish?
$MU #earningsseason
User-0fc0a3a7:
@Square-Creator-f889df39803e .
2
1
1.3k
·
--
Bullish
Verified
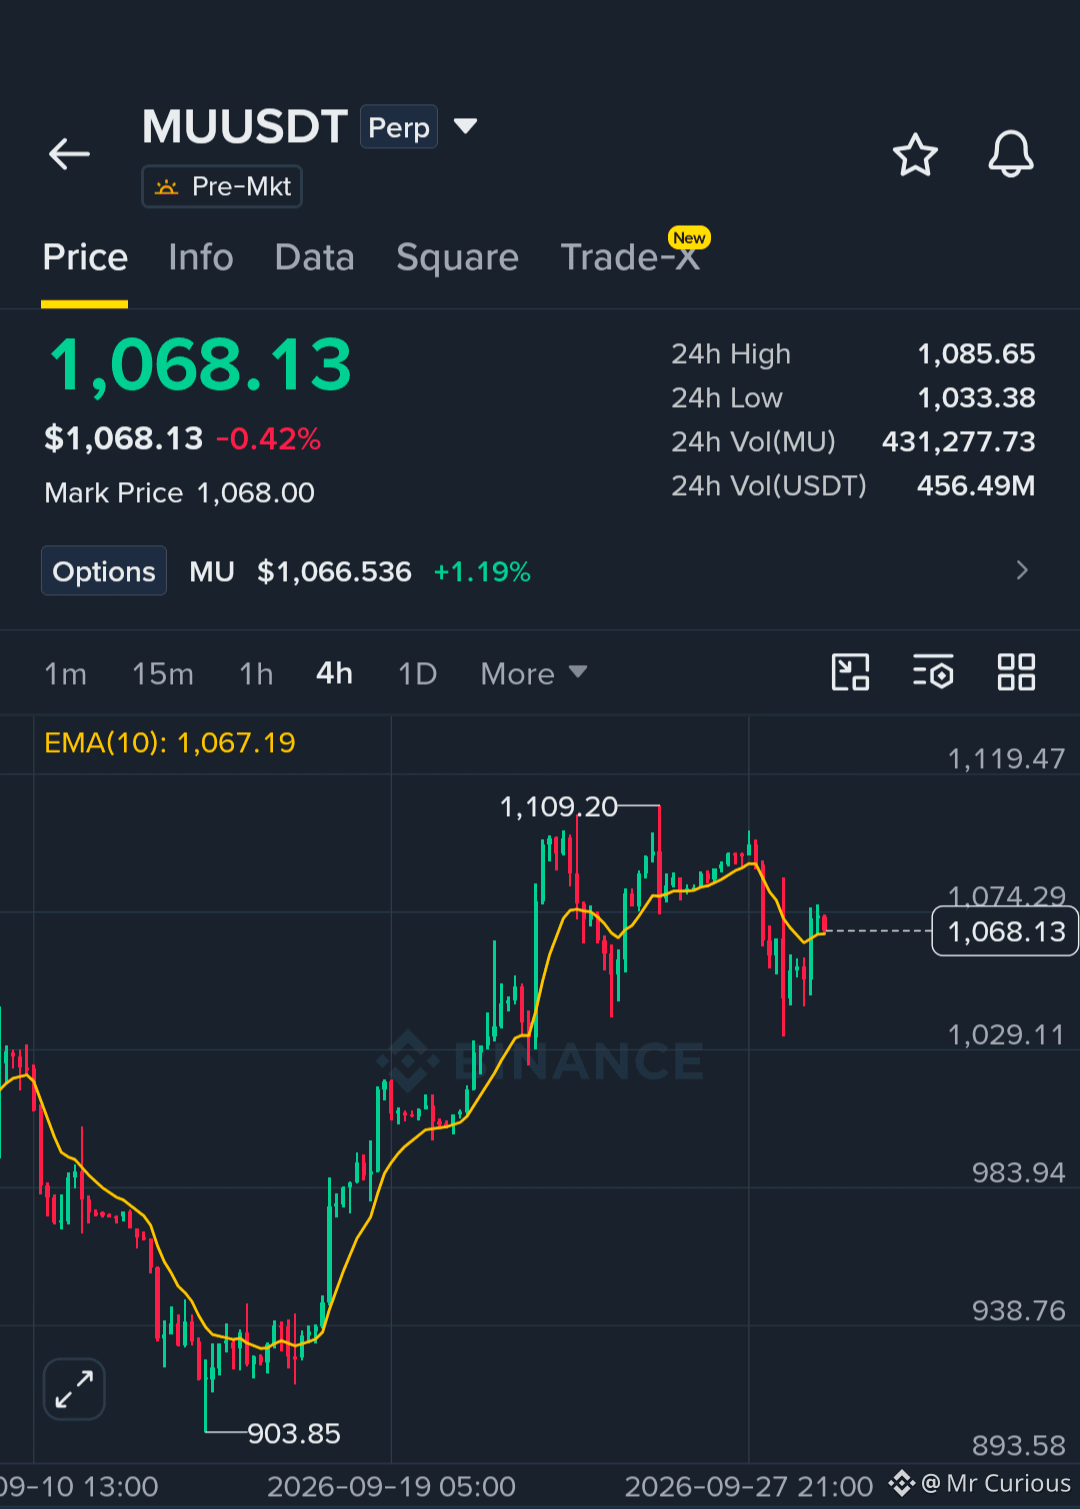
$MU earnings are here, and this is the moment I've been watching.
I'm staying bullish on $MU and planning to take long position while watching the 1080 and 1100 levels as the next upside targets.
Institutional price targets have also been raised, adding more attention to the setup.
Let's see how $MU reacts after the earnings report.
Trade Here 👇🏻
{future}(MUUSDT)
#EarningsSeason
$MU earnings are here, and this is the moment I've been watching.
I'm staying bullish on $MU and planning to take long position while watching the 1080 and 1100 levels as the next upside targets.
Institutional price targets have also been raised, adding more attention to the setup.
Let's see how $MU reacts after the earnings report.
Trade Here 👇🏻
#EarningsSeason
I'm staying bullish on $MU and planning to take long position while watching the 1080 and 1100 levels as the next upside targets.
Institutional price targets have also been raised, adding more attention to the setup.
Let's see how $MU reacts after the earnings report.
Trade Here 👇🏻
#EarningsSeason
subete_miru:
how are you gonna play this out? check reaction after earnings report? or if earnings report is good jump in? or wait for react and a higher time frame close?
2
2
528
·
--
Verified
Micron: 86% Gross Margin — The New Normal or Peak Cycle?MU : I care less about whether Micron beats Q4 expectations
The bigger question is whether the 86% gross margin is a new baseline or simply the peak of the cycle
Micron is benefiting from higher DRAM and HBM prices and tight supply. Q4 guidance is $49–51B in revenue with gross margin around 86%
But every memory cycle has the same problem. High prices eventually attract more supply
HBM is also taking up more DRAM capacity while AI demand keeps pushing higher end products
HBM4 is already in high volume shipments while HBM4E is expected to enter high volume production in 2027
That is why I will watch Q1 guidance more closely than the Q4 numbers
Can margins keep expanding
Can memory prices keep rising
How fast will HBM4 scale
And how long can Micron maintain its pricing power
This is not about being bullish or bearish and it does not need a price target
Is 86% gross margin the new baseline for memory or the peak profit of a cycle running very hot
That answer may matter more than the Q4 numbers themselves
#EarningsSeason
Micron: 86% Gross Margin — The New Normal or Peak Cycle?
MU : I care less about whether Micron beats Q4 expectations
The bigger question is whether the 86% gross margin is a new baseline or simply the peak of the cycle
Micron is benefiting from higher DRAM and HBM prices and tight supply. Q4 guidance is $49–51B in revenue with gross margin around 86%
But every memory cycle has the same problem. High prices eventually attract more supply
HBM is also taking up more DRAM capacity while AI demand keeps pushing higher end products
HBM4 is already in high volume shipments while HBM4E is expected to enter high volume production in 2027
That is why I will watch Q1 guidance more closely than the Q4 numbers
Can margins keep expanding
Can memory prices keep rising
How fast will HBM4 scale
And how long can Micron maintain its pricing power
This is not about being bullish or bearish and it does not need a price target
Is 86% gross margin the new baseline for memory or the peak profit of a cycle running very hot
That answer may matter more than the Q4 numbers themselves
#EarningsSeason
3
238
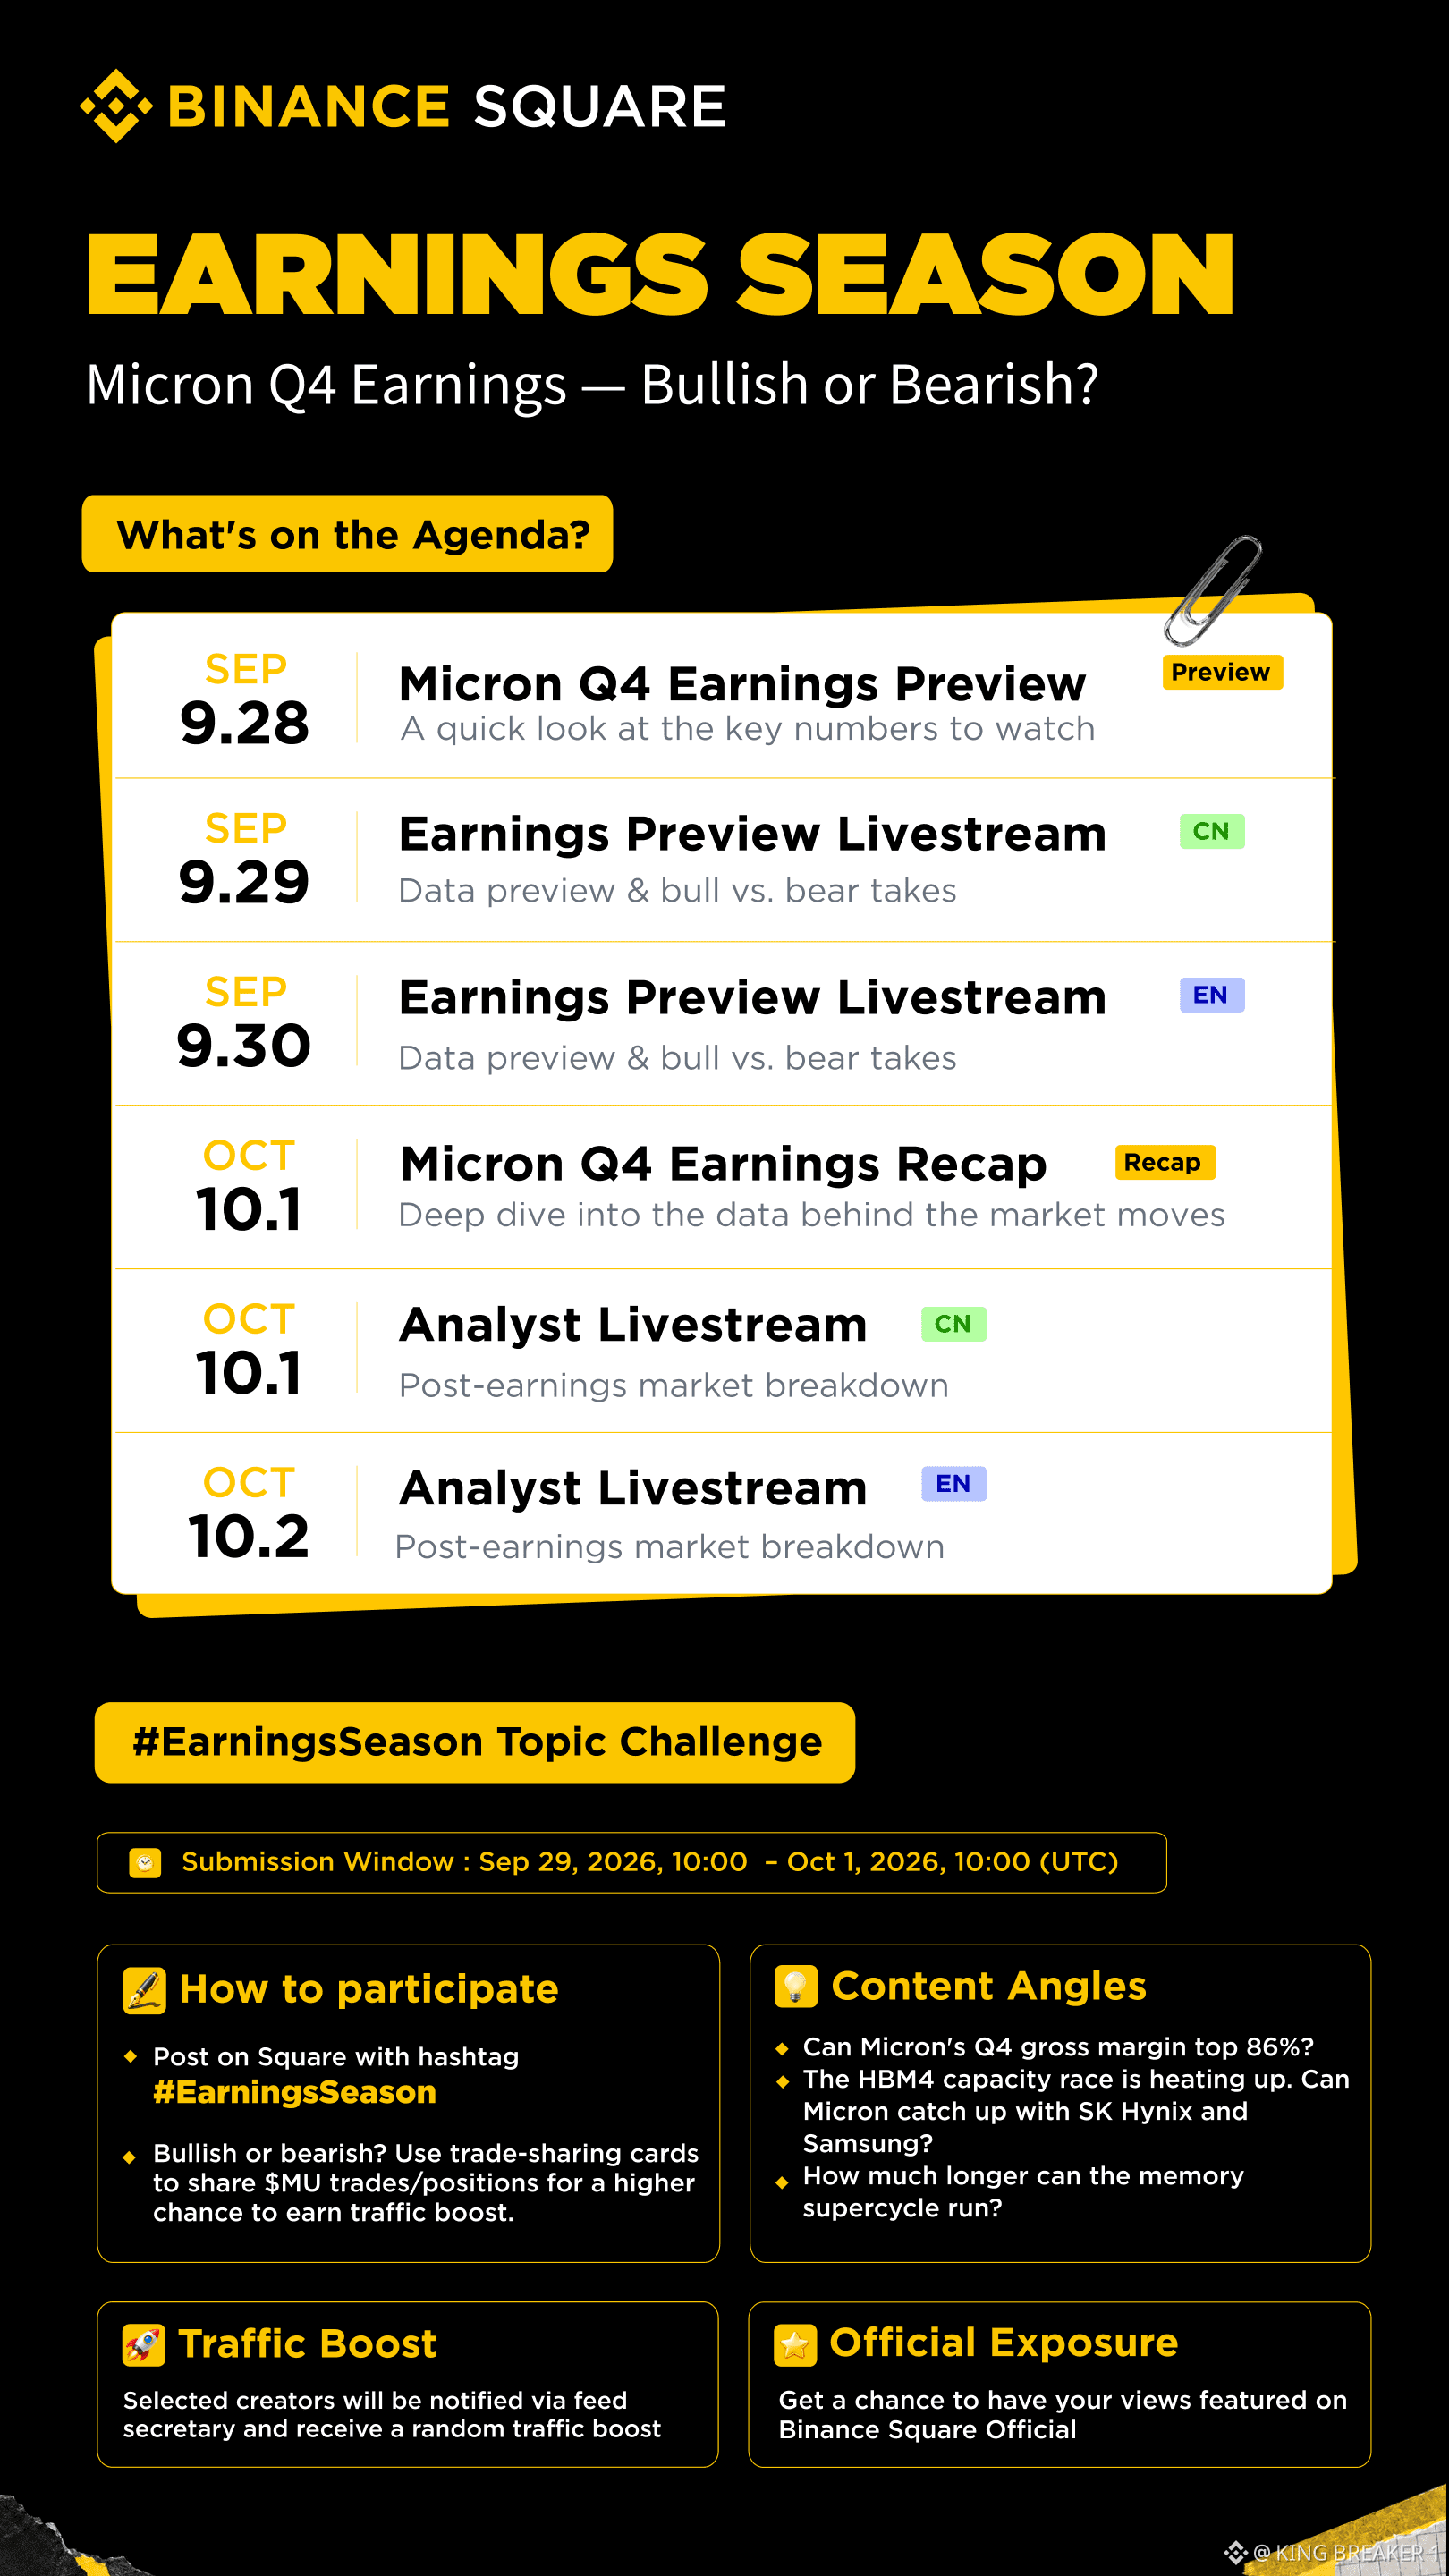
Micron Q4 Earnings: Bullish or Bearish?
Micron’s Q4 earnings are coming up, and the big questions are around margins, HBM4 competition, and the future of the memory supercycle.
Can Micron achieve an 86% gross margin? And can it keep up with SK Hynix and Samsung in the HBM race?
Binance Square is inviting creators to share their research, market views, and $MU trading perspectives using #EarningsSeason.
Submission Window: September 29 – October 1, 2026.
What’s your take on Micron? Bullish or bearish? Let's see what the numbers reveal!
#EarningsSeason
BlockBreaker:
Let's see the earnings numbers!
6
8
414
·
--
Bullish
#earningsseason 📊 Micron ($MU) FY2026 Q4 Earnings Watch |
Micron's FY2026 Q4 earnings are shaping up to be a key event for the semiconductor sector, with investors closely watching whether AI-driven memory demand continues to support the industry's current cycle.
Key metrics to watch
- 📈 Revenue growth and data center demand
- 💰 Gross margin performance
- 🧠 HBM and DRAM market trends
- 🔮 Management's FY2027 guidance
Market outlook
A stronger-than-expected outlook could improve market sentiment, while weaker guidance may increase short-term volatility. The most important factor will likely be management's forward guidance rather than the headline earnings alone.
This is market analysis for educational purposes and not financial advice.
#EarningsSeason #MU #Micron #Semiconductors #AI #Stocks #Investing
{future}(MUUSDT)
#earningsseason 📊 Micron ($MU) FY2026 Q4 Earnings Watch |
Micron's FY2026 Q4 earnings are shaping up to be a key event for the semiconductor sector, with investors closely watching whether AI-driven memory demand continues to support the industry's current cycle.
Key metrics to watch
- 📈 Revenue growth and data center demand
- 💰 Gross margin performance
- 🧠 HBM and DRAM market trends
- 🔮 Management's FY2027 guidance
Market outlook
A stronger-than-expected outlook could improve market sentiment, while weaker guidance may increase short-term volatility. The most important factor will likely be management's forward guidance rather than the headline earnings alone.
This is market analysis for educational purposes and not financial advice.
#EarningsSeason #MU #Micron #Semiconductors #AI #Stocks #Investing
206 Atlas:
Forward guidance matters more than the print, but don't ignore HBM supply constraints if they limit upside despite strong demand.
1
1
364
Verified
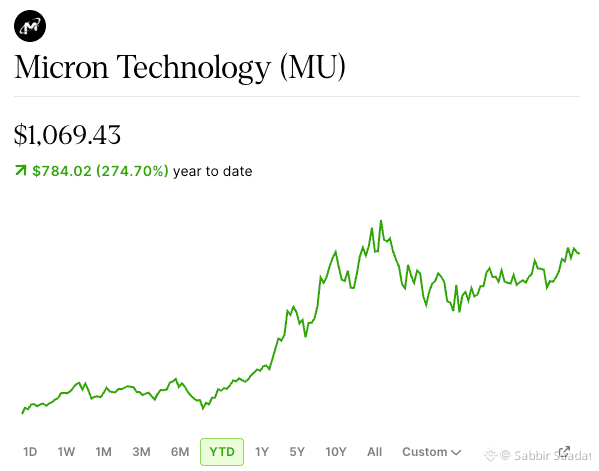
$MU is heading into earnings with expectations near record levels.
Micron reports Q4 tomorrow after market close, with:
- Revenue consensus: ~$50.9B–$51.3B
- Gross margin guidance: ~86%
- Adjusted EPS guidance: $31 ± $1
In each of its last two reports, $MU beat estimates by double-digit margins. Post-print reactions were mixed.
But tomorrow’s print carries more than just a beat-or-miss:
- Gross margins near 86% put the durability of this cycle in focus.
- Enterprise SSD revenue jumped 126% QoQ last quarter, adding another growth driver.
- JPMorgan estimates forward production coverage under Strategic Customer Agreements could exceed 35%, potentially reaching 50%+.
- Investors are watching for details on capital returns ahead of the December 9 CHIPS Act milestone.
Options are already pricing in about an 8.5% swing, with a $1,200 call wall.
All eyes are on FY27 guidance and how long Micron can sustain its record margins.
Trade $MU options with funded capital on Vanquish.
#EarningsSeason
1
184

·
--
Have you noticed how crypto traders obsess over every tech earnings report like it actually dictates where altcoins go next?
Most market participants keep losing money because they blindly front-run Wall Street numbers, treating traditional balance sheets as direct buy signals for digital assets. When greed creeps in, people rush into random plays right before an earnings print, only to get wiped out by the immediate volatility crush when the actual correlation breaks down.
The reality is that macro liquidity cycles move crypto, not a quarterly beat from big tech. If you want to navigate this properly, treat earnings releases as volatility checkpoints rather than directional guarantees. Watch how broader capital flows shift into infrastructure layers like $AVAX or decentralized storage plays like $FIL once the initial earnings hype settles.
Instead of gambling on the immediate headline reaction, map out your key support zones and let the market absorb the institutional volume first. The cleanest entries always appear after the post-earnings dust clears and liquidity rotates back into core assets like $ICP.
Are you actively trading around these corporate earnings reports or just sitting in spot until the volatility cools off?
#EarningsSeason #NvidiaApproves
Have you noticed how crypto traders obsess over every tech earnings report like it actually dictates where altcoins go next?
Most market participants keep losing money because they blindly front-run Wall Street numbers, treating traditional balance sheets as direct buy signals for digital assets. When greed creeps in, people rush into random plays right before an earnings print, only to get wiped out by the immediate volatility crush when the actual correlation breaks down.
The reality is that macro liquidity cycles move crypto, not a quarterly beat from big tech. If you want to navigate this properly, treat earnings releases as volatility checkpoints rather than directional guarantees. Watch how broader capital flows shift into infrastructure layers like $AVAX or decentralized storage plays like $FIL once the initial earnings hype settles.
Instead of gambling on the immediate headline reaction, map out your key support zones and let the market absorb the institutional volume first. The cleanest entries always appear after the post-earnings dust clears and liquidity rotates back into core assets like $ICP .
Are you actively trading around these corporate earnings reports or just sitting in spot until the volatility cools off?
#EarningsSeason #NvidiaApproves
88
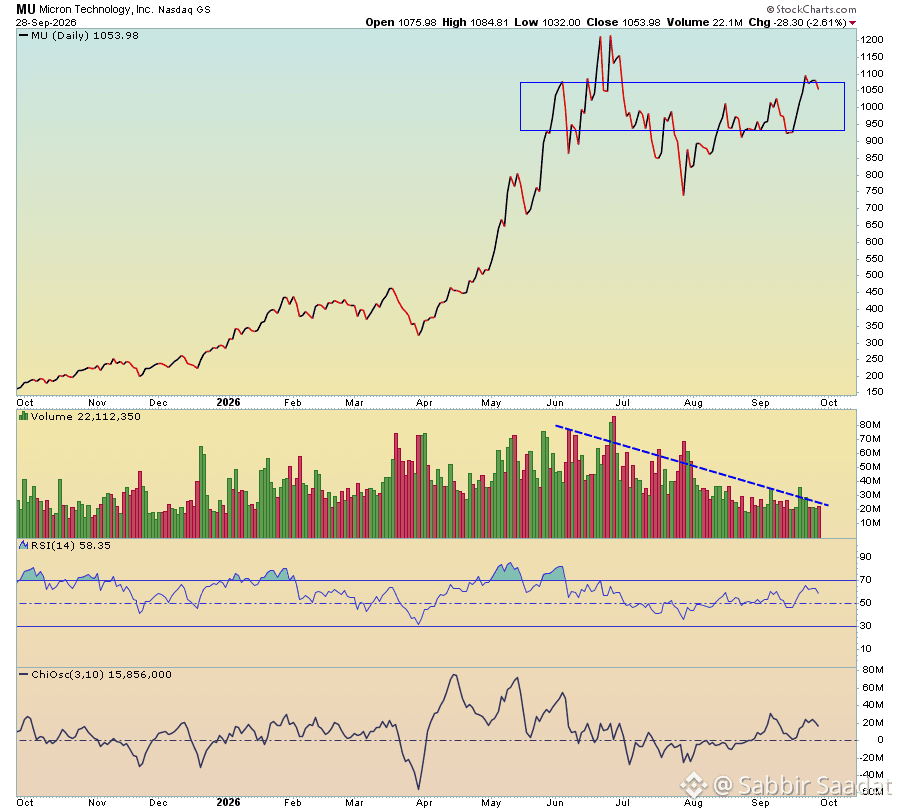
$MU Micron has endured some pretty harsh consolidations in the past 4 months or so.... the big picture here is such that what really matters is this 150-pt range..... any deviation out of it would be drawn back into this consolidation zone, while volume has generally cooled down.... the incoming earnings will define its trend into end of year - if a big b/o happens, it should take it up 400-500 pts minimum.... if no good, room for downside is pretty limited.....
#earningsseason
#earningsseason
humkash:
Please Follow me. I Followed you back. Please like my post.
1
1
143
#earningsseason
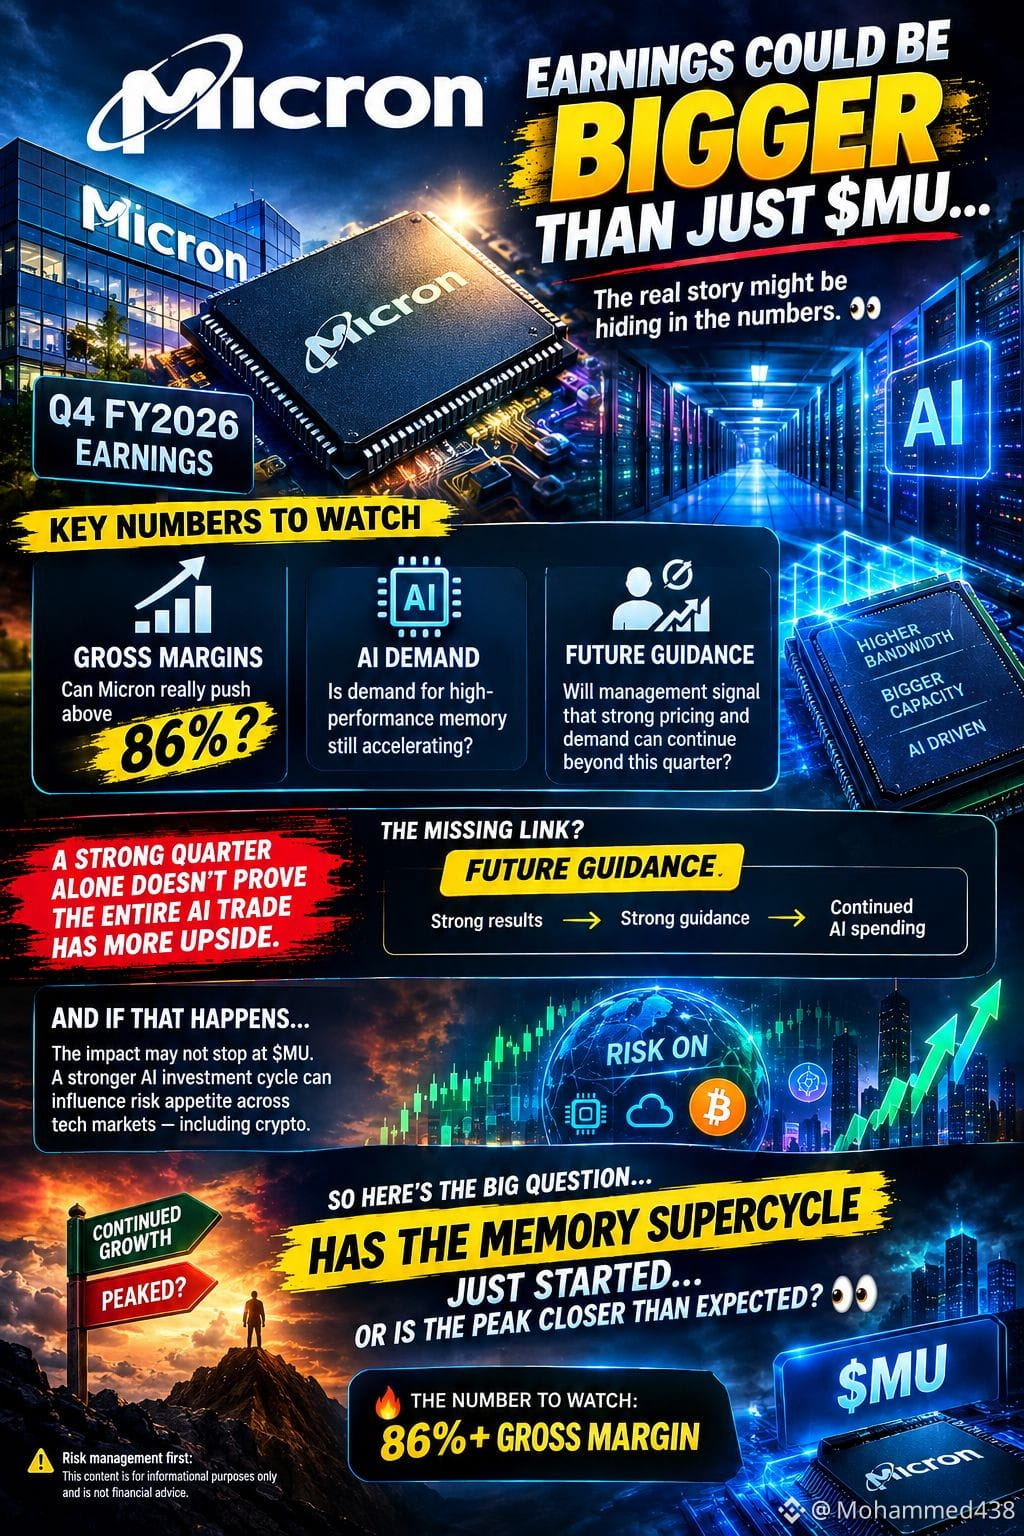
🚨 Micron Is About to Reveal Something Bigger Than $MU…
Micron’s Q4 FY2026 earnings are about to test a much bigger AI story.
The stock everyone is watching is $MU
{future}(MUUSDT)
But here’s what traders may actually be missing:
The real question isn’t whether Micron beats earnings.
It’s whether the numbers prove that the AI memory supercycle is still accelerating.
The market is watching one number especially closely:
86%+ gross margin.
If Micron can reach that level, it would show just how powerful pricing and demand for high-performance memory have become.
Then comes the bigger question:
📈 Is AI demand still accelerating?
🤖 Are customers still fighting for advanced memory capacity?
💰 Can Micron maintain these margins?
👀 And what does management say about the next quarter?
But here’s the important part:
A strong quarter alone doesn't prove the entire AI trade has more upside.
The missing link is future guidance.
Strong results → strong guidance → continued AI infrastructure spending
That chain could reinforce the broader AI investment narrative.
And if that happens, the impact may not stop at $MU.
AI infrastructure remains one of the major forces shaping risk appetite across technology and other markets — including crypto.
But what if the numbers look great.
.and management signals that growth is starting to slow?
Then traders could start asking a very different question Did Micron just confirm the Memory Supercycle… or show us that the peak is closer than expected?
That’s why this earnings report could matter far beyond Micron.
🔥 The number to watch: 86%+ gross margin.
But the number that could matter even more?
Future guidance.
$MU $BTC
{future}(BTCUSDT)
#MU #AI #AIInfrastructure #Crypto
#earningsseason
🚨 Micron Is About to Reveal Something Bigger Than $MU …
Micron’s Q4 FY2026 earnings are about to test a much bigger AI story.
The stock everyone is watching is $MU
But here’s what traders may actually be missing:
The real question isn’t whether Micron beats earnings.
It’s whether the numbers prove that the AI memory supercycle is still accelerating.
The market is watching one number especially closely:
86%+ gross margin.
If Micron can reach that level, it would show just how powerful pricing and demand for high-performance memory have become.
Then comes the bigger question:
📈 Is AI demand still accelerating?
🤖 Are customers still fighting for advanced memory capacity?
💰 Can Micron maintain these margins?
👀 And what does management say about the next quarter?
But here’s the important part:
A strong quarter alone doesn't prove the entire AI trade has more upside.
The missing link is future guidance.
Strong results → strong guidance → continued AI infrastructure spending
That chain could reinforce the broader AI investment narrative.
And if that happens, the impact may not stop at $MU .
AI infrastructure remains one of the major forces shaping risk appetite across technology and other markets — including crypto.
But what if the numbers look great.
.and management signals that growth is starting to slow?
Then traders could start asking a very different question Did Micron just confirm the Memory Supercycle… or show us that the peak is closer than expected?
That’s why this earnings report could matter far beyond Micron.
🔥 The number to watch: 86%+ gross margin.
But the number that could matter even more?
Future guidance.
$MU $BTC
#MU #AI #AIInfrastructure #Crypto
206 Atlas:
Micron’s guidance matters more for the AI narrative than its current margins.
2
3
901
·
--
Bullish
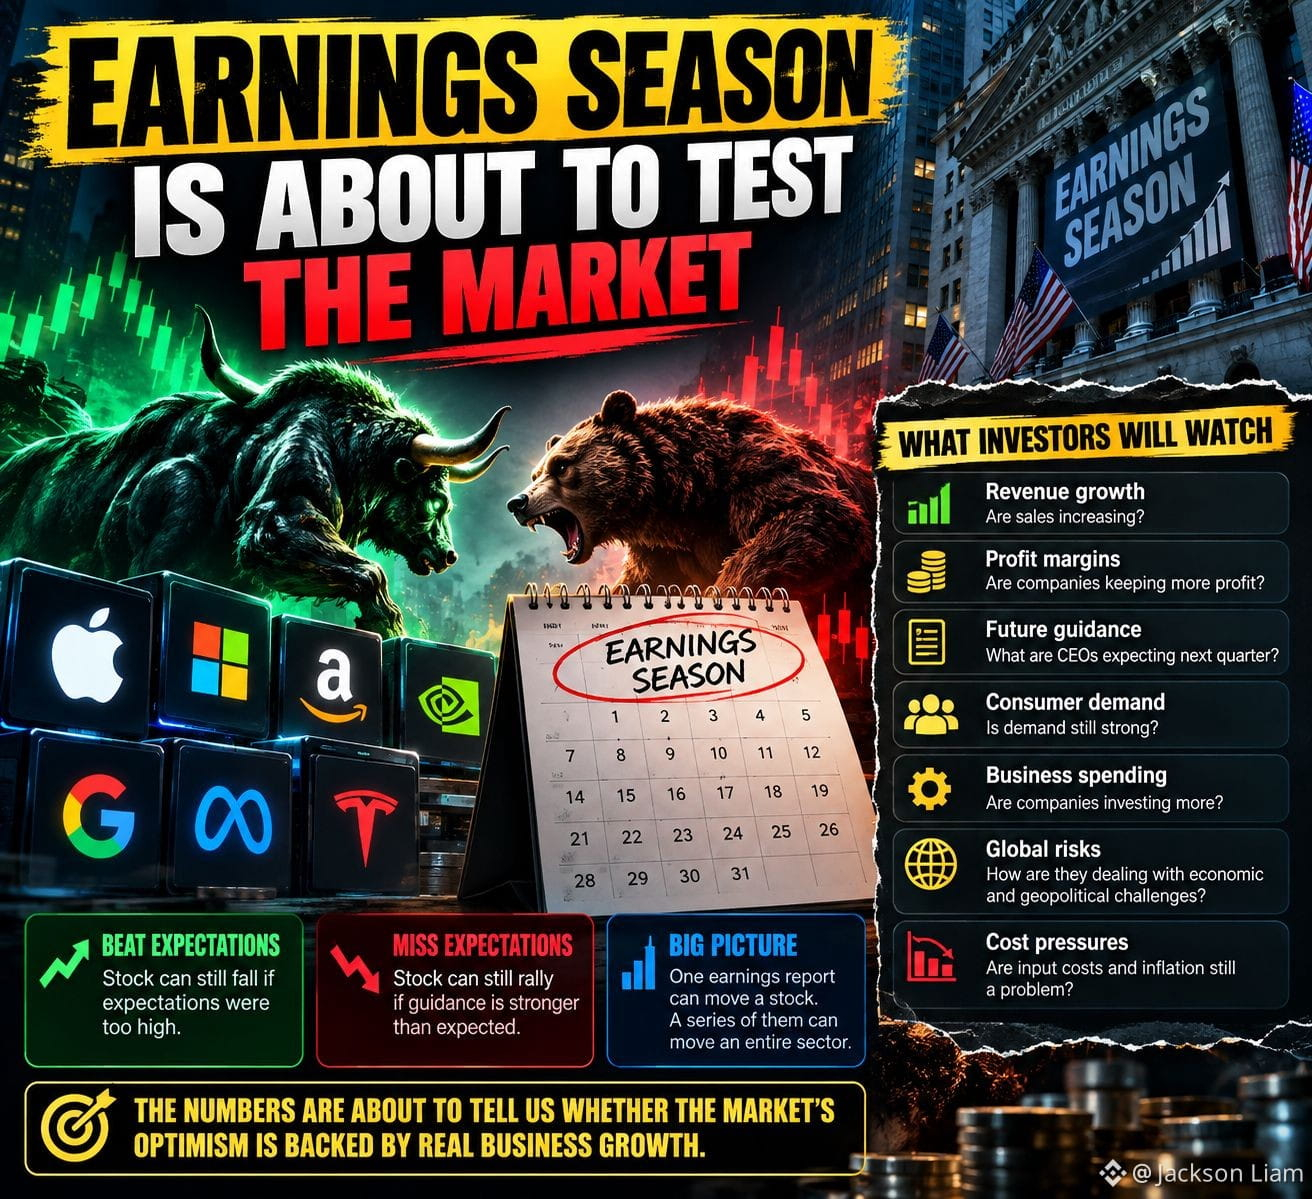
EARNINGS SEASON IS ABOUT TO TEST THE MARKET 🚨
The market has been pricing in growth, strong demand, and resilient corporate profits.
Now companies have to prove it.
Investors won’t just be looking at whether earnings beat or missed estimates.
They’ll be watching:
💰 Revenue growth
📈 Profit margins
👀 Future guidance
🏦 Consumer demand
⚙️ Business spending
🌍 Global risks
📉 Cost pressures
And here’s where things get interesting:
A company can beat earnings and still fall if expectations were too high.
Another can miss estimates and rally if management delivers stronger guidance.
That’s why this earnings season could create some serious opportunities — and some painful surprises.
One headline can move a stock.
A major earnings wave can move an entire sector.
The numbers are about to tell us whether the market’s optimism is backed by real business growth.
#EarningsSeason
1
146
#earningsseason
🚨 MICRON EARNINGS ARE COMING — $MU BULLISH OR BEARISH? 👀
The FY2026 Q4 results drop September 30, and this earnings report could be a major test for the AI memory supercycle. 📊
Micron previously guided for:
💰 $50B ± $1B revenue
📈 ~86% gross margin
⚡ $31 EPS ± $1
And with AI demand driving massive memory requirements, investors will be watching the numbers — but guidance for the next quarter may matter even more. 👀
🔥 BULL CASE: Strong results + higher guidance = memory supercycle stays hot
🩸 BEAR CASE: Results disappoint + weaker outlook = AI memory trade gets hit
Options markets are pricing a move of roughly 8.6% in either direction around earnings.
WHAT'S YOUR CALL FOR $MU?
VOTE BELOW 👇
#MicronsAIboom #MU #EarningsSeason
#earningsseason
🚨 MICRON EARNINGS ARE COMING — $MU BULLISH OR BEARISH? 👀
The FY2026 Q4 results drop September 30, and this earnings report could be a major test for the AI memory supercycle. 📊
Micron previously guided for:
💰 $50B ± $1B revenue
📈 ~86% gross margin
⚡ $31 EPS ± $1
And with AI demand driving massive memory requirements, investors will be watching the numbers — but guidance for the next quarter may matter even more. 👀
🔥 BULL CASE: Strong results + higher guidance = memory supercycle stays hot
🩸 BEAR CASE: Results disappoint + weaker outlook = AI memory trade gets hit
Options markets are pricing a move of roughly 8.6% in either direction around earnings.
WHAT'S YOUR CALL FOR $MU ?
VOTE BELOW 👇
#MicronsAIboom #MU #EarningsSeason
🟢 BULLISH 🚀
🔴 BEARISH 📉
18 hr(s) left
58
·
--
Micron Earnings: Can the Memory Supercycle Hold?Micron’s FY2026 Q4 earnings are more than just another earnings report for $MU.
The bigger question is whether the numbers can justify the extremely strong memory-cycle narrative that has built up around AI infrastructure, HBM and tight DRAM/NAND supply.
Micron has guided for around $50B in Q4 revenue, with a gross margin of approximately 86% and adjusted EPS around $31.
That 86% margin is the number I’ll be watching most closely.
For context, Micron generated $41.46B revenue in Q3, while gross margin reached 84.6%. Moving from there toward 86% would show that pricing power and product mix are still supporting extraordinary profitability.
But there is another side to the story.
The market already expects a huge quarter. Current consensus estimates are around $50.86B revenue and $31.45 EPS, meaning simply beating the numbers may not be enough to create a strong reaction. Investors will likely pay close attention to what management says about future memory pricing, HBM demand, supply conditions and the pace of capacity expansion.
The interesting part of this cycle is that Micron’s business is benefiting from AI servers requiring significantly more high-performance memory. Micron has also said its HBM4 is already in high-volume shipments for its lead customer, while HBM4E volume production is expected in 2027.
So for me, the earnings reaction isn't simply about:
Did Micron beat EPS?
I’m more interested in:
• Can gross margin actually reach or exceed 86%?
• Is memory pricing still moving higher?
• How strong is HBM demand going into FY2027?
• Is supply still tight enough to protect margins?
• And most importantly, does management give investors another reason to believe this memory cycle can last?
There is also an important risk.
Memory has historically been a cyclical business. Extremely high margins can attract additional capacity, and eventually supply can catch up with demand. That means the market may start looking beyond FY2026 numbers and asking how sustainable these margins really are.
That is why this earnings report feels bigger than just $MU.
If Micron can deliver strong numbers and maintain confidence around future pricing, HBM demand and supply discipline, it would provide another important data point for the broader AI-memory thesis.
If the numbers are strong but future guidance becomes more cautious, the market could focus on how much optimism is already priced into the stock.
I’m watching the 86% gross-margin target and FY2027 commentary more closely than the headline EPS number.
Do you think Micron can push gross margin above 86%, or are expectations already too high?
#EarningsSeason $MU
Micron Earnings: Can the Memory Supercycle Hold?
Micron’s FY2026 Q4 earnings are more than just another earnings report for $MU .
The bigger question is whether the numbers can justify the extremely strong memory-cycle narrative that has built up around AI infrastructure, HBM and tight DRAM/NAND supply.
Micron has guided for around $50B in Q4 revenue, with a gross margin of approximately 86% and adjusted EPS around $31.
That 86% margin is the number I’ll be watching most closely.
For context, Micron generated $41.46B revenue in Q3, while gross margin reached 84.6%. Moving from there toward 86% would show that pricing power and product mix are still supporting extraordinary profitability.
But there is another side to the story.
The market already expects a huge quarter. Current consensus estimates are around $50.86B revenue and $31.45 EPS, meaning simply beating the numbers may not be enough to create a strong reaction. Investors will likely pay close attention to what management says about future memory pricing, HBM demand, supply conditions and the pace of capacity expansion.
The interesting part of this cycle is that Micron’s business is benefiting from AI servers requiring significantly more high-performance memory. Micron has also said its HBM4 is already in high-volume shipments for its lead customer, while HBM4E volume production is expected in 2027.
So for me, the earnings reaction isn't simply about:
Did Micron beat EPS?
I’m more interested in:
• Can gross margin actually reach or exceed 86%?
• Is memory pricing still moving higher?
• How strong is HBM demand going into FY2027?
• Is supply still tight enough to protect margins?
• And most importantly, does management give investors another reason to believe this memory cycle can last?
There is also an important risk.
Memory has historically been a cyclical business. Extremely high margins can attract additional capacity, and eventually supply can catch up with demand. That means the market may start looking beyond FY2026 numbers and asking how sustainable these margins really are.
That is why this earnings report feels bigger than just $MU .
If Micron can deliver strong numbers and maintain confidence around future pricing, HBM demand and supply discipline, it would provide another important data point for the broader AI-memory thesis.
If the numbers are strong but future guidance becomes more cautious, the market could focus on how much optimism is already priced into the stock.
I’m watching the 86% gross-margin target and FY2027 commentary more closely than the headline EPS number.
Do you think Micron can push gross margin above 86%, or are expectations already too high?
#EarningsSeason $MU
1
204
·
--
Verified
#EarningsSeason | $MU : The 86% Margin Test
Micron’s Sept. 30 FY2026 Q4 earnings are less about simply beating estimates and more about whether the current memory super cycle can support another major step-up.
Micron generated $41.46B revenue in Q3, up sharply from $23.86B in Q2, while gross margin reached roughly 84.6%. For Q4, management guided to $50B ± $1B revenue, ~86% gross margin, and $31 ± $1 non-GAAP EPS.
That guidance itself sets a very high bar:
$41.46B → $50B revenue
≈ 20.6% sequential growth
~84.6% → ~86% gross margin
≈ +1.4 percentage points
The bigger story is HBM and AI infrastructure. Micron says its HBM4 is already in high-volume shipments for its lead customer, while HBM4E development is underway with volume production expected in 2027.
And the supply picture matters too. Samsung said today that HBM could account for nearly 30% of global DRAM wafer capacity next year, versus around 20% currently. Because HBM and standard DRAM use the same wafer capacity, a larger HBM allocation can tighten conventional DRAM supply.
So my trade plan is simple: I would not chase the first post-earnings candle. I want to see three things together:
1️⃣ Revenue: Does $MU beat or merely meet the $50B guide?
2️⃣ Margin: Can Micron actually sustain or exceed the ~86% target?
3️⃣ FY2027 outlook: Does management signal that AI/HBM demand and pricing strength can continue?
If earnings beat but FY2027 commentary shows margin pressure, the headline numbers may not tell the whole story.
For me, the real question is not “Will Micron have a strong quarter?”
It is:
Can an 86%+ gross-margin environment become sustainable as the memory super cycle enters its next phase?
That is what I’ll be watching before adjusting my $MU position.
#EarningsSeason #LearnWithFatima
With Micron guiding ~86% gross margin on $50B Q4 revenue, can HBM demand and tight DRAM supply sustain margins above 86% through FY2027 despite competition and capacity expansion?
🟢 A. Strong HBM
🟡 B. Margin Normalizes
🔴 C. Supply Pressure
⚪ D. Unclear Outlook
19 hr(s) left
3
732

#EarningsSeason
Can Micron beat 86% gross margin — and will that even be enough for MU?
That’s the part I’m watching most closely going into Micron’s FY2026 Q4 report on September 30.
Micron’s own guide is already huge: $50B ± $1B revenue, roughly 86% gross margin, and $31 ± $1 in non-GAAP EPS.
And honestly, I think 86% is achievable.
But maybe that’s not the real question.
Q3 already delivered an 84.9% non-GAAP gross margin, so the step toward 86% isn’t some crazy leap. The bigger issue is what happens after that. Micron says its Q4 margin outlook already assumes a meaningful moderation in the rate of price increases.
That makes the FY2027 outlook really important.
If Micron beats Q4 but sounds cautious on future pricing, margins, or capacity, the market could focus on the second half of the sentence rather than the headline beat.
And there’s another interesting piece: Micron is already shipping HBM4 in high volume to its lead customer, while HBM4E volume production is expected in 2027. The company also expects FY2027 quarterly capex to run above Q4 levels as it expands cleanroom capacity for longer-term demand.
So I’m constructive on the fundamentals, but much less comfortable assuming the stock automatically follows.
The real test is whether these margins are becoming a durable earnings structure — or simply an extraordinary point in the memory cycle.
That’s what I’ll be listening for after the numbers.
Still trying to figure out what this actually changes.
307
·
--
#earningsseason Micron earnings this week could test whether the memory boom has more room to run - Micron is generating margins that would have been almost unthinkable in previous memory cycles, while the stock still trades at a low earnings multiple.$AXTI $SYRUP $ICP
#earningsseason Micron earnings this week could test whether the memory boom has more room to run - Micron is generating margins that would have been almost unthinkable in previous memory cycles, while the stock still trades at a low earnings multiple.$AXTI $SYRUP $ICP
146
·
--
#earningsseason
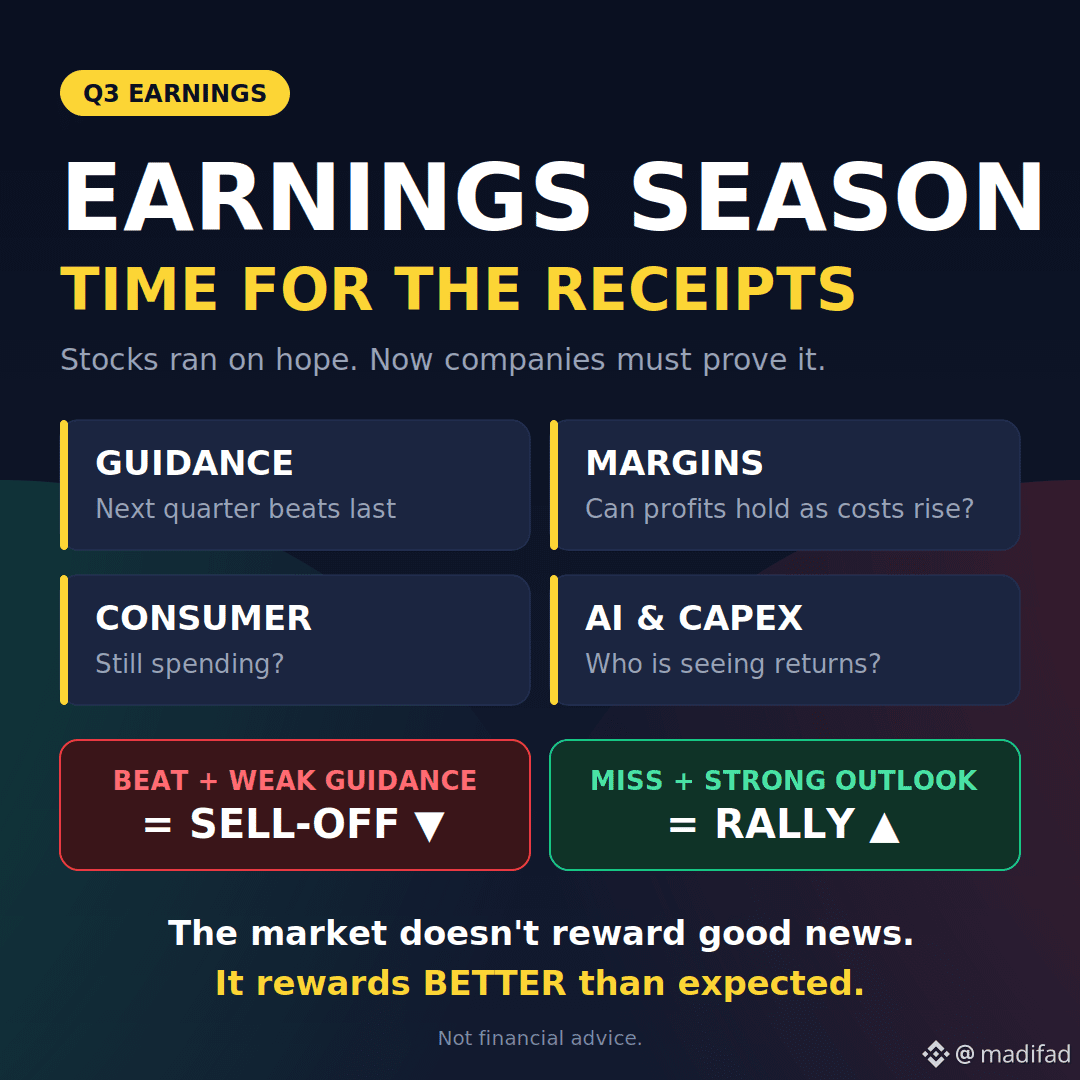
EARNINGS SEASON IS HERE. TIME FOR THE RECEIPTS 🔥
Stocks have been running on hope.
Now companies have to prove it.
What actually moves prices:
🎯 Guidance matters more than last quarter
🧮 Margins: can profits hold as costs rise?
🛒 Consumer demand: still spending?
🏭 AI and capex: who's seeing returns?
The market doesn't reward good news. It rewards better than expected news.
✅ Beat + weak guidance = sell-off
✅ Miss + strong outlook = rally
Check what's priced in. Size your positions. Don't get caught by one gap.
Are you positioned or waiting? 👇
Not financial advice.
#earningsseason #stocks #Investing
AngelOfCrypto_-:
nice
3
640
·
--
🔥 Why Crypto Traders Should Watch Wall Street
Wall Street earnings aren’t just about stocks anymore. They can move crypto too. 👀
As earnings season kicks off, here are 3 things I’m watching:
💼 1. Corporate BTC Holdings
Companies holding digital assets will reveal how strong their balance sheets and buying capacity really are. That could offer clues about future institutional demand for $BTC.
🤖 2. Big Tech & AI Earnings
Strong tech earnings can improve risk appetite across markets. Weak guidance can do the opposite. Either way, high-beta assets and AI-related crypto could react quickly.
🏦 3. Institutional Crypto Adoption
Earnings from major financial firms can give us clues about custody, trading activity and demand for spot crypto products.
And here’s the important part:
A strong earnings report doesn’t automatically mean BTC pumps.
Markets trade expectations.
A beat can already be priced in. A miss can trigger a sharp risk-off move.
So instead of watching headlines alone, watch:
📊 Earnings vs expectations
💰 Liquidity flows
📈 BTC volume & price structure
🏦 Institutional demand
⚠️ Market reaction after the numbers
Earnings season could bring some serious volatility.
Are you expecting BTC to break higher 🚀 or face a pullback 🐻?
Drop your view below 👇
$BTC $B $BR
#EarningsSeason #CryptoNews #Marketupdates #WallStreet #cryptotrading
{spot}(BTCUSDT)
{future}(BRUSDT)
🔥 Why Crypto Traders Should Watch Wall Street
Wall Street earnings aren’t just about stocks anymore. They can move crypto too. 👀
As earnings season kicks off, here are 3 things I’m watching:
💼 1. Corporate BTC Holdings
Companies holding digital assets will reveal how strong their balance sheets and buying capacity really are. That could offer clues about future institutional demand for $BTC .
🤖 2. Big Tech & AI Earnings
Strong tech earnings can improve risk appetite across markets. Weak guidance can do the opposite. Either way, high-beta assets and AI-related crypto could react quickly.
🏦 3. Institutional Crypto Adoption
Earnings from major financial firms can give us clues about custody, trading activity and demand for spot crypto products.
And here’s the important part:
A strong earnings report doesn’t automatically mean BTC pumps.
Markets trade expectations.
A beat can already be priced in. A miss can trigger a sharp risk-off move.
So instead of watching headlines alone, watch:
📊 Earnings vs expectations
💰 Liquidity flows
📈 BTC volume & price structure
🏦 Institutional demand
⚠️ Market reaction after the numbers
Earnings season could bring some serious volatility.
Are you expecting BTC to break higher 🚀 or face a pullback 🐻?
Drop your view below 👇
$BTC $B $BR
#EarningsSeason #CryptoNews #Marketupdates #WallStreet #cryptotrading
25
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#EarningsSeason
183,377 views
1,719 Discussing
2
#BitwiseLaunchesFirstSpotNEARETF
5,437 views
207 Discussing
3
#USJobOpeningsFallToFiveMonthLow
8,551 views
156 Discussing
4
#ECBToTestAIAgentsInDigitalEuroPayments
12,131 views
328 Discussing
5
#JapanFSABacksFourthStablecoinTradeSettlementPilot
13,913 views
380 Discussing
6
#BitgetHackerFailsToMoveStolenFunds
28,122 views
513 Discussing
7
#BitMineETHHoldingsTop6Million
25,504 views
641 Discussing
8
#StrategyAdds1666BTCHoldingsReach847666
21,839 views
449 Discussing
9
#NvidiaApproves$150BBuyback
4,280 views
68 Discussing
10
#OpenAIDelaysGPT6.1OverSafetyIssues
34,063 views
815 Discussing