

#pmi
pmi
121,579 views
387 Discussing
Hot
Latest

S&P Global released the preliminary October PMI data for the United States today, showing a notable divergence across economic sectors. The Manufacturing PMI unexpectedly climbed to 56.0, beating expectations of 55.5 and marking its highest reading in 53 months. In contrast, the Services PMI softened to 57.9, below forecasts of 58.0 and down from 58.8 previously, pulling the Composite PMI to 57.6.
The 53-month peak in manufacturing activity highlights strong underlying industrial resilience despite tighter monetary policy. However, the slight cooling in services suggests consumer demand is moderating. Combined, these figures present a mixed macroeconomic backdrop for the Federal Reserve as it monitors growth momentum.
Traditional financial markets reacted with caution following the release. Both the S&P 500 and Nasdaq dropped to five-week lows, falling 0.4% and 0.2% respectively, while bond yields digested the persistent strength in factory activity alongside equity de-risking.
For digital assets, robust industrial data dampens immediate hopes for aggressive monetary easing, keeping risk appetite constrained. $BTC and broader crypto markets may face continued short-term consolidation as traders balance sticky economic strength with softening tech valuations. 📊
#PMI #USData #MacroEconomics #FederalReserve
57

·
--
U.S. PMI eased, but interest rates rose: On the 23rd, the two-year Treasury yield climbed to 4.69% from 4.65% the previous day.
If you’re hoping for a cooling economy and cheaper financing, it’s natural to see weaker data and expect monetary easing. But it’s important to distinguish between slower expansion and accelerating price hikes by businesses.
S&P Global reported on the 23rd that the composite PMI fell to 57.6 in October from 58.4 in September, still well above the 50-point expansion threshold. Meanwhile, the pace of selling-price increases by businesses was the fastest since August 2022. Demand remains strong and price pressures have not eased, so slower growth alone is not enough to conclude that inflation is cooling.
The two-year yield had fallen 16 basis points on the 22nd, then rebounded 4 basis points on the 23rd; it has not moved in one direction consistently. This is a Treasury yield, not a funding rate on contracts, and the day’s change cannot be attributed entirely to the PMI.
For risk positions that rely on cheap financing, delayed monetary easing means higher costs for holding positions over time. The case for easing financing pressure will be more complete if businesses slow their price increases and short-term yields continue to fall. Betting on the PMI headline alone means taking on the risk that neither of these developments has materialized yet.
This content participates in Binance Square’s content mining program. The author may receive platform commissions and engagement rewards.
#宏观 #PMI #InterestRates
53

·
--
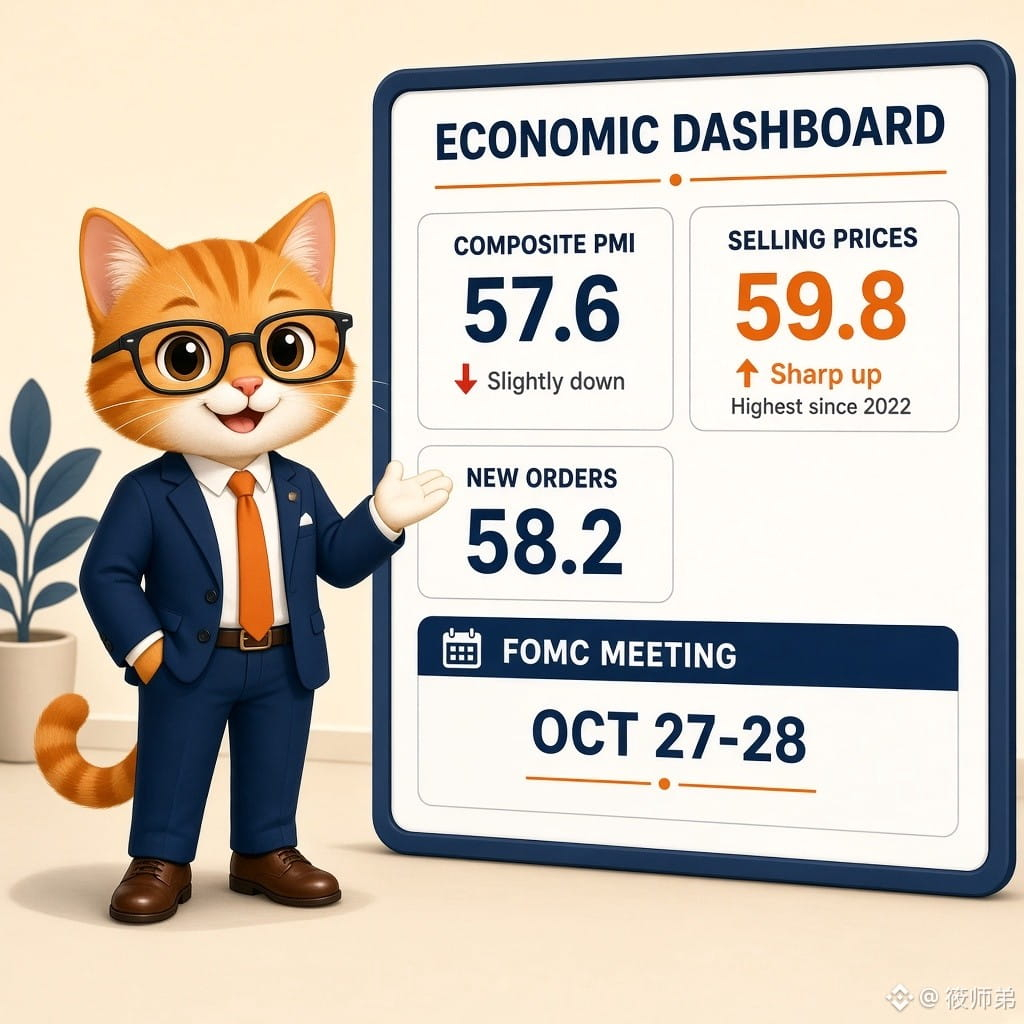
U.S. October Flash PMI: Factory Price Growth Fastest in 4 Years, Making Fed Easing Next Week Harder
S&P Global released its preliminary October U.S. composite PMI on Friday, at 57.6, down from September’s 58.4—a five-year high—but still in expansion territory. New orders rose to 58.2, their highest level since March 2022. The output price index hit 59.8, marking the fastest rate of increase since August 2022. The supplier delivery times index fell to 38.1, its weakest reading in more than four years. Manufacturing employment rose at its fastest pace since March 2012. (Reuters/S&P Global)
【View】
Growth hasn’t buckled, and pricing power is returning—a hawkish signal ahead of next week’s FOMC meeting. The economy remains hot, and amid the oil price shock, businesses are passing costs on to customers. Markets are currently betting the Fed will hold rates steady this week, with the probability of a December rate hike at around 80%. This PMI report, with prices rising while activity holds up, looks more likely to fuel the case for a December hike.
【Opportunities/Risks】
Watch closely for whether Wednesday’s FOMC statement and press conference emphasize sticky inflation. If the Fed signals a December hike, risk assets could come under pressure, and $BTC will need to hold the ETF cost-basis zone around $80,000–$81,500. If the Fed plays down the prospect of a hike, there may be a short-term window for a rebound. Also keep an eye on next week’s preliminary GDP reading and the earnings reports of hyperscale cloud providers for their impact on the AI spending narrative.
Do you think this PMI report, with prices rising while activity holds up, will make the Fed more willing to hike rates in December, or will it be constrained by political considerations ahead of the election?
#宏观经济 #美联储 #PMI $BTC $ETH
For reference only; this does not constitute investment advice.
248

S&P Global released preliminary US Purchasing Managers’ Index (PMI) data for October today. The preliminary US manufacturing PMI came in at 56, significantly above the market forecast of 55.5 and the previous reading of 55.9, reaching its highest level in nearly 53 months. The preliminary services PMI came in at 57.9, slightly below the forecast of 58.0 and the previous reading of 58.8, while the composite PMI remained firmly in expansion territory at 57.6.
The sharp rebound in manufacturing activity reflects the continued resilience of the US real economy, but also reinforces expectations that inflation will remain sticky. With concerns about inflation still lingering, stronger-than-expected output data has directly weakened bets on a rapid shift toward accommodative monetary policy, putting rate-cut trades to a severe repricing test.
As a result, risk appetite in traditional financial markets came under clear pressure. The S&P 500 and Nasdaq both fell to nearly five-week lows, down 0.4% and 0.2%, respectively, on the day. Meanwhile, supported by economic resilience, the dollar index and US Treasury yields remained elevated, continuing to weigh on the valuations of risk assets.
For crypto markets, a meaningful easing of macro liquidity conditions appears unlikely in the short term, dampening investors’ appetite for high-volatility assets. If an overheated economy prompts central banks to maintain a hawkish stance, $BTC could face valuation pressure from tighter liquidity. Investors should remain highly cautious and guard against the risk of a second bottom.📉
#PMI #USMarket #MacroEconomics
29

S&P Global officially released the preliminary US October PMI data today. The data showed that the preliminary US October Manufacturing PMI came in at 56.0, not only exceeding the market forecast of 55.5 and the previous reading of 55.9, but also reaching its highest level in nearly 53 months. The preliminary Composite PMI came in at 57.6, also above the forecast of 57.4, while the preliminary Services PMI came in at 57.9.
Manufacturing data showed strong, better-than-expected expansion, dispelling earlier market concerns that economic momentum was beginning to slow. Driven by the manufacturing index's sharp rebound to 56.0, the broader macroeconomic fundamentals demonstrated remarkable resilience, clearing away technical concerns about a hard landing.
Strong real-economy data are providing a solid floor of support for risk assets. Although the broader US equity market has seen a mild technical pullback recently, the Philadelphia Semiconductor Index stabilized and rebounded 0.5% intraday, indicating that major bullish investors are actively buying at key support levels and that market risk appetite is gradually recovering.
For the crypto market, resilient fundamentals are creating a favorable liquidity environment for high-beta assets. With macroeconomic recession fears disproven, buying support for $BTC and major crypto assets in key support zones has strengthened significantly. They may be poised for a technical rebound as risk appetite recovers. 📈
#MacroData #PMI #CryptoMarket
112

·
--
S&P Global has just released its preliminary October U.S. PMI figures, offering a multifaceted view of the economy’s health. Most notably, the manufacturing PMI unexpectedly rose to 56, well above the forecast of 55.5 and reaching its highest level in 53 months. By contrast, the services PMI edged down to 57.9, bringing the composite PMI to 57.6.
The strong rebound in manufacturing suggests that new orders and industrial supply chains are recovering very positively. However, with all the indices holding firmly above the 50-point expansion threshold, concerns are also growing that inflation could return. The market has been forced to reassess the possibility that monetary policy will remain restrictive for longer than expected.
In response to the solid economic data, bond yields and the U.S. dollar held firm, putting direct pressure on the stock market. U.S. stock indices such as the S&P 500 and Nasdaq faced selling pressure and hit their lowest levels in five weeks. Large capital flows are showing a defensive tilt amid macroeconomic uncertainty.
In the crypto market, short-term caution could slow speculative flows into $BTC and other risky assets. However, the fact that the U.S. economy continues to grow rather than slip into recession remains a positive macroeconomic support for the market’s long-term structure.
#PMI #MacroEconomics #CryptoAnalysis
194

Tonight at 9:45 and 10:00, two data releases will decide how Bitcoin spends this weekend.
Here’s the counterintuitive part: whatever the data shows, it could hurt crypto. PMI beats expectations and consumer confidence rebounds → the economy is doing fine → a December rate hike is all but certain, and crypto takes a hit. Data comes in much worse than expected → recession fears return → risk assets get dumped, and crypto takes a hit too. Damned either way.
Traders are already positioning themselves: $BTC is stuck in the middle at 81,600. 80,000 is the line in the sand—lose it, and 72,000–75,000 is next. It’ll take a move above 82,900 to get out of the woods. Friday’s weekly candle close and thin weekend liquidity will only amplify the volatility.
The comments section is open: A) Buy the dip once tonight’s data is out; B) Get out first and wait for the dust to settle.
#PMI #美联储 #Bitcoin
$BTC $ETH $SOL
65
S&P Global released its flash Purchasing Managers’ Index (PMI) data for France for October today. The data showed that France’s flash manufacturing PMI fell sharply to 49.3, well below the 50-point threshold between expansion and contraction, and far below the market expectation of 50.5 and the previous reading of 50.6. The services PMI also plunged from 51.2 to 48.4, pulling the flash composite PMI down to just 48.4.
As the eurozone’s second-largest economy, France saw all its key PMIs fall into contraction territory. This sharp deterioration significantly undermines the market’s previous, cautiously optimistic expectations that the European economy would stabilize and recover. The signal clearly indicates that, under the combined pressure of tight monetary policy and weak external demand, the risk of a deteriorating economic outlook in Europe’s core economies is accelerating, and speculation over further rate cuts by the European Central Bank is likely to intensify once again.
In macro-financial markets, the euro fell against the U.S. dollar shortly after the data was released, breaking below the 1.12 level and declining 0.12% on the day. The accelerating loss of economic momentum could put further downward pressure on European bond yields, while highlighting the relative safe-haven resilience of U.S. dollar assets amid macroeconomic headwinds. Global foreign exchange and sovereign bond markets are facing a fresh repricing of expectations.
For crypto markets, the widespread weakness in European economic data has further heightened concerns about a global growth slowdown. With both liquidity and fundamentals under pressure, investor risk appetite is clearly subdued. Investors are more inclined to stay on the sidelines or shift back into higher-certainty assets. Risk assets such as BTC may face sustained liquidity constraints and further volatility tests in the near term.
#MacroEconomics #PMI #Europe #CryptoLiquidity
71
·
--
S&P Global’s September services PMI report, released today, came in at 58.8, up from 58.7 the previous month. Overall business activity in the US is accelerating to its highest level in more than five years, keeping the composite PMI at a solid 58.4.
Improving economic data has reinforced forecasts that US GDP growth could reach 4% in the third quarter, led by a boom in the technology and AI sectors. However, the risk of the economy overheating is returning as input cost inflation climbs to a four-year high, adding further pressure to the Fed’s efforts to contain inflation.
This rapid growth is fueling concerns in financial markets that monetary policy will remain tighter for longer. US Treasury yields and the US Dollar Index remain under significant upward pressure, lowering expectations for policy easing in the near term.
In crypto markets, short-term caution could intensify as concerns about persistent inflation draw capital toward traditional safe-haven assets. However, the expanding technology infrastructure and AI boom remains a medium-term catalyst supporting related narratives in the market. $BTC
#PMI #USData #MacroEconomy
389

·
--
【BTC faces 4 more macroeconomic tests this week? The Fed is key 🔥】
[🔥 宏观消息面解读进群聊](https://app.binance.com/uni-qr/MwYFhLo4)
Bitcoin has just bounced, but this week brings another wave of macroeconomic data.
And this time, the most important thing isn’t whether any single data point looks good or bad—it’s whether the Fed will continue signaling rate hikes.
There are 4 key things to watch this week:
First, the U.S. services PMI.
If the services sector remains strong, it would suggest the economy is still resilient, and markets may once again worry that interest rates will stay high.
Second, the Fed meeting minutes.
This is the most important item this week. Markets want to know how hawkish Fed officials were after the last rate hike, and whether they’ll raise rates again this year.
Third, U.S. initial jobless claims.
Last week, nonfarm payrolls added just 29,000 jobs, well below expectations. Markets are now watching to see whether the labor market is really starting to cool.
Fourth, U.S. consumer confidence.
This data has a relatively smaller impact, but a sharp deterioration in consumer confidence could also prompt markets to reassess the state of the U.S. economy.
Put simply, BTC is facing one central question right now:
Is the U.S. economy actually “cooling,” or is it just slowing temporarily?
If the economy cools and employment continues to weaken, markets may lower their expectations for further rate hikes—which could actually be good for BTC.
But if the economy and inflation remain resilient and the Fed stays hawkish, the dollar and Treasury yields could put pressure on risk assets again.
📌 So what really matters this week isn’t just whether BTC goes up or down. It’s whether the services sector, employment data, and Fed meeting minutes further shift market expectations for the next interest rate decision.
#美联储10月加息概率降至17% #PMI
【BTC faces 4 more macroeconomic tests this week? The Fed is key 🔥】
🔥 宏观消息面解读进群聊
Bitcoin has just bounced, but this week brings another wave of macroeconomic data.
And this time, the most important thing isn’t whether any single data point looks good or bad—it’s whether the Fed will continue signaling rate hikes.
There are 4 key things to watch this week:
First, the U.S. services PMI.
If the services sector remains strong, it would suggest the economy is still resilient, and markets may once again worry that interest rates will stay high.
Second, the Fed meeting minutes.
This is the most important item this week. Markets want to know how hawkish Fed officials were after the last rate hike, and whether they’ll raise rates again this year.
Third, U.S. initial jobless claims.
Last week, nonfarm payrolls added just 29,000 jobs, well below expectations. Markets are now watching to see whether the labor market is really starting to cool.
Fourth, U.S. consumer confidence.
This data has a relatively smaller impact, but a sharp deterioration in consumer confidence could also prompt markets to reassess the state of the U.S. economy.
Put simply, BTC is facing one central question right now:
Is the U.S. economy actually “cooling,” or is it just slowing temporarily?
If the economy cools and employment continues to weaken, markets may lower their expectations for further rate hikes—which could actually be good for BTC.
But if the economy and inflation remain resilient and the Fed stays hawkish, the dollar and Treasury yields could put pressure on risk assets again.
📌 So what really matters this week isn’t just whether BTC goes up or down. It’s whether the services sector, employment data, and Fed meeting minutes further shift market expectations for the next interest rate decision.
#美联储10月加息概率降至17% #PMI
394
·
--
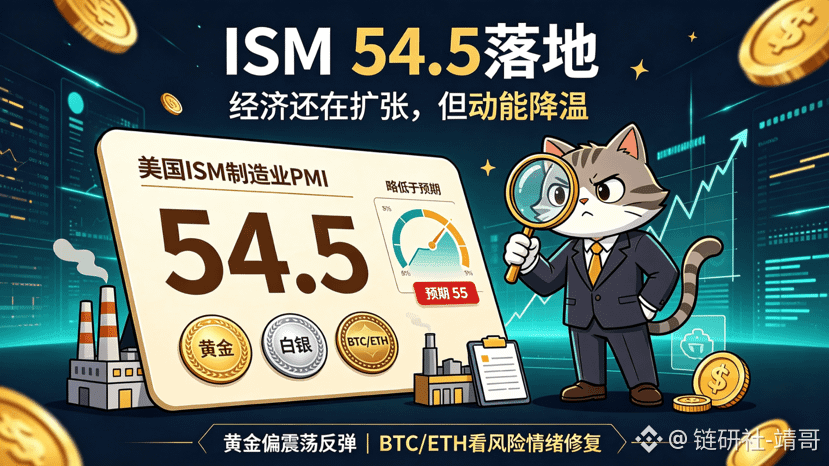
🔥 US ISM Manufacturing PMI comes in! One article to understand the logic behind gold, silver, + BTC/ETH market moves!
Key data: September ISM Manufacturing PMI 54.5, below expectations of 55; prior reading was 54.6. It still holds above the 50 line dividing expansion and contraction.
One-sentence takeaway: Economic resilience is still there, but the expansion momentum is cooling off—this is a neutral-to-slightly bullish signal, “not bad, but not strong.”
✨ Gold & Silver
The data came in below expectations. Market expectations for the Fed to keep interest rates high eased slightly. Treasury yields saw downward pressure, giving gold and silver a chance for a short-term rebound.
👉 Strategy: Gold—try a small long position near support; take profit in batches at overhead resistance levels. Silver—higher sensitivity means stronger volatility; control position size strictly.
⚠️ Note: The data did not break below the expansion/contraction line, so it’s not a major bullish signal for a recession scenario. This rebound is more like a range-bound market—don’t chase higher prices!
✨ BTC & ETH
Crypto assets are risk assets. This data suggests the US economy is not facing a “hard landing” risk, so it won’t trigger panic-style crashes. However, it’s also not strong enough to ignite a full-blown bull run. Most likely, prices will continue to trade in a range.
👉 Strategy: Don’t chase upside with heavy size. You can continue holding BTC/ETH positions; reduce exposure in batches near higher levels. If you’re on the sidelines, wait for a pullback to key support before considering a low entry. Focus on upcoming catalysts like the Non-Farm Payrolls and PCE inflation data.
💡 Summary: This report is just a warm-up; the main event is still ahead—Non-Farm Payrolls + PCE. The current market is mostly range-bound. Don’t go all-in, and keep leverage light.
Do you think gold will surge first tonight, or pull back first? Let’s discuss in the comments!
⚠️ Risk warning: Viewpoints are for market analysis only and do not constitute any investment advice. Leverage trading carries extremely high risk. #ISM #PMI $BTC $ETH $XAU
{future}(XAUUSDT)
{future}(ETHUSDT)
{future}(BTCUSDT)
🔥 US ISM Manufacturing PMI comes in! One article to understand the logic behind gold, silver, + BTC/ETH market moves!
Key data: September ISM Manufacturing PMI 54.5, below expectations of 55; prior reading was 54.6. It still holds above the 50 line dividing expansion and contraction.
One-sentence takeaway: Economic resilience is still there, but the expansion momentum is cooling off—this is a neutral-to-slightly bullish signal, “not bad, but not strong.”
✨ Gold & Silver
The data came in below expectations. Market expectations for the Fed to keep interest rates high eased slightly. Treasury yields saw downward pressure, giving gold and silver a chance for a short-term rebound.
👉 Strategy: Gold—try a small long position near support; take profit in batches at overhead resistance levels. Silver—higher sensitivity means stronger volatility; control position size strictly.
⚠️ Note: The data did not break below the expansion/contraction line, so it’s not a major bullish signal for a recession scenario. This rebound is more like a range-bound market—don’t chase higher prices!
✨ BTC & ETH
Crypto assets are risk assets. This data suggests the US economy is not facing a “hard landing” risk, so it won’t trigger panic-style crashes. However, it’s also not strong enough to ignite a full-blown bull run. Most likely, prices will continue to trade in a range.
👉 Strategy: Don’t chase upside with heavy size. You can continue holding BTC/ETH positions; reduce exposure in batches near higher levels. If you’re on the sidelines, wait for a pullback to key support before considering a low entry. Focus on upcoming catalysts like the Non-Farm Payrolls and PCE inflation data.
💡 Summary: This report is just a warm-up; the main event is still ahead—Non-Farm Payrolls + PCE. The current market is mostly range-bound. Don’t go all-in, and keep leverage light.
Do you think gold will surge first tonight, or pull back first? Let’s discuss in the comments!
⚠️ Risk warning: Viewpoints are for market analysis only and do not constitute any investment advice. Leverage trading carries extremely high risk. #ISM #PMI $BTC $ETH $XAU
499
·
--
The US ISM Manufacturing PMI index reached 54.5 versus the expected 54.8.
The US economy is still in an expansion phase.
#PMI
The US ISM Manufacturing PMI index reached 54.5 versus the expected 54.8.
The US economy is still in an expansion phase.
#PMI
The US economy is still in an expansion phase.
#PMI
111
S&P Global’s latest release shows the final value of the U.S. manufacturing purchasing managers’ index (PMI) for September. The data indicates that the indicator ultimately came in at 55.9, which is not only below the prior reading of 57, but also reflects signs of a marginal slowdown in the expansion momentum of U.S. manufacturing.
Although the data remains in the expansion zone above the 50 break-even line, the sharp drop in the pace of expansion cannot be ignored. Against the backdrop of the Federal Reserve’s recent return to a tighter policy path, the cost and interest-rate pressures faced by real manufacturing are beginning to show up, and market assessments of economic growth resilience may need to be recalibrated.
The macro-financial markets have reacted in a defensive manner. Signals of slower economic growth may weigh on the U.S. dollar index in the near term, while fluctuations in the U.S. Treasury yield curve are in focus. If overall risk-off sentiment intensifies, it could also limit upside potential for commodities and traditional risk assets.
For the crypto market, weaker macro fundamentals are not simply a positive for rate cuts; they instead intensify concerns about stagflation during a period of liquidity contraction. In the absence of strong incremental capital inflows, core assets such as $BTC may face greater near-term volatility and adjustment pressure. Investors should be alert to downside risks stemming from a decline in sentiment.📉
#MacroEconomics #PMI #CryptoMarket
104
·
--
Wow, China’s manufacturing PMI is back above 50, and Asian stocks jump right at the open!
In September, the official manufacturing PMI hit 50.1, up from 49.8 in August—returning to the expansion zone for the first time since June. Beijing wasted no time with a “combo deal”: lowering financing costs and the central bank stepping up lending. At the open, Japan’s Nikkei surged 647 points to 66,128. TSMC touched 25,05 New Taiwan dollars. Philadelphia’s semiconductor stocks rose 1.3% overnight. Meanwhile, the Hang Seng index actually fell 0.53%, as money took profits before the National Day holiday.
This is a macro tailwind for the market: risk appetite is back. BTC was quoted at 83,430, up 0.57%, and funds behind Shan Sai’s institutional targets are rotating next. Goldman Sachs put it plainly: this looks more like a policy signal than an immediate, strong stimulus.
With China’s PMI back above the breakeven line, Asian buying keeps at it. Tonight, stay cautious before the U.S. PCE data lands.
#宏观 #PMI
$BTC $ETH
1
63
According to the latest official data, China’s September official manufacturing PMI came in at 50.1. It not only met market expectations, but also successfully crossed the breakeven line and returned to the expansion zone, up from the previous 49.8. Meanwhile, Australia reported that its August non-seasonally adjusted CPI year-on-year rose 4%, which was higher than the previous 3.5% but below the market expectation of 4.1%.
The manufacturing sector’s return to the expansion zone confirms that momentum in the real economy is bottoming out and picking up, providing solid support for global macro liquidity. Australia’s inflation data coming in below expectations has also effectively eased concerns among Asia-Pacific central banks about further tightening. Positive fundamentals are gradually building.
In the FX market, after the data release, AUD/USD saw a short-term drop of nearly 20 pips to around 0.6975 for technical consolidation. Overall, the significant repair in leading economic indicators has improved risk appetite markedly. After the bottoming structure is completed, non–USD currencies and commodities are expected to see a stronger upward moving-average alignment.
For the crypto market, the substantial improvement in macro fundamentals provides a healthy long setup for risk assets such as $BTC. As expectations for liquidity improve and panic sentiment fades, clear signs of capital returning have emerged. The certainty of launching a new upswing after breaking key resistance levels is continuing to strengthen.📊
#MacroEconomics #PMI #CryptoTrading
According to the latest official data, China’s September official manufacturing PMI came in at 50.1. It not only met market expectations, but also successfully crossed the breakeven line and returned to the expansion zone, up from the previous 49.8. Meanwhile, Australia reported that its August non-seasonally adjusted CPI year-on-year rose 4%, which was higher than the previous 3.5% but below the market expectation of 4.1%.
The manufacturing sector’s return to the expansion zone confirms that momentum in the real economy is bottoming out and picking up, providing solid support for global macro liquidity. Australia’s inflation data coming in below expectations has also effectively eased concerns among Asia-Pacific central banks about further tightening. Positive fundamentals are gradually building.
In the FX market, after the data release, AUD/USD saw a short-term drop of nearly 20 pips to around 0.6975 for technical consolidation. Overall, the significant repair in leading economic indicators has improved risk appetite markedly. After the bottoming structure is completed, non–USD currencies and commodities are expected to see a stronger upward moving-average alignment.
For the crypto market, the substantial improvement in macro fundamentals provides a healthy long setup for risk assets such as $BTC . As expectations for liquidity improve and panic sentiment fades, clear signs of capital returning have emerged. The certainty of launching a new upswing after breaking key resistance levels is continuing to strengthen.📊
#MacroEconomics #PMI #CryptoTrading
113
·
--
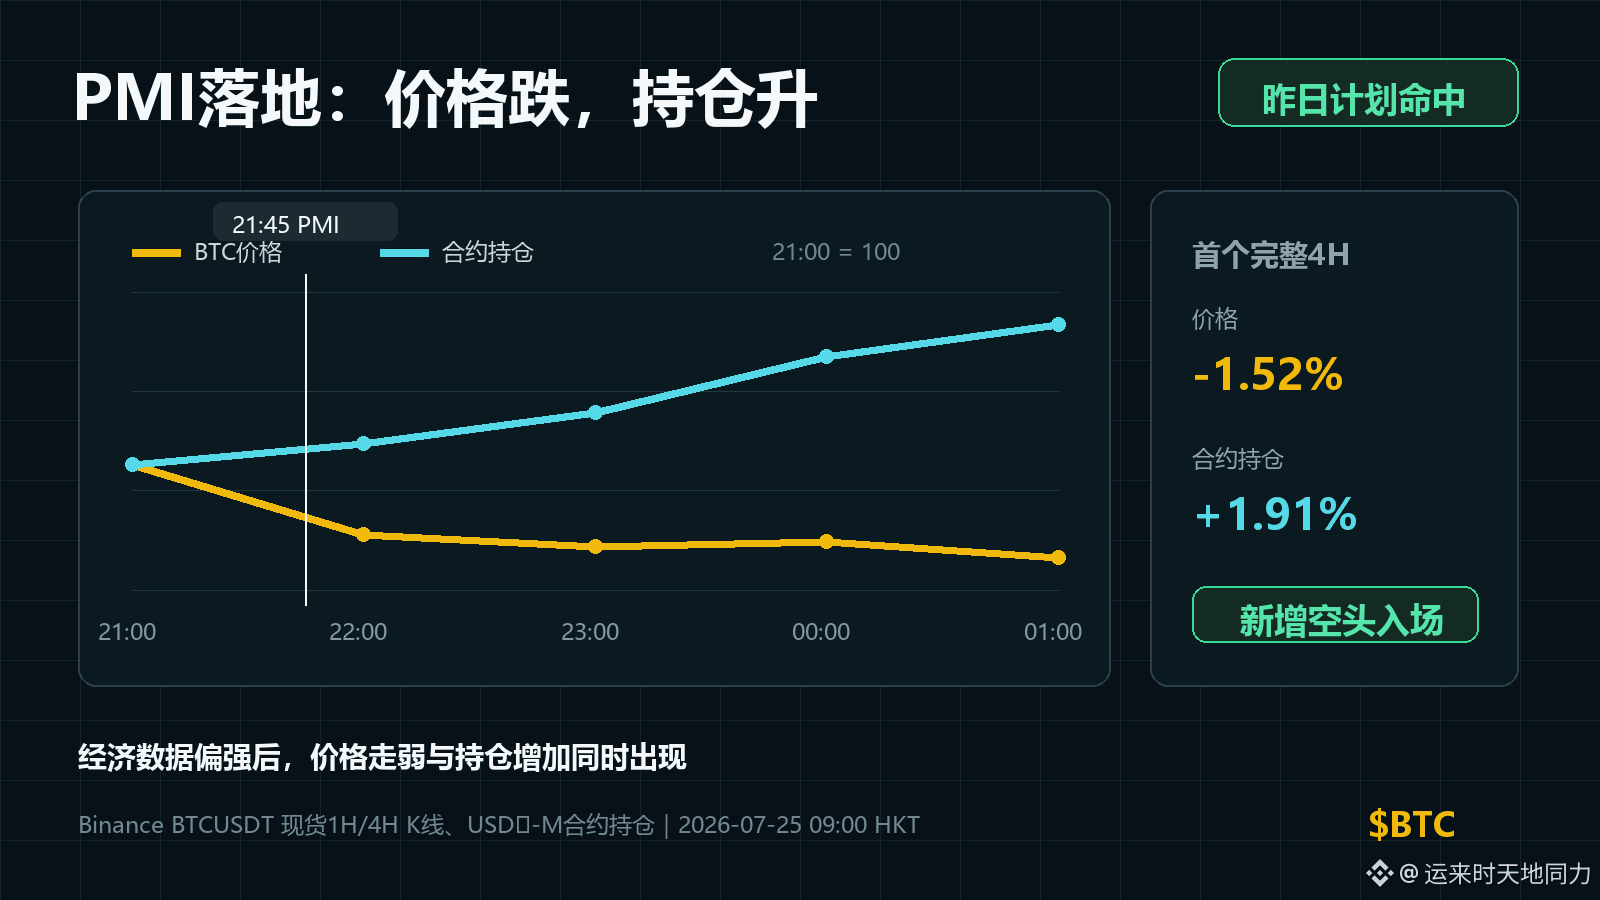
$BTC Last night after the PMI was released, prices fell and open interest rose; the bearish branch I planned yesterday hit. Yesterday at 21:45 I was waiting for the U.S. July PMI: the composite index rose from 51.9 to 53.6, meaning economic activity was stronger than last month, and companies’ rate of price increases is also accelerating.
In the first full 4H after the news landed, BTC fell from 65,083 to 64,094, while contract open interest actually increased by 1.91%. This suggests that during the decline, someone actively opened short positions—it's not only long holders passively exiting. Therefore, the conditions I set yesterday were confirmed.
After that, price did not show any clear rebound, and open interest did not decrease. Next, we’ll see whether the new shorts continue to stay open: if the price stops falling and open interest drops, it means shorts take profit and exit; if the price keeps weakening and open interest rises again, it means actively opening shorts is still increasing.
#BTC #交易复盘 #PMI
173
·
--
Newly released US production data is sending fairly mixed signals.
Specifically, the ISM Manufacturing PMI index reached 55.6 points, beating expectations quite clearly versus the forecast of 53.9 (the previous period was 53.3), indicating that factory activity is growing more strongly than expected. In contrast, S&P Global’s Manufacturing PMI index was flat at 53.9 points, reflecting that this sector is still maintaining a steady pace.
#Economy #US #PMI $USD $BTC
$NEAR
112
·
--
The newly released U.S. manufacturing data is sending some fairly mixed signals.
Specifically, the ISM Manufacturing PMI index reached 55.6 points, beating expectations quite clearly versus the forecast of 53.9 (the prior period was 53.3), indicating that factory activity is growing much more strongly than expected. By contrast, S&P Global’s Manufacturing PMI remained flat at 53.9 points, reflecting that this sector is still maintaining a stable pace.
#Economy #US #PMI $USD $BTC
$NEAR
129
·
--
Article
Macroeconomy Weekly Outlook Week of August 31 – September 6, 2026$BTC Macroeconomy Weekly Outlook☕️
Weekly Bias: 🟩Bullish | Strong bullish trend intact with ADX confirming strength. RSI cooling to 72 from 82, still overbought but healthy pullback. TD Sequential at 3 Down suggests the correction may be nearing exhaustion. Key catalysts this week: China PMI, ISM Manufacturing, JOLTS, ADP, Jobless Claims, and the mother of all data – NFP on Friday.
Monday, 31 Aug: 🟩 Green. China Manufacturing PMI forecast at 49.5 from 49.2 previous, a slight recovery. China Non-Manufacturing PMI at 49.5 from 49.0 previous. Chicago PMI at 13:45 UTC forecast at 57.8 from 57.6 previous, a slight beat. Japanese Capital Spending at 23:50 UTC forecast at -0.2% from 0.0% previous.
Monday is a data-light session with China data as the headline catalyst. China Manufacturing PMI is expected to recover slightly from 49.2 to 49.5, still in contraction but improving. This is a mild bullish signal for global growth. Chicago PMI is expected to beat slightly at 57.8 from 57.6, a green signal that could strengthen the DXY. However, the market is still digesting the Jackson Hole rhetoric, which leans dovish. Teacher expects green on Monday with Blackrock buying. The structural bull case remains intact.
Prediction: Bitcoin volatile with price range $77,500~$79,500
Direction: 🟩Bullish
Tuesday, 1 Sep: 🟨 Sideways. China RatingDog Manufacturing PMI at 01:45 UTC forecast at 51.5 from 50.9 previous, a beat. S&P Global Manufacturing PMI at 13:45 UTC forecast at 53.2 from 53.2 previous, flat. ISM Manufacturing PMI at 14:00 UTC forecast at 55.2 from 55.6 previous, a slight drop. ISM Manufacturing Prices at 71.2 from 71.1 previous, flat. JOLTS Job Openings at 14:00 UTC forecast at 7.330M from 7.359M previous, a drop. Fed Vice Chair Barr speaks at 13:05 UTC.
Tuesday is packed with manufacturing and labour data. ISM Manufacturing is expected to drop from 55.6 to 55.2, a dovish cooling signal that weakens the DXY and supports Bitcoin. JOLTS is expected to drop from 7.359M to 7.330M, another dovish labour signal. S&P Global PMI is flat at 53.2. The data leans dovish overall. However, Barr speaking is a wildcard. Teacher predicts Bitcoin will be sideways with Blackrock selling into strength. Expect a range-bound session with a slight bullish skew.
Prediction: Bitcoin slow with price range $77,000~$79,000
Direction: 🟨Sideways
Wednesday, 2 Sep: 🟩 Green. ADP Nonfarm Employment Change at 12:15 UTC forecast at 47K from 44K previous, a slight recovery. Factory Orders at 14:00 UTC forecast at 0.6% from -0.3% previous, a significant recovery. Crude Oil Inventories at 14:30 UTC forecast at 0.095M from 0.095M previous, flat. Beige Book at 18:00 UTC.
Wednesday is ADP and Factory Orders day. ADP is expected to recover from 44K to 47K, a green signal that strengthens the DXY and pressures Bitcoin. Factory Orders are expected to recover sharply from -0.3% to 0.6%, another green signal. Crude Oil Inventories are flat at 0.095M. The data leans green, which should pressure Bitcoin. However, Teacher predicts Bitcoin will be green on Wednesday, arguing that the ADP number is still "hina" (low) and not enough to give the Fed room to be hawkish. The Beige Book will likely confirm slowing growth. Expect a green day with a potential pump towards 80k.
Prediction: Bitcoin volatile with price range $77,500~$80,000
Direction: 🟩Bullish
Thursday, 3 Sep: 🟥 Red. Japanese Services PMI at 00:30 UTC forecast at 52.3 from 52.3 previous, flat. Initial Jobless Claims at 12:30 UTC forecast at 205K from 203K previous, a rise. Continuing Claims at 1,778K from 1,778K previous, flat. Trade Balance at 12:30 UTC forecast at -86.40B from -73.30B previous, a widening deficit. ISM Non-Manufacturing PMI at 14:00 UTC forecast at 54.1 from 54.1 previous, flat. ISM Non-Manufacturing Prices at 70.3 from 70.3 previous, flat. Fed Walker speaks at 14:00 UTC. Atlanta Fed GDPNow at 4.0% from 4.3% previous, a drop.
Thursday is Jobless Claims and ISM Services day. Initial Jobless Claims are expected to rise from 203K to 205K, a dovish labour signal that should weaken the DXY and support Bitcoin. However, ISM Non-Manufacturing PMI is flat at 54.1, neutral. Trade Balance widening to -86.40B from -73.30B is a structural dollar negative. The data leans dovish, but Teacher predicts Bitcoin will be red on Thursday with Blackrock selling. Expect a pullback towards 77k.
Prediction: Bitcoin volatile with price range $76,500~$78,500
Direction: 🟥Bearish
Friday, 4 Sep: 🟩🟥 Volatile. NFP Day. Nonfarm Payrolls at 12:30 UTC forecast at 58K from -23K previous, a recovery. Average Hourly Earnings forecast at 0.3% from 0.1% previous, a rise. Unemployment Rate forecast at 4.1% from 4.1% previous, flat. Private Nonfarm Payrolls at 50K from 30K previous. Participation Rate at 61.4%.
Friday is the absolute king of the week. NFP is expected to recover from -23K to 58K, a significant improvement but still historically weak. Average Hourly Earnings are expected to rise from 0.1% to 0.3%, a green signal that could cap the upside. Unemployment rate flat at 4.1%. The data is mixed but leans dovish overall. Teacher predicts Bitcoin will be green on Friday with Blackrock buying big. However, Friday is always a pump and dump day. The weekend war premium and profit-taking will trigger a dump after the initial spike. Expect a pump towards 81k, followed by a dump towards 79k.
Prediction: Bitcoin volatile with price range $78,000~$81,500
Direction: 🟩Bullish then 🟥Bearish (Pump and Dump)
Saturday, September 5
Analysis: Weekend. No data. Markets closed. Geopolitical headlines (War Premium) may emerge. It is advisable to not trade on weekend, rest well and have fun with family and friends.
Prediction: Bitcoin slow with range $78,000~$79,500 because no data/holiday/no institution movement.
Direction: 🟨Sideways☕️
Sunday, September 6
Analysis: OPEC Meeting at 10:00 UTC. Potential oil supply decision. Geopolitical headlines (War Premium) may emerge. It is advisable to not trade on weekend, rest well and have fun with family and friends.
Prediction: Bitcoin slow with range $78,000~$79,500 because no institution movement. OPEC meeting is a wildcard.
Direction: 🟨Sideways☕️
Bias: The structural bull case remains intact. NFP is expected to recover from -23K to 58K, but this is still historically weak and does not give the Fed room to be hawkish. The Treasury buyback narrative, yen weakness, and Jackson Hole dovish rhetoric continue to provide a tailwind. The pullback to 77.7k is healthy and likely finished. The next leg higher towards 82k is expected, driven by NFP weakness and Blackrock inflows. Risk management is key. Weekend war risks remain the wildcard.
#NFA #DYOR 🔥
Not a futures signal🛑
$ETH $BNB #PMI #jolts #ISM #ADP #NFP
Macroeconomy Weekly Outlook Week of August 31 – September 6, 2026
$BTC Macroeconomy Weekly Outlook☕️
Weekly Bias: 🟩Bullish | Strong bullish trend intact with ADX confirming strength. RSI cooling to 72 from 82, still overbought but healthy pullback. TD Sequential at 3 Down suggests the correction may be nearing exhaustion. Key catalysts this week: China PMI, ISM Manufacturing, JOLTS, ADP, Jobless Claims, and the mother of all data – NFP on Friday.
Monday, 31 Aug: 🟩 Green. China Manufacturing PMI forecast at 49.5 from 49.2 previous, a slight recovery. China Non-Manufacturing PMI at 49.5 from 49.0 previous. Chicago PMI at 13:45 UTC forecast at 57.8 from 57.6 previous, a slight beat. Japanese Capital Spending at 23:50 UTC forecast at -0.2% from 0.0% previous.
Monday is a data-light session with China data as the headline catalyst. China Manufacturing PMI is expected to recover slightly from 49.2 to 49.5, still in contraction but improving. This is a mild bullish signal for global growth. Chicago PMI is expected to beat slightly at 57.8 from 57.6, a green signal that could strengthen the DXY. However, the market is still digesting the Jackson Hole rhetoric, which leans dovish. Teacher expects green on Monday with Blackrock buying. The structural bull case remains intact.
Prediction: Bitcoin volatile with price range $77,500~$79,500
Direction: 🟩Bullish
Tuesday, 1 Sep: 🟨 Sideways. China RatingDog Manufacturing PMI at 01:45 UTC forecast at 51.5 from 50.9 previous, a beat. S&P Global Manufacturing PMI at 13:45 UTC forecast at 53.2 from 53.2 previous, flat. ISM Manufacturing PMI at 14:00 UTC forecast at 55.2 from 55.6 previous, a slight drop. ISM Manufacturing Prices at 71.2 from 71.1 previous, flat. JOLTS Job Openings at 14:00 UTC forecast at 7.330M from 7.359M previous, a drop. Fed Vice Chair Barr speaks at 13:05 UTC.
Tuesday is packed with manufacturing and labour data. ISM Manufacturing is expected to drop from 55.6 to 55.2, a dovish cooling signal that weakens the DXY and supports Bitcoin. JOLTS is expected to drop from 7.359M to 7.330M, another dovish labour signal. S&P Global PMI is flat at 53.2. The data leans dovish overall. However, Barr speaking is a wildcard. Teacher predicts Bitcoin will be sideways with Blackrock selling into strength. Expect a range-bound session with a slight bullish skew.
Prediction: Bitcoin slow with price range $77,000~$79,000
Direction: 🟨Sideways
Wednesday, 2 Sep: 🟩 Green. ADP Nonfarm Employment Change at 12:15 UTC forecast at 47K from 44K previous, a slight recovery. Factory Orders at 14:00 UTC forecast at 0.6% from -0.3% previous, a significant recovery. Crude Oil Inventories at 14:30 UTC forecast at 0.095M from 0.095M previous, flat. Beige Book at 18:00 UTC.
Wednesday is ADP and Factory Orders day. ADP is expected to recover from 44K to 47K, a green signal that strengthens the DXY and pressures Bitcoin. Factory Orders are expected to recover sharply from -0.3% to 0.6%, another green signal. Crude Oil Inventories are flat at 0.095M. The data leans green, which should pressure Bitcoin. However, Teacher predicts Bitcoin will be green on Wednesday, arguing that the ADP number is still "hina" (low) and not enough to give the Fed room to be hawkish. The Beige Book will likely confirm slowing growth. Expect a green day with a potential pump towards 80k.
Prediction: Bitcoin volatile with price range $77,500~$80,000
Direction: 🟩Bullish
Thursday, 3 Sep: 🟥 Red. Japanese Services PMI at 00:30 UTC forecast at 52.3 from 52.3 previous, flat. Initial Jobless Claims at 12:30 UTC forecast at 205K from 203K previous, a rise. Continuing Claims at 1,778K from 1,778K previous, flat. Trade Balance at 12:30 UTC forecast at -86.40B from -73.30B previous, a widening deficit. ISM Non-Manufacturing PMI at 14:00 UTC forecast at 54.1 from 54.1 previous, flat. ISM Non-Manufacturing Prices at 70.3 from 70.3 previous, flat. Fed Walker speaks at 14:00 UTC. Atlanta Fed GDPNow at 4.0% from 4.3% previous, a drop.
Thursday is Jobless Claims and ISM Services day. Initial Jobless Claims are expected to rise from 203K to 205K, a dovish labour signal that should weaken the DXY and support Bitcoin. However, ISM Non-Manufacturing PMI is flat at 54.1, neutral. Trade Balance widening to -86.40B from -73.30B is a structural dollar negative. The data leans dovish, but Teacher predicts Bitcoin will be red on Thursday with Blackrock selling. Expect a pullback towards 77k.
Prediction: Bitcoin volatile with price range $76,500~$78,500
Direction: 🟥Bearish
Friday, 4 Sep: 🟩🟥 Volatile. NFP Day. Nonfarm Payrolls at 12:30 UTC forecast at 58K from -23K previous, a recovery. Average Hourly Earnings forecast at 0.3% from 0.1% previous, a rise. Unemployment Rate forecast at 4.1% from 4.1% previous, flat. Private Nonfarm Payrolls at 50K from 30K previous. Participation Rate at 61.4%.
Friday is the absolute king of the week. NFP is expected to recover from -23K to 58K, a significant improvement but still historically weak. Average Hourly Earnings are expected to rise from 0.1% to 0.3%, a green signal that could cap the upside. Unemployment rate flat at 4.1%. The data is mixed but leans dovish overall. Teacher predicts Bitcoin will be green on Friday with Blackrock buying big. However, Friday is always a pump and dump day. The weekend war premium and profit-taking will trigger a dump after the initial spike. Expect a pump towards 81k, followed by a dump towards 79k.
Prediction: Bitcoin volatile with price range $78,000~$81,500
Direction: 🟩Bullish then 🟥Bearish (Pump and Dump)
Saturday, September 5
Analysis: Weekend. No data. Markets closed. Geopolitical headlines (War Premium) may emerge. It is advisable to not trade on weekend, rest well and have fun with family and friends.
Prediction: Bitcoin slow with range $78,000~$79,500 because no data/holiday/no institution movement.
Direction: 🟨Sideways☕️
Sunday, September 6
Analysis: OPEC Meeting at 10:00 UTC. Potential oil supply decision. Geopolitical headlines (War Premium) may emerge. It is advisable to not trade on weekend, rest well and have fun with family and friends.
Prediction: Bitcoin slow with range $78,000~$79,500 because no institution movement. OPEC meeting is a wildcard.
Direction: 🟨Sideways☕️
Bias: The structural bull case remains intact. NFP is expected to recover from -23K to 58K, but this is still historically weak and does not give the Fed room to be hawkish. The Treasury buyback narrative, yen weakness, and Jackson Hole dovish rhetoric continue to provide a tailwind. The pullback to 77.7k is healthy and likely finished. The next leg higher towards 82k is expected, driven by NFP weakness and Blackrock inflows. Risk management is key. Weekend war risks remain the wildcard.
#NFA #DYOR 🔥
Not a futures signal🛑
$ETH $BNB #PMI #jolts #ISM #ADP #NFP
1
134
Tim Moore, Global Economics Director at S&P Global, disclosed in the latest UK August Purchasing Managers’ Index (PMI) report that the final UK services PMI reading rebounded from 52.1 in July to 52.5 in August, the highest pace of growth since April this year. With the services sector—the main pillar of the UK economy—recording expansion for the second month in a row, business and consumer spending has shown a degree of resilience after an earlier pullback. However, this final reading is slightly below the market consensus of 52.8. More importantly, the report clearly noted a significant increase in the number of companies reporting rising costs, with signs that inflation pressure is starting to build.
From a macro perspective, this seemingly moderate expansion masks risks of stagflation. As a key source of core inflation, the services sector’s renewed rise in cost and price pressures directly undermines the optimistic narrative in the market that inflation will fall steadily. For the Bank of England, given stubborn cost-side pressures, any premature or overly aggressive rate-cutting move could trigger a second round of inflation. This data not only dispels fantasies of a rapid pivot to easing, but further reinforces the policy logic that interest rates will remain at a high level for longer.
In traditional financial markets, persistent cost pressure combined with sticky inflation will provide upward support to UK government bond yields, delaying the normalisation of the yield curve. Although the pound may receive a temporary boost as rate-cut expectations cool, this resilience—driven by cost pressure rather than productivity gains—will in reality erode companies’ forward profit margins, thereby exerting an implicit drag on valuations of risk assets such as equities. As a result, global capital markets’ risk appetite faces further contraction.
For the crypto asset market, with major overseas central banks being constrained by sticky inflation and postponing the release of liquidity, the macro liquidity environment is unlikely to provide incremental momentum in the near term. Under the double squeeze of persistently high real interest rates and uncertainty in the geopolitical situation, risk assets represented by bitcoin are likely to remain in a defensive period characterised by limited liquidity. Investors should be highly alert to the risk of asset price pullbacks when rate-cut expectations repeatedly fail to materialise.
#英国经济 #PMI #Inflation
38
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BinancePick
3.2M views
157,454 Discussing
2
#EarningsSeason
5.4M views
26,254 Discussing
3
#BitmineAdds10452ETH
0 views
0 Discussing
4
#SouthKoreaConsidersEducationTaxOnCryptoExchanges
131 views
22 Discussing
5
#OCCUrgesCommunityBanksToEnterStablecoinPayments
56 views
13 Discussing
6
#RippleWinsFullApprovalAsNationalTrustBank
62 views
15 Discussing
7
#AkashSelectsSolanaAsMigrationTarget
0 views
0 Discussing
8
#OndoToOpenSubscriptionsForOpenAIPreIPOTokenizedNotes
5 views
3 Discussing
9
#AnthropicTTMRevenueGrewAbout1200%
42,780 views
506 Discussing
10
#AnthropicS1ExpectedToday
35,025 views
396 Discussing