

#earningseason
earningseason
3,482 views
19 Discussing
Hot
Latest
Verified
I’m skeptical of the AI bubble. Micron just gave me $54.23 billion in quarterly revenue to argue with.
MU beat expectations—and its next-quarter outlook gives the bulls more ammunition. 👀
Fiscal Q4 results:
• Revenue: $54.23B vs. $51.33B expected.
• Adjusted EPS: $33.42 vs. $31.72 expected.
• Adjusted gross margin: 87%.
Next quarter’s guidance midpoint:
• Revenue: $61.5B.
• Adjusted EPS: $38.15.
But the detail that caught my attention goes beyond the earnings beat.
Customer financial commitments under long-term supply agreements increased from $22B to $32B, mostly through cash deposits.
Customers putting money down carries more weight than another executive saying “AI changes everything.”
My position hasn’t changed: I don’t own MU. I passed below $200 last year because I didn’t understand the business well enough.
Today, I respect it much more. These results strengthen my conviction that Micron can keep growing, even while I question the returns on parts of the wider AI spending boom.
There’s still a catch: next quarter’s adjusted gross-margin guidance is 86.25%, slightly below this quarter’s 87%. Strong growth doesn’t make this business immune to pressure.
The report gives the bullish thesis more substance. It doesn’t make every entry price attractive.
Would you buy MU after this report—or wait for the price to offer you a better deal?
#EarningSeason #MicronPostsRecord84.9%GrossMargin
{spot}(MUBUSDT)
I’m skeptical of the AI bubble. Micron just gave me $54.23 billion in quarterly revenue to argue with.
MU beat expectations—and its next-quarter outlook gives the bulls more ammunition. 👀
Fiscal Q4 results:
• Revenue: $54.23B vs. $51.33B expected.
• Adjusted EPS: $33.42 vs. $31.72 expected.
• Adjusted gross margin: 87%.
Next quarter’s guidance midpoint:
• Revenue: $61.5B.
• Adjusted EPS: $38.15.
But the detail that caught my attention goes beyond the earnings beat.
Customer financial commitments under long-term supply agreements increased from $22B to $32B, mostly through cash deposits.
Customers putting money down carries more weight than another executive saying “AI changes everything.”
My position hasn’t changed: I don’t own MU. I passed below $200 last year because I didn’t understand the business well enough.
Today, I respect it much more. These results strengthen my conviction that Micron can keep growing, even while I question the returns on parts of the wider AI spending boom.
There’s still a catch: next quarter’s adjusted gross-margin guidance is 86.25%, slightly below this quarter’s 87%. Strong growth doesn’t make this business immune to pressure.
The report gives the bullish thesis more substance. It doesn’t make every entry price attractive.
Would you buy MU after this report—or wait for the price to offer you a better deal?
#EarningSeason #MicronPostsRecord84.9%GrossMargin
AngelOfCrypto_-:
nice
2
3
1.2k
·
--
🔥🔥 CRYPTO EARNING SEASON IS HERE! 💰
Binance users can explore different ways to earn through staking, savings, Launchpool and selected earning opportunities—but always check the current terms, APY and risks before joining. 🚀📈
💎 More opportunities
🎁 More rewards
⚡ More ways to put your crypto to work
Don’t just hold — learn, research & grow! 🟡🔥
#BinanceSquareTalks #Crypto_Jobs🎯 #EarningSeason
54
·
--
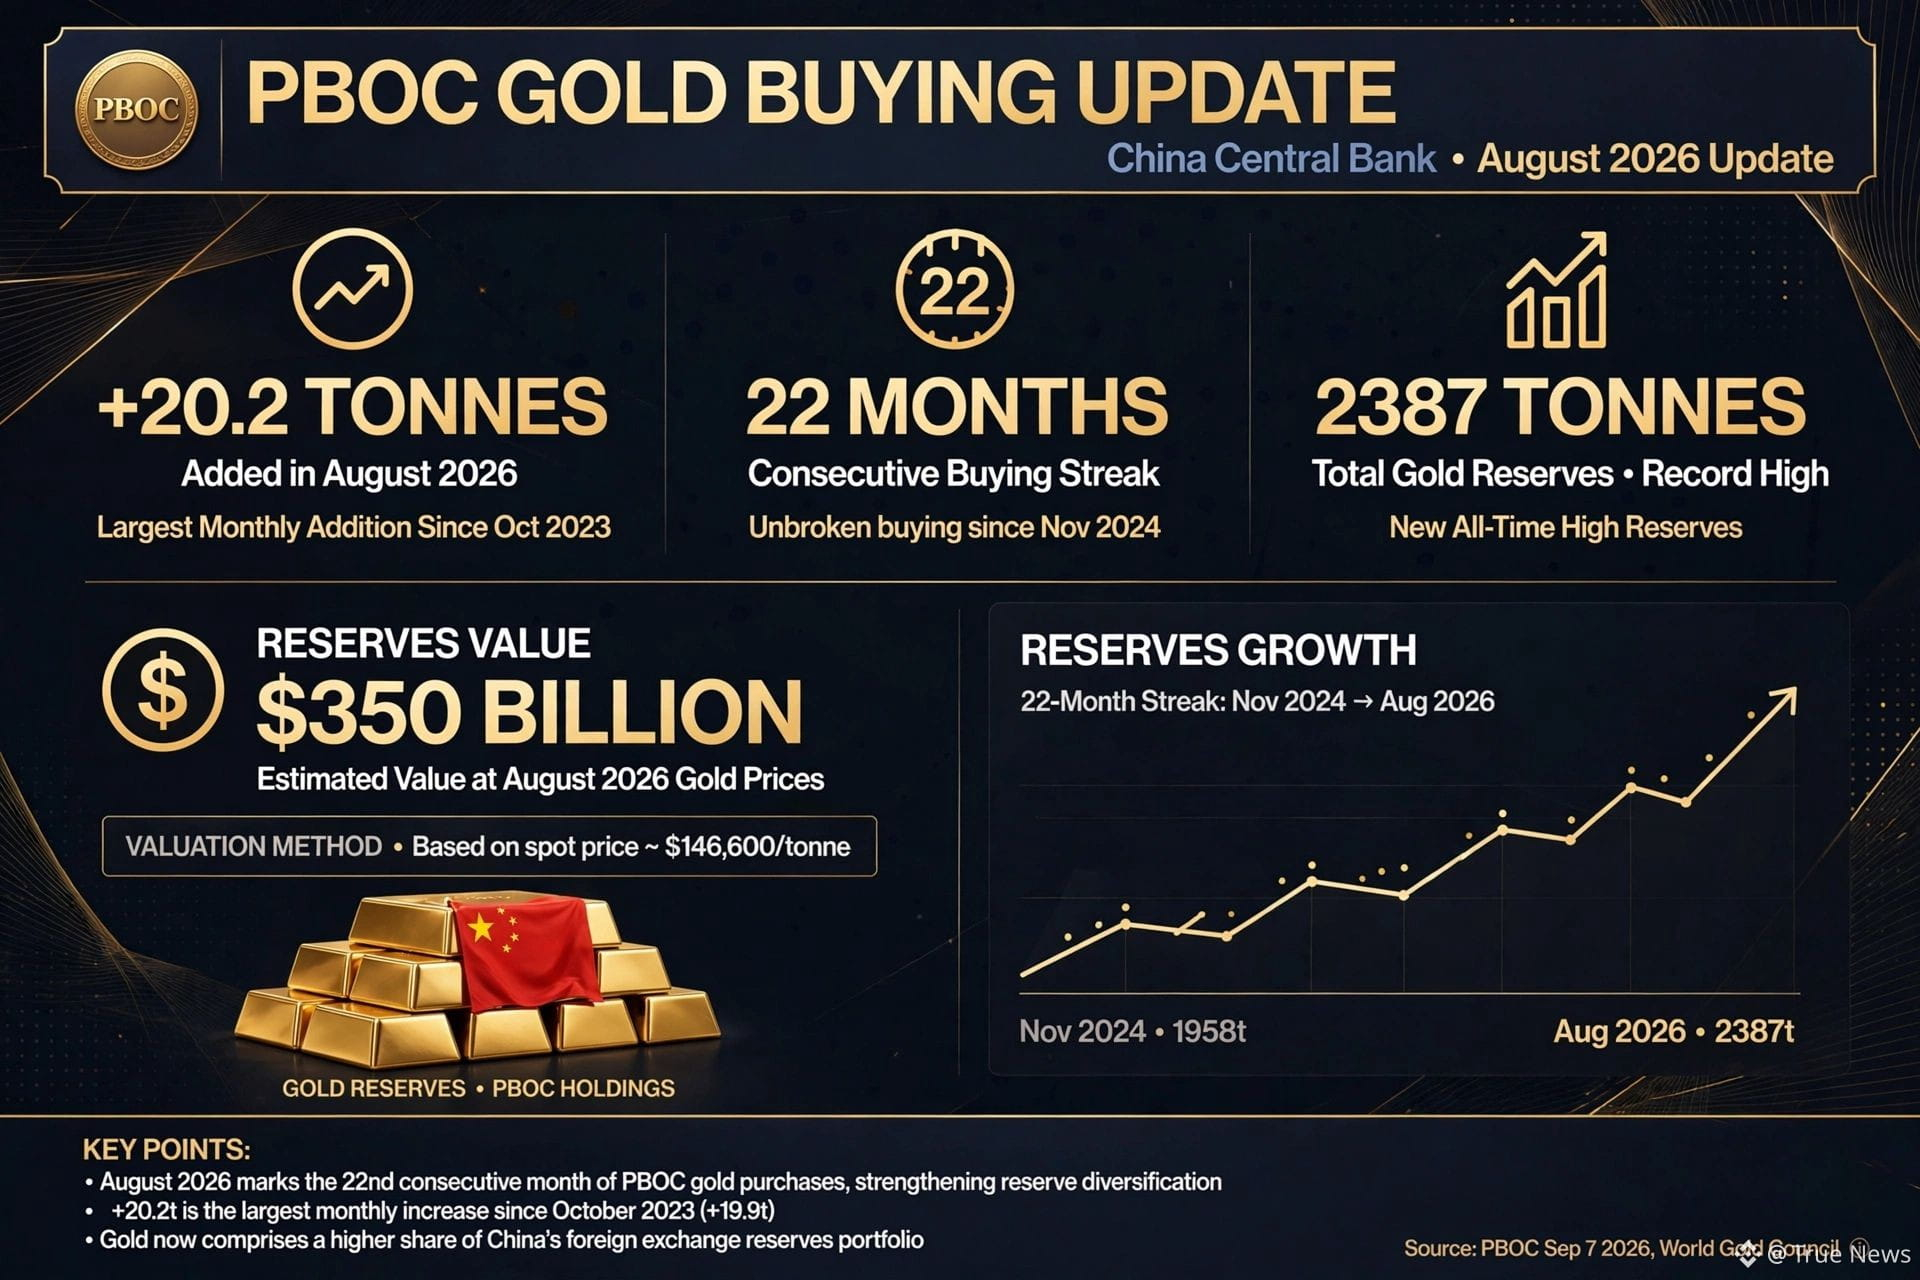
China just made its biggest gold move since 2023.
Official PBOC data released Sep 7 shows China added 20.2 tonnes (650k oz) in August, largest monthly buy since Oct 2023.
This is 22nd straight month of buying, total reserves now 2,387 tonnes, record high worth $350B.
I checked World Gold Council data - China imported 1,141 tonnes in 2026 alone. Gold is now 10% of their forex, vs US 60%. They are clearly de-dollarizing.
My take: This is bullish for both gold and BTC. Central banks buying hard means fiat trust falling. What's your view?
$PAXG $XAUT
#Gold #China #earningseason
1
139
·
--
Verified
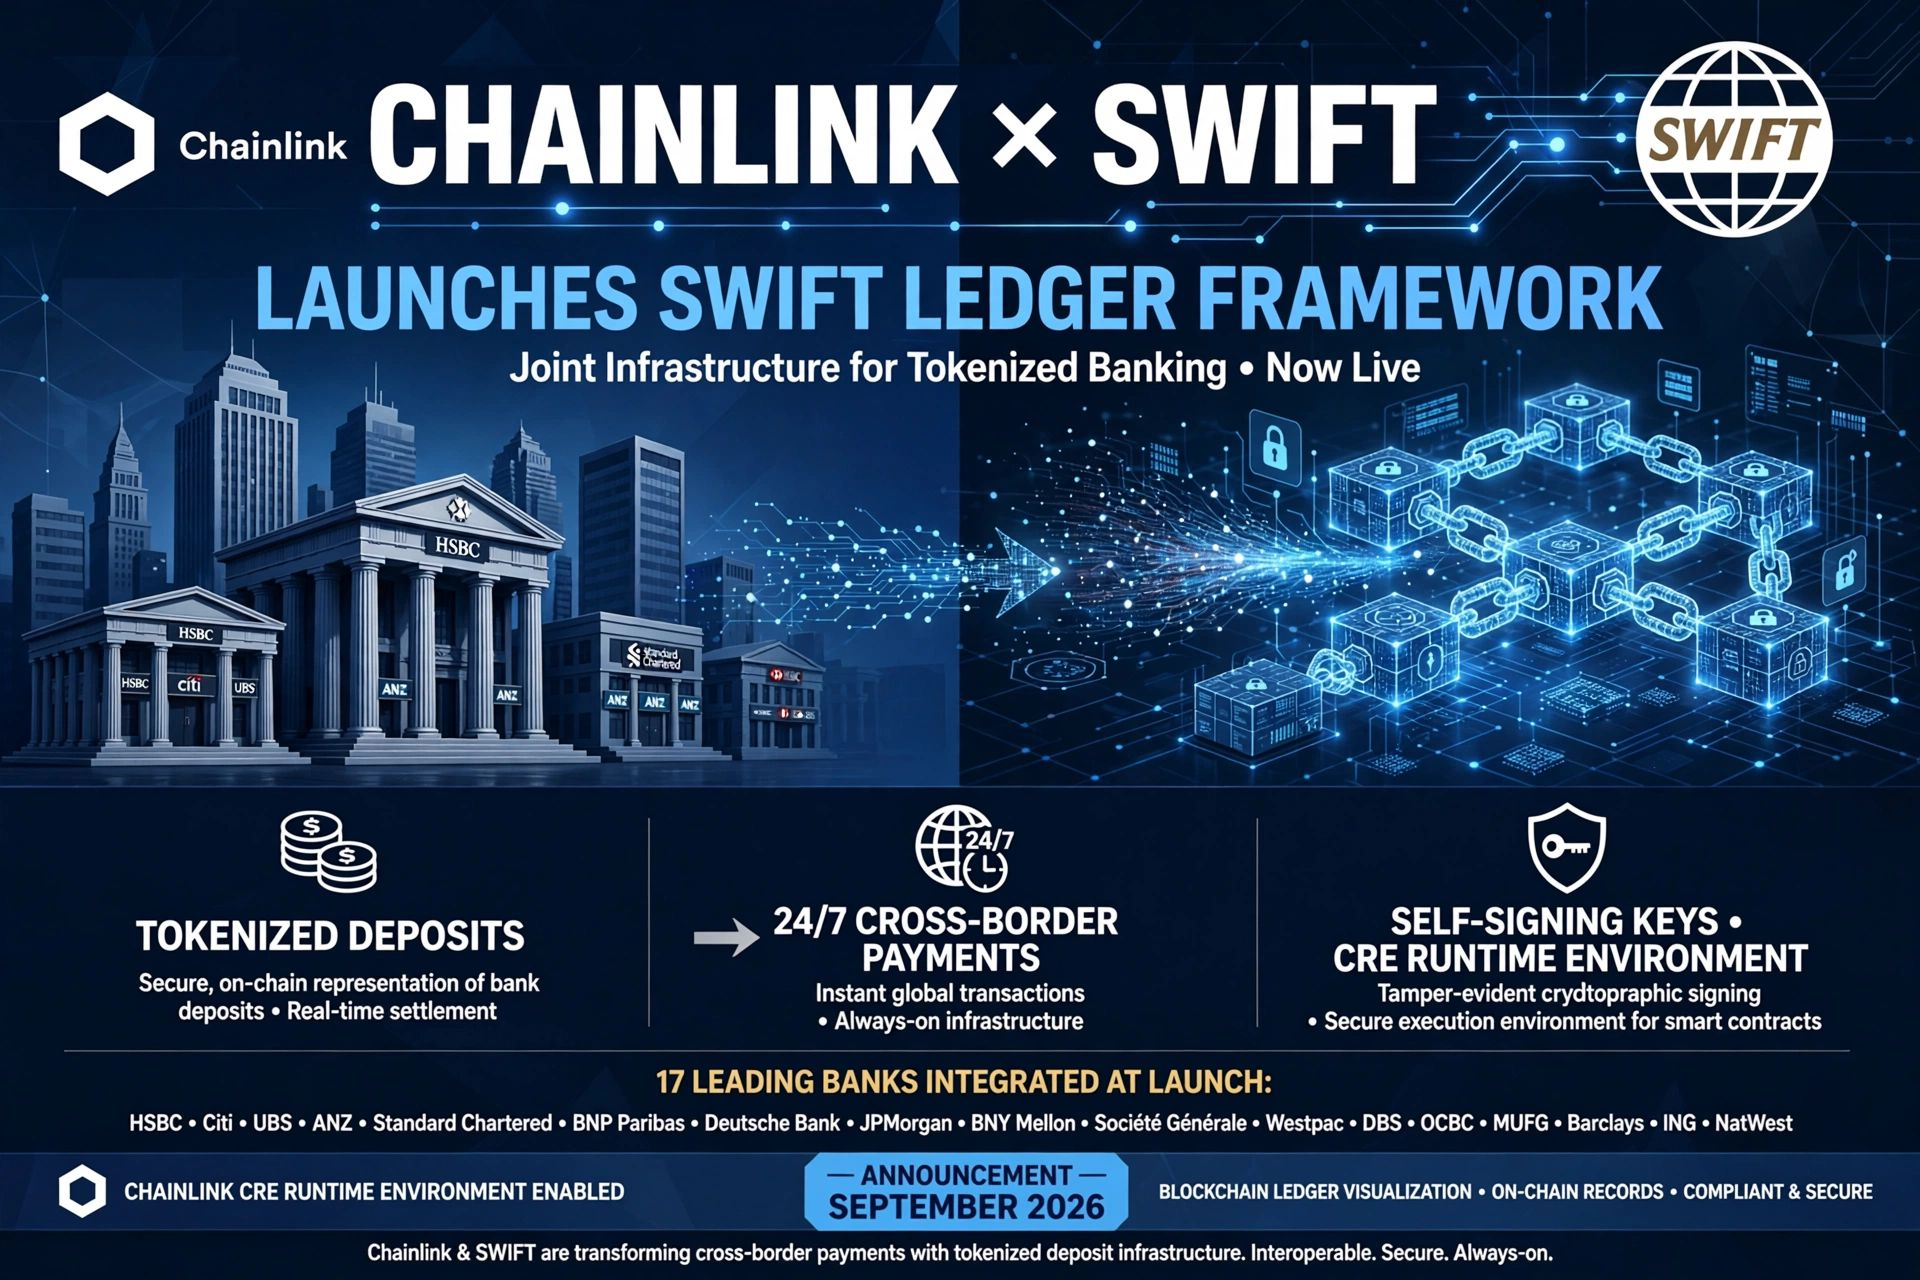
🚨 BREAKING: Chainlink x SWIFT — Bank Ledger Framework Launched!
Massive step for tokenized banking!
Chainlink announced on Sept 28 that it will connect bank systems and signing infrastructure to SWIFT's blockchain ledger through its platform.
Key Points:
CRE lets institutions retain transaction signing keys while orchestrating workflows that access SWIFT's shared ledger SWIFT's ledger supports 24/7 tokenized deposit payments while final settlement continues through existing mechanisms Seventeen banks across six continents are preparing live pilots using tokenized deposits Banks include ANZ, HSBC, Citibank, Standard Chartered, and UBS Framework uses self-signing model — keys stay with bank, Chainlink Runtime Environment (CRE) coordinates workflowSWIFT connects more than 11,500 financial institutions across 200 marketsAnnounced at Sibos 2026 alongside CCIP 2.0
This positions Chainlink as the bridge between traditional banks and on-chain payments.
$LINK $XRP $HBAR $ONDO
#Chainlink #SWIFT #LINK #Tokenization #RWA #Banking #earningseason #chainlinklaunchesbankswiftledgerframework
{spot}(LINKUSDT)
{spot}(XRPUSDT)
{spot}(HBARUSDT)
🚨 BREAKING: Chainlink x SWIFT — Bank Ledger Framework Launched!
Massive step for tokenized banking!
Chainlink announced on Sept 28 that it will connect bank systems and signing infrastructure to SWIFT's blockchain ledger through its platform.
Key Points:
CRE lets institutions retain transaction signing keys while orchestrating workflows that access SWIFT's shared ledger SWIFT's ledger supports 24/7 tokenized deposit payments while final settlement continues through existing mechanisms Seventeen banks across six continents are preparing live pilots using tokenized deposits Banks include ANZ, HSBC, Citibank, Standard Chartered, and UBS Framework uses self-signing model — keys stay with bank, Chainlink Runtime Environment (CRE) coordinates workflowSWIFT connects more than 11,500 financial institutions across 200 marketsAnnounced at Sibos 2026 alongside CCIP 2.0
This positions Chainlink as the bridge between traditional banks and on-chain payments.
$LINK $XRP $HBAR $ONDO
#Chainlink #SWIFT #LINK #Tokenization #RWA #Banking #earningseason #chainlinklaunchesbankswiftledgerframework
Binance BiBi:
Working on it. Your reply is on the way.
5
6
3.1k
·
--
Bullish
🚨 DON'T MAKE THIS MASSIVE TRADING MISTAKE IN THIS MARKET…
While 90% of retail traders are panic selling on small dips and chasing low-cap pumps, smart capital is quietly building positions in real assets. 📉📈
Quick question for the real traders here 👇
If you could only allocate $100 into ONE option for the next 30 days, which move are you making?
1️⃣ Buy $BTC on key support
2️⃣ Accumulate $ETH $ on dips
3️⃣ Bet on high-growth L2 / AI tokens ($PHA, $SOL, etc.)
4️⃣ Hold USDT and wait for a deeper crash
Drop your choice and strategy in the comments! Let's see where the smart money is heading. 🚀
#cryptooinsigts #earningseason #Bitcoin #Ethereum #Altcoins $BTC
{spot}(ETHUSDT)
{spot}(BTCUSDT)
🚨 DON'T MAKE THIS MASSIVE TRADING MISTAKE IN THIS MARKET…
While 90% of retail traders are panic selling on small dips and chasing low-cap pumps, smart capital is quietly building positions in real assets. 📉📈
Quick question for the real traders here 👇
If you could only allocate $100 into ONE option for the next 30 days, which move are you making?
1️⃣ Buy $BTC on key support
2️⃣ Accumulate $ETH $ on dips
3️⃣ Bet on high-growth L2 / AI tokens ($PHA, $SOL, etc.)
4️⃣ Hold USDT and wait for a deeper crash
Drop your choice and strategy in the comments! Let's see where the smart money is heading. 🚀
#cryptooinsigts #earningseason #Bitcoin #Ethereum #Altcoins $BTC
94
·
--
🚨 MICRON (MU) — AI CHIP DEMAND IS HEATING UP 🔥
Micron Technology is one of the major players in memory chips, including DRAM and NAND. With AI data centers requiring huge amounts of high-performance memory, demand for advanced memory products remains an important theme for the semiconductor market. 🤖💾
📌 Why traders are watching MU: • Strong AI & data-center memory demand • Growing focus on high-bandwidth memory (HBM) • Semiconductor sector momentum • Earnings and guidance can strongly impact MU’s price
Remember: MU is a stock, not a cryptocurrency, and its price can be highly volatile around earnings and major semiconductor news.
What do you think? 👇 📈 Bullish on MU 📉 Bearish on MU 👀 Watching only
#Micron #MU #AI #Semiconductors #StockMarket #TechStocks #BinanceSquare #CryptoCommunity
#earningseason
Captain Abd Elnaser:
Look
35
2
67
🚨 $BTC CROSSES $84,000 AGAIN
Bitcoin just pushed back above $84K, with the 1H chart showing strong buying momentum.
From the chart:
Current: ~$85,374
24H high: $85,650
Support: $84,000–$84,100
Next resistance: $85,650–$86,000
BTC is now testing the area where sellers previously stepped in. A clean hold above $84K keeps the short-term structure interesting, while losing that level could bring the recent $82.9K area back into focus.
$84K is the level to watch. 👀
$BTC #Bitcoin #BTC #Crypto #BinanceSquare #Earningseason
{future}(BTCUSDT)
🚨 $BTC CROSSES $84,000 AGAIN
Bitcoin just pushed back above $84K, with the 1H chart showing strong buying momentum.
From the chart:
Current: ~$85,374
24H high: $85,650
Support: $84,000–$84,100
Next resistance: $85,650–$86,000
BTC is now testing the area where sellers previously stepped in. A clean hold above $84K keeps the short-term structure interesting, while losing that level could bring the recent $82.9K area back into focus.
$84K is the level to watch. 👀
$BTC #Bitcoin #BTC #Crypto #BinanceSquare #Earningseason
62
·
--
Verified
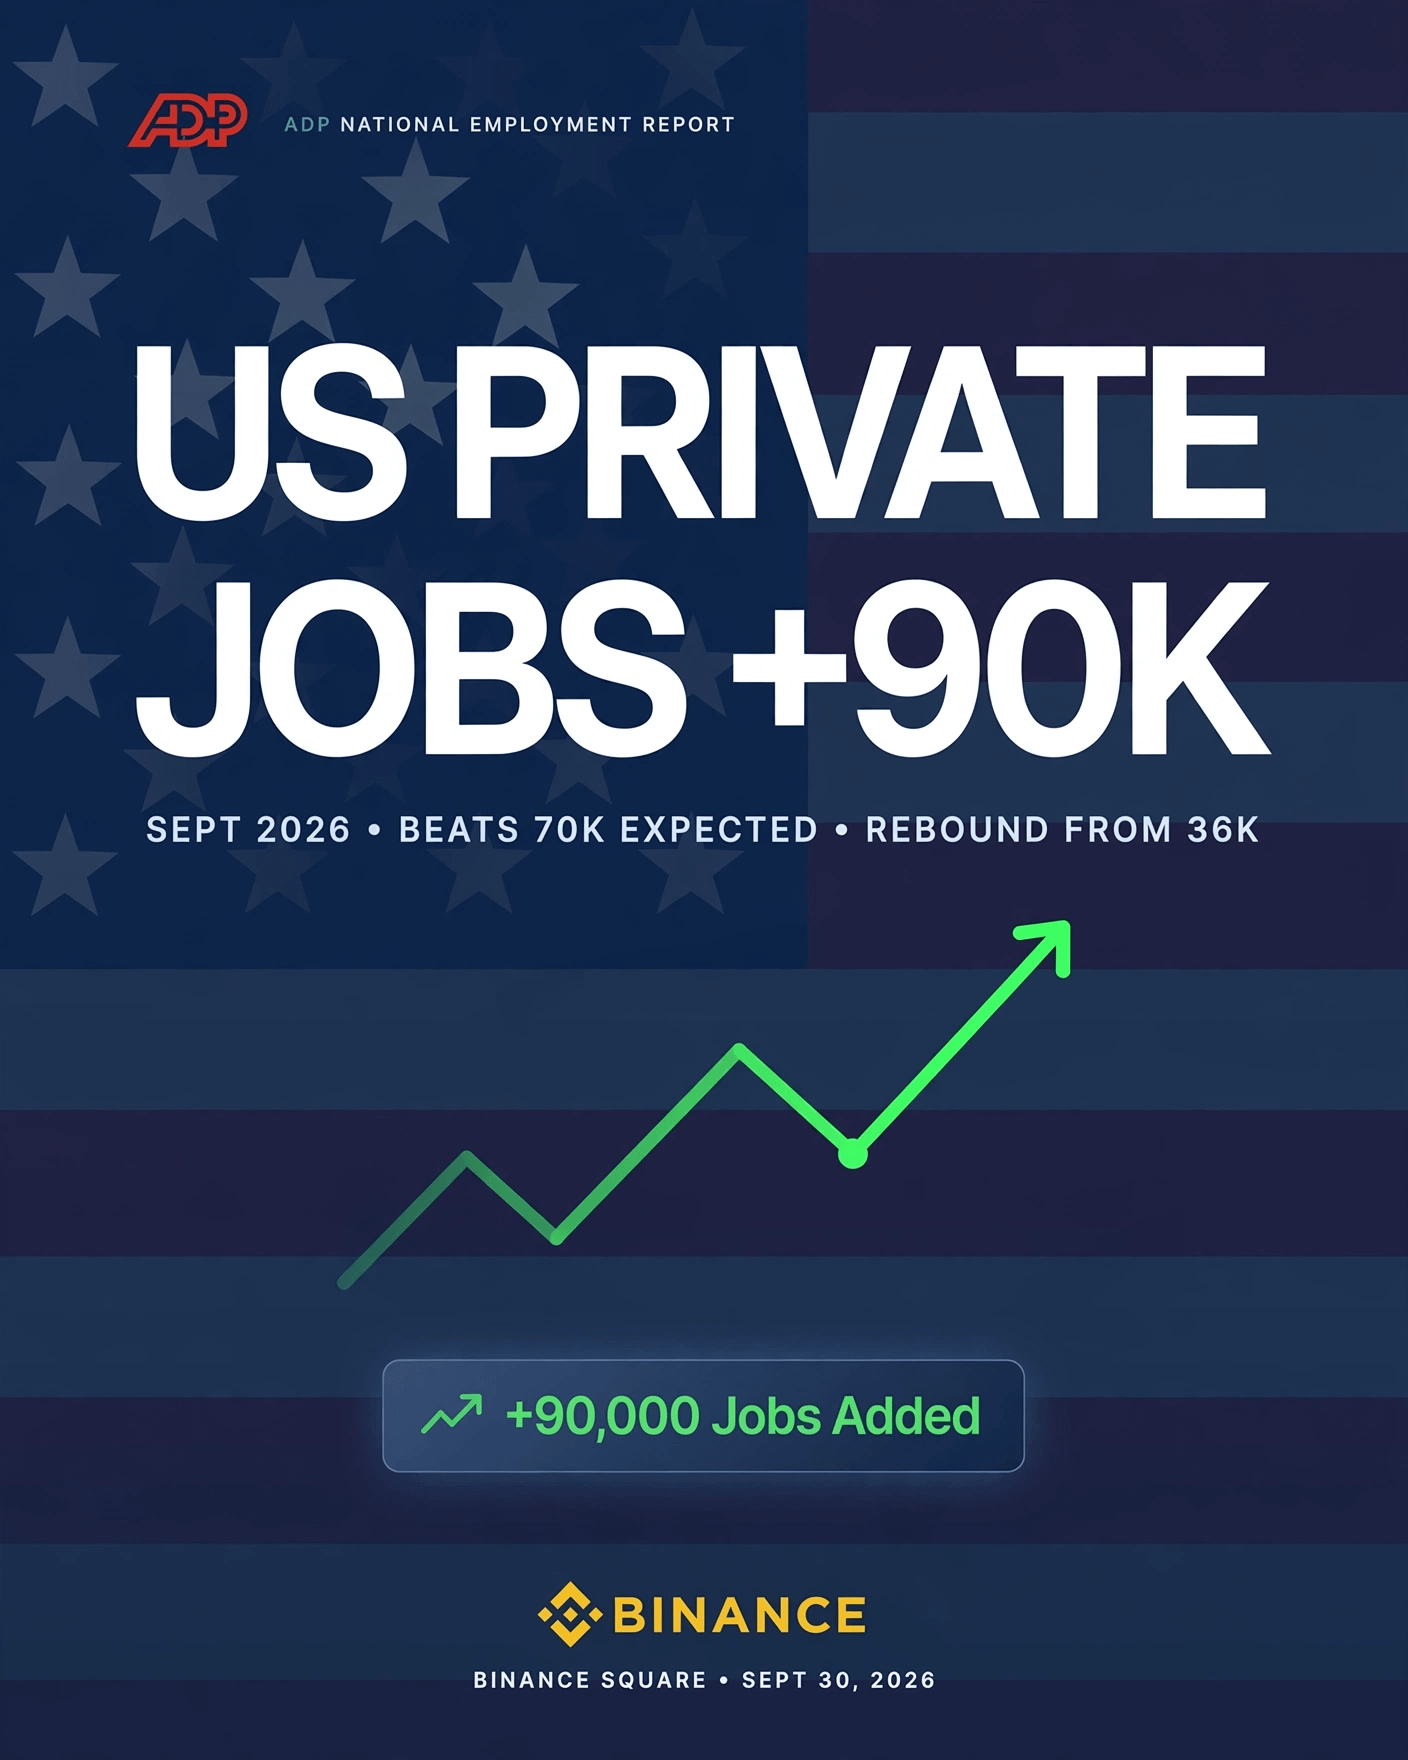
🚨 BREAKING: US Private Sector Adds 90K Jobs in September!
ADP Report Sept 30 2026: +90K vs 70K expected, up from revised 36K in August.
First rebound since May! Breakdown: Education & Health +55K, Leisure +22K, Construction +15K, Manufacturing +17K.
Financial -16K weak.
Pay growth solid: Job-stayers +4.4% YoY, job-changers +7.3%. Base pay +3.2%. Strong labor market but cooling inflation keeps Fed cut hopes alive.
Is this bullish for risk assets?
$BTC $ETH $SOL
#ADP #USJobs #NFP #Economy #Breaking #earningseason #usadpadds90000jobsinseptember
1
1.6k

·
--
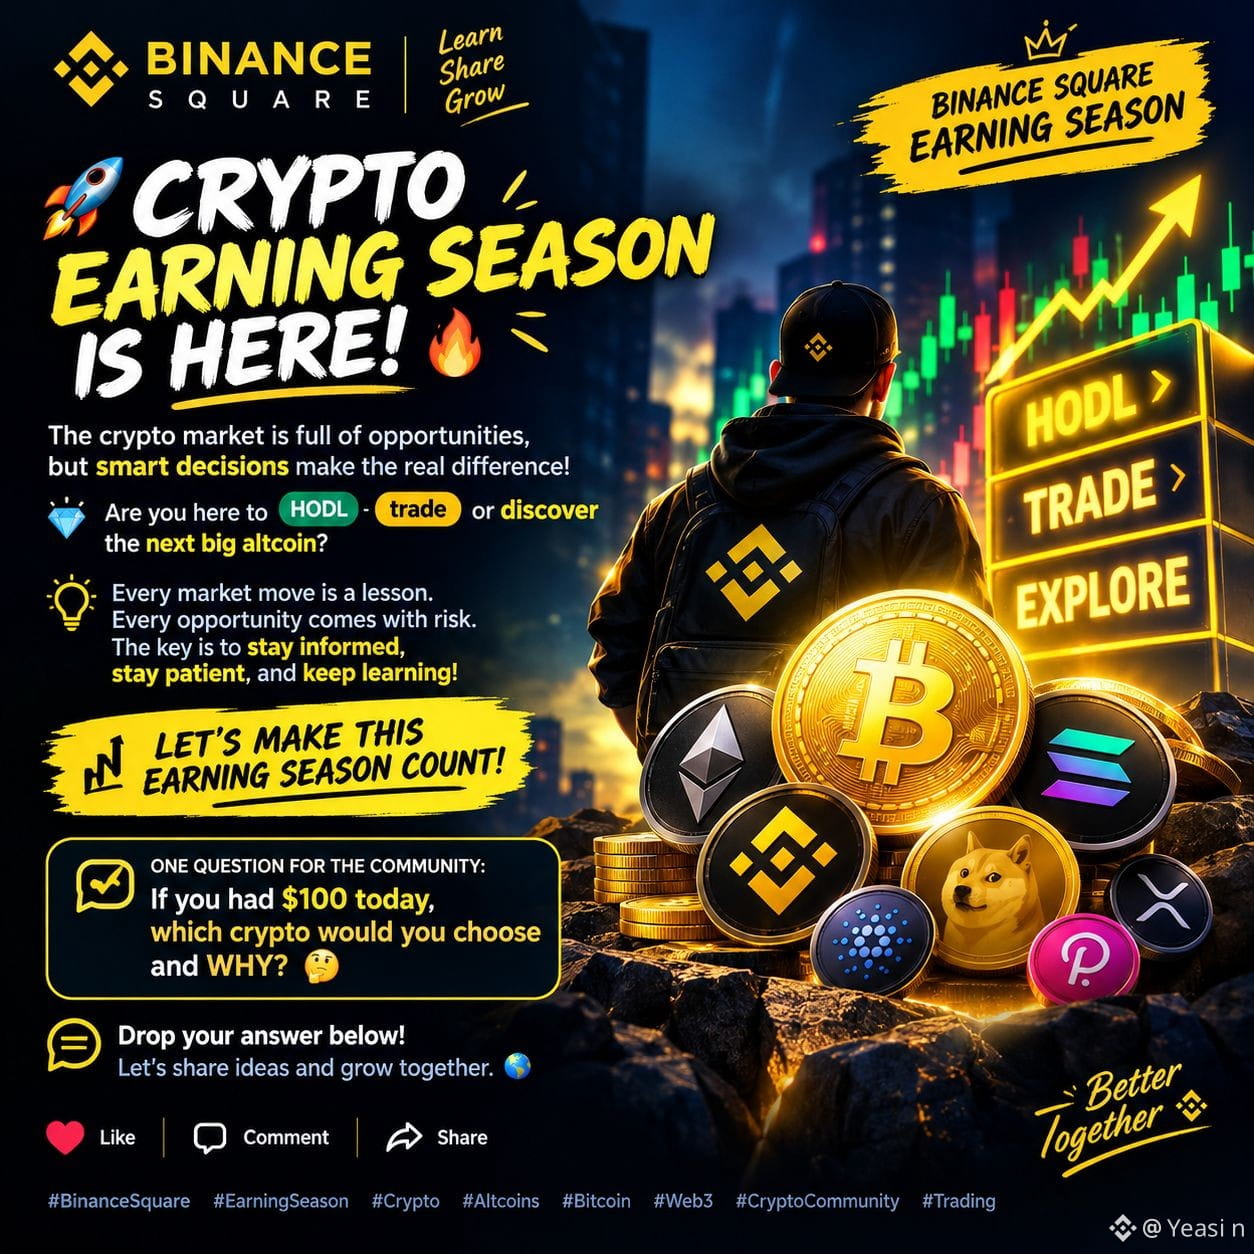
🔥 CRYPTO EARNING SEASON IS HERE! 💰🚀
The crypto market is full of opportunities, but smart decisions make the real difference! 👀
💎 Are you here to HODL, trade, or discover the next big altcoin?
📈 Every market move is a lesson. Every opportunity comes with risk. The key is to stay informed, stay patient, and keep learning!
🔥 LET'S MAKE THIS EARNING SEASON COUNT!
👇 ONE QUESTION FOR THE COMMUNITY:
If you had $100 today, which crypto would you choose and WHY? 🤔💰
Drop your answer below! Let's share ideas and grow together. 🌍
#BinanceSquare #EarningSeason #Crypto #Altcoins #Bitcoin #Web3
73
·
--
Bullish
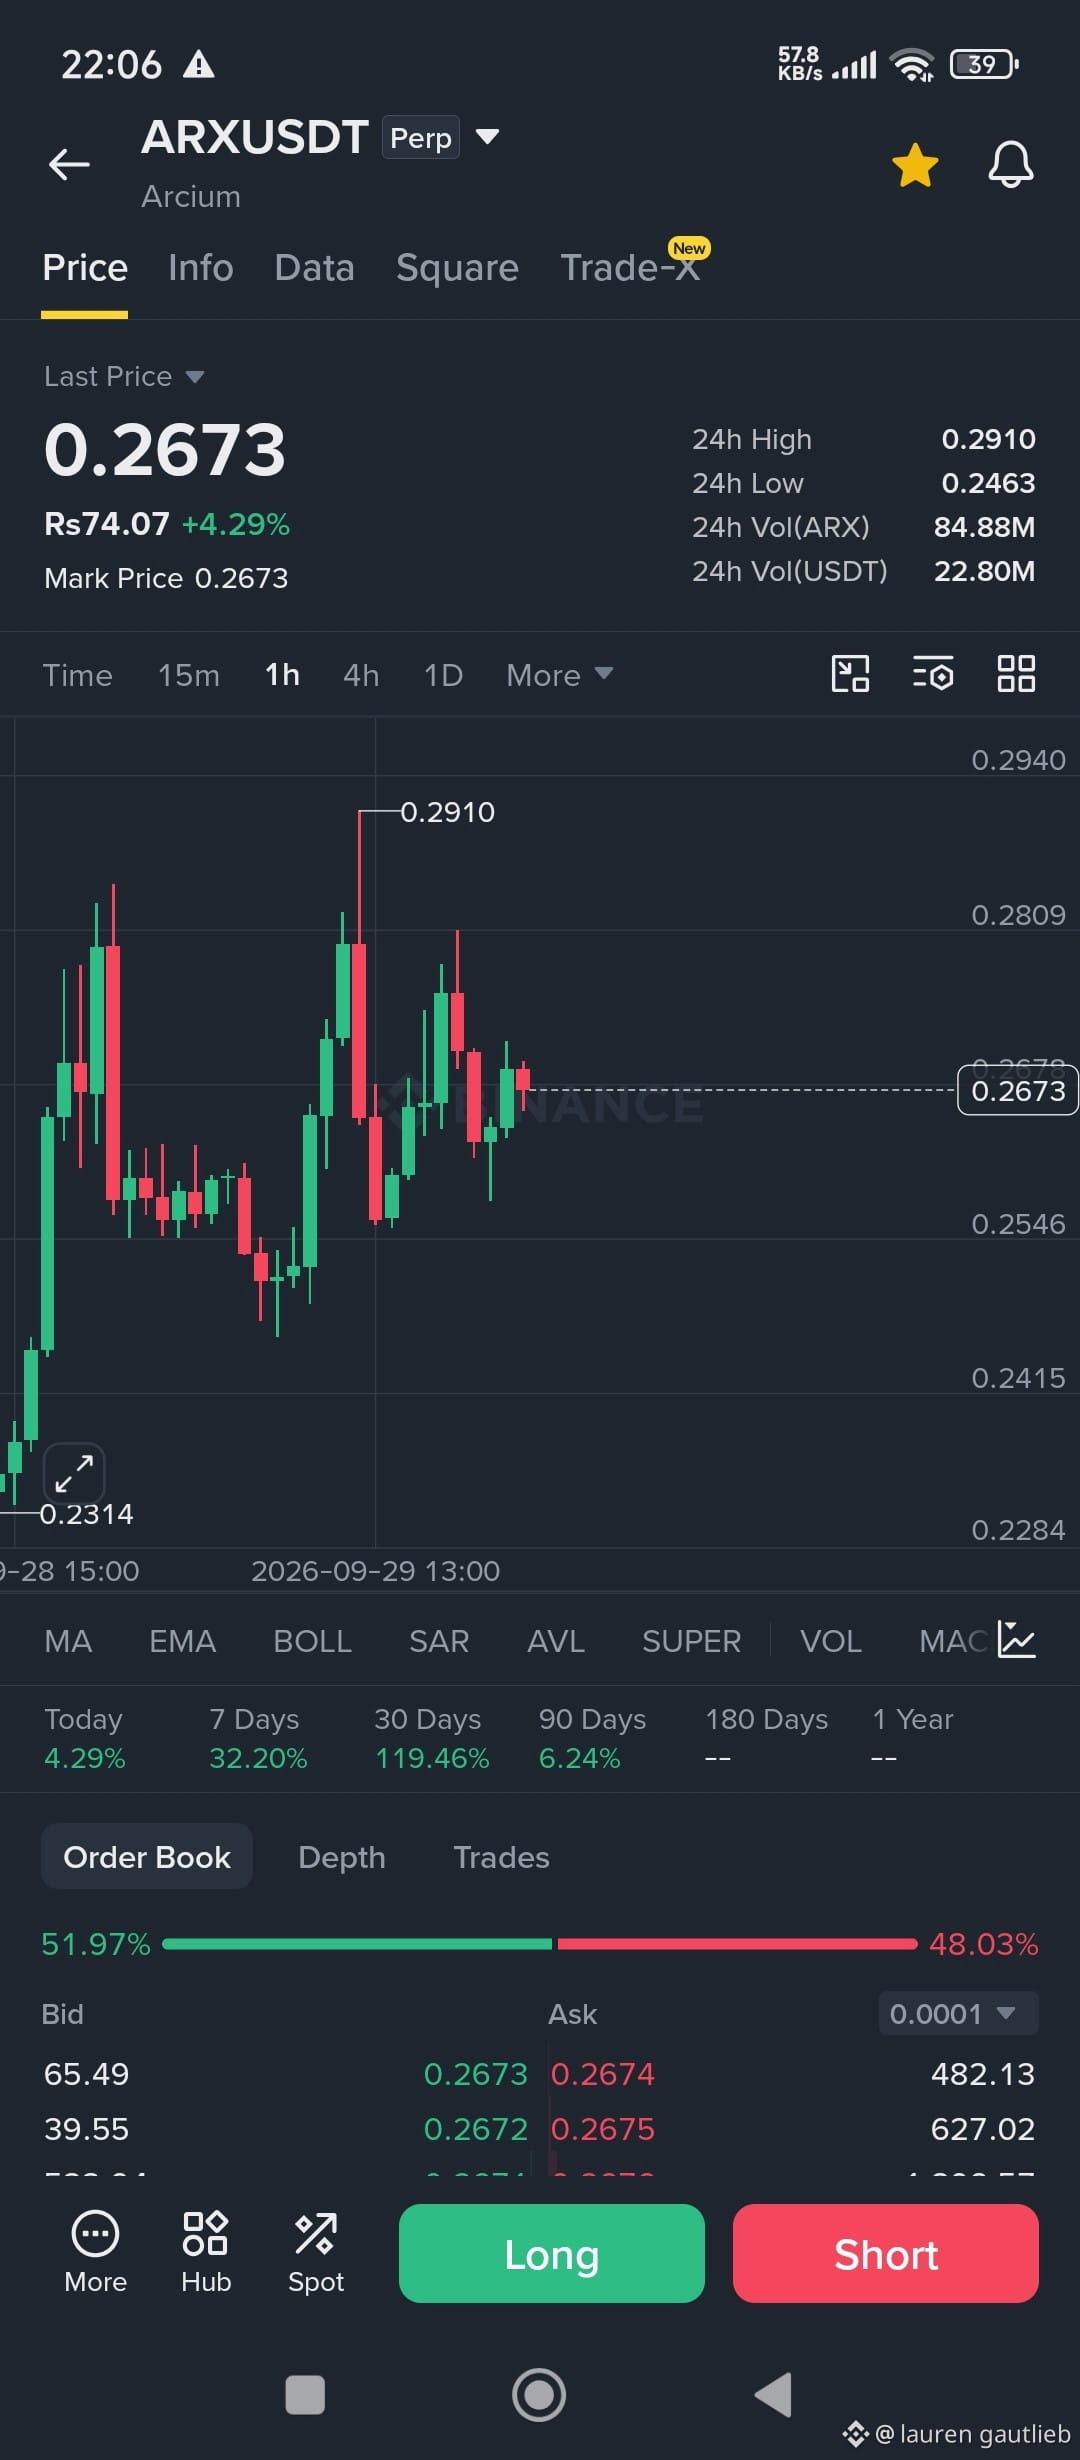
$ARX USDT LONG TRADE SIGNAL 🚀🔥
📈 Trade Setup: Long
🎯 Entry: 0.2640–0.2680
🟢 TP1: 0.2809
🟢 TP2: 0.2910
🟢 TP3: 0.3040
🔴 SL: 0.2540
Market Outlook: $ARX is holding above the 0.2546 support zone after a strong rebound. A sustained move above 0.2809 could open the path toward 0.2910 and higher resistance levels. Losing 0.2540 would weaken the bullish setup.
#ARX #ARXUSDT #Earningseason #EarningsSeason
1
772
·
--
#EarningsSeason
$BTC $GOLD.US #btc70k #Earncommissions #Earningseason
💰 Earning Season is here!
The crypto market can create opportunities, but smart decisions matter more than chasing quick profits.
Stay patient. Manage your risk. Keep learning. 📈
What are you watching this season — BTC, ETH, or Altcoins? 👇
#EarningSeason💰 Earning Season is here!
206 Atlas:
Patience is good, but vague risk management means nothing without defined invalidation.
1
1
104
·
--
Partly True
Micron Technology is expected to release its fiscal fourth-quarter financial results for 2026 on September 30, 2026, after the U.S. market closes.
📊 Wall Street Forecasts and Expectations
Revenue is expected to be: ~$50.0 billion to $51.4 billion (according to Micron’s official guidance of $50.0 billion ± $1 billion).
Non-GAAP EPS: ~US$31.00 to US$31.60.
Non-GAAP gross margin: About 86%.
Growth catalysts: A surge in demand for AI memory chips, especially high-bandwidth memory (HBM) and DRAM
Suitable for short-term trading/“scalping”; only accumulate if it’s below 1000
#EarningsSeason #EarningSeason
158
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#KoreaProposesTokenizingStocksAndBonds
13,467 views
263 Discussing
2
#MetaMaskExitsLidoValidatorsAfterSecurityIncident
79,058 views
989 Discussing
3
#MicronBeatsEarningsLiftsGuidance
46,377 views
758 Discussing
4
#CFTCSubmitsTwoEventContractRulesToWhiteHouse
32,115 views
625 Discussing
5
#BitcoinClears$85200
38,249 views
363 Discussing
6
#AltcoinSeasonIndexHoldsAbove60For5Days
180,812 views
2,213 Discussing
7
#USADPAdds90000JobsInSeptember
85,313 views
1,257 Discussing
8
#USCorePCEEasesTo3%InAugust
60,630 views
813 Discussing
9
#KospiPostsWorstQuarterSince2020
31,533 views
638 Discussing
10
#SECToClarifyOnChainFundraisingRules
76,579 views
877 Discussing