
#chipequipment
chipequipment
0 views
3 Discussing
Hot
Latest

·
--
Article
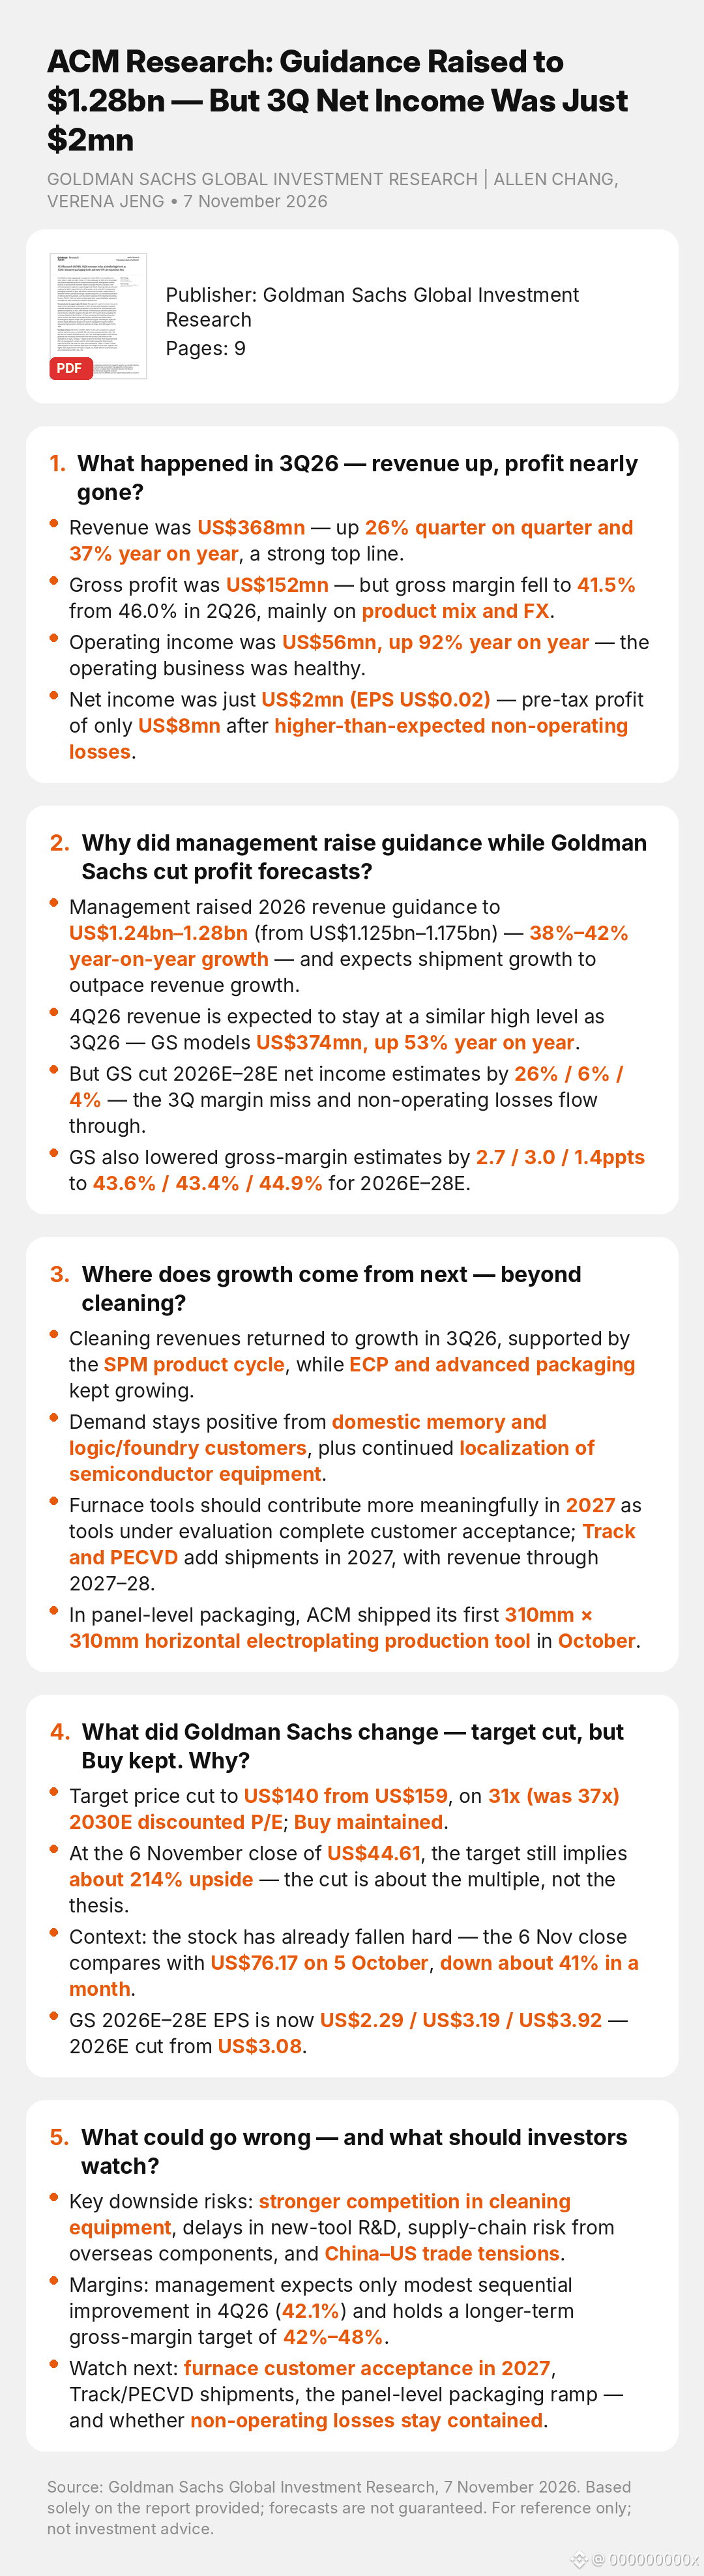
ACM Research: Guidance Raised to $1.28bn — But 3Q Net Income Was Just $2mnACM Research: Guidance Raised to $1.28bn — But 3Q Net Income Was Just $2mn
$ACMR
GOLDMAN SACHS GLOBAL INVESTMENT RESEARCH | ALLEN CHANG, VERENA JENG • 7 November 2026
1. What happened in 3Q26 — revenue up, profit nearly gone?
• Revenue was US$368mn — up 26% quarter on quarter and 37% year on year, a strong top line.
• Gross profit was US$152mn — but gross margin fell to 41.5% from 46.0% in 2Q26, mainly on product mix and FX.
• Operating income was US$56mn, up 92% year on year — the operating business was healthy.
• Net income was just US$2mn (EPS US$0.02) — pre-tax profit of only US$8mn after higher-than-expected non-operating losses.
2. Why did management raise guidance while Goldman Sachs cut profit forecasts?
• Management raised 2026 revenue guidance to US$1.24bn–1.28bn (from US$1.125bn–1.175bn) — 38%–42% year-on-year growth — and expects shipment growth to outpace revenue growth.
• 4Q26 revenue is expected to stay at a similar high level as 3Q26 — GS models US$374mn, up 53% year on year.
• But GS cut 2026E–28E net income estimates by 26% / 6% / 4% — the 3Q margin miss and non-operating losses flow through.
• GS also lowered gross-margin estimates by 2.7 / 3.0 / 1.4ppts to 43.6% / 43.4% / 44.9% for 2026E–28E.
3. Where does growth come from next — beyond cleaning?
• Cleaning revenues returned to growth in 3Q26, supported by the SPM product cycle, while ECP and advanced packaging kept growing.
• Demand stays positive from domestic memory and logic/foundry customers, plus continued localization of semiconductor equipment.
• Furnace tools should contribute more meaningfully in 2027 as tools under evaluation complete customer acceptance; Track and PECVD add shipments in 2027, with revenue through 2027–28.
• In panel-level packaging, ACM shipped its first 310mm × 310mm horizontal electroplating production tool in October.
4. What did Goldman Sachs change — target cut, but Buy kept. Why?
• Target price cut to US$140 from US$159, on 31x (was 37x) 2030E discounted P/E; Buy maintained.
• At the 6 November close of US$44.61, the target still implies about 214% upside — the cut is about the multiple, not the thesis.
• Context: the stock has already fallen hard — the 6 Nov close compares with US$76.17 on 5 October, down about 41% in a month.
• GS 2026E–28E EPS is now US$2.29 / US$3.19 / US$3.92 — 2026E cut from US$3.08.
5. What could go wrong — and what should investors watch?
• Key downside risks: stronger competition in cleaning equipment, delays in new-tool R&D, supply-chain risk from overseas components, and China–US trade tensions.
• Margins: management expects only modest sequential improvement in 4Q26 (42.1%) and holds a longer-term gross-margin target of 42%–48%.
• Watch next: furnace customer acceptance in 2027, Track/PECVD shipments, the panel-level packaging ramp — and whether non-operating losses stay contained.
Since the report (20 Nov): AI hardware sold off sharply — Nvidia -14%, Nasdaq -5.3% in a day — a reminder that the datacenter chain is not immune to valuation resets. (Market reports, 21 Nov 2026.)
#Semiconductors #AI #ChinaTech #ChipEquipment #AdvancedPackaging
Source: Goldman Sachs Global Investment Research, 7 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-b12f72e6b0e549dc8891c713b598a994-en
Visit unhidea.com for more of the latest sell-side research interpretations.
ACM Research: Guidance Raised to $1.28bn — But 3Q Net Income Was Just $2mn
ACM Research: Guidance Raised to $1.28bn — But 3Q Net Income Was Just $2mn
$ACMR
GOLDMAN SACHS GLOBAL INVESTMENT RESEARCH | ALLEN CHANG, VERENA JENG • 7 November 2026
1. What happened in 3Q26 — revenue up, profit nearly gone?
• Revenue was US$368mn — up 26% quarter on quarter and 37% year on year, a strong top line.
• Gross profit was US$152mn — but gross margin fell to 41.5% from 46.0% in 2Q26, mainly on product mix and FX.
• Operating income was US$56mn, up 92% year on year — the operating business was healthy.
• Net income was just US$2mn (EPS US$0.02) — pre-tax profit of only US$8mn after higher-than-expected non-operating losses.
2. Why did management raise guidance while Goldman Sachs cut profit forecasts?
• Management raised 2026 revenue guidance to US$1.24bn–1.28bn (from US$1.125bn–1.175bn) — 38%–42% year-on-year growth — and expects shipment growth to outpace revenue growth.
• 4Q26 revenue is expected to stay at a similar high level as 3Q26 — GS models US$374mn, up 53% year on year.
• But GS cut 2026E–28E net income estimates by 26% / 6% / 4% — the 3Q margin miss and non-operating losses flow through.
• GS also lowered gross-margin estimates by 2.7 / 3.0 / 1.4ppts to 43.6% / 43.4% / 44.9% for 2026E–28E.
3. Where does growth come from next — beyond cleaning?
• Cleaning revenues returned to growth in 3Q26, supported by the SPM product cycle, while ECP and advanced packaging kept growing.
• Demand stays positive from domestic memory and logic/foundry customers, plus continued localization of semiconductor equipment.
• Furnace tools should contribute more meaningfully in 2027 as tools under evaluation complete customer acceptance; Track and PECVD add shipments in 2027, with revenue through 2027–28.
• In panel-level packaging, ACM shipped its first 310mm × 310mm horizontal electroplating production tool in October.
4. What did Goldman Sachs change — target cut, but Buy kept. Why?
• Target price cut to US$140 from US$159, on 31x (was 37x) 2030E discounted P/E; Buy maintained.
• At the 6 November close of US$44.61, the target still implies about 214% upside — the cut is about the multiple, not the thesis.
• Context: the stock has already fallen hard — the 6 Nov close compares with US$76.17 on 5 October, down about 41% in a month.
• GS 2026E–28E EPS is now US$2.29 / US$3.19 / US$3.92 — 2026E cut from US$3.08.
5. What could go wrong — and what should investors watch?
• Key downside risks: stronger competition in cleaning equipment, delays in new-tool R&D, supply-chain risk from overseas components, and China–US trade tensions.
• Margins: management expects only modest sequential improvement in 4Q26 (42.1%) and holds a longer-term gross-margin target of 42%–48%.
• Watch next: furnace customer acceptance in 2027, Track/PECVD shipments, the panel-level packaging ramp — and whether non-operating losses stay contained.
Since the report (20 Nov): AI hardware sold off sharply — Nvidia -14%, Nasdaq -5.3% in a day — a reminder that the datacenter chain is not immune to valuation resets. (Market reports, 21 Nov 2026.)
#Semiconductors #AI #ChinaTech #ChipEquipment #AdvancedPackaging
Source: Goldman Sachs Global Investment Research, 7 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-b12f72e6b0e549dc8891c713b598a994-en
Visit unhidea.com for more of the latest sell-side research interpretations.
$ACMR
GOLDMAN SACHS GLOBAL INVESTMENT RESEARCH | ALLEN CHANG, VERENA JENG • 7 November 2026
1. What happened in 3Q26 — revenue up, profit nearly gone?
• Revenue was US$368mn — up 26% quarter on quarter and 37% year on year, a strong top line.
• Gross profit was US$152mn — but gross margin fell to 41.5% from 46.0% in 2Q26, mainly on product mix and FX.
• Operating income was US$56mn, up 92% year on year — the operating business was healthy.
• Net income was just US$2mn (EPS US$0.02) — pre-tax profit of only US$8mn after higher-than-expected non-operating losses.
2. Why did management raise guidance while Goldman Sachs cut profit forecasts?
• Management raised 2026 revenue guidance to US$1.24bn–1.28bn (from US$1.125bn–1.175bn) — 38%–42% year-on-year growth — and expects shipment growth to outpace revenue growth.
• 4Q26 revenue is expected to stay at a similar high level as 3Q26 — GS models US$374mn, up 53% year on year.
• But GS cut 2026E–28E net income estimates by 26% / 6% / 4% — the 3Q margin miss and non-operating losses flow through.
• GS also lowered gross-margin estimates by 2.7 / 3.0 / 1.4ppts to 43.6% / 43.4% / 44.9% for 2026E–28E.
3. Where does growth come from next — beyond cleaning?
• Cleaning revenues returned to growth in 3Q26, supported by the SPM product cycle, while ECP and advanced packaging kept growing.
• Demand stays positive from domestic memory and logic/foundry customers, plus continued localization of semiconductor equipment.
• Furnace tools should contribute more meaningfully in 2027 as tools under evaluation complete customer acceptance; Track and PECVD add shipments in 2027, with revenue through 2027–28.
• In panel-level packaging, ACM shipped its first 310mm × 310mm horizontal electroplating production tool in October.
4. What did Goldman Sachs change — target cut, but Buy kept. Why?
• Target price cut to US$140 from US$159, on 31x (was 37x) 2030E discounted P/E; Buy maintained.
• At the 6 November close of US$44.61, the target still implies about 214% upside — the cut is about the multiple, not the thesis.
• Context: the stock has already fallen hard — the 6 Nov close compares with US$76.17 on 5 October, down about 41% in a month.
• GS 2026E–28E EPS is now US$2.29 / US$3.19 / US$3.92 — 2026E cut from US$3.08.
5. What could go wrong — and what should investors watch?
• Key downside risks: stronger competition in cleaning equipment, delays in new-tool R&D, supply-chain risk from overseas components, and China–US trade tensions.
• Margins: management expects only modest sequential improvement in 4Q26 (42.1%) and holds a longer-term gross-margin target of 42%–48%.
• Watch next: furnace customer acceptance in 2027, Track/PECVD shipments, the panel-level packaging ramp — and whether non-operating losses stay contained.
Since the report (20 Nov): AI hardware sold off sharply — Nvidia -14%, Nasdaq -5.3% in a day — a reminder that the datacenter chain is not immune to valuation resets. (Market reports, 21 Nov 2026.)
#Semiconductors #AI #ChinaTech #ChipEquipment #AdvancedPackaging
Source: Goldman Sachs Global Investment Research, 7 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-b12f72e6b0e549dc8891c713b598a994-en
Visit unhidea.com for more of the latest sell-side research interpretations.
ACMRUS-11.54%
·
--
Bullish
🟢 $LRCX
{future}(LRCXUSDT)
Short Liquidation Alert
💰 Liquidated Amount:
$6.3225K
📍 Liquidation Price:
$287.38478 (BINANCE)
━━━━━━━━━━━━━━
📊 Trade Outlook
🎯 Target:
$298.80
📥 Entry Zone:
$288.20–$289.40
📈 Take Profit:
$296.10
🛑 Stop Loss:
$283.70
━━━━━━━━━━━━━━
⚡ ELITE TRADE INSIGHT ⚡
The short liquidation points to renewed buying momentum, with upside liquidity potentially building above the current liquidation zone. Confirmation above the entry range would improve the continuation setup, while a defined stop helps control risk if the squeeze fades.
#LRCX #Semiconductors #ChipEquipment
🟢 $LRCX
Short Liquidation Alert
💰 Liquidated Amount:
$6.3225K
📍 Liquidation Price:
$287.38478 (BINANCE)
━━━━━━━━━━━━━━
📊 Trade Outlook
🎯 Target:
$298.80
📥 Entry Zone:
$288.20–$289.40
📈 Take Profit:
$296.10
🛑 Stop Loss:
$283.70
━━━━━━━━━━━━━━
⚡ ELITE TRADE INSIGHT ⚡
The short liquidation points to renewed buying momentum, with upside liquidity potentially building above the current liquidation zone. Confirmation above the entry range would improve the continuation setup, while a defined stop helps control risk if the squeeze fades.
#LRCX #Semiconductors #ChipEquipment
Short Liquidation Alert
💰 Liquidated Amount:
$6.3225K
📍 Liquidation Price:
$287.38478 (BINANCE)
━━━━━━━━━━━━━━
📊 Trade Outlook
🎯 Target:
$298.80
📥 Entry Zone:
$288.20–$289.40
📈 Take Profit:
$296.10
🛑 Stop Loss:
$283.70
━━━━━━━━━━━━━━
⚡ ELITE TRADE INSIGHT ⚡
The short liquidation points to renewed buying momentum, with upside liquidity potentially building above the current liquidation zone. Confirmation above the entry range would improve the continuation setup, while a defined stop helps control risk if the squeeze fades.
#LRCX #Semiconductors #ChipEquipment
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BTCReboundsAbove$60KAmidWhaleDipBuying
5,597 views
59 Discussing
2
#NvidiaLoses$2.7TrillionInMonthAndAHalf
44,691 views
209 Discussing
3
#GlobalStocksFaceLongestLosingStreakSince2023
402,328 views
2,668 Discussing
4
#BlackRockIBITPostsRecord$541MSingleDayOutflow
59,781 views
146 Discussing
5
#AnthropicPlungesTowardIPOPriceonDay2
215,608 views
1,713 Discussing
6
#TwentyOneCapitalAdds172.25BTC
105,300 views
1,117 Discussing
7
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
14,573 views
67 Discussing
8
#HKBillProposesHK$100KFineForUnauthorizedCryptoTitles
3,621 views
30 Discussing
9
#BitMineFaces$10.1BUnrealizedETHLoss
6,986 views
32 Discussing
10
#StrategyReports$35BNetReserves
3,741 views
24 Discussing