
#aappl
aappl
764 views
8 Discussing
Hot
Latest

Partly True
$AAPL.US
Apple's Biggest Earnings Risk May Not Be Its Products. It's the Valuation.
Apple ($AAPL
{future}(AAPLUSDT)
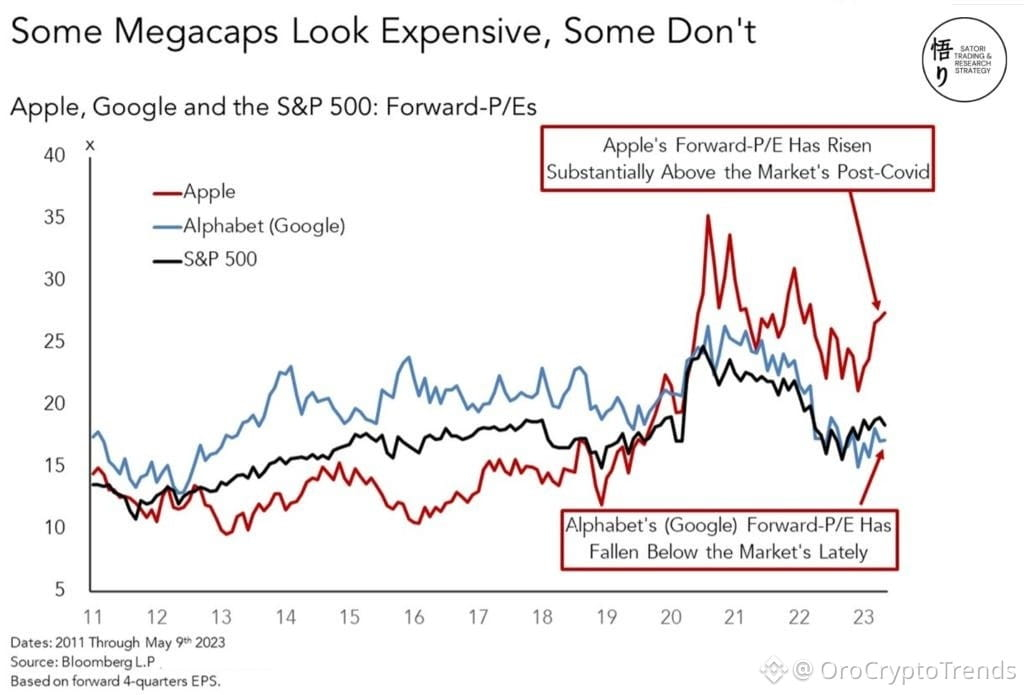
) is trading at roughly 36x forward earnings, nearly twice the S&P 500's valuation. That's a demanding price to defend.
The stock is down 2.18% to $337.29, and the timing matters. Earnings are approaching, but investors aren't just looking for another strong iPhone quarter. They're expecting execution across several fronts.
What caught my attention is the combination of risks.
There are questions around product reliability, including screen and hinge issues. Memory-chip inflation could also pressure gross margins over the next couple of quarters. Then there's the AI narrative, which has raised expectations for Apple's next phase of growth.
Here's my concern: even a decent earnings beat might not be enough.
When a company trades at such a premium, the market starts demanding more than good results. It wants convincing forward guidance, healthy margins and evidence that product execution can support the valuation.
I'll be watching holiday-quarter guidance, memory costs and management's comments on AI-enabled devices.
If those expectations aren't met, Apple's valuation premium could become its biggest vulnerability.
Am I reading this wrong, or is the market demanding too much from Apple?
#AAPPL
Not financial advice. Do your own research.
$AAPL.US
Apple's Biggest Earnings Risk May Not Be Its Products. It's the Valuation.
Apple ($AAPL
) is trading at roughly 36x forward earnings, nearly twice the S&P 500's valuation. That's a demanding price to defend.
The stock is down 2.18% to $337.29, and the timing matters. Earnings are approaching, but investors aren't just looking for another strong iPhone quarter. They're expecting execution across several fronts.
What caught my attention is the combination of risks.
There are questions around product reliability, including screen and hinge issues. Memory-chip inflation could also pressure gross margins over the next couple of quarters. Then there's the AI narrative, which has raised expectations for Apple's next phase of growth.
Here's my concern: even a decent earnings beat might not be enough.
When a company trades at such a premium, the market starts demanding more than good results. It wants convincing forward guidance, healthy margins and evidence that product execution can support the valuation.
I'll be watching holiday-quarter guidance, memory costs and management's comments on AI-enabled devices.
If those expectations aren't met, Apple's valuation premium could become its biggest vulnerability.
Am I reading this wrong, or is the market demanding too much from Apple?
#AAPPL
Not financial advice. Do your own research.
Apple's Biggest Earnings Risk May Not Be Its Products. It's the Valuation.
Apple ($AAPL
) is trading at roughly 36x forward earnings, nearly twice the S&P 500's valuation. That's a demanding price to defend.
The stock is down 2.18% to $337.29, and the timing matters. Earnings are approaching, but investors aren't just looking for another strong iPhone quarter. They're expecting execution across several fronts.
What caught my attention is the combination of risks.
There are questions around product reliability, including screen and hinge issues. Memory-chip inflation could also pressure gross margins over the next couple of quarters. Then there's the AI narrative, which has raised expectations for Apple's next phase of growth.
Here's my concern: even a decent earnings beat might not be enough.
When a company trades at such a premium, the market starts demanding more than good results. It wants convincing forward guidance, healthy margins and evidence that product execution can support the valuation.
I'll be watching holiday-quarter guidance, memory costs and management's comments on AI-enabled devices.
If those expectations aren't met, Apple's valuation premium could become its biggest vulnerability.
Am I reading this wrong, or is the market demanding too much from Apple?
#AAPPL
Not financial advice. Do your own research.
AAPLUS-3.23%
1.1k
#AppleEarningsAhead-CanStockHitNewHigh
$AAPL breaking out! Candle chart confirms *BULLISH BREAKOUT* above 250 resistance on rising volume — classic pre-earnings momentum.
Price at 257.80 (+2.1%) after strong green marubozu candle. Previous resistance at 250 now flipped to support. Higher highs + higher volume since Sep 5 shows accumulation.
*Candle Pattern:* Consolidation 252-255 for 2 weeks, now explosive breakout. No long wicks = buyers in control. If earnings beat Oct 31, next leg up.
*Levels:*
- Support: 250.00 (must hold)
- Target: 265.00 — new ATH zone
- Sentiment: Bullish, RSI 68 strong but not overbought
*Can AAPL hit new high?* Yes, setup is perfect. iPhone 16 sales + Services growth key. But beware — if guidance weak, that big green candle can turn into bearish engulfing fast.
Strategy: Watch 250 support. Hold above = ATH likely.
#AppleEarningsAhead #AAPPL #StockMarket #BinancePick
#AppleEarningsAhead-CanStockHitNewHigh
$AAPL breaking out! Candle chart confirms *BULLISH BREAKOUT* above 250 resistance on rising volume — classic pre-earnings momentum.
Price at 257.80 (+2.1%) after strong green marubozu candle. Previous resistance at 250 now flipped to support. Higher highs + higher volume since Sep 5 shows accumulation.
*Candle Pattern:* Consolidation 252-255 for 2 weeks, now explosive breakout. No long wicks = buyers in control. If earnings beat Oct 31, next leg up.
*Levels:*
- Support: 250.00 (must hold)
- Target: 265.00 — new ATH zone
- Sentiment: Bullish, RSI 68 strong but not overbought
*Can AAPL hit new high?* Yes, setup is perfect. iPhone 16 sales + Services growth key. But beware — if guidance weak, that big green candle can turn into bearish engulfing fast.
Strategy: Watch 250 support. Hold above = ATH likely.
#AppleEarningsAhead #AAPPL #StockMarket #BinancePick
$AAPL breaking out! Candle chart confirms *BULLISH BREAKOUT* above 250 resistance on rising volume — classic pre-earnings momentum.
Price at 257.80 (+2.1%) after strong green marubozu candle. Previous resistance at 250 now flipped to support. Higher highs + higher volume since Sep 5 shows accumulation.
*Candle Pattern:* Consolidation 252-255 for 2 weeks, now explosive breakout. No long wicks = buyers in control. If earnings beat Oct 31, next leg up.
*Levels:*
- Support: 250.00 (must hold)
- Target: 265.00 — new ATH zone
- Sentiment: Bullish, RSI 68 strong but not overbought
*Can AAPL hit new high?* Yes, setup is perfect. iPhone 16 sales + Services growth key. But beware — if guidance weak, that big green candle can turn into bearish engulfing fast.
Strategy: Watch 250 support. Hold above = ATH likely.
#AppleEarningsAhead #AAPPL #StockMarket #BinancePick
165
StockLite_247
·
--
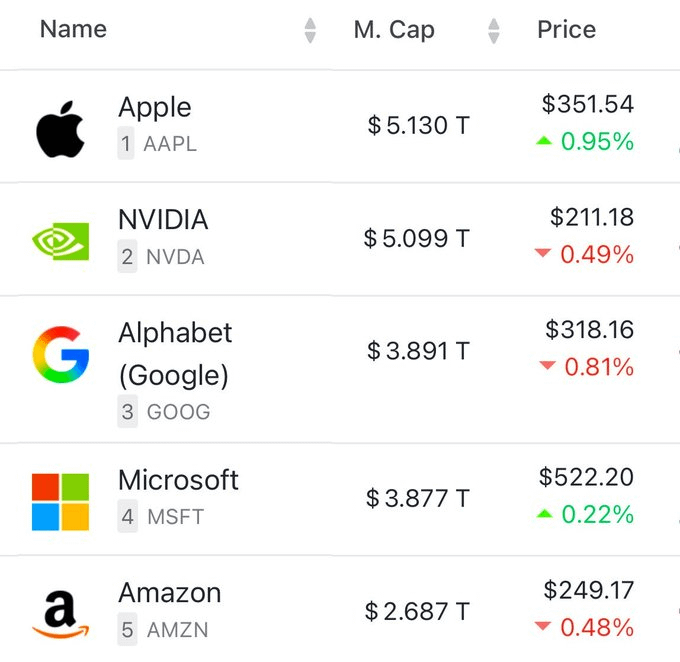
$AAPL just surpassed $NVDA to become the world’s most valuable company.
2
77

·
--
Bullish
wirah
·
--
$AAPL.US
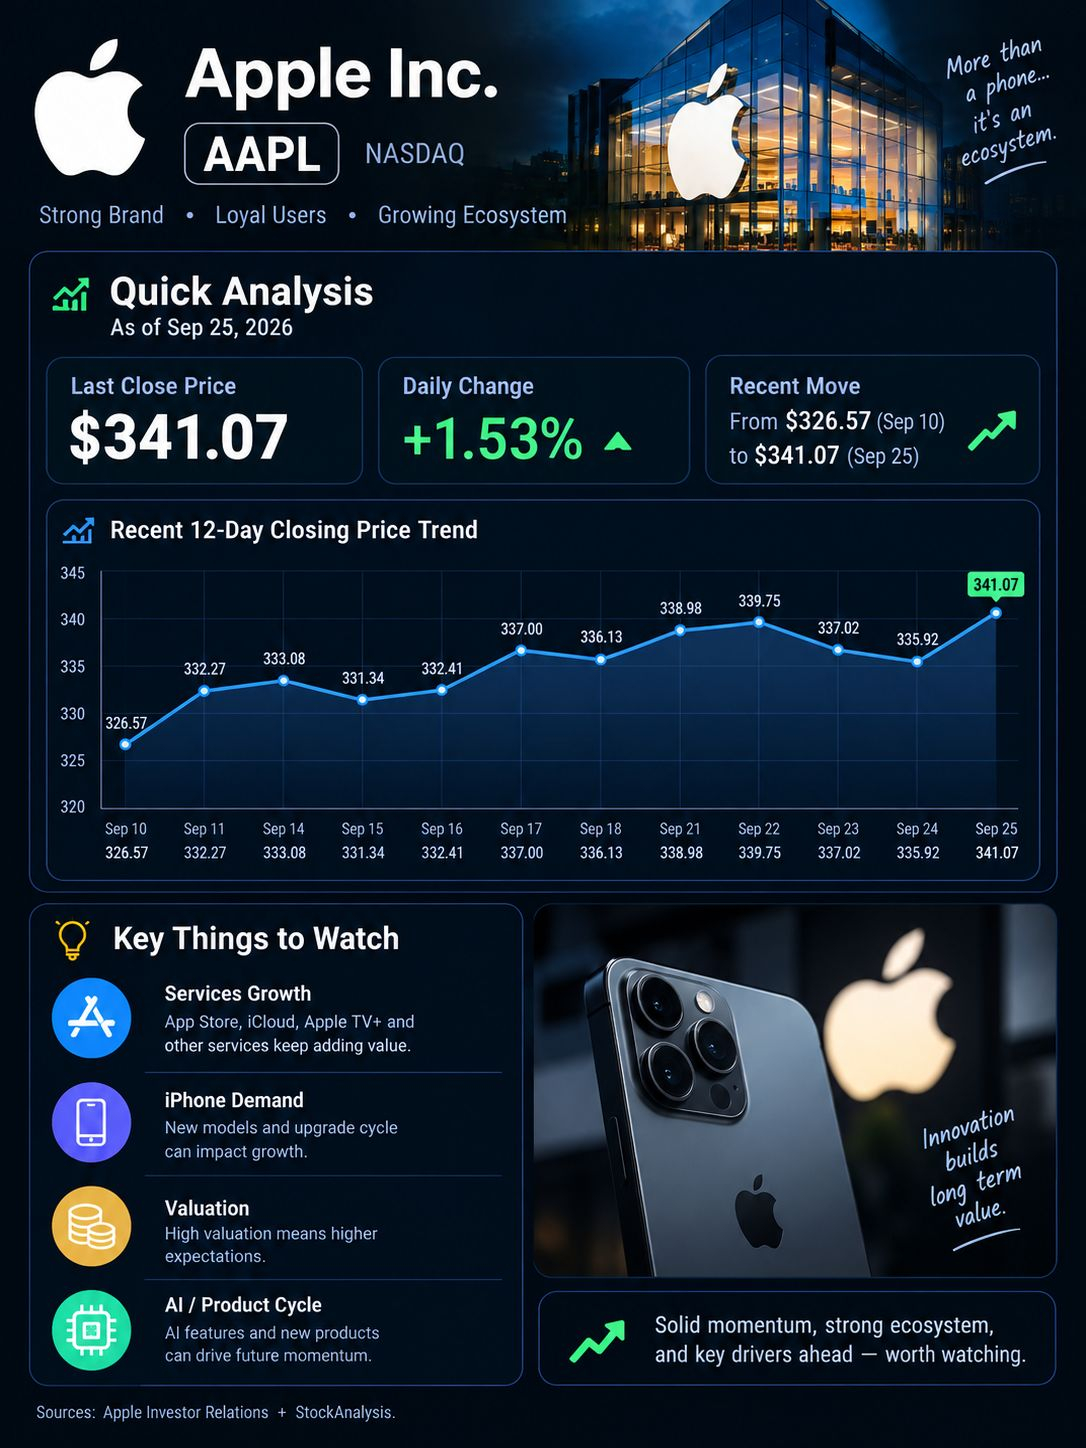
🍎 $AAPL — Apple ka real “hack” sirf iPhone nahi, uska ecosystem hai. Services + loyal users + new products growth ko support karte hain. Recent price action bhi strong raha: $326.57 → $341.07. Lekin valuation high hai, isliye hype ke bajaye numbers aur trend ko watch karna smart hai.#CircleMints500MUSDCOnSolana #BlackRockBuildsTokenizedPortfoliosForOndo #BitwiseFilesToListNEARETFOnNYSEArca
🍎 $AAPL — Apple ka real “hack” sirf iPhone nahi, uska ecosystem hai. Services + loyal users + new products growth ko support karte hain. Recent price action bhi strong raha: $326.57 → $341.07. Lekin valuation high hai, isliye hype ke bajaye numbers aur trend ko watch karna smart hai.#CircleMints500MUSDCOnSolana #BlackRockBuildsTokenizedPortfoliosForOndo #BitwiseFilesToListNEARETFOnNYSEArca
14
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BinanceIncidentReport
91,143 views
842 Discussing
2
#BinanceReopensWithdrawalsForMoreAssets
226,341 views
1,971 Discussing
3
#BinanceHourlyDepositsExceedWithdrawals
101,725 views
942 Discussing
4
#BhutanGelephuCentralBankCanHoldBitcoinReserves
13 views
5 Discussing
5
#MorganStanleyAmongFirstBanksToUseDTCCTokenization
0 views
6 Discussing
6
#NasdaqRises0.8%AsChipStocksRebound
9 views
5 Discussing
7
#USMidtermElections
992,019 views
4,833 Discussing
8
#AnthropicIPOPricedDownasInvestorsEye$1.5T
5,886 views
67 Discussing
9
#USOctoberNFP-AreRateCutsStillPossible
186,650 views
1,389 Discussing
10
#AppleReportsMixedResults
87,166 views
1,034 Discussing