
大晖哥Whdysseus
1.1k Posts
大晖哥Whdysseus
Report
Block User
X@Whdysseus|1783DAO和博链BroadChain创始人|Crypto Since 2014|二级市场投研与行业研究|币安全球区块链百强创作者入围|原证券/基金从业者|关注Crypto、美股、港股、全球科技与新兴产业|香港|新加坡|东京|首尔|迪拜|阿布扎比…

原创之星
Frequent Trader
8.8 Years
101 Following
2.2K+ Followers
3.1K+ Liked
1 Badges
Posts
All
Quotes
Videos
Live
PINNED
PINNED
·
--
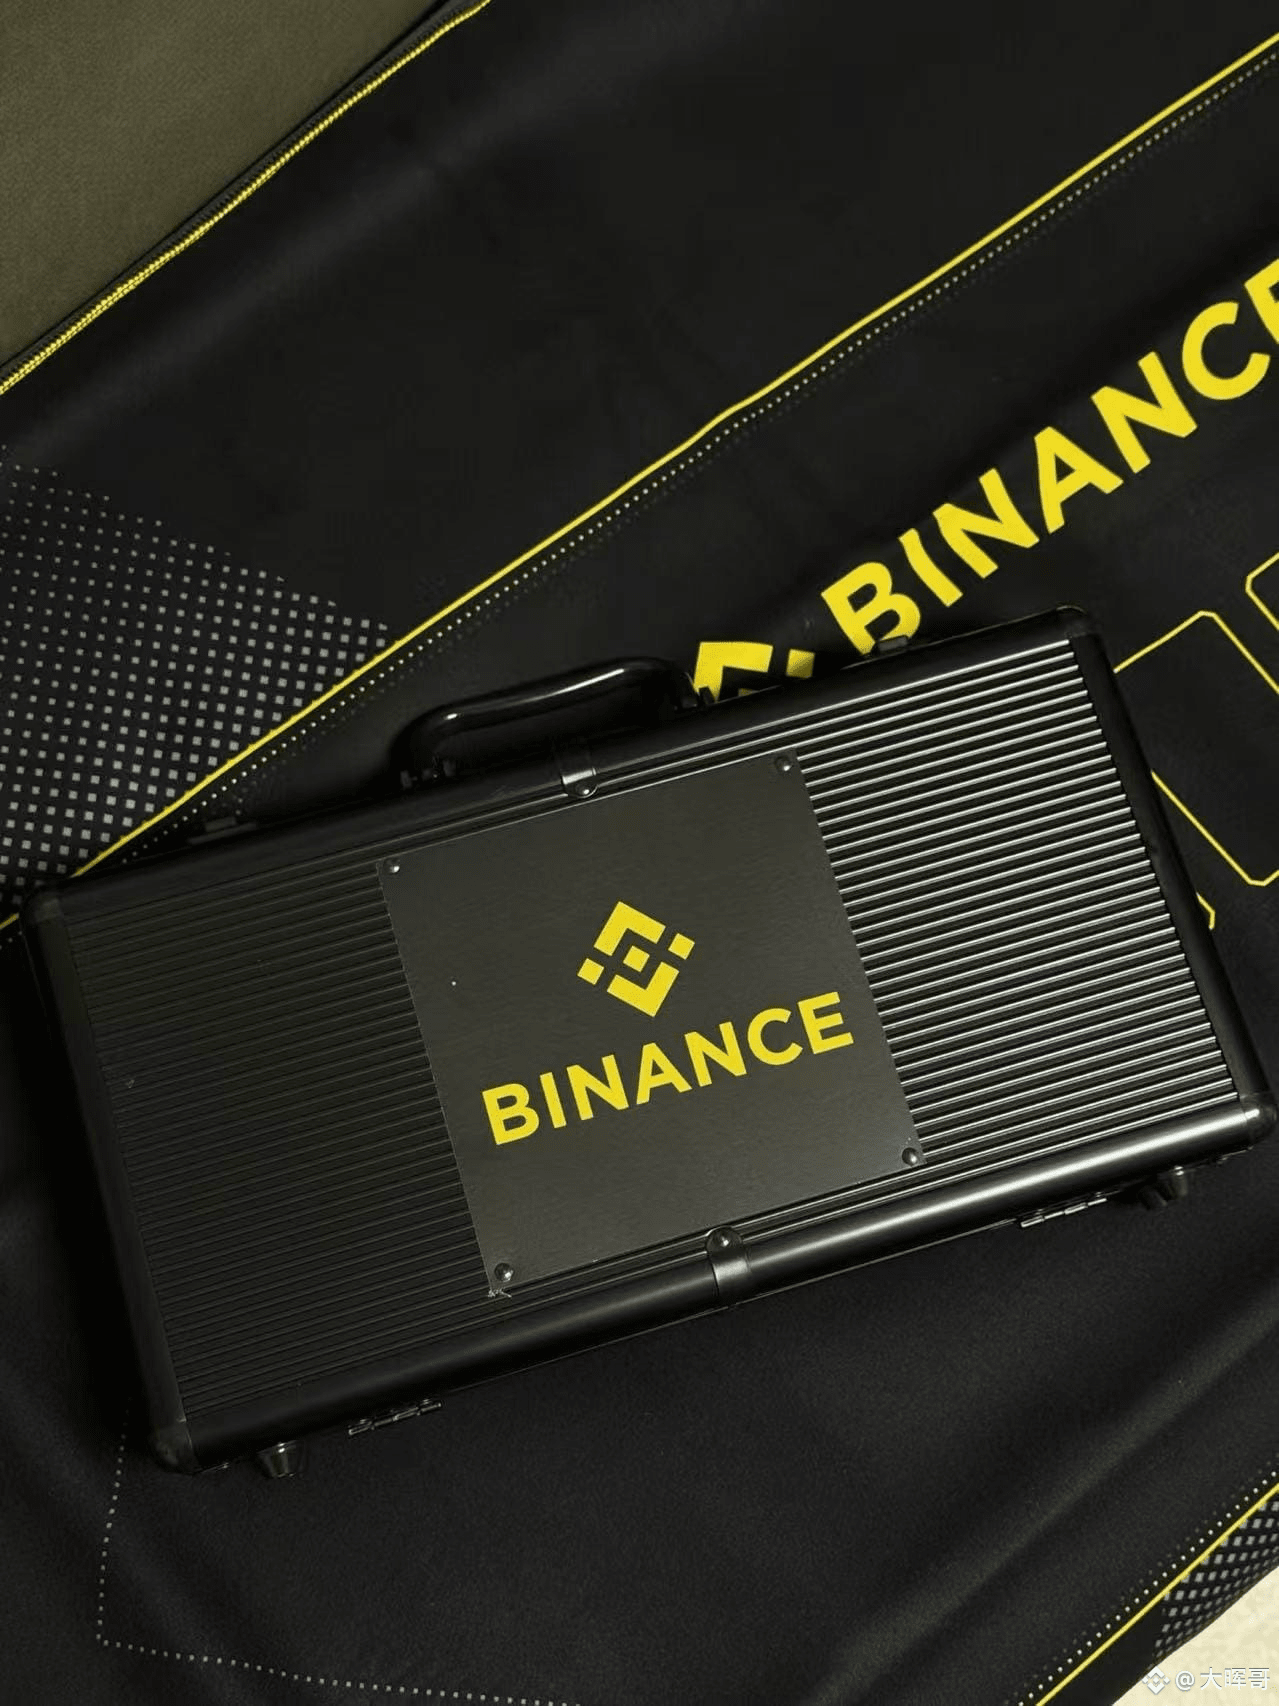
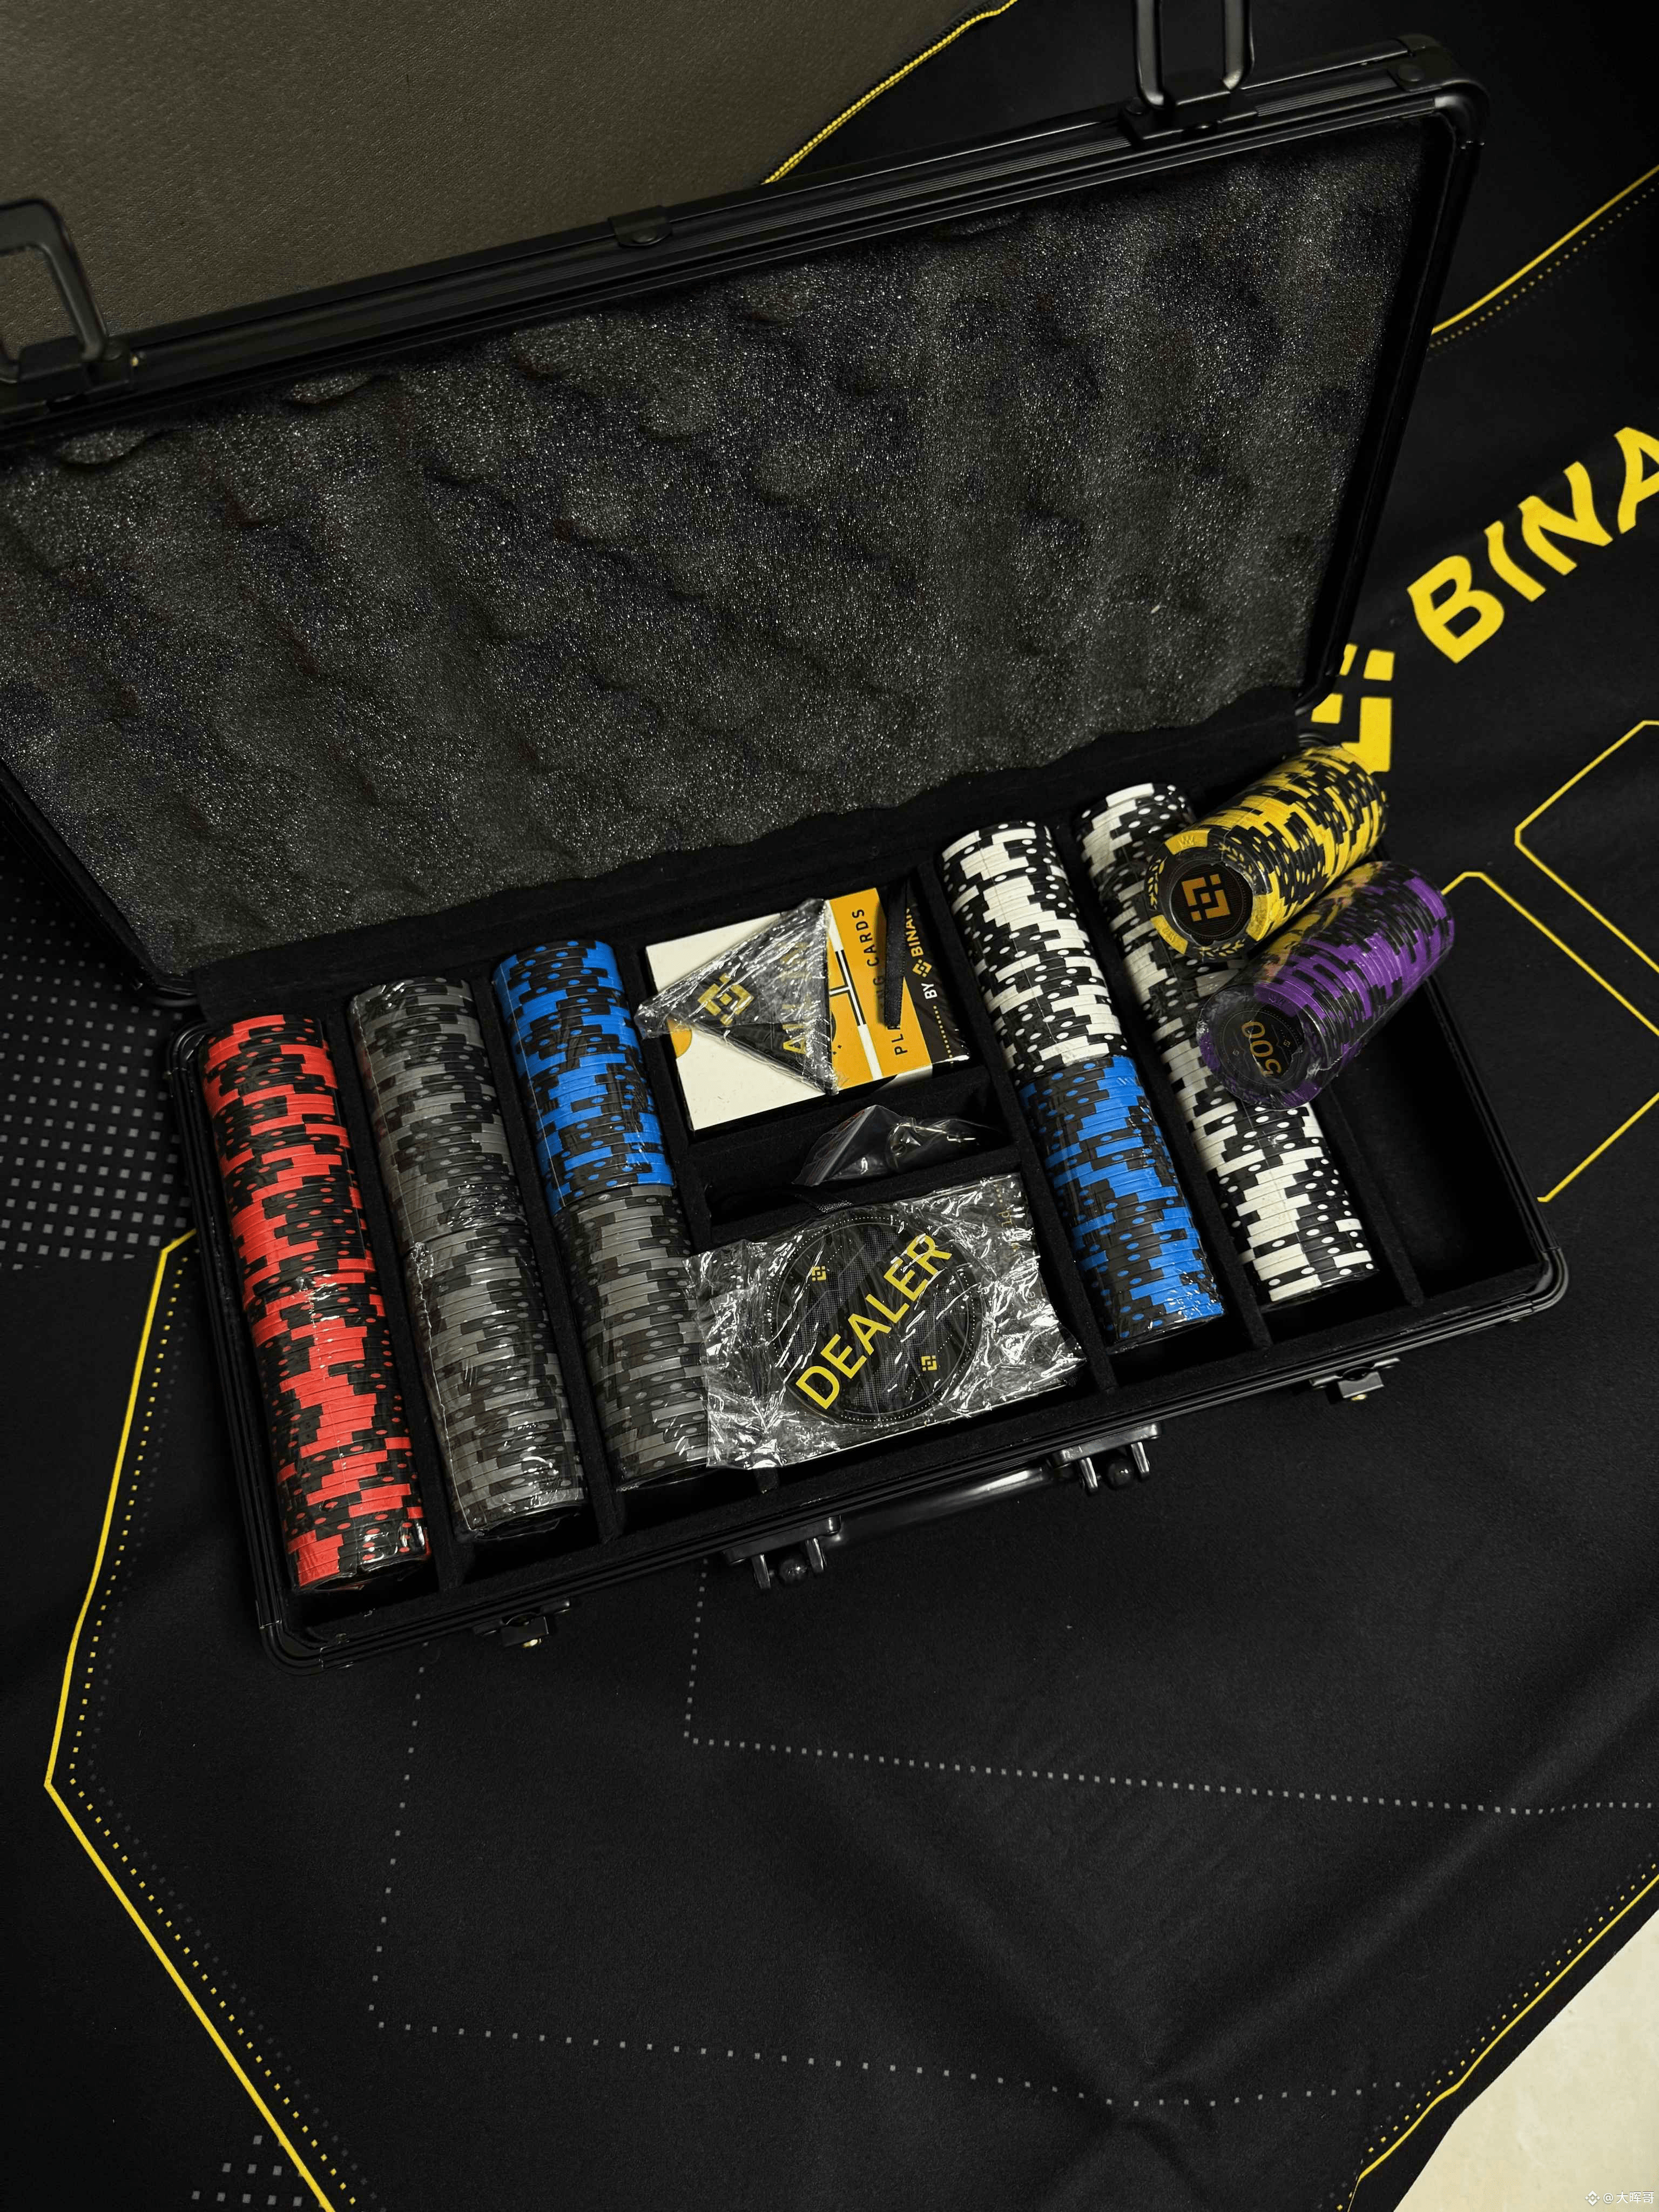
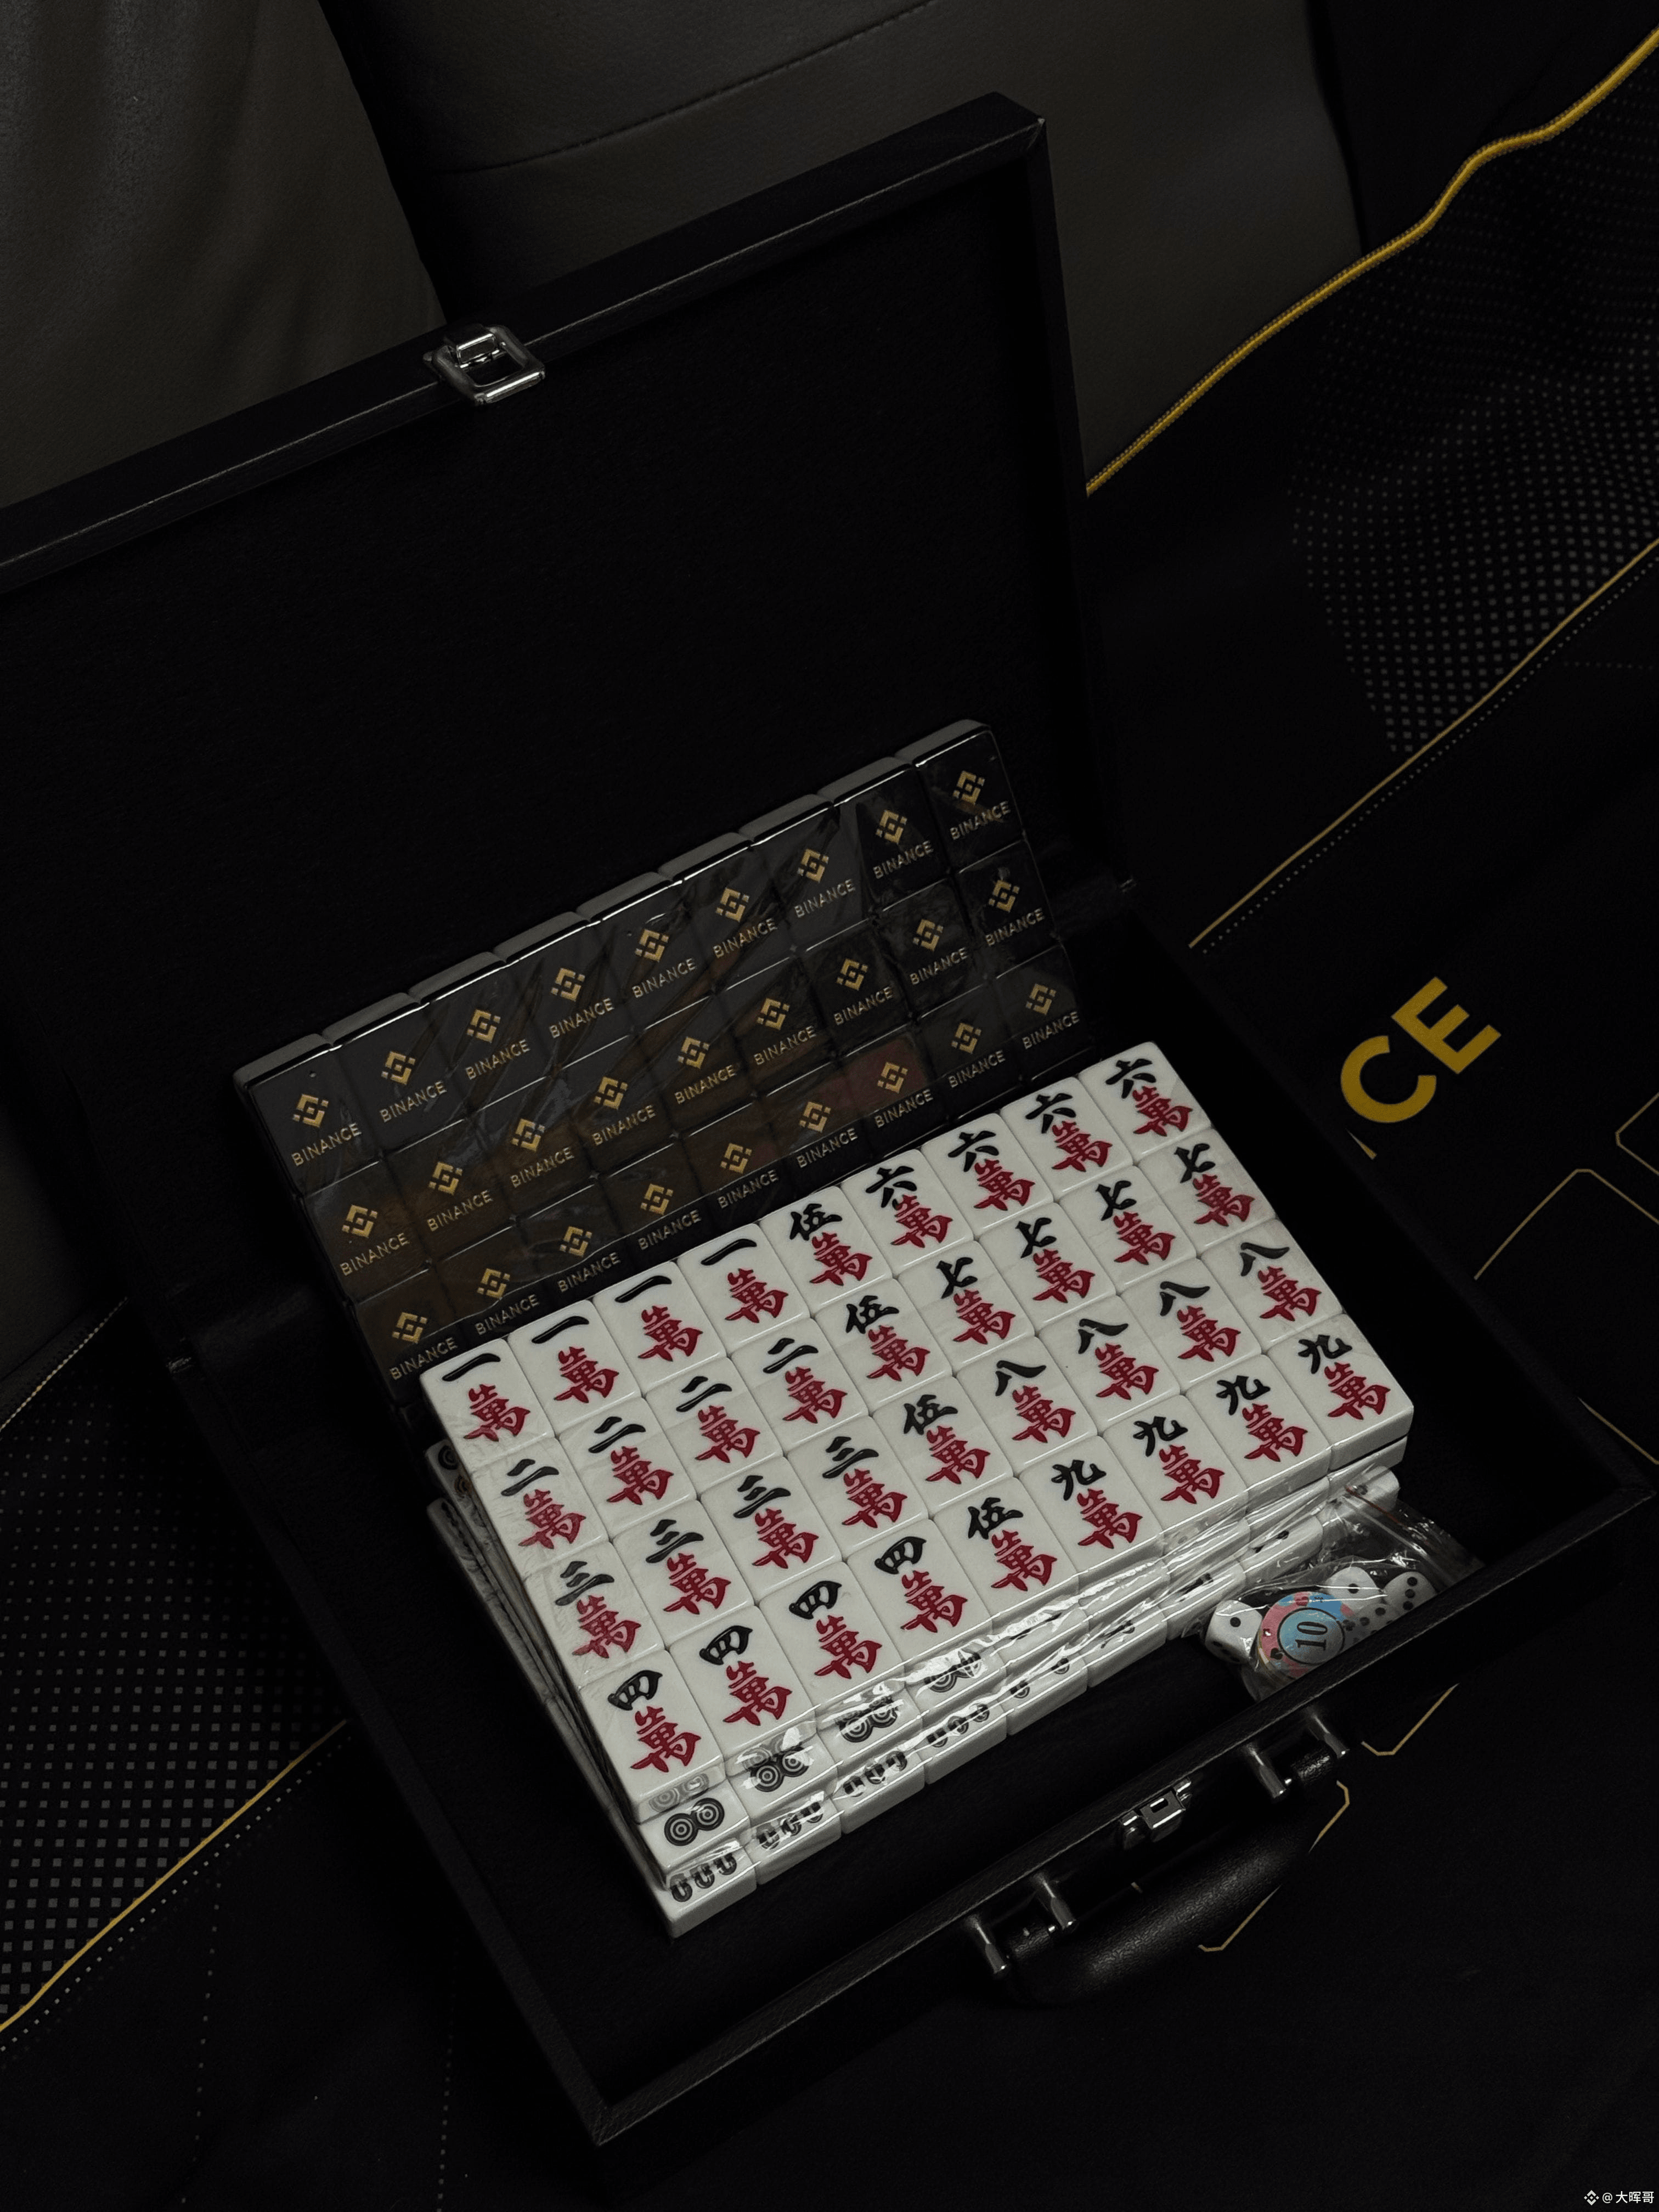
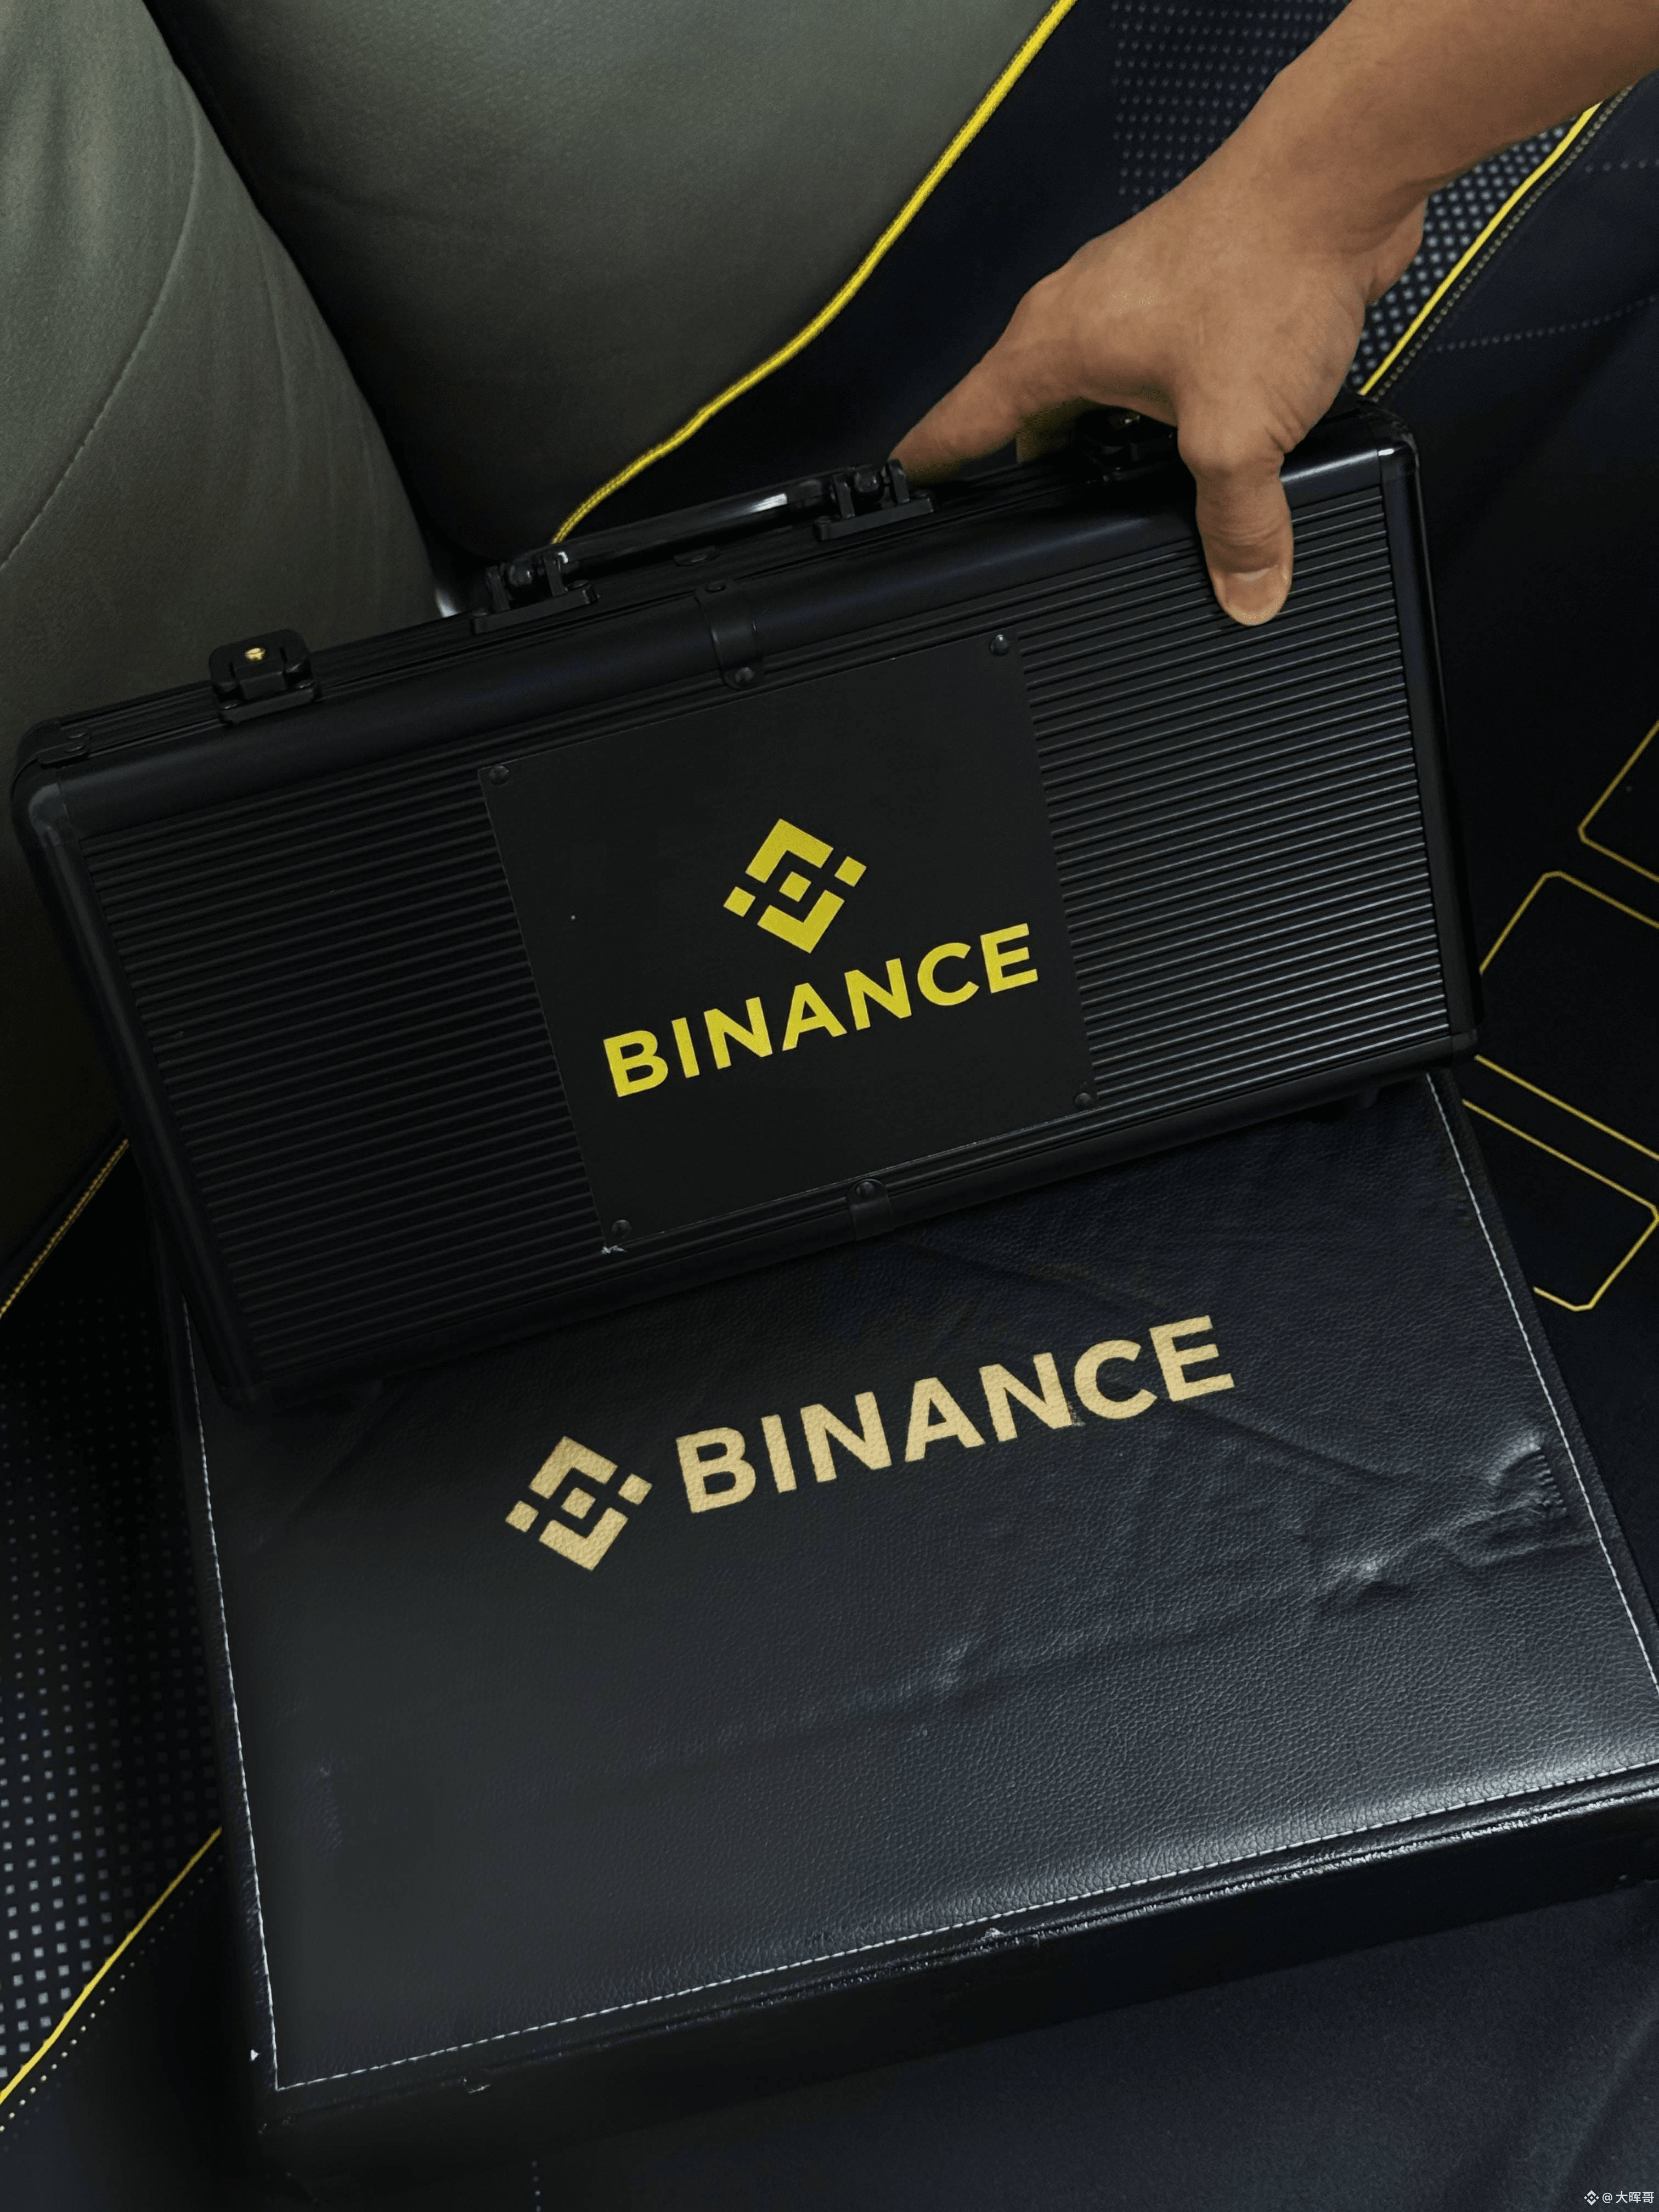
Binance VIP 9 Customer Exclusive
Global Limited Edition of 50 Sets
Texas + Mahjong Set
The family of 1783DAO is so powerful
Binance VIP 9 Customer Exclusive
Global Limited Edition of 50 Sets
Texas + Mahjong Set
The family of 1783DAO is so powerful
Global Limited Edition of 50 Sets
Texas + Mahjong Set
The family of 1783DAO is so powerful
39
11
102
38.4k
·
--
In the U.S. midterm elections, the biggest loser may well be Musk.
He poured in money, effort, and publicity, throwing his full support behind Trump and the Republican Party.
Musk is expected to have spent about $446 million this election cycle. But Trump and the Republicans suffered a crushing defeat, with Democrats sweeping both the House and the Senate.
The money was spent, but the election was lost. So who’s happiest?
Don’t forget another old fox on Wall Street: Soros.
The longtime Democratic supporter and financial mogul also invested about $100 million this cycle.
One poured in over $400 million, the other about $100 million, yet the political outcomes were worlds apart.
But this time, at least one thing is clear: the world’s richest person can buy many things—but not a guaranteed election result.
In the U.S. midterm elections, the biggest loser may well be Musk.
He poured in money, effort, and publicity, throwing his full support behind Trump and the Republican Party.
Musk is expected to have spent about $446 million this election cycle. But Trump and the Republicans suffered a crushing defeat, with Democrats sweeping both the House and the Senate.
The money was spent, but the election was lost. So who’s happiest?
Don’t forget another old fox on Wall Street: Soros.
The longtime Democratic supporter and financial mogul also invested about $100 million this cycle.
One poured in over $400 million, the other about $100 million, yet the political outcomes were worlds apart.
But this time, at least one thing is clear: the world’s richest person can buy many things—but not a guaranteed election result.
He poured in money, effort, and publicity, throwing his full support behind Trump and the Republican Party.
Musk is expected to have spent about $446 million this election cycle. But Trump and the Republicans suffered a crushing defeat, with Democrats sweeping both the House and the Senate.
The money was spent, but the election was lost. So who’s happiest?
Don’t forget another old fox on Wall Street: Soros.
The longtime Democratic supporter and financial mogul also invested about $100 million this cycle.
One poured in over $400 million, the other about $100 million, yet the political outcomes were worlds apart.
But this time, at least one thing is clear: the world’s richest person can buy many things—but not a guaranteed election result.
1
3.7k
·
--
As of September 30, Circle holds
380 million CC, worth approximately $47.99 million
504,000 HYPE, worth approximately $45.88 million
77 BTC, worth approximately $6.39 million
4.1 million SUI, worth approximately $4.77 million
1,728 ETH, worth approximately $4.64 million
As of September 30, Circle holds
380 million CC, worth approximately $47.99 million
504,000 HYPE, worth approximately $45.88 million
77 BTC, worth approximately $6.39 million
4.1 million SUI, worth approximately $4.77 million
1,728 ETH, worth approximately $4.64 million
380 million CC, worth approximately $47.99 million
504,000 HYPE, worth approximately $45.88 million
77 BTC, worth approximately $6.39 million
4.1 million SUI, worth approximately $4.77 million
1,728 ETH, worth approximately $4.64 million
2.1k
·
--
Trump lost Congress, and Trump-related assets took a hit too.
In the U.S. midterm elections, Democrats won control of both the House and the Senate.
Trump acknowledged that the war with Iran was one reason Republicans lost, but said he had no regrets.
The market reaction was more direct:
Trump Media & Technology Group fell more than 11%, Tesla dropped 4.76%, the TRUMP token fell about 11%, and WLFI also came under pressure.
Of course, the decline in these assets wasn’t entirely caused by the election.
But one question is increasingly worth taking seriously:
When a company’s valuation or a token’s narrative is too closely tied to a political figure, the election itself becomes a risk event.
In the past, people bought into Trump-related assets to trade on his political influence.
Now they may need to reassess the political risk.
Politics can give assets a premium—and make it disappear overnight.
Going forward, the Trump family’s crypto ventures may be worth watching even more closely than the broader market.
Trump lost Congress, and Trump-related assets took a hit too.
In the U.S. midterm elections, Democrats won control of both the House and the Senate.
Trump acknowledged that the war with Iran was one reason Republicans lost, but said he had no regrets.
The market reaction was more direct:
Trump Media & Technology Group fell more than 11%, Tesla dropped 4.76%, the TRUMP token fell about 11%, and WLFI also came under pressure.
Of course, the decline in these assets wasn’t entirely caused by the election.
But one question is increasingly worth taking seriously:
When a company’s valuation or a token’s narrative is too closely tied to a political figure, the election itself becomes a risk event.
In the past, people bought into Trump-related assets to trade on his political influence.
Now they may need to reassess the political risk.
Politics can give assets a premium—and make it disappear overnight.
Going forward, the Trump family’s crypto ventures may be worth watching even more closely than the broader market.
In the U.S. midterm elections, Democrats won control of both the House and the Senate.
Trump acknowledged that the war with Iran was one reason Republicans lost, but said he had no regrets.
The market reaction was more direct:
Trump Media & Technology Group fell more than 11%, Tesla dropped 4.76%, the TRUMP token fell about 11%, and WLFI also came under pressure.
Of course, the decline in these assets wasn’t entirely caused by the election.
But one question is increasingly worth taking seriously:
When a company’s valuation or a token’s narrative is too closely tied to a political figure, the election itself becomes a risk event.
In the past, people bought into Trump-related assets to trade on his political influence.
Now they may need to reassess the political risk.
Politics can give assets a premium—and make it disappear overnight.
Going forward, the Trump family’s crypto ventures may be worth watching even more closely than the broader market.
1
3.9k
·
--
Circle’s Q3 2026 financial results: stablecoin interest income fell, while a presale of ARC tokens helped boost performance.
Q3 2026:
Total revenue: $865 million, up 17%
Net income: $226 million, up 5%
Adjusted EBITDA: $317 million, up 85%
USDC reserve income: $658 million, down 8%
Most notably, other revenue totaled $207 million, of which $182 million came from the ARC token presale. That was equivalent to 21% of total revenue for the quarter.
Circle is transforming from a company that earns interest on stablecoin reserves into a provider of public blockchain, payments, and on-chain financial infrastructure.
Token sales can generate a one-time revenue boost, but long-term valuation ultimately depends on the ability to generate sustained earnings.
The three key metrics to watch going forward are USDC circulation, payments revenue, and actual usage of the Arc ecosystem.
Circle’s Q3 2026 financial results: stablecoin interest income fell, while a presale of ARC tokens helped boost performance.
Q3 2026:
Total revenue: $865 million, up 17%
Net income: $226 million, up 5%
Adjusted EBITDA: $317 million, up 85%
USDC reserve income: $658 million, down 8%
Most notably, other revenue totaled $207 million, of which $182 million came from the ARC token presale. That was equivalent to 21% of total revenue for the quarter.
Circle is transforming from a company that earns interest on stablecoin reserves into a provider of public blockchain, payments, and on-chain financial infrastructure.
Token sales can generate a one-time revenue boost, but long-term valuation ultimately depends on the ability to generate sustained earnings.
The three key metrics to watch going forward are USDC circulation, payments revenue, and actual usage of the Arc ecosystem.
Q3 2026:
Total revenue: $865 million, up 17%
Net income: $226 million, up 5%
Adjusted EBITDA: $317 million, up 85%
USDC reserve income: $658 million, down 8%
Most notably, other revenue totaled $207 million, of which $182 million came from the ARC token presale. That was equivalent to 21% of total revenue for the quarter.
Circle is transforming from a company that earns interest on stablecoin reserves into a provider of public blockchain, payments, and on-chain financial infrastructure.
Token sales can generate a one-time revenue boost, but long-term valuation ultimately depends on the ability to generate sustained earnings.
The three key metrics to watch going forward are USDC circulation, payments revenue, and actual usage of the Arc ecosystem.
107
·
--
Anthropic’s IPO website is live. The AI giant is finally about to let retail investors around the world get in on the action.
The website is extremely simple, with just three circles and a single line:
More information to come.
On October 26, Anthropic officially filed its IPO prospectus, planning to list on Nasdaq under the ticker ANT.
This offering won’t be limited to U.S. investors. It is also planned to include Japan, the U.K., Canada, Australia, and some European markets.
Japanese regulatory filings indicate that the offering to local investors could be worth up to about $3.5 billion.
The latest prospectus shows revenue of about $17 billion in the third quarter of 2026, while the company still posted a loss of about $23.3 billion over the same period.
That’s what’s most surreal about the AI industry:
Revenue is growing at a staggering pace, and so is the rate at which money is being burned.
Now the capital markets face a more practical question:
What is an AI company that could change the world actually worth?
A technological revolution can be real without making every purchase at any price profitable.
Anthropic’s upcoming IPO could become an important stress test for the valuation of AI assets worldwide.
Anthropic’s IPO website is live. The AI giant is finally about to let retail investors around the world get in on the action.
The website is extremely simple, with just three circles and a single line:
More information to come.
On October 26, Anthropic officially filed its IPO prospectus, planning to list on Nasdaq under the ticker ANT.
This offering won’t be limited to U.S. investors. It is also planned to include Japan, the U.K., Canada, Australia, and some European markets.
Japanese regulatory filings indicate that the offering to local investors could be worth up to about $3.5 billion.
The latest prospectus shows revenue of about $17 billion in the third quarter of 2026, while the company still posted a loss of about $23.3 billion over the same period.
That’s what’s most surreal about the AI industry:
Revenue is growing at a staggering pace, and so is the rate at which money is being burned.
Now the capital markets face a more practical question:
What is an AI company that could change the world actually worth?
A technological revolution can be real without making every purchase at any price profitable.
Anthropic’s upcoming IPO could become an important stress test for the valuation of AI assets worldwide.
The website is extremely simple, with just three circles and a single line:
More information to come.
On October 26, Anthropic officially filed its IPO prospectus, planning to list on Nasdaq under the ticker ANT.
This offering won’t be limited to U.S. investors. It is also planned to include Japan, the U.K., Canada, Australia, and some European markets.
Japanese regulatory filings indicate that the offering to local investors could be worth up to about $3.5 billion.
The latest prospectus shows revenue of about $17 billion in the third quarter of 2026, while the company still posted a loss of about $23.3 billion over the same period.
That’s what’s most surreal about the AI industry:
Revenue is growing at a staggering pace, and so is the rate at which money is being burned.
Now the capital markets face a more practical question:
What is an AI company that could change the world actually worth?
A technological revolution can be real without making every purchase at any price profitable.
Anthropic’s upcoming IPO could become an important stress test for the valuation of AI assets worldwide.
298
·
--
Can you believe it? The world’s largest exchange, Binance, lost $6.3 billion—and got taken down by a “fake job interview”?
The details of the biggest crypto theft in history are out.
The hackers didn’t use any high-tech methods to break through its defenses. Instead, they started laying the groundwork back in June 2026, setting up fake job openings and interviews. Posing as HR staff or interviewers, they sent links containing malware and hacked straight into Binance engineers’ computers!
The whole thing is utterly surreal and ironic:
A top tech company spent a fortune on security systems and audited its smart contracts countless times, only to have its own backyard breached using the most old-fashioned “phone scam” tactics.
It’s a wake-up call for everyone:
1. As long as there are people in a system, there are vulnerabilities.
2. With AI technology so advanced these days, AI face swaps and fake video calls are incredibly hard to guard against.
DeFi fears bugs in the code; CEX fears employees clicking the wrong links.
Can you believe it? The world’s largest exchange, Binance, lost $6.3 billion—and got taken down by a “fake job interview”?
The details of the biggest crypto theft in history are out.
The hackers didn’t use any high-tech methods to break through its defenses. Instead, they started laying the groundwork back in June 2026, setting up fake job openings and interviews. Posing as HR staff or interviewers, they sent links containing malware and hacked straight into Binance engineers’ computers!
The whole thing is utterly surreal and ironic:
A top tech company spent a fortune on security systems and audited its smart contracts countless times, only to have its own backyard breached using the most old-fashioned “phone scam” tactics.
It’s a wake-up call for everyone:
1. As long as there are people in a system, there are vulnerabilities.
2. With AI technology so advanced these days, AI face swaps and fake video calls are incredibly hard to guard against.
DeFi fears bugs in the code; CEX fears employees clicking the wrong links.
The details of the biggest crypto theft in history are out.
The hackers didn’t use any high-tech methods to break through its defenses. Instead, they started laying the groundwork back in June 2026, setting up fake job openings and interviews. Posing as HR staff or interviewers, they sent links containing malware and hacked straight into Binance engineers’ computers!
The whole thing is utterly surreal and ironic:
A top tech company spent a fortune on security systems and audited its smart contracts countless times, only to have its own backyard breached using the most old-fashioned “phone scam” tactics.
It’s a wake-up call for everyone:
1. As long as there are people in a system, there are vulnerabilities.
2. With AI technology so advanced these days, AI face swaps and fake video calls are incredibly hard to guard against.
DeFi fears bugs in the code; CEX fears employees clicking the wrong links.
2
1.1k
·
--
Verified
Major good news—Trump is changing his tune so fast even Wall Street can’t keep up.
After Republicans suffered a major setback in the U.S. midterm elections, Trump told The New York Times that he was willing to accept the election results and was also prepared to work with Democrats. The two sides might be able to reach some agreements.
At the same time, he stressed on social media: “I’m not on the ballot. If I were, we’d win by a landslide!”
A familiar line: when the election goes badly, it can’t all be my fault.
And when it comes to negotiations, everyone can share the credit.
But there’s another thing Xiaohuihui is more concerned about when it comes to the financial markets:
If the U.S. ends up with a divided government, Trump’s fiscal, tax, and regulatory agenda over the next two years could face more congressional checks and balances.
That could lead to policy gridlock, but it could also push the two parties to compromise on some issues.
Elections are elections, business is business.
Trump never admits defeat, but when it comes to deals that need to be made, he still has to negotiate.
Major good news—Trump is changing his tune so fast even Wall Street can’t keep up.
After Republicans suffered a major setback in the U.S. midterm elections, Trump told The New York Times that he was willing to accept the election results and was also prepared to work with Democrats. The two sides might be able to reach some agreements.
At the same time, he stressed on social media: “I’m not on the ballot. If I were, we’d win by a landslide!”
A familiar line: when the election goes badly, it can’t all be my fault.
And when it comes to negotiations, everyone can share the credit.
But there’s another thing Xiaohuihui is more concerned about when it comes to the financial markets:
If the U.S. ends up with a divided government, Trump’s fiscal, tax, and regulatory agenda over the next two years could face more congressional checks and balances.
That could lead to policy gridlock, but it could also push the two parties to compromise on some issues.
Elections are elections, business is business.
Trump never admits defeat, but when it comes to deals that need to be made, he still has to negotiate.
After Republicans suffered a major setback in the U.S. midterm elections, Trump told The New York Times that he was willing to accept the election results and was also prepared to work with Democrats. The two sides might be able to reach some agreements.
At the same time, he stressed on social media: “I’m not on the ballot. If I were, we’d win by a landslide!”
A familiar line: when the election goes badly, it can’t all be my fault.
And when it comes to negotiations, everyone can share the credit.
But there’s another thing Xiaohuihui is more concerned about when it comes to the financial markets:
If the U.S. ends up with a divided government, Trump’s fiscal, tax, and regulatory agenda over the next two years could face more congressional checks and balances.
That could lead to policy gridlock, but it could also push the two parties to compromise on some issues.
Elections are elections, business is business.
Trump never admits defeat, but when it comes to deals that need to be made, he still has to negotiate.
10
9
38.1k
·
--
Musk bet on Texas for five years, never expecting the state’s governor to switch parties first.
In 2021, Tesla moved its headquarters from California to Austin, Texas.
In 2024, SpaceX and X also announced, one after another, that they would move their headquarters to Texas.
Low taxes, a relatively relaxed regulatory environment, and abundant energy and land resources have gradually made Texas the home base of Musk’s business empire.
Then came a major upset in the 2026 U.S. midterm elections:
Democrat Gina Hinojosa defeated incumbent Republican Governor Greg Abbott.
After 32 years, Democrats reclaimed the Texas governorship.
More interestingly, during her campaign, Hinojosa also raised concerns about AI data centers’ energy consumption and the cost of living for residents.
Texas has long attracted investment through its energy, manufacturing, and tech industries. Now, local voters are taking another look at the costs and benefits of economic growth.
Of course, a change of governor doesn’t mean Texas will immediately change its business policies.
But this election shows at least one thing: companies can vote with their feet, and capital can choose where to settle, but ultimately, it’s voters who decide the direction of local politics.
The next chapter in Musk’s Texas story could get even more interesting.
Musk bet on Texas for five years, never expecting the state’s governor to switch parties first.
In 2021, Tesla moved its headquarters from California to Austin, Texas.
In 2024, SpaceX and X also announced, one after another, that they would move their headquarters to Texas.
Low taxes, a relatively relaxed regulatory environment, and abundant energy and land resources have gradually made Texas the home base of Musk’s business empire.
Then came a major upset in the 2026 U.S. midterm elections:
Democrat Gina Hinojosa defeated incumbent Republican Governor Greg Abbott.
After 32 years, Democrats reclaimed the Texas governorship.
More interestingly, during her campaign, Hinojosa also raised concerns about AI data centers’ energy consumption and the cost of living for residents.
Texas has long attracted investment through its energy, manufacturing, and tech industries. Now, local voters are taking another look at the costs and benefits of economic growth.
Of course, a change of governor doesn’t mean Texas will immediately change its business policies.
But this election shows at least one thing: companies can vote with their feet, and capital can choose where to settle, but ultimately, it’s voters who decide the direction of local politics.
The next chapter in Musk’s Texas story could get even more interesting.
In 2021, Tesla moved its headquarters from California to Austin, Texas.
In 2024, SpaceX and X also announced, one after another, that they would move their headquarters to Texas.
Low taxes, a relatively relaxed regulatory environment, and abundant energy and land resources have gradually made Texas the home base of Musk’s business empire.
Then came a major upset in the 2026 U.S. midterm elections:
Democrat Gina Hinojosa defeated incumbent Republican Governor Greg Abbott.
After 32 years, Democrats reclaimed the Texas governorship.
More interestingly, during her campaign, Hinojosa also raised concerns about AI data centers’ energy consumption and the cost of living for residents.
Texas has long attracted investment through its energy, manufacturing, and tech industries. Now, local voters are taking another look at the costs and benefits of economic growth.
Of course, a change of governor doesn’t mean Texas will immediately change its business policies.
But this election shows at least one thing: companies can vote with their feet, and capital can choose where to settle, but ultimately, it’s voters who decide the direction of local politics.
The next chapter in Musk’s Texas story could get even more interesting.
3
3
7.2k
·
--
In the U.S. midterm elections, Wall Street may have more to focus on next than just the Federal Reserve: Congress.
According to the latest vote count, results have been called in 154 House races:
102 seats for the Democrats and 52 for the Republicans.
The Democrats have flipped a net 5 seats. Election forecaster DDHQ has also predicted that the Democrats will retake control of the House.
But keep in mind that the House has 435 seats, and 218 are needed for a majority. Many races are still too close to call.
Xiaohuihui is more focused on how this election will affect the capital markets.
If the Republicans lose control of the House, the Trump administration may face more complicated negotiations in Congress as it pursues tax and spending policies and parts of its legislative agenda.
But that doesn't mean U.S. stocks are bound to fall.
Historically, markets have also risen during periods of divided government.
For investors, the questions that really matter are:
1. Will fiscal policy change?
2. Will legislation on AI, technology, and crypto regulation continue to move forward?
3. Will budget and debt negotiations add to market volatility?
Elections determine who holds power, but what markets ultimately trade on is how policy changes affect corporate profits and the flow of capital.
What matters more to watch next than guessing which party will win is whether the two parties can reach agreement on key economic policies.
In the U.S. midterm elections, Wall Street may have more to focus on next than just the Federal Reserve: Congress.
According to the latest vote count, results have been called in 154 House races:
102 seats for the Democrats and 52 for the Republicans.
The Democrats have flipped a net 5 seats. Election forecaster DDHQ has also predicted that the Democrats will retake control of the House.
But keep in mind that the House has 435 seats, and 218 are needed for a majority. Many races are still too close to call.
Xiaohuihui is more focused on how this election will affect the capital markets.
If the Republicans lose control of the House, the Trump administration may face more complicated negotiations in Congress as it pursues tax and spending policies and parts of its legislative agenda.
But that doesn't mean U.S. stocks are bound to fall.
Historically, markets have also risen during periods of divided government.
For investors, the questions that really matter are:
1. Will fiscal policy change?
2. Will legislation on AI, technology, and crypto regulation continue to move forward?
3. Will budget and debt negotiations add to market volatility?
Elections determine who holds power, but what markets ultimately trade on is how policy changes affect corporate profits and the flow of capital.
What matters more to watch next than guessing which party will win is whether the two parties can reach agreement on key economic policies.
According to the latest vote count, results have been called in 154 House races:
102 seats for the Democrats and 52 for the Republicans.
The Democrats have flipped a net 5 seats. Election forecaster DDHQ has also predicted that the Democrats will retake control of the House.
But keep in mind that the House has 435 seats, and 218 are needed for a majority. Many races are still too close to call.
Xiaohuihui is more focused on how this election will affect the capital markets.
If the Republicans lose control of the House, the Trump administration may face more complicated negotiations in Congress as it pursues tax and spending policies and parts of its legislative agenda.
But that doesn't mean U.S. stocks are bound to fall.
Historically, markets have also risen during periods of divided government.
For investors, the questions that really matter are:
1. Will fiscal policy change?
2. Will legislation on AI, technology, and crypto regulation continue to move forward?
3. Will budget and debt negotiations add to market volatility?
Elections determine who holds power, but what markets ultimately trade on is how policy changes affect corporate profits and the flow of capital.
What matters more to watch next than guessing which party will win is whether the two parties can reach agreement on key economic policies.
3
8k
·
--
Article
Aave lays it out to the SEC: DeFi is not a bank and should not be treated as a securities issuerAave is pushing for something that could change the entire DeFi industry.
On November 3, Aave Labs, together with Kamino and Veda, publicly released a legal framework submitted to the U.S. SEC.
The core argument is intriguing:
Decentralized lending protocols should not be regulated as securities issuers or traditional financial intermediaries.
Moreover, they are not asking the SEC for special exemptions for DeFi. Rather, they argue that under existing securities laws, qualifying decentralized lending should not be considered securities transactions in the first place.
A few key points:
Users depositing assets into a lending market is not the same as entrusting money to a company to invest, and there is no promise of returns in the traditional sense.
Aave lays it out to the SEC: DeFi is not a bank and should not be treated as a securities issuer
Aave is pushing for something that could change the entire DeFi industry.
On November 3, Aave Labs, together with Kamino and Veda, publicly released a legal framework submitted to the U.S. SEC.
The core argument is intriguing:
Decentralized lending protocols should not be regulated as securities issuers or traditional financial intermediaries.
Moreover, they are not asking the SEC for special exemptions for DeFi. Rather, they argue that under existing securities laws, qualifying decentralized lending should not be considered securities transactions in the first place.
A few key points:
Users depositing assets into a lending market is not the same as entrusting money to a company to invest, and there is no promise of returns in the traditional sense.
On November 3, Aave Labs, together with Kamino and Veda, publicly released a legal framework submitted to the U.S. SEC.
The core argument is intriguing:
Decentralized lending protocols should not be regulated as securities issuers or traditional financial intermediaries.
Moreover, they are not asking the SEC for special exemptions for DeFi. Rather, they argue that under existing securities laws, qualifying decentralized lending should not be considered securities transactions in the first place.
A few key points:
Users depositing assets into a lending market is not the same as entrusting money to a company to invest, and there is no promise of returns in the traditional sense.
1
2.4k
·
--
Is the A-share market finally getting a major boost? IPOs reportedly put on hold, and major shareholders barred from selling down!
Hey everyone, according to people in the know, the CSRC met with investment banks and served up two major measures:
1. Pause IPOs: No need to rush to issue new shares and drain the market for now.
2. Restrict share sales: Major shareholders want to cash out on a large scale? Hold on—wait until the market stabilizes.
And that’s not all. The central bank and the Hong Kong Monetary Authority have also stepped in, lowering the interest rate on loans for stock buybacks and purchases from 1.25% to 1%, while expanding the swap facility.
Put simply, they don’t want any more money draining out of the market.
IPO fundraising in 2026 has already topped 292 billion yuan, the highest level since 2023. That’s been a serious drain on the market. Now, with the tap turned off and major shareholders’ exits restricted, this is a textbook move to support the market. For retail investors like us, it’s definitely some welcome short-term breathing room.
But don’t get too excited just yet. For now, this is only “verbal guidance”; no official document has been issued. We’ll have to see how the authorities put it into practice.
Will this one-two punch be enough to lift the broader market?
Is the A-share market finally getting a major boost? IPOs reportedly put on hold, and major shareholders barred from selling down!
Hey everyone, according to people in the know, the CSRC met with investment banks and served up two major measures:
1. Pause IPOs: No need to rush to issue new shares and drain the market for now.
2. Restrict share sales: Major shareholders want to cash out on a large scale? Hold on—wait until the market stabilizes.
And that’s not all. The central bank and the Hong Kong Monetary Authority have also stepped in, lowering the interest rate on loans for stock buybacks and purchases from 1.25% to 1%, while expanding the swap facility.
Put simply, they don’t want any more money draining out of the market.
IPO fundraising in 2026 has already topped 292 billion yuan, the highest level since 2023. That’s been a serious drain on the market. Now, with the tap turned off and major shareholders’ exits restricted, this is a textbook move to support the market. For retail investors like us, it’s definitely some welcome short-term breathing room.
But don’t get too excited just yet. For now, this is only “verbal guidance”; no official document has been issued. We’ll have to see how the authorities put it into practice.
Will this one-two punch be enough to lift the broader market?
Hey everyone, according to people in the know, the CSRC met with investment banks and served up two major measures:
1. Pause IPOs: No need to rush to issue new shares and drain the market for now.
2. Restrict share sales: Major shareholders want to cash out on a large scale? Hold on—wait until the market stabilizes.
And that’s not all. The central bank and the Hong Kong Monetary Authority have also stepped in, lowering the interest rate on loans for stock buybacks and purchases from 1.25% to 1%, while expanding the swap facility.
Put simply, they don’t want any more money draining out of the market.
IPO fundraising in 2026 has already topped 292 billion yuan, the highest level since 2023. That’s been a serious drain on the market. Now, with the tap turned off and major shareholders’ exits restricted, this is a textbook move to support the market. For retail investors like us, it’s definitely some welcome short-term breathing room.
But don’t get too excited just yet. For now, this is only “verbal guidance”; no official document has been issued. We’ll have to see how the authorities put it into practice.
Will this one-two punch be enough to lift the broader market?
114
·
--
On the occasion of Uniswap’s 8th anniversary, founder Hayden Adams shared some interesting data.
1. The ratio of DEX to CEX trading volume has grown from 0% to 40%.
2. Uniswap’s spot trading volume is now equivalent to 31% of Binance’s. Hayden believes that if it reaches 50%, Uniswap could become the world’s largest trading venue.
3. In the third quarter of 2026, there were 14,000 assets on Uniswap with 30-day trading volumes exceeding $100,000 each.
4. Over roughly the past year and a half, RWA trading on Uniswap has grown by 9,000%.
5. Hooks on Uniswap v4 now account for 11% of protocol trading volume, and are still growing rapidly.
But Xiaohuihui believes the truly important thing isn’t these numbers—it’s that Uniswap’s business model is changing.
In the past, Uniswap was primarily a DEX where retail traders traded altcoins.
Now, it is increasingly becoming foundational trading infrastructure for onchain capital markets.
From Robinhood Chain, to Circle’s public blockchain Arc and Kraken’s public blockchain Ink, to tokenized stocks and RWAs, more and more financial applications need an open layer of liquidity.
In the future, users may not even know they’re using Uniswap.
They’ll simply be buying and selling assets on Robinhood, in a wallet, through a bank, or in some financial app, while the underlying liquidity comes from Uniswap.
This is what Xiaohuihui has always emphasized: Uniswap is moving from B2C to B2B2C.
Even more worth watching is the change in UNI’s value-capture mechanism.
In the past, no matter how large Uniswap’s trading volume grew, it was difficult for UNI holders to directly share in the protocol’s growth.
Now, with the rollout of protocol fees, UNI burns, and Aggregator Hooks, trading activity has the potential to translate into token value.
But these things can’t simply be equated: growth in protocol trading volume ≠ proportional growth in protocol revenue ≠ a guaranteed increase in UNI’s price.
What really matters going forward is how much in fees Uniswap can capture, how much UNI it burns, and whether these figures can continue to grow.
Eight years ago, Uniswap challenged centralized exchanges.
Eight years later, it has a real opportunity to challenge the trading infrastructure of traditional financial markets.
What Xiaohuihui is bullish on is Uniswap becoming the liquidity backbone of onchain capital markets—not just a DEX.
If this thesis proves correct, UNI’s future valuation shouldn’t be based solely on the framework used for ordinary DEX tokens.
On the occasion of Uniswap’s 8th anniversary, founder Hayden Adams shared some interesting data.
1. The ratio of DEX to CEX trading volume has grown from 0% to 40%.
2. Uniswap’s spot trading volume is now equivalent to 31% of Binance’s. Hayden believes that if it reaches 50%, Uniswap could become the world’s largest trading venue.
3. In the third quarter of 2026, there were 14,000 assets on Uniswap with 30-day trading volumes exceeding $100,000 each.
4. Over roughly the past year and a half, RWA trading on Uniswap has grown by 9,000%.
5. Hooks on Uniswap v4 now account for 11% of protocol trading volume, and are still growing rapidly.
But Xiaohuihui believes the truly important thing isn’t these numbers—it’s that Uniswap’s business model is changing.
In the past, Uniswap was primarily a DEX where retail traders traded altcoins.
Now, it is increasingly becoming foundational trading infrastructure for onchain capital markets.
From Robinhood Chain, to Circle’s public blockchain Arc and Kraken’s public blockchain Ink, to tokenized stocks and RWAs, more and more financial applications need an open layer of liquidity.
In the future, users may not even know they’re using Uniswap.
They’ll simply be buying and selling assets on Robinhood, in a wallet, through a bank, or in some financial app, while the underlying liquidity comes from Uniswap.
This is what Xiaohuihui has always emphasized: Uniswap is moving from B2C to B2B2C.
Even more worth watching is the change in UNI’s value-capture mechanism.
In the past, no matter how large Uniswap’s trading volume grew, it was difficult for UNI holders to directly share in the protocol’s growth.
Now, with the rollout of protocol fees, UNI burns, and Aggregator Hooks, trading activity has the potential to translate into token value.
But these things can’t simply be equated: growth in protocol trading volume ≠ proportional growth in protocol revenue ≠ a guaranteed increase in UNI’s price.
What really matters going forward is how much in fees Uniswap can capture, how much UNI it burns, and whether these figures can continue to grow.
Eight years ago, Uniswap challenged centralized exchanges.
Eight years later, it has a real opportunity to challenge the trading infrastructure of traditional financial markets.
What Xiaohuihui is bullish on is Uniswap becoming the liquidity backbone of onchain capital markets—not just a DEX.
If this thesis proves correct, UNI’s future valuation shouldn’t be based solely on the framework used for ordinary DEX tokens.
1. The ratio of DEX to CEX trading volume has grown from 0% to 40%.
2. Uniswap’s spot trading volume is now equivalent to 31% of Binance’s. Hayden believes that if it reaches 50%, Uniswap could become the world’s largest trading venue.
3. In the third quarter of 2026, there were 14,000 assets on Uniswap with 30-day trading volumes exceeding $100,000 each.
4. Over roughly the past year and a half, RWA trading on Uniswap has grown by 9,000%.
5. Hooks on Uniswap v4 now account for 11% of protocol trading volume, and are still growing rapidly.
But Xiaohuihui believes the truly important thing isn’t these numbers—it’s that Uniswap’s business model is changing.
In the past, Uniswap was primarily a DEX where retail traders traded altcoins.
Now, it is increasingly becoming foundational trading infrastructure for onchain capital markets.
From Robinhood Chain, to Circle’s public blockchain Arc and Kraken’s public blockchain Ink, to tokenized stocks and RWAs, more and more financial applications need an open layer of liquidity.
In the future, users may not even know they’re using Uniswap.
They’ll simply be buying and selling assets on Robinhood, in a wallet, through a bank, or in some financial app, while the underlying liquidity comes from Uniswap.
This is what Xiaohuihui has always emphasized: Uniswap is moving from B2C to B2B2C.
Even more worth watching is the change in UNI’s value-capture mechanism.
In the past, no matter how large Uniswap’s trading volume grew, it was difficult for UNI holders to directly share in the protocol’s growth.
Now, with the rollout of protocol fees, UNI burns, and Aggregator Hooks, trading activity has the potential to translate into token value.
But these things can’t simply be equated: growth in protocol trading volume ≠ proportional growth in protocol revenue ≠ a guaranteed increase in UNI’s price.
What really matters going forward is how much in fees Uniswap can capture, how much UNI it burns, and whether these figures can continue to grow.
Eight years ago, Uniswap challenged centralized exchanges.
Eight years later, it has a real opportunity to challenge the trading infrastructure of traditional financial markets.
What Xiaohuihui is bullish on is Uniswap becoming the liquidity backbone of onchain capital markets—not just a DEX.
If this thesis proves correct, UNI’s future valuation shouldn’t be based solely on the framework used for ordinary DEX tokens.
6
2
4
7.5k
·
--
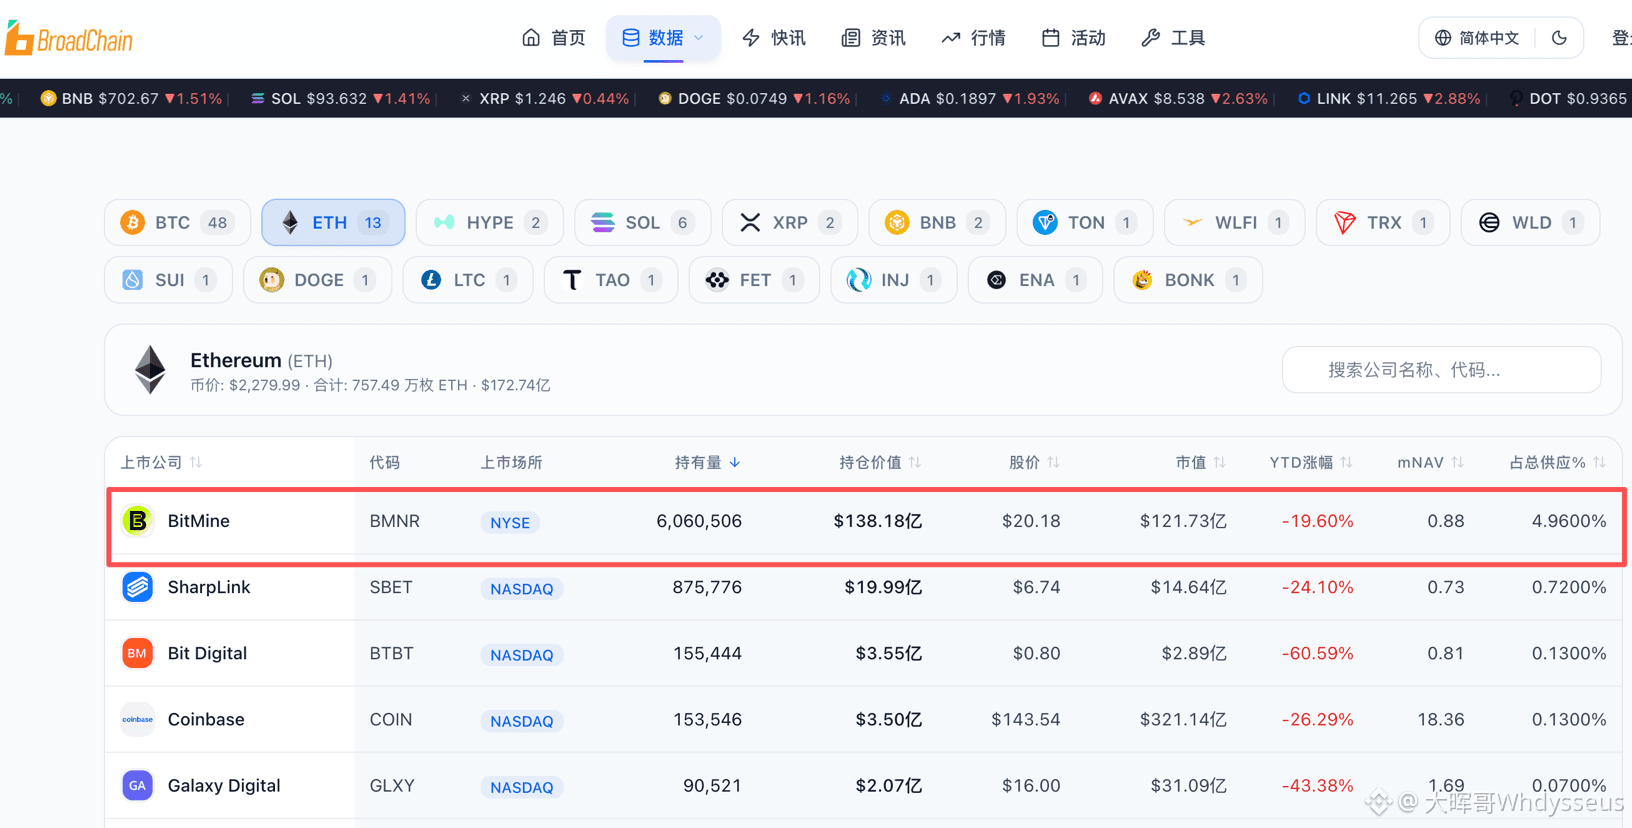
Bitcoin has Strategy, and Ethereum has Bitmine. Publicly traded companies are becoming crypto’s biggest hoarding whales.
Last week, Bitmine bought another 8,573 ETH. As of November 1, Bitmine held 6,060,506 ETH, about 4.96% of Ethereum’s total supply.
But what’s more noteworthy is that it has already staked 5.227 million ETH, or 86% of its holdings.
Based on current figures, this is expected to generate about $358 million in staking revenue per year.
What does this mean?
Strategy is accumulating BTC, betting primarily on Bitcoin’s long-term appreciation and the capital markets’ willingness to keep financing it.
Bitmine is accumulating ETH. In addition to waiting for its price to rise, it can continuously earn new ETH through staking.
One is more like a digital gold reserve company; the other is trying to become a publicly traded company holding vast amounts of yield-generating assets.
Crypto is entering a new phase: it’s not just about who is buying coins, but also who is gaining control of more and more of them.
Bitcoin has Strategy, and Ethereum has Bitmine. Publicly traded companies are becoming crypto’s biggest hoarding whales.
Last week, Bitmine bought another 8,573 ETH. As of November 1, Bitmine held 6,060,506 ETH, about 4.96% of Ethereum’s total supply.
But what’s more noteworthy is that it has already staked 5.227 million ETH, or 86% of its holdings.
Based on current figures, this is expected to generate about $358 million in staking revenue per year.
What does this mean?
Strategy is accumulating BTC, betting primarily on Bitcoin’s long-term appreciation and the capital markets’ willingness to keep financing it.
Bitmine is accumulating ETH. In addition to waiting for its price to rise, it can continuously earn new ETH through staking.
One is more like a digital gold reserve company; the other is trying to become a publicly traded company holding vast amounts of yield-generating assets.
Crypto is entering a new phase: it’s not just about who is buying coins, but also who is gaining control of more and more of them.
Last week, Bitmine bought another 8,573 ETH. As of November 1, Bitmine held 6,060,506 ETH, about 4.96% of Ethereum’s total supply.
But what’s more noteworthy is that it has already staked 5.227 million ETH, or 86% of its holdings.
Based on current figures, this is expected to generate about $358 million in staking revenue per year.
What does this mean?
Strategy is accumulating BTC, betting primarily on Bitcoin’s long-term appreciation and the capital markets’ willingness to keep financing it.
Bitmine is accumulating ETH. In addition to waiting for its price to rise, it can continuously earn new ETH through staking.
One is more like a digital gold reserve company; the other is trying to become a publicly traded company holding vast amounts of yield-generating assets.
Crypto is entering a new phase: it’s not just about who is buying coins, but also who is gaining control of more and more of them.
1.6k
·
--
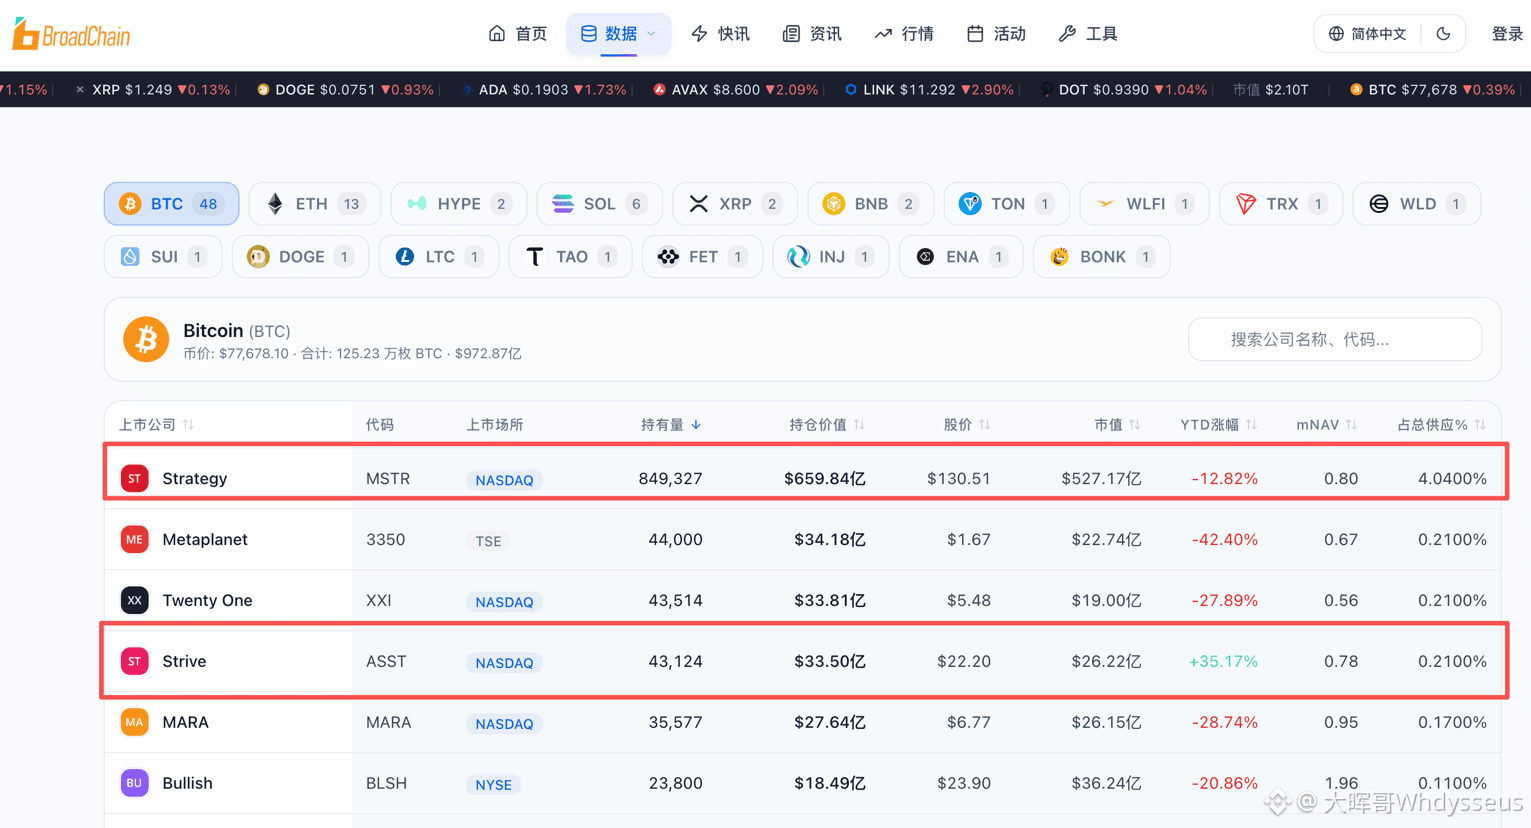
The two publicly traded companies, Strategy and Strive, have already accumulated 4.25% of Bitcoin’s total supply.
Strategy continued buying last week, adding about 810 BTC to bring its total holdings to 849,327 BTC, or 4.04% of Bitcoin’s 21 million total supply.
Strive added 124 BTC last week, bringing its total holdings to 43,124 BTC, or about 0.21% of the total supply.
While the market continues to debate whether Bitcoin is in a bull or bear market, these publicly traded companies are adding more BTC to their balance sheets through financing, stock offerings, and preferred stock.
But this is more than just a simple long-term bullish bet.
Bitcoin is gradually shifting from a speculative asset for retail investors to a capital-markets tool for publicly traded companies.
The upside is that demand from long-term holders may increase.
The risk is that the ability to buy Bitcoin is becoming increasingly dependent on capital-market financing. If financing conditions deteriorate, the pace of accumulation could also slow.
Bitcoin used to be all about miner selling pressure. Now, investors also need to watch publicly traded companies’ ability to raise capital.
The two publicly traded companies, Strategy and Strive, have already accumulated 4.25% of Bitcoin’s total supply.
Strategy continued buying last week, adding about 810 BTC to bring its total holdings to 849,327 BTC, or 4.04% of Bitcoin’s 21 million total supply.
Strive added 124 BTC last week, bringing its total holdings to 43,124 BTC, or about 0.21% of the total supply.
While the market continues to debate whether Bitcoin is in a bull or bear market, these publicly traded companies are adding more BTC to their balance sheets through financing, stock offerings, and preferred stock.
But this is more than just a simple long-term bullish bet.
Bitcoin is gradually shifting from a speculative asset for retail investors to a capital-markets tool for publicly traded companies.
The upside is that demand from long-term holders may increase.
The risk is that the ability to buy Bitcoin is becoming increasingly dependent on capital-market financing. If financing conditions deteriorate, the pace of accumulation could also slow.
Bitcoin used to be all about miner selling pressure. Now, investors also need to watch publicly traded companies’ ability to raise capital.
Strategy continued buying last week, adding about 810 BTC to bring its total holdings to 849,327 BTC, or 4.04% of Bitcoin’s 21 million total supply.
Strive added 124 BTC last week, bringing its total holdings to 43,124 BTC, or about 0.21% of the total supply.
While the market continues to debate whether Bitcoin is in a bull or bear market, these publicly traded companies are adding more BTC to their balance sheets through financing, stock offerings, and preferred stock.
But this is more than just a simple long-term bullish bet.
Bitcoin is gradually shifting from a speculative asset for retail investors to a capital-markets tool for publicly traded companies.
The upside is that demand from long-term holders may increase.
The risk is that the ability to buy Bitcoin is becoming increasingly dependent on capital-market financing. If financing conditions deteriorate, the pace of accumulation could also slow.
Bitcoin used to be all about miner selling pressure. Now, investors also need to watch publicly traded companies’ ability to raise capital.
1
769
·
--
For the past two years, everyone has been scrambling to get their hands on Nvidia GPUs.
But as AI data centers grow ever larger, the real bottleneck is shifting from “how fast can we compute?” to “how fast can we move data?”
When clusters are made up of tens or even hundreds of thousands of GPUs, even the most powerful chips go to waste if they can’t transfer data between one another fast enough.
That’s why optical communications are becoming increasingly important.
Marvell already makes custom AI chips, networking chips, and optical DSPs. It then acquired Celestial AI, and now it’s snapping up laser giant Lumentum.
Its goal is clear:
Evolve from selling chips to controlling the entire high-speed interconnect infrastructure of AI data centers.
What’s more, as CPO (co-packaged optics) advances, some of the value traditionally found in pluggable optical transceivers may shift to chips and light sources.
If Marvell sticks only to its existing DSP business, it could even find itself disrupted by the very technology of the future.
So this acquisition isn’t just about expansion—it’s about buying a ticket to the future ahead of time.
But there’s a question to consider.
At a price of $115 billion, is it buying a technological moat for the next decade—or buying at the peak of the AI capital-spending frenzy?
Xiao Hui Hui increasingly feels that the most worthwhile thing to study in the second half of the AI race isn’t just GPUs, but the infrastructure that lets GPUs truly perform.
Compute is the engine; optical communications are the highway.
As the number of engines keeps growing, the highway may be the next tollbooth.
For the past two years, everyone has been scrambling to get their hands on Nvidia GPUs.
But as AI data centers grow ever larger, the real bottleneck is shifting from “how fast can we compute?” to “how fast can we move data?”
When clusters are made up of tens or even hundreds of thousands of GPUs, even the most powerful chips go to waste if they can’t transfer data between one another fast enough.
That’s why optical communications are becoming increasingly important.
Marvell already makes custom AI chips, networking chips, and optical DSPs. It then acquired Celestial AI, and now it’s snapping up laser giant Lumentum.
Its goal is clear:
Evolve from selling chips to controlling the entire high-speed interconnect infrastructure of AI data centers.
What’s more, as CPO (co-packaged optics) advances, some of the value traditionally found in pluggable optical transceivers may shift to chips and light sources.
If Marvell sticks only to its existing DSP business, it could even find itself disrupted by the very technology of the future.
So this acquisition isn’t just about expansion—it’s about buying a ticket to the future ahead of time.
But there’s a question to consider.
At a price of $115 billion, is it buying a technological moat for the next decade—or buying at the peak of the AI capital-spending frenzy?
Xiao Hui Hui increasingly feels that the most worthwhile thing to study in the second half of the AI race isn’t just GPUs, but the infrastructure that lets GPUs truly perform.
Compute is the engine; optical communications are the highway.
As the number of engines keeps growing, the highway may be the next tollbooth.
But as AI data centers grow ever larger, the real bottleneck is shifting from “how fast can we compute?” to “how fast can we move data?”
When clusters are made up of tens or even hundreds of thousands of GPUs, even the most powerful chips go to waste if they can’t transfer data between one another fast enough.
That’s why optical communications are becoming increasingly important.
Marvell already makes custom AI chips, networking chips, and optical DSPs. It then acquired Celestial AI, and now it’s snapping up laser giant Lumentum.
Its goal is clear:
Evolve from selling chips to controlling the entire high-speed interconnect infrastructure of AI data centers.
What’s more, as CPO (co-packaged optics) advances, some of the value traditionally found in pluggable optical transceivers may shift to chips and light sources.
If Marvell sticks only to its existing DSP business, it could even find itself disrupted by the very technology of the future.
So this acquisition isn’t just about expansion—it’s about buying a ticket to the future ahead of time.
But there’s a question to consider.
At a price of $115 billion, is it buying a technological moat for the next decade—or buying at the peak of the AI capital-spending frenzy?
Xiao Hui Hui increasingly feels that the most worthwhile thing to study in the second half of the AI race isn’t just GPUs, but the infrastructure that lets GPUs truly perform.
Compute is the engine; optical communications are the highway.
As the number of engines keeps growing, the highway may be the next tollbooth.
235
·
--
When the bull market ends, some assets are merely correcting, while others are close to going to zero.
See how far major assets are from their all-time highs:
S&P 500: -3%
Microsoft: -6%
Nvidia: -16%
Tesla: -20%
Meta: -23%
AMD: -24%
Gold: -31%
Google: -32%
Bitcoin: -39%
Netflix: -54%
Ethereum: -55%
Now take a look at meme coins:
DOGE: -90%
TRUMP: -98%
MELANIA: -99%
In a bull market, everyone compares how fast things are going up. It’s only in a bear market that you find out who can survive.
Some have been unfairly punished, some are seeing the bubble deflate, and some may never return to their highs.
The most important thing in investing isn’t catching every explosive rally—it’s avoiding crashes you may never recover from.
When the bull market ends, some assets are merely correcting, while others are close to going to zero.
See how far major assets are from their all-time highs:
S&P 500: -3%
Microsoft: -6%
Nvidia: -16%
Tesla: -20%
Meta: -23%
AMD: -24%
Gold: -31%
Google: -32%
Bitcoin: -39%
Netflix: -54%
Ethereum: -55%
Now take a look at meme coins:
DOGE: -90%
TRUMP: -98%
MELANIA: -99%
In a bull market, everyone compares how fast things are going up. It’s only in a bear market that you find out who can survive.
Some have been unfairly punished, some are seeing the bubble deflate, and some may never return to their highs.
The most important thing in investing isn’t catching every explosive rally—it’s avoiding crashes you may never recover from.
See how far major assets are from their all-time highs:
S&P 500: -3%
Microsoft: -6%
Nvidia: -16%
Tesla: -20%
Meta: -23%
AMD: -24%
Gold: -31%
Google: -32%
Bitcoin: -39%
Netflix: -54%
Ethereum: -55%
Now take a look at meme coins:
DOGE: -90%
TRUMP: -98%
MELANIA: -99%
In a bull market, everyone compares how fast things are going up. It’s only in a bear market that you find out who can survive.
Some have been unfairly punished, some are seeing the bubble deflate, and some may never return to their highs.
The most important thing in investing isn’t catching every explosive rally—it’s avoiding crashes you may never recover from.
2
959
·
--
Musk’s Grok recently expanded its payment support to include Alipay and China UnionPay, and mainland China, Hong Kong, Macao, and Taiwan have also appeared as subscription region options.
But the price is what’s really worth paying attention to.
Musk has bundled Grok, Cursor, and X Premium into The X Subscription:
• Plus: $8/month
• Premium: $30/month
• Super: $100/month
The $30 Premium plan includes Grok, Cursor’s coding tools, Grok Bot, and X Premium+ benefits.
Services that were originally subscribed to separately are now being sold together in one bundle.
There’s one catch, though: Grok and Cursor share a weekly AI usage allowance, and using third-party models like Claude and GPT through Cursor still costs extra.
What Musk may really be trying to do isn’t sell a cheaper version of Grok, but tie AI, coding tools, and a social platform together.
Before, users chose whichever AI was the smartest.
In the future, users may stick with whichever ecosystem offers the best-value, most convenient AI plan.
While AI models are competing on capability, Musk has already started competing on bundles.
If you could use Grok, Cursor, and X Premium+ for $30, would you still subscribe to ChatGPT or Claude separately?
Musk’s Grok recently expanded its payment support to include Alipay and China UnionPay, and mainland China, Hong Kong, Macao, and Taiwan have also appeared as subscription region options.
But the price is what’s really worth paying attention to.
Musk has bundled Grok, Cursor, and X Premium into The X Subscription:
• Plus: $8/month
• Premium: $30/month
• Super: $100/month
The $30 Premium plan includes Grok, Cursor’s coding tools, Grok Bot, and X Premium+ benefits.
Services that were originally subscribed to separately are now being sold together in one bundle.
There’s one catch, though: Grok and Cursor share a weekly AI usage allowance, and using third-party models like Claude and GPT through Cursor still costs extra.
What Musk may really be trying to do isn’t sell a cheaper version of Grok, but tie AI, coding tools, and a social platform together.
Before, users chose whichever AI was the smartest.
In the future, users may stick with whichever ecosystem offers the best-value, most convenient AI plan.
While AI models are competing on capability, Musk has already started competing on bundles.
If you could use Grok, Cursor, and X Premium+ for $30, would you still subscribe to ChatGPT or Claude separately?
But the price is what’s really worth paying attention to.
Musk has bundled Grok, Cursor, and X Premium into The X Subscription:
• Plus: $8/month
• Premium: $30/month
• Super: $100/month
The $30 Premium plan includes Grok, Cursor’s coding tools, Grok Bot, and X Premium+ benefits.
Services that were originally subscribed to separately are now being sold together in one bundle.
There’s one catch, though: Grok and Cursor share a weekly AI usage allowance, and using third-party models like Claude and GPT through Cursor still costs extra.
What Musk may really be trying to do isn’t sell a cheaper version of Grok, but tie AI, coding tools, and a social platform together.
Before, users chose whichever AI was the smartest.
In the future, users may stick with whichever ecosystem offers the best-value, most convenient AI plan.
While AI models are competing on capability, Musk has already started competing on bundles.
If you could use Grok, Cursor, and X Premium+ for $30, would you still subscribe to ChatGPT or Claude separately?
1.9k
·
--
Partly True
The scariest thing about AI isn’t how big the bubble is—it’s that cash flow is being drained almost dry.
In the first nine months of 2026, the five biggest U.S. tech giants generated $542.9 billion in operating cash flow, a record high.
But capital expenditures soared to $556.9 billion, causing share buybacks by publicly listed companies to plunge 83% year over year.
The old playbook for U.S. tech giants was: make lots of money, buy back shares like crazy, watch the stock price rise, and shareholders profit along with it.
Now it’s: make lots of money, spend like crazy on GPUs and data centers, count on AI to make money in the future, run out of cash for buybacks, and even issue high-interest debt.
The AI story isn’t over, but the capital markets are already demanding results.
Who do you think will ultimately foot the bill for the largest AI investment in history?
The scariest thing about AI isn’t how big the bubble is—it’s that cash flow is being drained almost dry.
In the first nine months of 2026, the five biggest U.S. tech giants generated $542.9 billion in operating cash flow, a record high.
But capital expenditures soared to $556.9 billion, causing share buybacks by publicly listed companies to plunge 83% year over year.
The old playbook for U.S. tech giants was: make lots of money, buy back shares like crazy, watch the stock price rise, and shareholders profit along with it.
Now it’s: make lots of money, spend like crazy on GPUs and data centers, count on AI to make money in the future, run out of cash for buybacks, and even issue high-interest debt.
The AI story isn’t over, but the capital markets are already demanding results.
Who do you think will ultimately foot the bill for the largest AI investment in history?
In the first nine months of 2026, the five biggest U.S. tech giants generated $542.9 billion in operating cash flow, a record high.
But capital expenditures soared to $556.9 billion, causing share buybacks by publicly listed companies to plunge 83% year over year.
The old playbook for U.S. tech giants was: make lots of money, buy back shares like crazy, watch the stock price rise, and shareholders profit along with it.
Now it’s: make lots of money, spend like crazy on GPUs and data centers, count on AI to make money in the future, run out of cash for buybacks, and even issue high-interest debt.
The AI story isn’t over, but the capital markets are already demanding results.
Who do you think will ultimately foot the bill for the largest AI investment in history?
1
1.8k
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BTCRebounds80K
41,694 views
603 Discussing
BITCOIN UPDATE I’M STILL BEARISH, AND HERE’S WHY! 🚨⚠️
As you all witnessed, BTC bounced back from the $75,700 area and touched $81K. First, the market trapped long traders, and then it trapped short traders.
I’m still bearish. First of all, as everyone knows, Democrats won today’s US midterm elections, and in my view, this outcome is bearish for the market.
The market can remain volatile in the short term and trap as many traders as it wants, but that doesn’t change the overall market outlook.
There are several important upcoming events, including US Non Farm Payrolls (November 6), US CPI Inflation (November 10), US PPI (November 13), US Retail Sales (November 17), FOMC Meeting Minutes (November 18), US PCE Inflation (November 25), Federal Reserve interest rate expectations, the US Dollar Index (DXY), Treasury Yields, Nasdaq performance, Bitcoin ETF flows, and ongoing( Iran ) Israel geopolitical developments. All of these could have a significant impact on Bitcoin and the overall crypto market.
But don’t get too carried away by Bitcoin’s recent movement. Technically speaking, there hasn’t been any major bullish move yet. Yesterday, BTC was trading between $80K and $82K, and even today, it’s still around the same range.
If you want to turn bullish, that’s entirely your choice.
In my previous post, I clearly explained that BTC had technical support in the $75K / $76K zone, and the price bounced from that support and made its way back towards $80K. But this wasn’t something I had failed to mention before. In fact, I repeatedly mentioned in my posts that BTC could move towards $80K, $81K, or even $82K.
Despite that, I’m still bearish.
And I don’t have just one reason to support my bearish outlook. I have several reasons, which I’ve already explained in my previous posts.
For now, I’ll continue to wait for BTC to drop below $74K, which I believe could happen very soon. In my view, such a correction is also necessary for the market.
Anyone looking for crypto guidance just let me know.
#BTCRebounds80K
Strategic Adviser
·17 Likes
·14.9k views
Binance98PercentReplenished
31,982 views
504 Discussing
USMidterms-WhatAreMarketsExpecting?
318,268 views
2,002 Discussing