
#soxs
soxs
91,155 views
1,382 Discussing
Hot
Latest
·
--
SOXS SLIDES INTO CRITICAL TEST 🚨📉
The $SOXS price ripped through the $37.2453 support line on the 15‑minute chart, carving a sharp lower wick that barely held above the intraday low of $37.0600. A decisive order‑block breach was confirmed by a volume surge to $115.55 M, indicating that institutional sellers are overwhelming the thin liquidity pool 📊. Momentum accelerators on the short‑timeframe EMAs turned negative, pushing the asset into a bearish divergence that aligns with the broader sector sell‑off.
At the same time, the $42.5661 resistance zone remains intact, acting as a ceiling for any immediate bounce. The price is now testing the $37.2453 foothold, and a clean retest could signal a shallow correction, but a break below $37.0600 would erode the low‑volume swing point and suggest a structural breakdown 🚨. Watch the mid‑range $39.9200 area for a potential short‑term pivot as order flow re‑accumulates.
Levels to monitor:
Watching support around $37.0200
Structure suggests resistance near $42.8000
Mid range area: $39.9500
DYOR
Follow for Updates
#SOXS #GENERAL_ALTCOIN #CryptoTrending #BinanceSquare
SOXS SLIDES INTO CRITICAL TEST 🚨📉
The $SOXS price ripped through the $37.2453 support line on the 15‑minute chart, carving a sharp lower wick that barely held above the intraday low of $37.0600. A decisive order‑block breach was confirmed by a volume surge to $115.55 M, indicating that institutional sellers are overwhelming the thin liquidity pool 📊. Momentum accelerators on the short‑timeframe EMAs turned negative, pushing the asset into a bearish divergence that aligns with the broader sector sell‑off.
At the same time, the $42.5661 resistance zone remains intact, acting as a ceiling for any immediate bounce. The price is now testing the $37.2453 foothold, and a clean retest could signal a shallow correction, but a break below $37.0600 would erode the low‑volume swing point and suggest a structural breakdown 🚨. Watch the mid‑range $39.9200 area for a potential short‑term pivot as order flow re‑accumulates.
Levels to monitor:
Watching support around $37.0200
Structure suggests resistance near $42.8000
Mid range area: $39.9500
DYOR
Follow for Updates
#SOXS #GENERAL_ALTCOIN #CryptoTrending #BinanceSquare
The $SOXS price ripped through the $37.2453 support line on the 15‑minute chart, carving a sharp lower wick that barely held above the intraday low of $37.0600. A decisive order‑block breach was confirmed by a volume surge to $115.55 M, indicating that institutional sellers are overwhelming the thin liquidity pool 📊. Momentum accelerators on the short‑timeframe EMAs turned negative, pushing the asset into a bearish divergence that aligns with the broader sector sell‑off.
At the same time, the $42.5661 resistance zone remains intact, acting as a ceiling for any immediate bounce. The price is now testing the $37.2453 foothold, and a clean retest could signal a shallow correction, but a break below $37.0600 would erode the low‑volume swing point and suggest a structural breakdown 🚨. Watch the mid‑range $39.9200 area for a potential short‑term pivot as order flow re‑accumulates.
Levels to monitor:
Watching support around $37.0200
Structure suggests resistance near $42.8000
Mid range area: $39.9500
DYOR
Follow for Updates
#SOXS #GENERAL_ALTCOIN #CryptoTrending #BinanceSquare
140
·
--
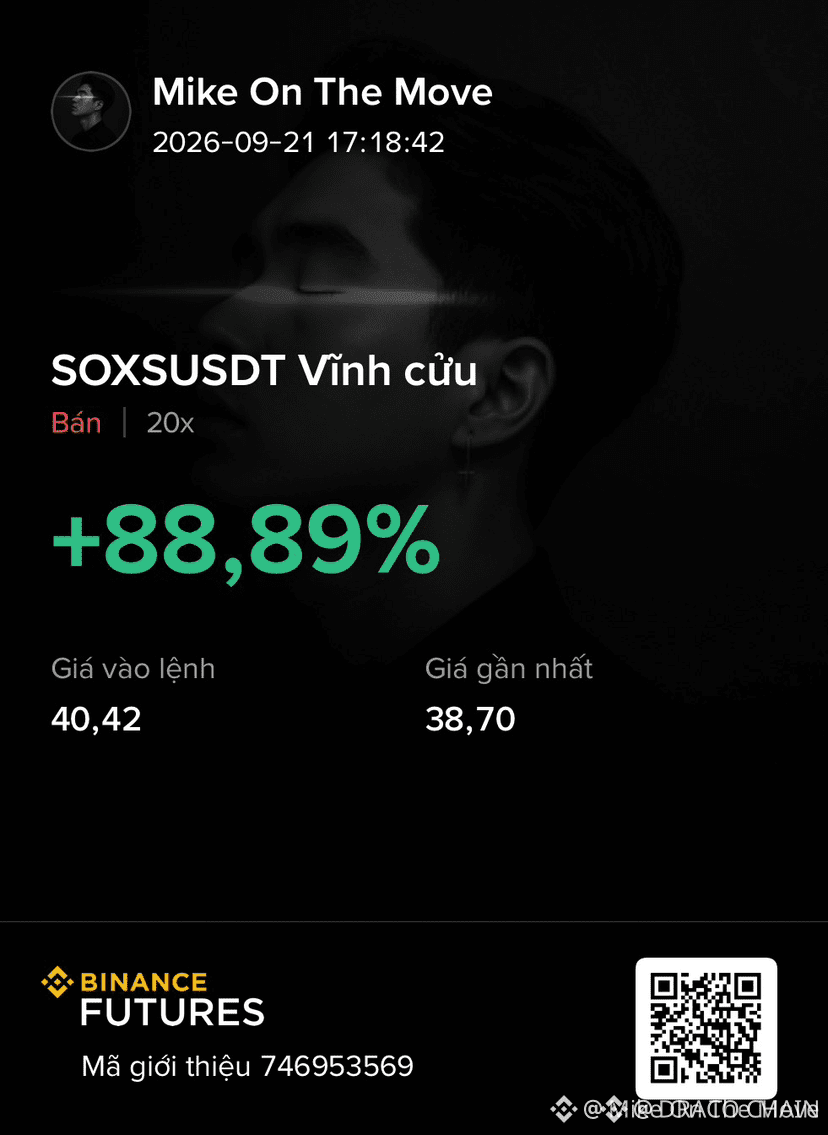
🚨 $SOXS SHORT EXPANSION HITS TP1 AS LIQUIDITY SWEEP DELIVERS 🔻
The institutional distribution phase on $SOXS continues to execute with high structural precision. 🦈 Smart money captured the upper liquidity pool before triggering this downside impulse, allowing our short positioning to slice directly into first target parameters. 📊
With TP1 secured, taking partial profits here mitigates downside execution risk while capitalizing on initial order book imbalance. 💡 Standard structural protocol applies: protect your principal by trailing stops into safe territory as we let remaining position volume target deeper efficiency gaps below. 💬 Did you lock in partials at TP1 or are you holding your full position for the lower liquidity pool sweep? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #TakeProfit #MarketStructure
🎯 🦈
🚨 $SOXS SHORT EXPANSION HITS TP1 AS LIQUIDITY SWEEP DELIVERS 🔻
The institutional distribution phase on $SOXS continues to execute with high structural precision. 🦈 Smart money captured the upper liquidity pool before triggering this downside impulse, allowing our short positioning to slice directly into first target parameters. 📊
With TP1 secured, taking partial profits here mitigates downside execution risk while capitalizing on initial order book imbalance. 💡 Standard structural protocol applies: protect your principal by trailing stops into safe territory as we let remaining position volume target deeper efficiency gaps below. 💬 Did you lock in partials at TP1 or are you holding your full position for the lower liquidity pool sweep? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #TakeProfit #MarketStructure
🎯 🦈
The institutional distribution phase on $SOXS continues to execute with high structural precision. 🦈 Smart money captured the upper liquidity pool before triggering this downside impulse, allowing our short positioning to slice directly into first target parameters. 📊
With TP1 secured, taking partial profits here mitigates downside execution risk while capitalizing on initial order book imbalance. 💡 Standard structural protocol applies: protect your principal by trailing stops into safe territory as we let remaining position volume target deeper efficiency gaps below. 💬 Did you lock in partials at TP1 or are you holding your full position for the lower liquidity pool sweep? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #TakeProfit #MarketStructure
🎯 🦈
83
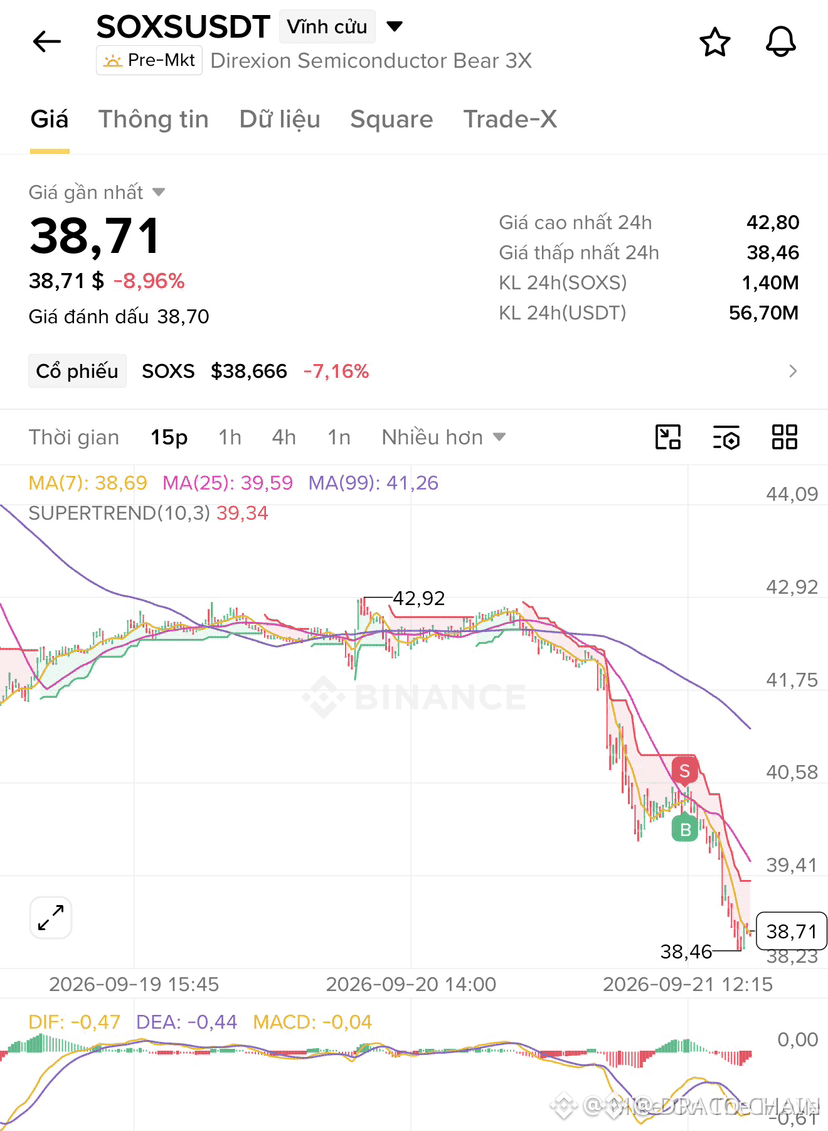
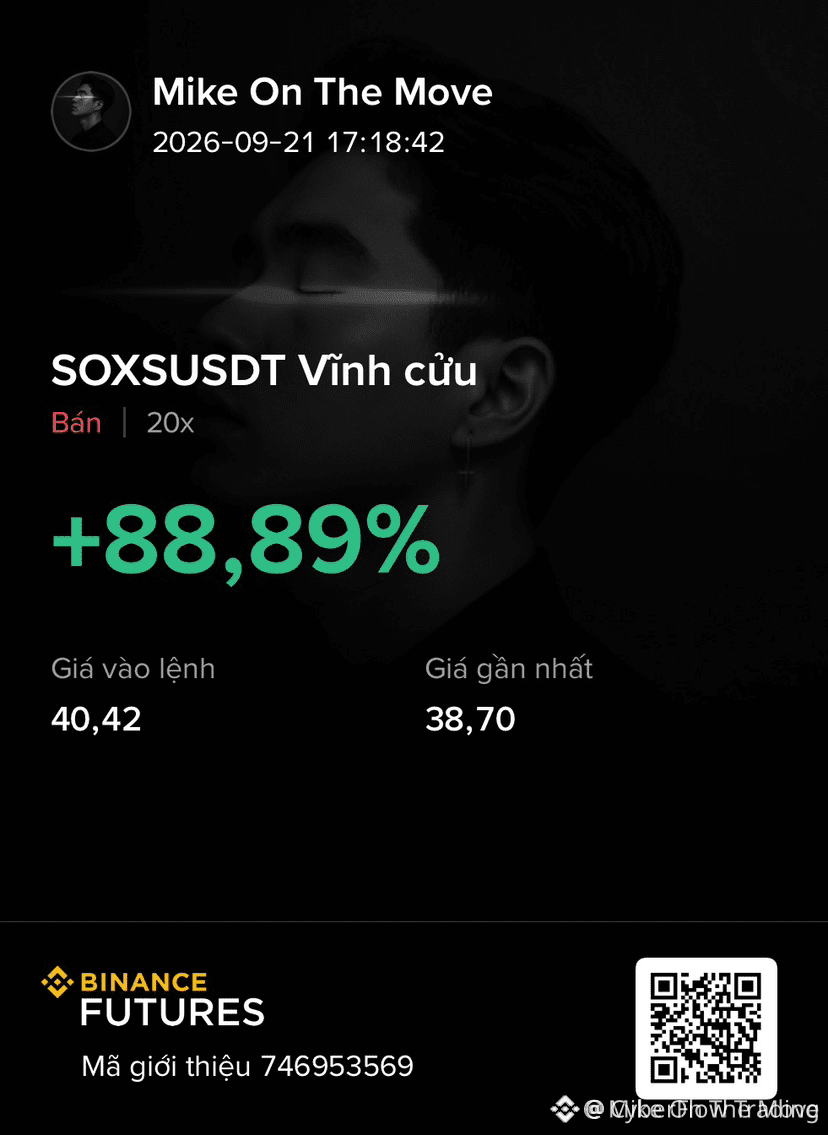
🎯 $SOXS SHORT DELIVERS AS FIRST TARGET SMASHED CLEANLY! 🔻
The short setup on $SOXS unfolded with clinical precision, sweeping through our first target as sell-side pressure escalated right on queue. Taking partial profits here derisks the execution completely, putting us in the driver seat for the rest of the move. 📉
Order flow continues to favor lower prices, with sellers aggressively capping every minor bounce near overhead resistance. Sliding stop-losses to protect capital allows the remaining runner to target deeper demand zones stress-free. 📊
💬 Did you take partials at TP1 or are you holding the full position for final targets? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #PriceAction #Trading
⚡ 🎯
🎯 $SOXS SHORT DELIVERS AS FIRST TARGET SMASHED CLEANLY! 🔻
The short setup on $SOXS unfolded with clinical precision, sweeping through our first target as sell-side pressure escalated right on queue. Taking partial profits here derisks the execution completely, putting us in the driver seat for the rest of the move. 📉
Order flow continues to favor lower prices, with sellers aggressively capping every minor bounce near overhead resistance. Sliding stop-losses to protect capital allows the remaining runner to target deeper demand zones stress-free. 📊
💬 Did you take partials at TP1 or are you holding the full position for final targets? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #PriceAction #Trading
⚡ 🎯
The short setup on $SOXS unfolded with clinical precision, sweeping through our first target as sell-side pressure escalated right on queue. Taking partial profits here derisks the execution completely, putting us in the driver seat for the rest of the move. 📉
Order flow continues to favor lower prices, with sellers aggressively capping every minor bounce near overhead resistance. Sliding stop-losses to protect capital allows the remaining runner to target deeper demand zones stress-free. 📊
💬 Did you take partials at TP1 or are you holding the full position for final targets? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #PriceAction #Trading
⚡ 🎯
99
·
--
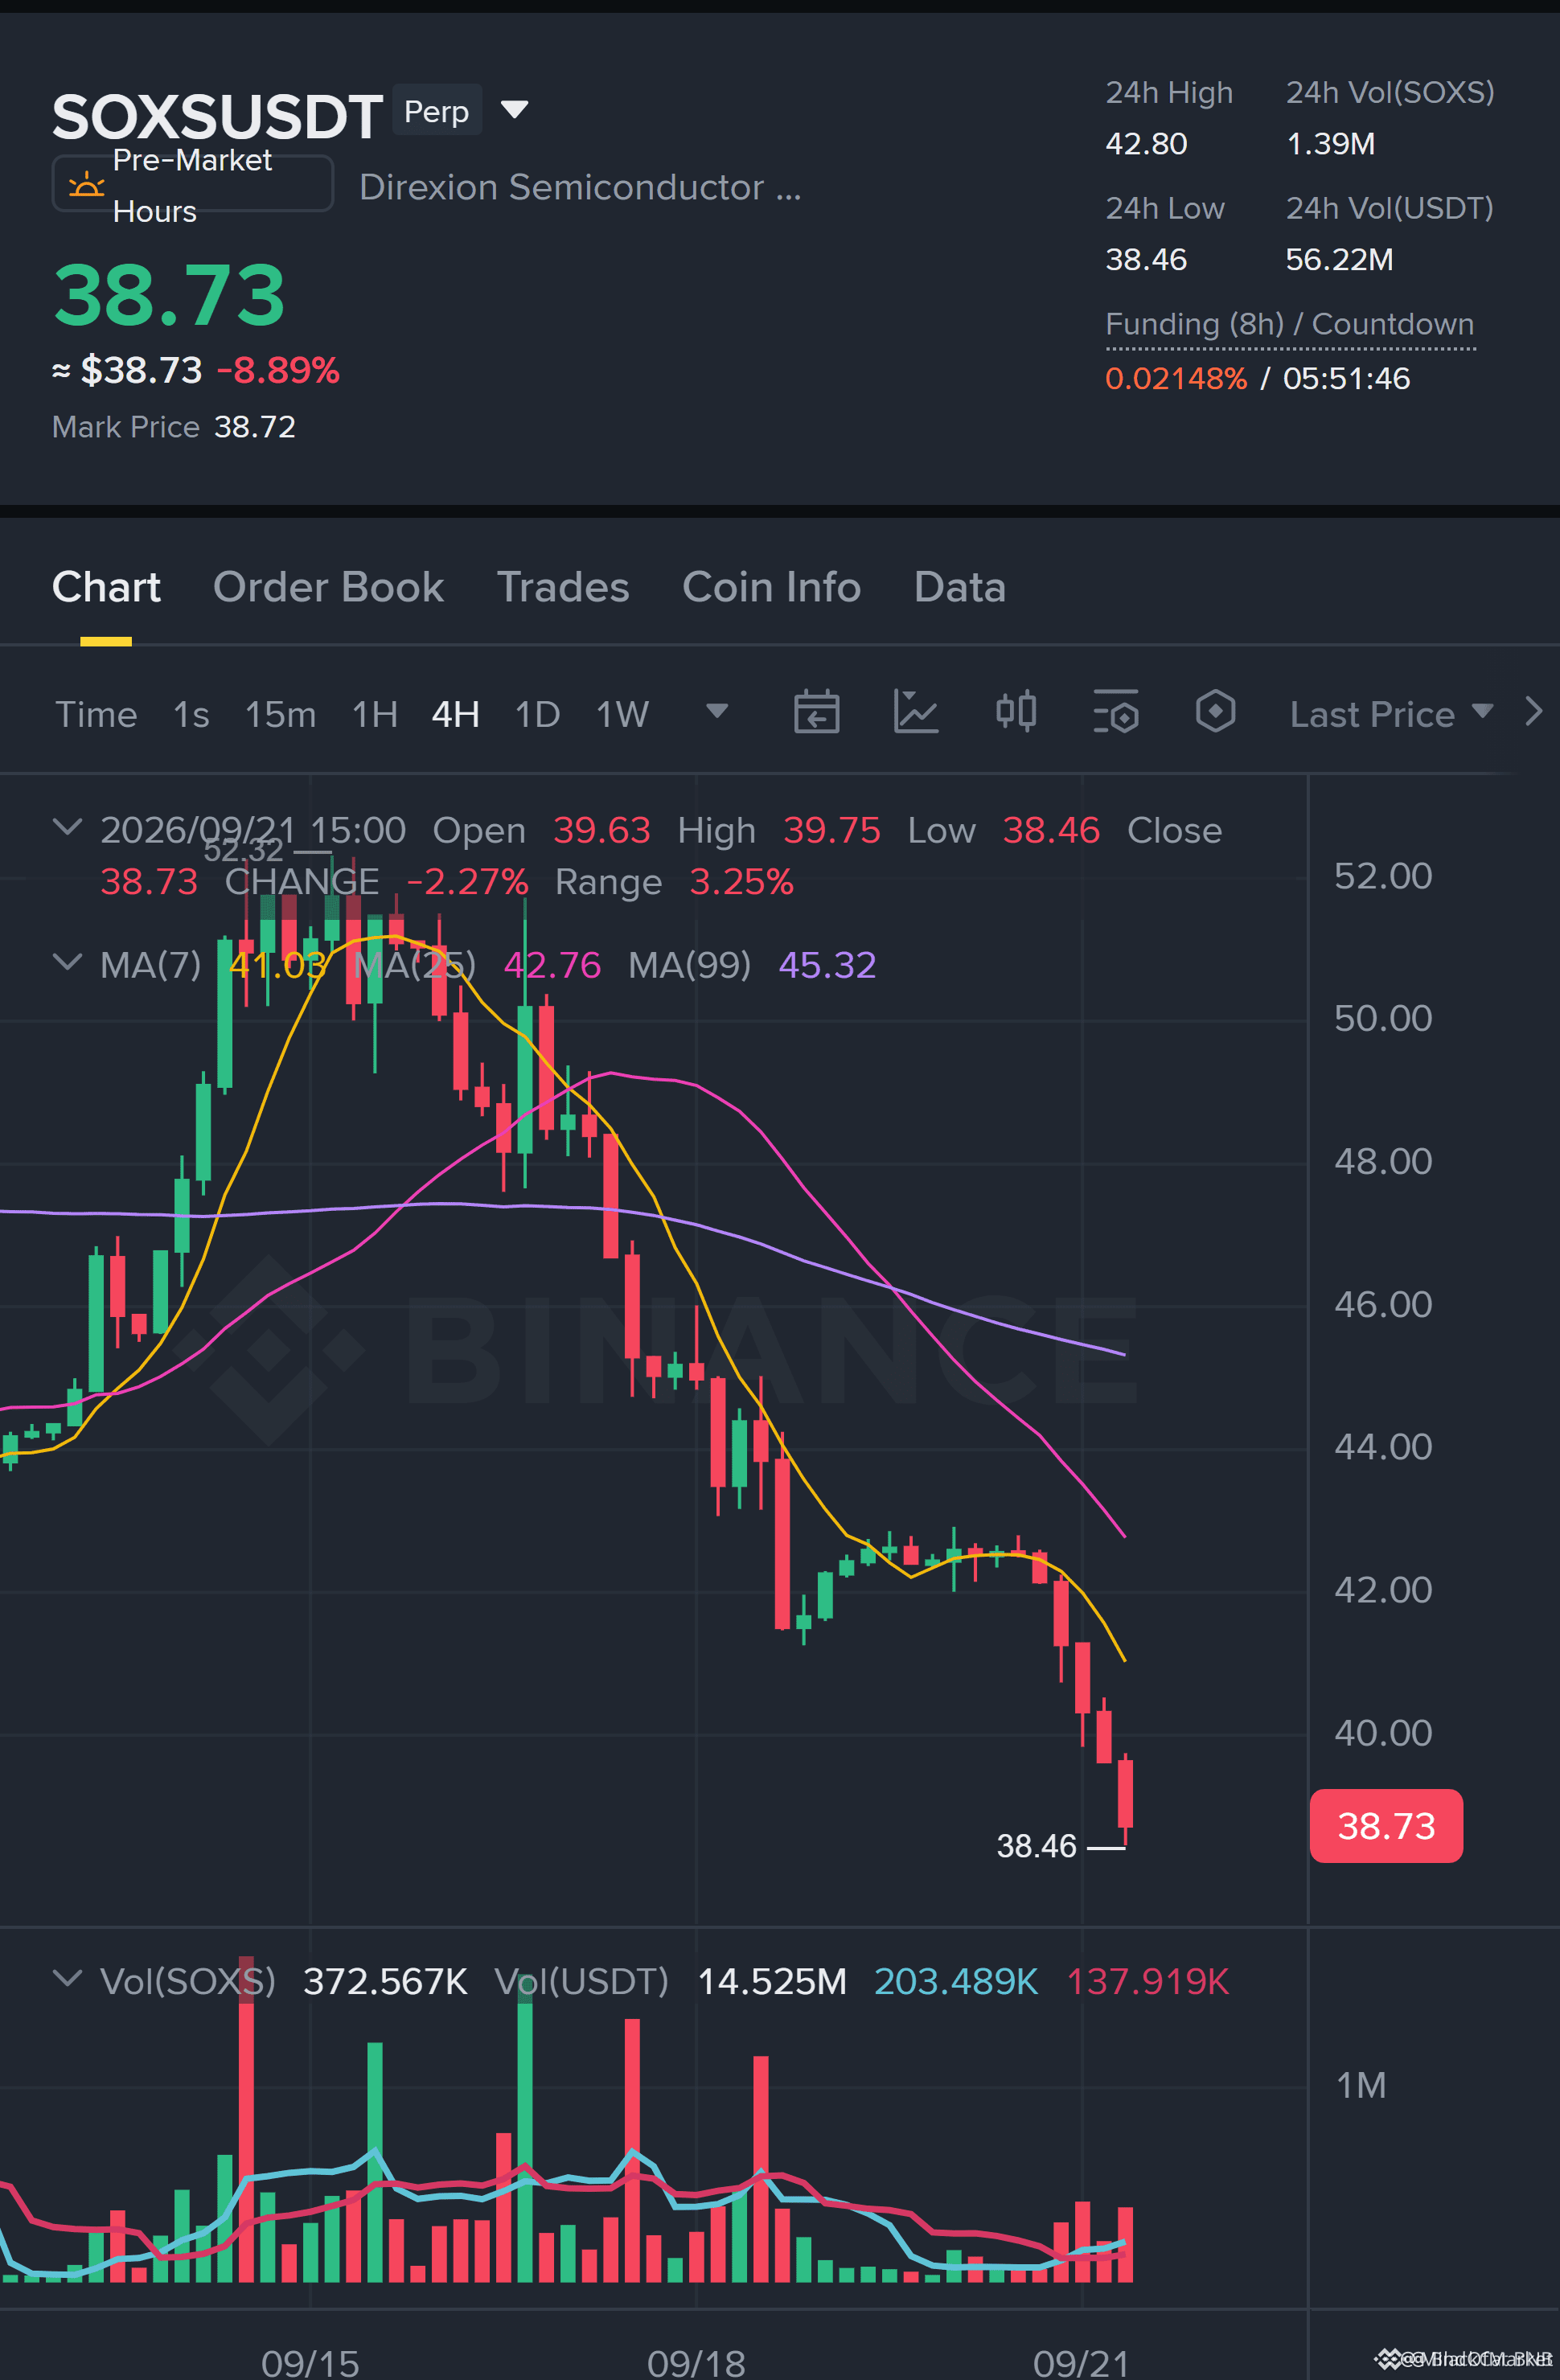
🔴 $SOXS BEARISH CONTINUATION SETTING UP AS INSTITUTIONAL MOMENTUM ALIGNS! 🎯
Entry: 39.34 - 39.44 🔴
Target: 37.83 🎯
Stop Loss: 40.04 ⚠️
The 1H timeframe continues to print lower highs, keeping smart money distribution cleanly intact. 📊 While momentum favours the downside, price has stretched past our immediate supply zone, making a disciplined retest into the 39.34–39.44 imbalance area essential before taking execution risks. 🔍
Wait for 15M lower-timeframe confirmation to validate structural weakness before committing capital to this order block retest. 📌 Are you letting price pull back into supply or chasing the breakout early? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #MarketStructure #Trading
🔴 🐻
🔴 $SOXS BEARISH CONTINUATION SETTING UP AS INSTITUTIONAL MOMENTUM ALIGNS! 🎯
Entry: 39.34 - 39.44 🔴
Target: 37.83 🎯
Stop Loss: 40.04 ⚠️
The 1H timeframe continues to print lower highs, keeping smart money distribution cleanly intact. 📊 While momentum favours the downside, price has stretched past our immediate supply zone, making a disciplined retest into the 39.34–39.44 imbalance area essential before taking execution risks. 🔍
Wait for 15M lower-timeframe confirmation to validate structural weakness before committing capital to this order block retest. 📌 Are you letting price pull back into supply or chasing the breakout early? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #MarketStructure #Trading
🔴 🐻
Entry: 39.34 - 39.44 🔴
Target: 37.83 🎯
Stop Loss: 40.04 ⚠️
The 1H timeframe continues to print lower highs, keeping smart money distribution cleanly intact. 📊 While momentum favours the downside, price has stretched past our immediate supply zone, making a disciplined retest into the 39.34–39.44 imbalance area essential before taking execution risks. 🔍
Wait for 15M lower-timeframe confirmation to validate structural weakness before committing capital to this order block retest. 📌 Are you letting price pull back into supply or chasing the breakout early? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #MarketStructure #Trading
🔴 🐻
110
·
--
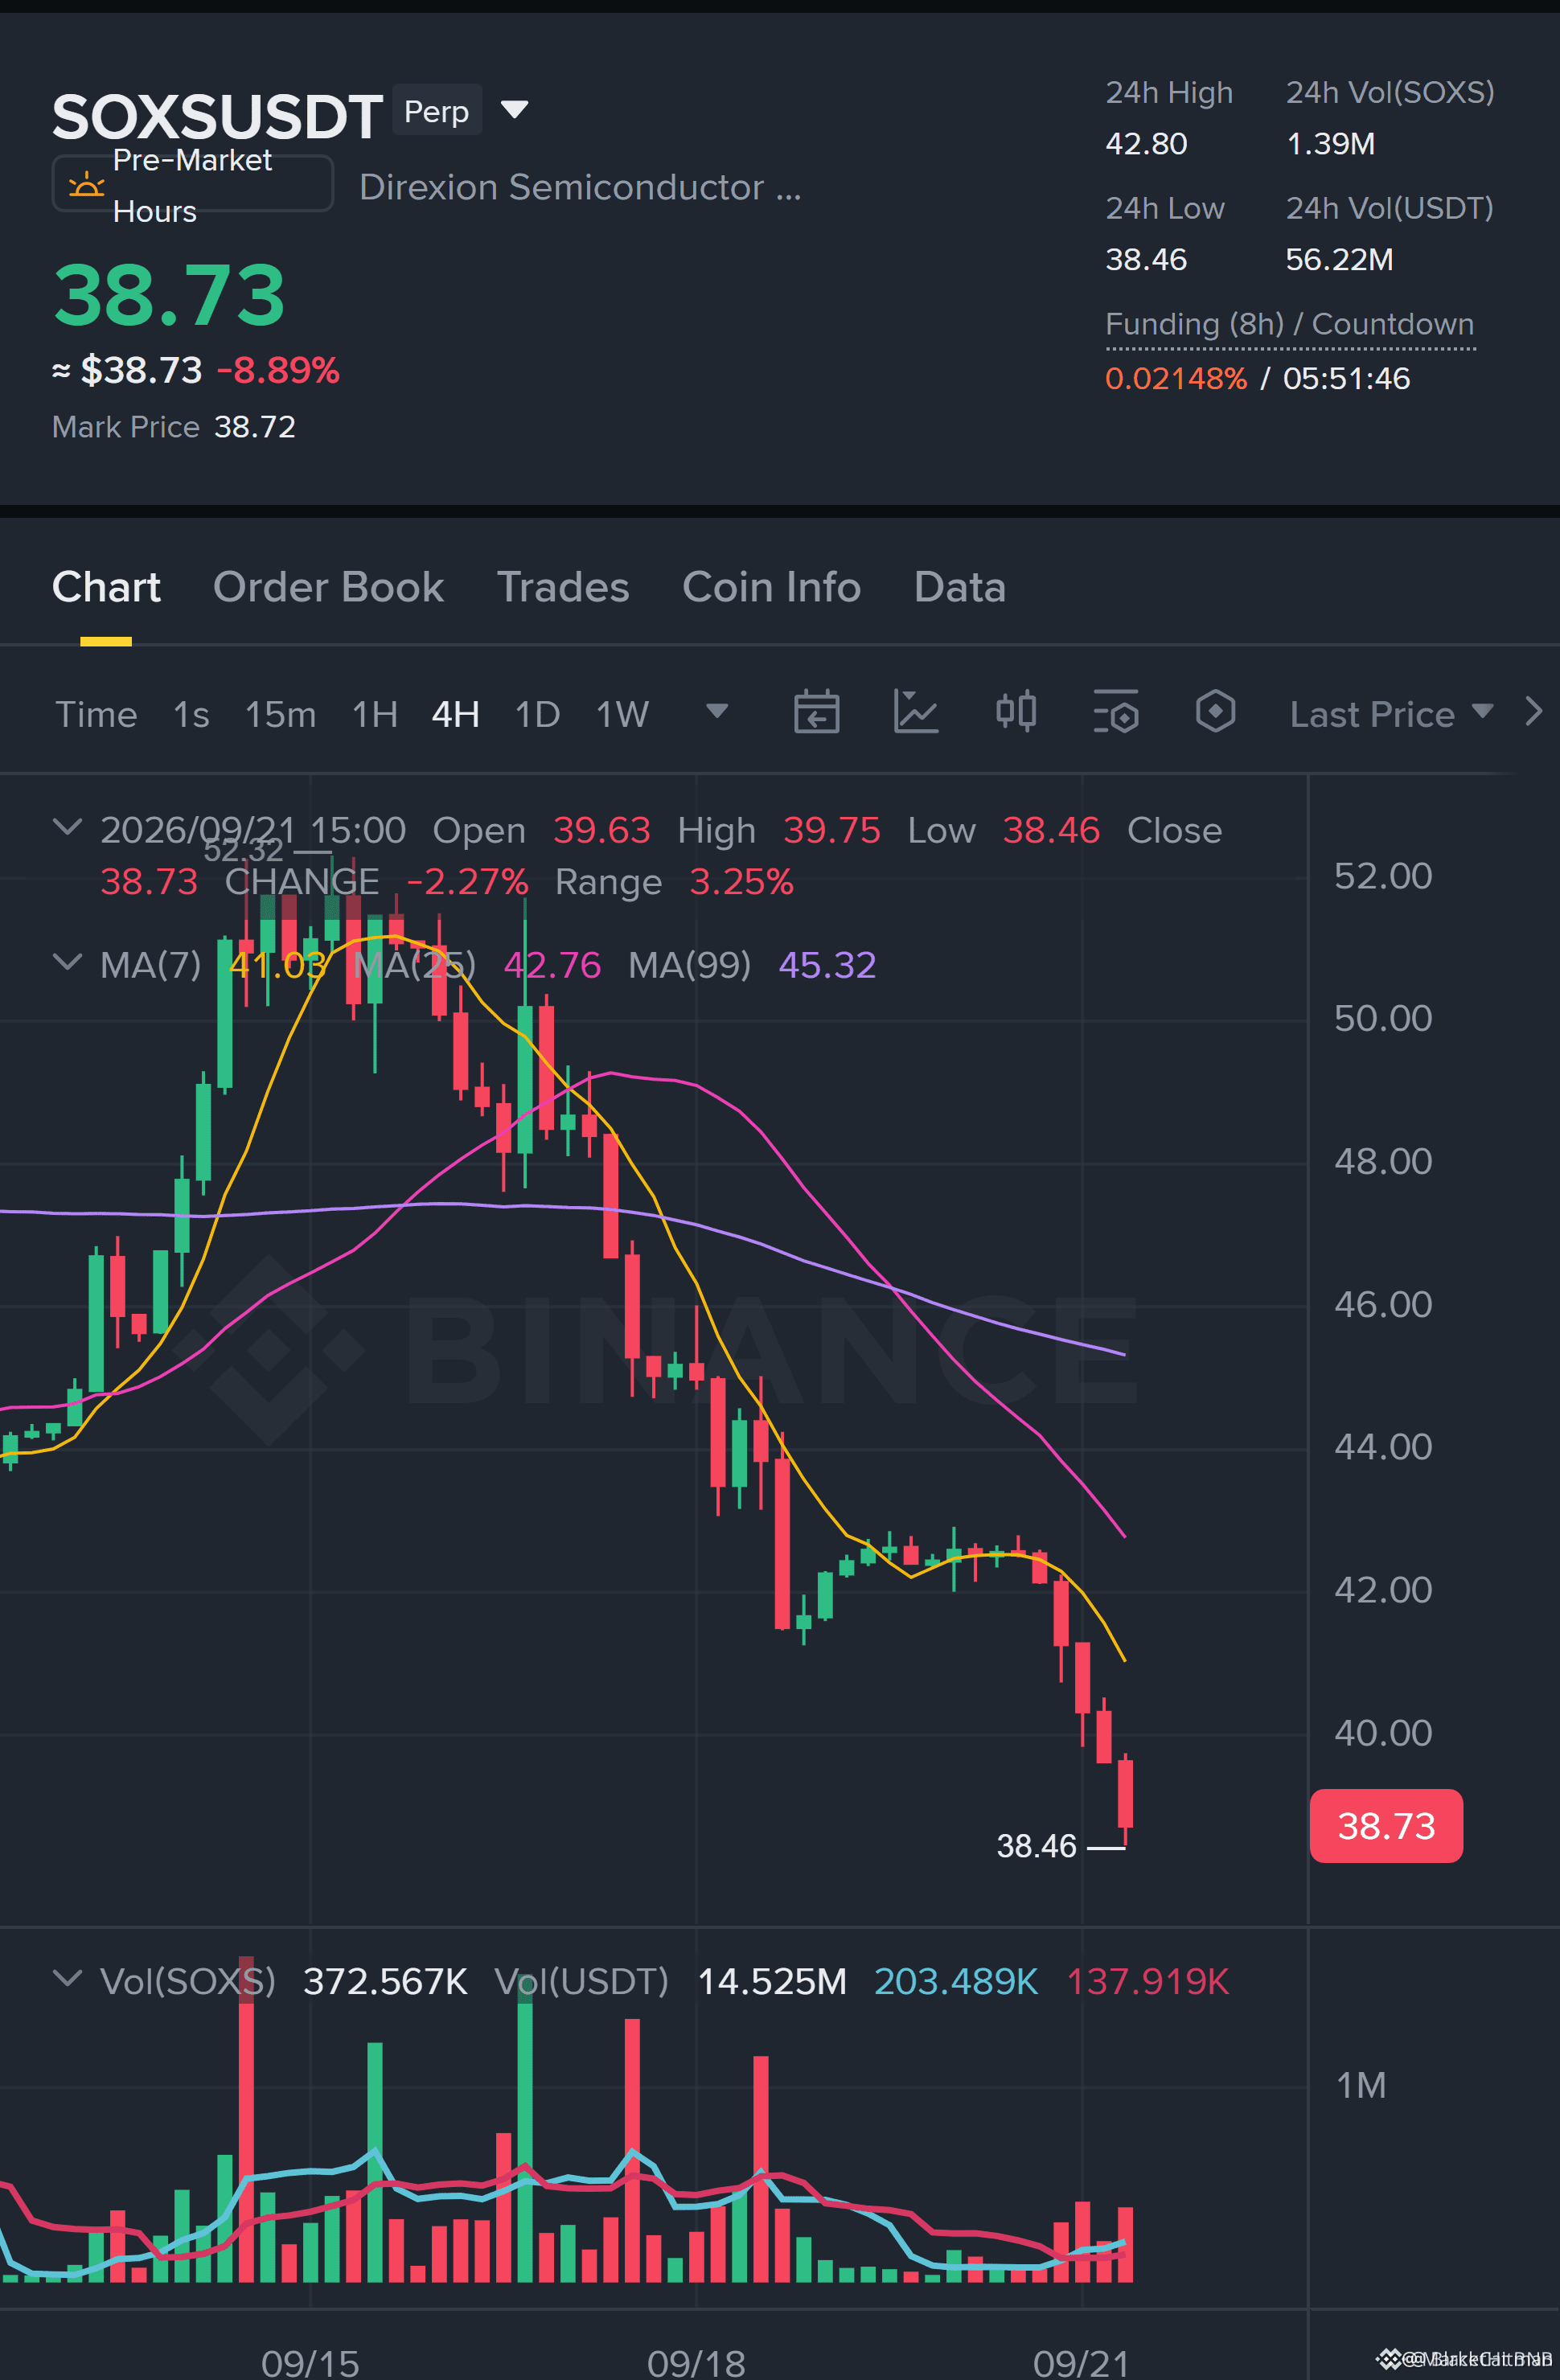
🚨 $SOXS BEARISH MOMENTUM BUILDING AS SELLERS GUARD THE 1H RESISTANCE! 🐻
Entry: 39.34 - 39.44 ⚡
Target: 37.83 🎯
Stop Loss: 40.04 ⚠️
📌 The 1H structure remains clearly aligned with the downside, but discipline is everything in these market conditions. 📉 Price is currently floating away from our planned sell zone, with lower-timeframe confirmation still waiting to lock in.
💡 Smart money respects the setup—we are letting price bounce back into the 39.34–39.44 retest zone to hunt for high-probability downside expansion toward 37.83. 📊 Keep this on your watchlist and let the confirmation trigger the execution. 💬 Are you stalking this retest for a short play, or waiting for lower levels? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #Bearish #Trading
🐻 🩸
🚨 $SOXS BEARISH MOMENTUM BUILDING AS SELLERS GUARD THE 1H RESISTANCE! 🐻
Entry: 39.34 - 39.44 ⚡
Target: 37.83 🎯
Stop Loss: 40.04 ⚠️
📌 The 1H structure remains clearly aligned with the downside, but discipline is everything in these market conditions. 📉 Price is currently floating away from our planned sell zone, with lower-timeframe confirmation still waiting to lock in.
💡 Smart money respects the setup—we are letting price bounce back into the 39.34–39.44 retest zone to hunt for high-probability downside expansion toward 37.83. 📊 Keep this on your watchlist and let the confirmation trigger the execution. 💬 Are you stalking this retest for a short play, or waiting for lower levels? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #Bearish #Trading
🐻 🩸
Entry: 39.34 - 39.44 ⚡
Target: 37.83 🎯
Stop Loss: 40.04 ⚠️
📌 The 1H structure remains clearly aligned with the downside, but discipline is everything in these market conditions. 📉 Price is currently floating away from our planned sell zone, with lower-timeframe confirmation still waiting to lock in.
💡 Smart money respects the setup—we are letting price bounce back into the 39.34–39.44 retest zone to hunt for high-probability downside expansion toward 37.83. 📊 Keep this on your watchlist and let the confirmation trigger the execution. 💬 Are you stalking this retest for a short play, or waiting for lower levels? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #Bearish #Trading
🐻 🩸
UsamaRafique123:
u will see soxs at 60 very soon
1
164

·
--
Keeping our focus sharp today—here is the complete long entry breakdown for $SOXS.
⚡ $SOXS — LONG SETUP
📍 Entry: 38.54 – 38.77
🎯 TP1: 39.24
🎯 TP2: 39.55
🎯 TP3: 40.02
🛑 Stop Loss: 38.31
Trade here 👇
📌 Trade management rules: see pinned post.
What’s your take on $SOXS right now? Let me know in the comments and follow for daily setups!
#WriteToEarn #SOXS #CryptoTrading #BinanceSquare #Crypto
Keeping our focus sharp today—here is the complete long entry breakdown for $SOXS .
⚡ $SOXS — LONG SETUP
📍 Entry: 38.54 – 38.77
🎯 TP1: 39.24
🎯 TP2: 39.55
🎯 TP3: 40.02
🛑 Stop Loss: 38.31
Trade here 👇
📌 Trade management rules: see pinned post.
What’s your take on $SOXS right now? Let me know in the comments and follow for daily setups!
#WriteToEarn #SOXS #CryptoTrading #BinanceSquare #Crypto
⚡ $SOXS — LONG SETUP
📍 Entry: 38.54 – 38.77
🎯 TP1: 39.24
🎯 TP2: 39.55
🎯 TP3: 40.02
🛑 Stop Loss: 38.31
Trade here 👇
📌 Trade management rules: see pinned post.
What’s your take on $SOXS right now? Let me know in the comments and follow for daily setups!
#WriteToEarn #SOXS #CryptoTrading #BinanceSquare #Crypto
1
168
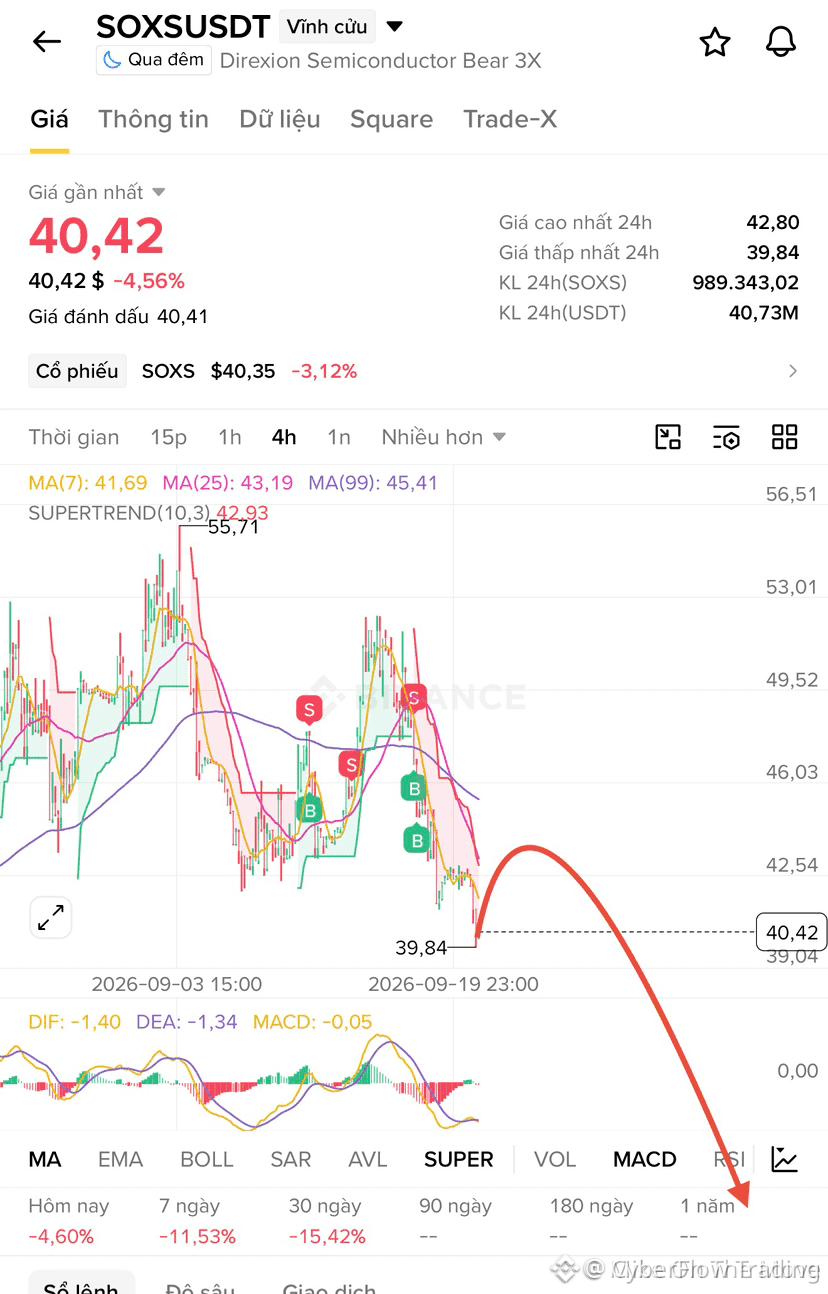
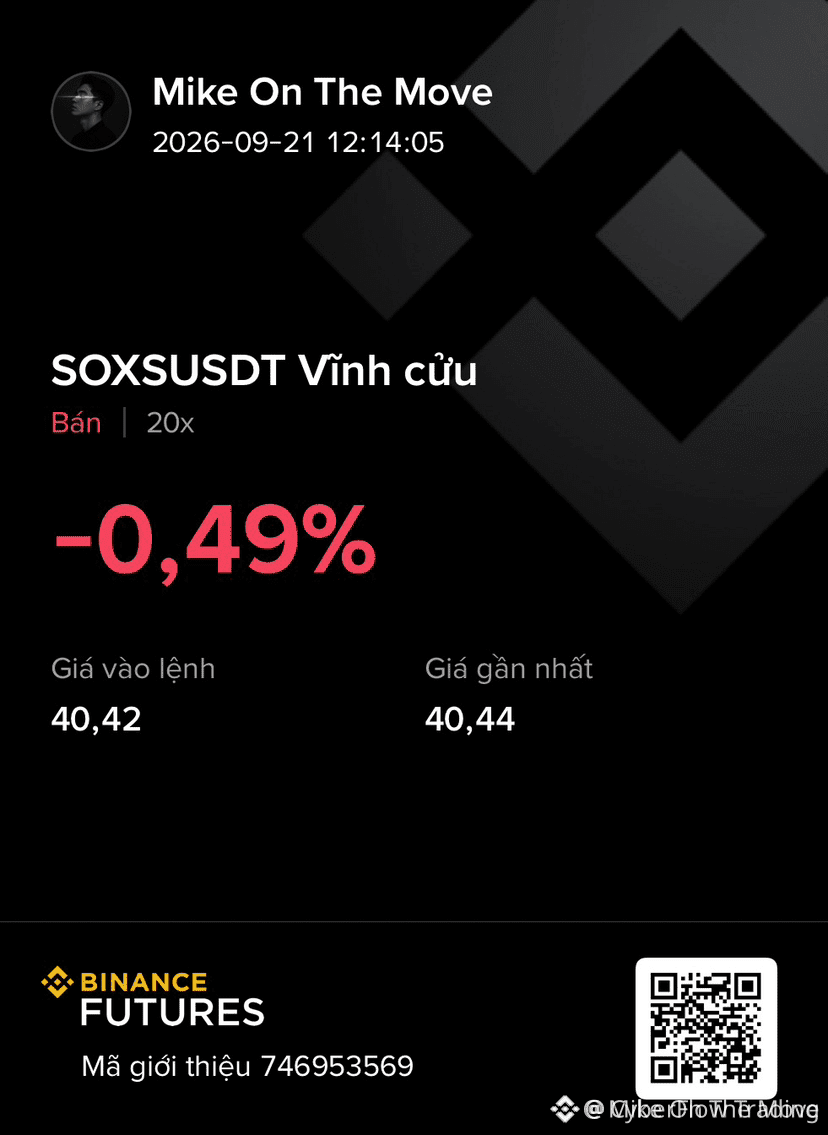
🚨 $SOXS IS ROLLING OVER AS SELLERS RECLAIM CONTROL FOR A CLEAN DOWNSIDE SWEEP! 📉
Entry: 39.8 - 41.0 ⚡
Target: 36.5 🎯
Stop Loss: 44.0 ⚠️
📌 Momentum is visibly exhausting at the upper boundary, paving the way for heavy distribution as bid support begins to crack. Sellers are front-running the breakdown, setting up a high-conviction window to capitalize on the sliding order flow. 📉
💡 Structure points directly toward lower liquidity pools as buying volume dries up on every retest. Risk parameters remain crisp above resistance, giving us an asymmetric execution window for the downside extension. 💬 Are you positioning for this downside leg or watching from the sidelines? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #Crypto #Bearish #Trading
🔻 🐻
🚨 $SOXS IS ROLLING OVER AS SELLERS RECLAIM CONTROL FOR A CLEAN DOWNSIDE SWEEP! 📉
Entry: 39.8 - 41.0 ⚡
Target: 36.5 🎯
Stop Loss: 44.0 ⚠️
📌 Momentum is visibly exhausting at the upper boundary, paving the way for heavy distribution as bid support begins to crack. Sellers are front-running the breakdown, setting up a high-conviction window to capitalize on the sliding order flow. 📉
💡 Structure points directly toward lower liquidity pools as buying volume dries up on every retest. Risk parameters remain crisp above resistance, giving us an asymmetric execution window for the downside extension. 💬 Are you positioning for this downside leg or watching from the sidelines? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #Crypto #Bearish #Trading
🔻 🐻
Entry: 39.8 - 41.0 ⚡
Target: 36.5 🎯
Stop Loss: 44.0 ⚠️
📌 Momentum is visibly exhausting at the upper boundary, paving the way for heavy distribution as bid support begins to crack. Sellers are front-running the breakdown, setting up a high-conviction window to capitalize on the sliding order flow. 📉
💡 Structure points directly toward lower liquidity pools as buying volume dries up on every retest. Risk parameters remain crisp above resistance, giving us an asymmetric execution window for the downside extension. 💬 Are you positioning for this downside leg or watching from the sidelines? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #Crypto #Bearish #Trading
🔻 🐻
100
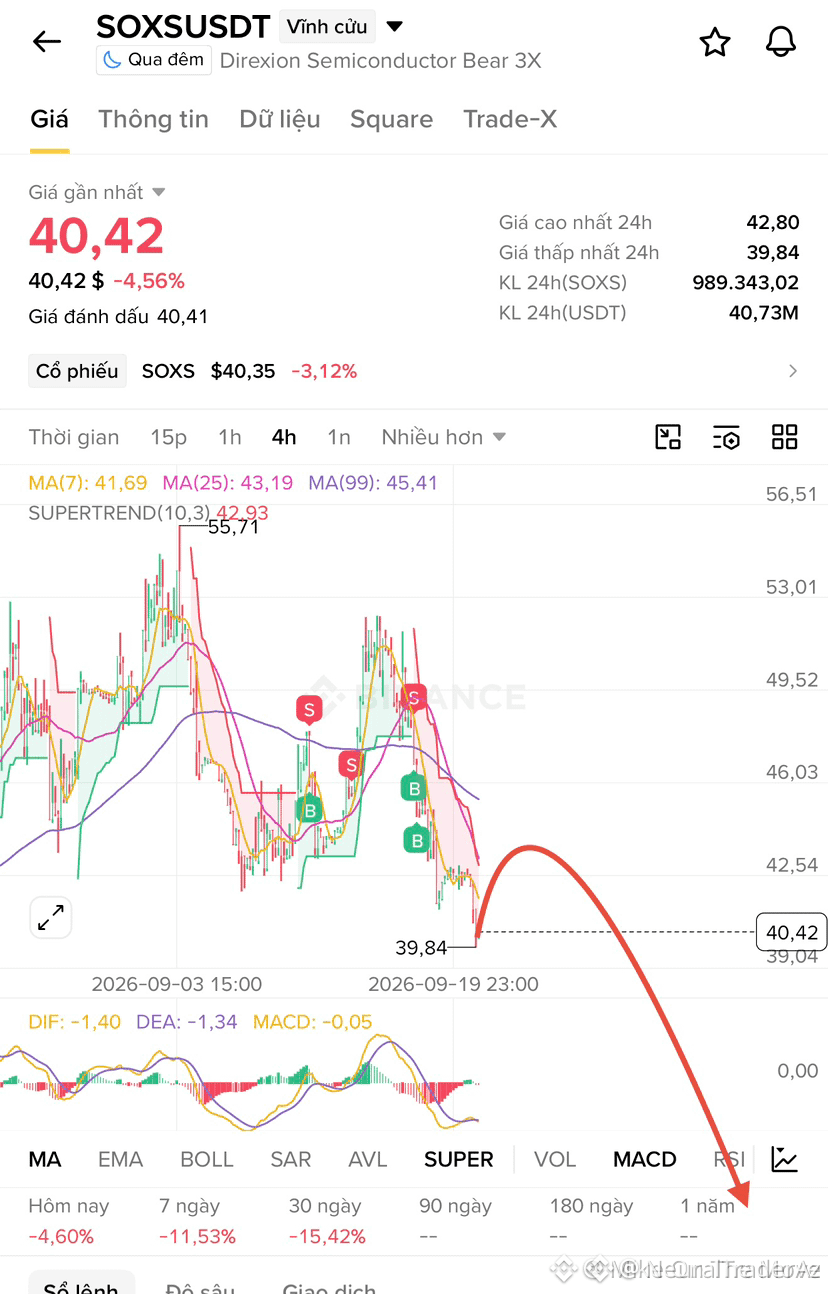
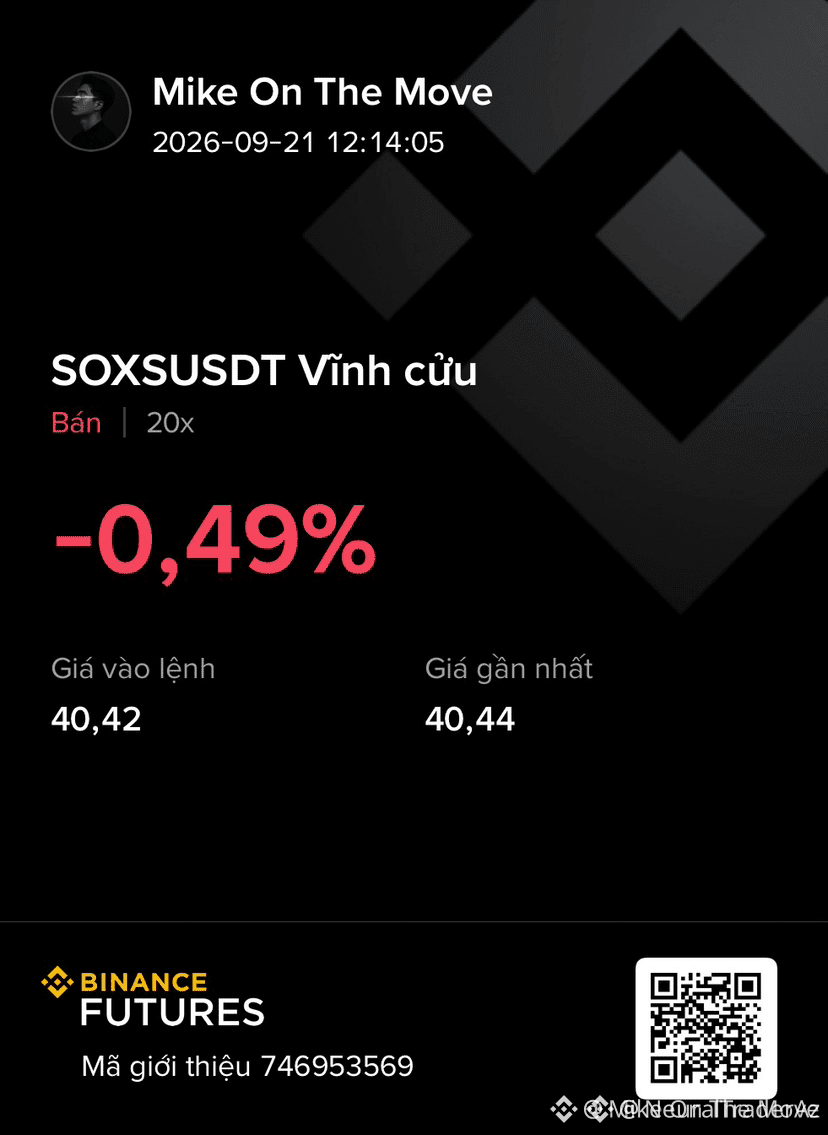
🚨 $SOXS INSTITUTIONAL REJECTION AT RESISTANCE OPENS HEAVY DOWNSIDE LIQUIDITY DROP 🔴
Entry: 39.8 - 41.0 🔴
Target: 39.2 / 37.8 / 36.5 🎯
Stop Loss: 44.0 🛑
📌 $SOXS is showing clear signs of structural distribution near the upper premium supply zone. Smart money appears to be capitalizing on top-side liquidity between 39.8 and 41.0 to build short exposure. 🔍
🩸 A sharp displacement lower toward the market inefficiency pools below should accelerate downside momentum as sell-side liquidity gets swept. Invalidation remains strictly defined above the key pivot high at 44.0. 🛡️
💬 Do you expect institutional sellers to push all the way to TP3, or will support absorb this move early? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #MarketStructure #Bearish
📉 🐻
🚨 $SOXS INSTITUTIONAL REJECTION AT RESISTANCE OPENS HEAVY DOWNSIDE LIQUIDITY DROP 🔴
Entry: 39.8 - 41.0 🔴
Target: 39.2 / 37.8 / 36.5 🎯
Stop Loss: 44.0 🛑
📌 $SOXS is showing clear signs of structural distribution near the upper premium supply zone. Smart money appears to be capitalizing on top-side liquidity between 39.8 and 41.0 to build short exposure. 🔍
🩸 A sharp displacement lower toward the market inefficiency pools below should accelerate downside momentum as sell-side liquidity gets swept. Invalidation remains strictly defined above the key pivot high at 44.0. 🛡️
💬 Do you expect institutional sellers to push all the way to TP3, or will support absorb this move early? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #MarketStructure #Bearish
📉 🐻
Entry: 39.8 - 41.0 🔴
Target: 39.2 / 37.8 / 36.5 🎯
Stop Loss: 44.0 🛑
📌 $SOXS is showing clear signs of structural distribution near the upper premium supply zone. Smart money appears to be capitalizing on top-side liquidity between 39.8 and 41.0 to build short exposure. 🔍
🩸 A sharp displacement lower toward the market inefficiency pools below should accelerate downside momentum as sell-side liquidity gets swept. Invalidation remains strictly defined above the key pivot high at 44.0. 🛡️
💬 Do you expect institutional sellers to push all the way to TP3, or will support absorb this move early? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #SOXS #ShortSetup #MarketStructure #Bearish
📉 🐻
75
·
--
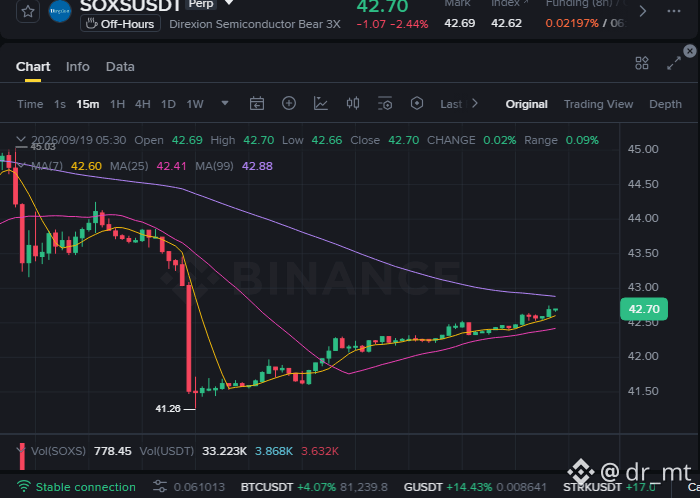
$SOXS is trying to flip the tape right here 🔥
After that sharp flush, price stabilized and started grinding higher instead of rolling back over. Now it’s printing above the breakout line at 42.6400, with buyers still holding the move together.
That’s why 42.6900 is the actionable long area — it’s the spot where the breakout stays alive if the market keeps accepting above the level.
TP1: 43.1169
First place to start locking something in if the push continues.
TP2: 43.5438
Next continuation zone if momentum keeps building.
TP3: 43.9707
Stretch target if this breakout starts to accelerate.
STOP LOSS: 41.8362
Lose that level and the rebound thesis breaks down.
Risk reminder: early breakouts can fail fast — keep size disciplined and respect the stop ⚠️
$SOXS looks live from here. Are you in this move? 👇
#SOXS #CryptoTrading #Breakout #BinanceSquare
$SOXS is trying to flip the tape right here 🔥
After that sharp flush, price stabilized and started grinding higher instead of rolling back over. Now it’s printing above the breakout line at 42.6400, with buyers still holding the move together.
That’s why 42.6900 is the actionable long area — it’s the spot where the breakout stays alive if the market keeps accepting above the level.
TP1: 43.1169
First place to start locking something in if the push continues.
TP2: 43.5438
Next continuation zone if momentum keeps building.
TP3: 43.9707
Stretch target if this breakout starts to accelerate.
STOP LOSS: 41.8362
Lose that level and the rebound thesis breaks down.
Risk reminder: early breakouts can fail fast — keep size disciplined and respect the stop ⚠️
$SOXS looks live from here. Are you in this move? 👇
#SOXS #CryptoTrading #Breakout #BinanceSquare
After that sharp flush, price stabilized and started grinding higher instead of rolling back over. Now it’s printing above the breakout line at 42.6400, with buyers still holding the move together.
That’s why 42.6900 is the actionable long area — it’s the spot where the breakout stays alive if the market keeps accepting above the level.
TP1: 43.1169
First place to start locking something in if the push continues.
TP2: 43.5438
Next continuation zone if momentum keeps building.
TP3: 43.9707
Stretch target if this breakout starts to accelerate.
STOP LOSS: 41.8362
Lose that level and the rebound thesis breaks down.
Risk reminder: early breakouts can fail fast — keep size disciplined and respect the stop ⚠️
$SOXS looks live from here. Are you in this move? 👇
#SOXS #CryptoTrading #Breakout #BinanceSquare
143
·
--
The current price action on $SOXS has triggered a clean setup that aligns with my long-term accumulation model, signaling a potential upside rotation. I’ve refined the entry parameters based on the latest localized support test, and the risk-to-reward profile is now sitting exactly where I need it to be.
⚡ $SOXS — LONG SETUP
📍 Entry: 41.14 – 41.39
🎯 TP1: 41.89
🎯 TP2: 42.22
🎯 TP3: 42.72
🛑 Stop Loss: 40.9
Trade here 👇
📌 Trade management rules: see pinned post.
How are you positioning for this move? Drop your thoughts below or follow for more updates.
#WriteToEarn #SOXS #CryptoTrading #BinanceSquare #Crypto
The current price action on $SOXS has triggered a clean setup that aligns with my long-term accumulation model, signaling a potential upside rotation. I’ve refined the entry parameters based on the latest localized support test, and the risk-to-reward profile is now sitting exactly where I need it to be.
⚡ $SOXS — LONG SETUP
📍 Entry: 41.14 – 41.39
🎯 TP1: 41.89
🎯 TP2: 42.22
🎯 TP3: 42.72
🛑 Stop Loss: 40.9
Trade here 👇
📌 Trade management rules: see pinned post.
How are you positioning for this move? Drop your thoughts below or follow for more updates.
#WriteToEarn #SOXS #CryptoTrading #BinanceSquare #Crypto
⚡ $SOXS — LONG SETUP
📍 Entry: 41.14 – 41.39
🎯 TP1: 41.89
🎯 TP2: 42.22
🎯 TP3: 42.72
🛑 Stop Loss: 40.9
Trade here 👇
📌 Trade management rules: see pinned post.
How are you positioning for this move? Drop your thoughts below or follow for more updates.
#WriteToEarn #SOXS #CryptoTrading #BinanceSquare #Crypto
1
80
·
--
$SOXS #SOXS #Contract Trading
#1 on the Biggest Declines List | SOXS Reverse/Long Watch
24h Decline -13.02%
Current Price 37.2100
Trigger Level 37.2100
Invalidation Level 35.1634
Observation Levels 39.0705 / 40.9310
Market Clues: SOXS ranks #1 on the biggest declines list / 24h decline -13.02% / after panic selling is released, the room to keep dropping starts to narrow
After the #1 biggest-declines panic selling is released, the downside room narrows; you can set up a counter long position. The invalidation level is the stop-loss level.
$SOXS #SOXS #Contract Trading
#1 on the Biggest Declines List | SOXS Reverse/Long Watch
24h Decline -13.02%
Current Price 37.2100
Trigger Level 37.2100
Invalidation Level 35.1634
Observation Levels 39.0705 / 40.9310
Market Clues: SOXS ranks #1 on the biggest declines list / 24h decline -13.02% / after panic selling is released, the room to keep dropping starts to narrow
After the #1 biggest-declines panic selling is released, the downside room narrows; you can set up a counter long position. The invalidation level is the stop-loss level.
#1 on the Biggest Declines List | SOXS Reverse/Long Watch
24h Decline -13.02%
Current Price 37.2100
Trigger Level 37.2100
Invalidation Level 35.1634
Observation Levels 39.0705 / 40.9310
Market Clues: SOXS ranks #1 on the biggest declines list / 24h decline -13.02% / after panic selling is released, the room to keep dropping starts to narrow
After the #1 biggest-declines panic selling is released, the downside room narrows; you can set up a counter long position. The invalidation level is the stop-loss level.
234
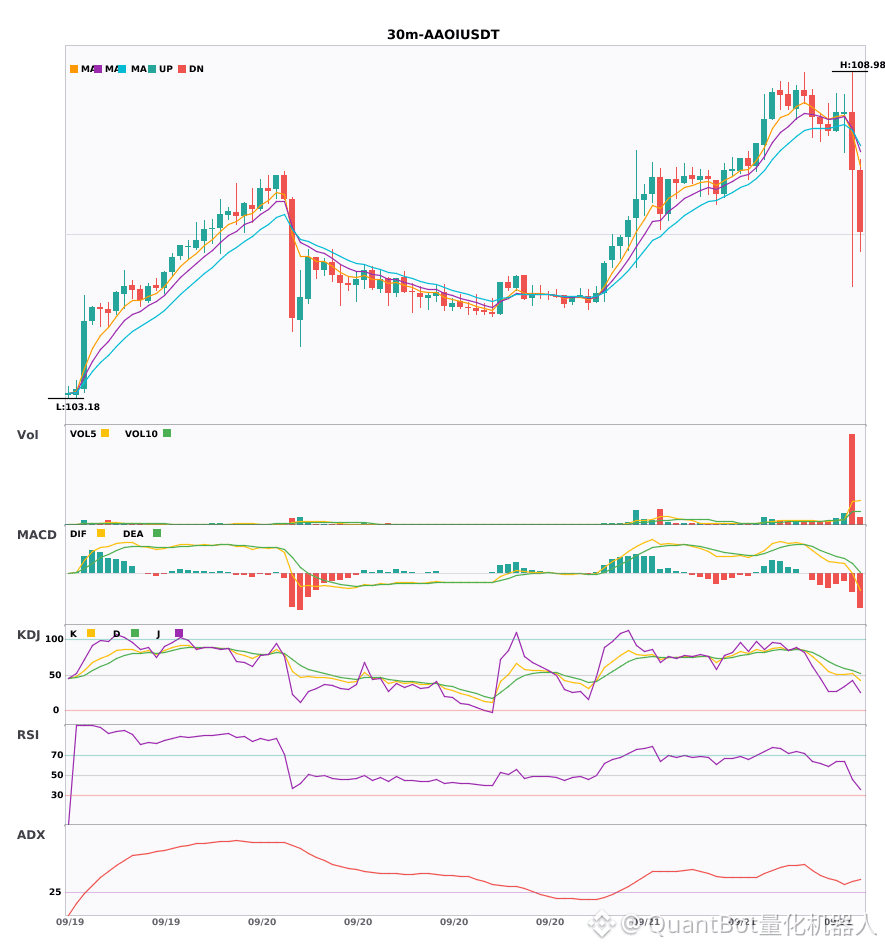
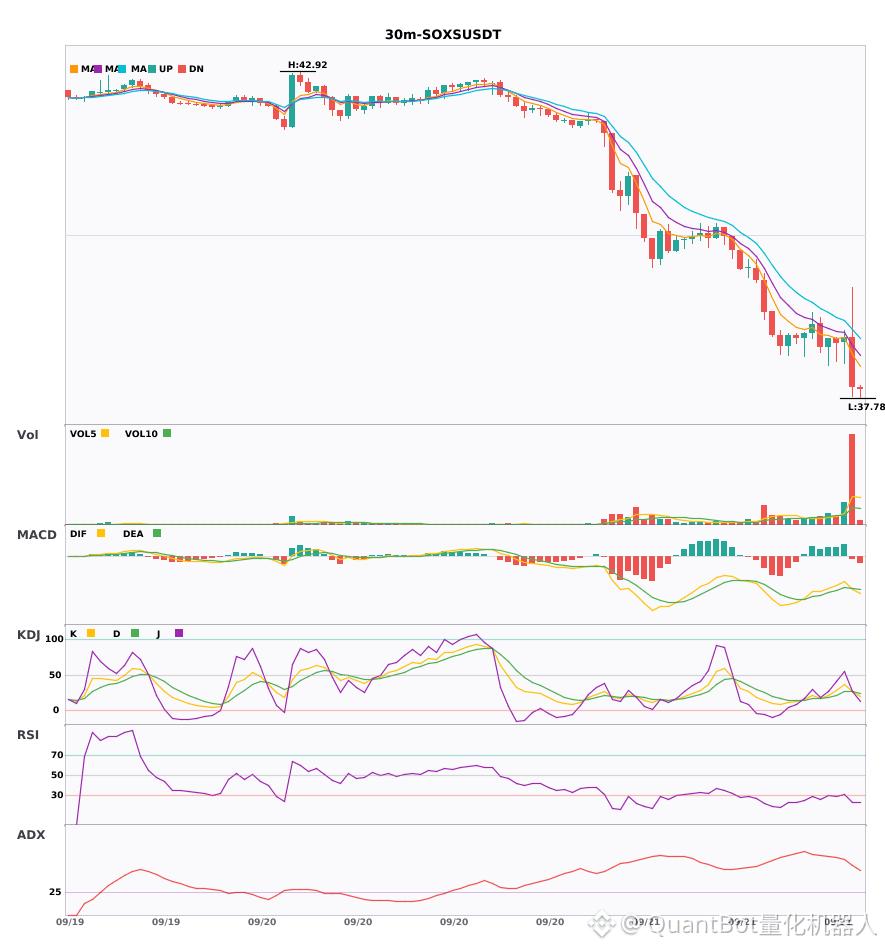
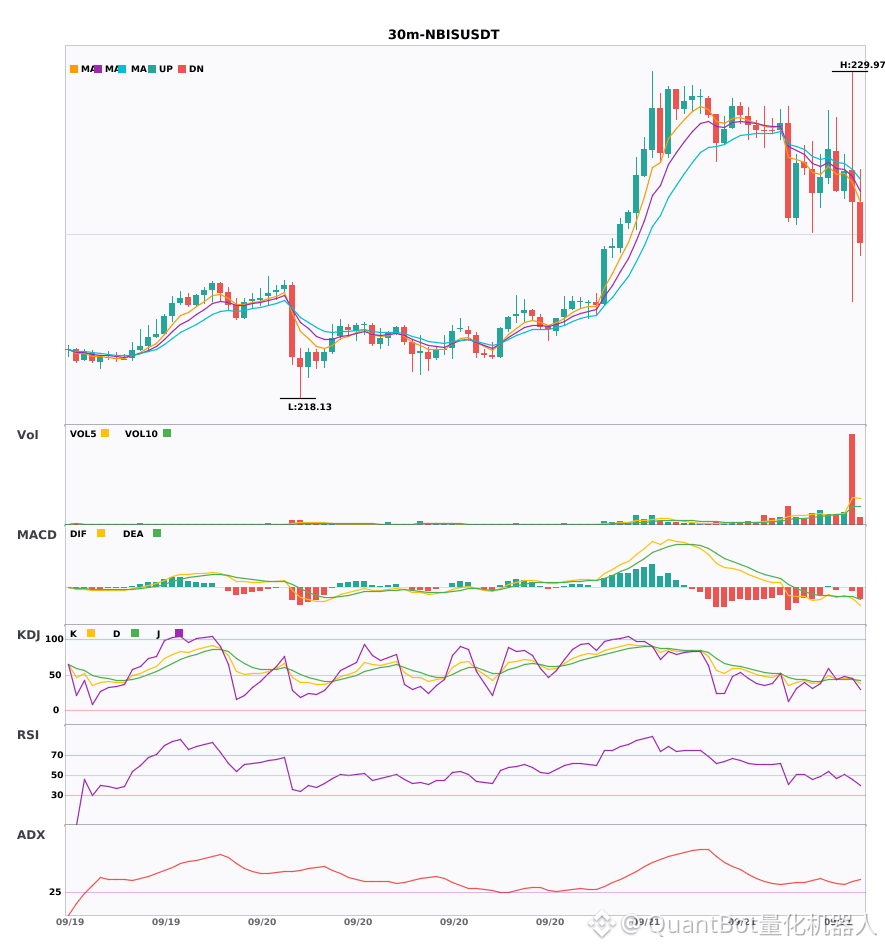
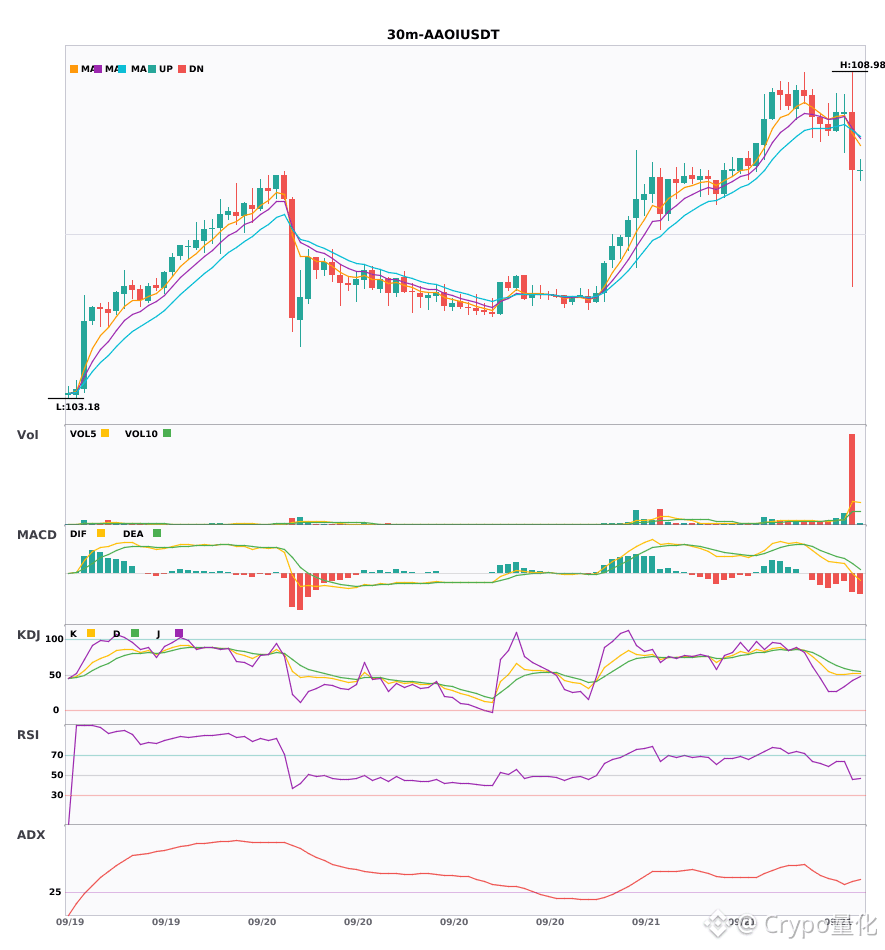
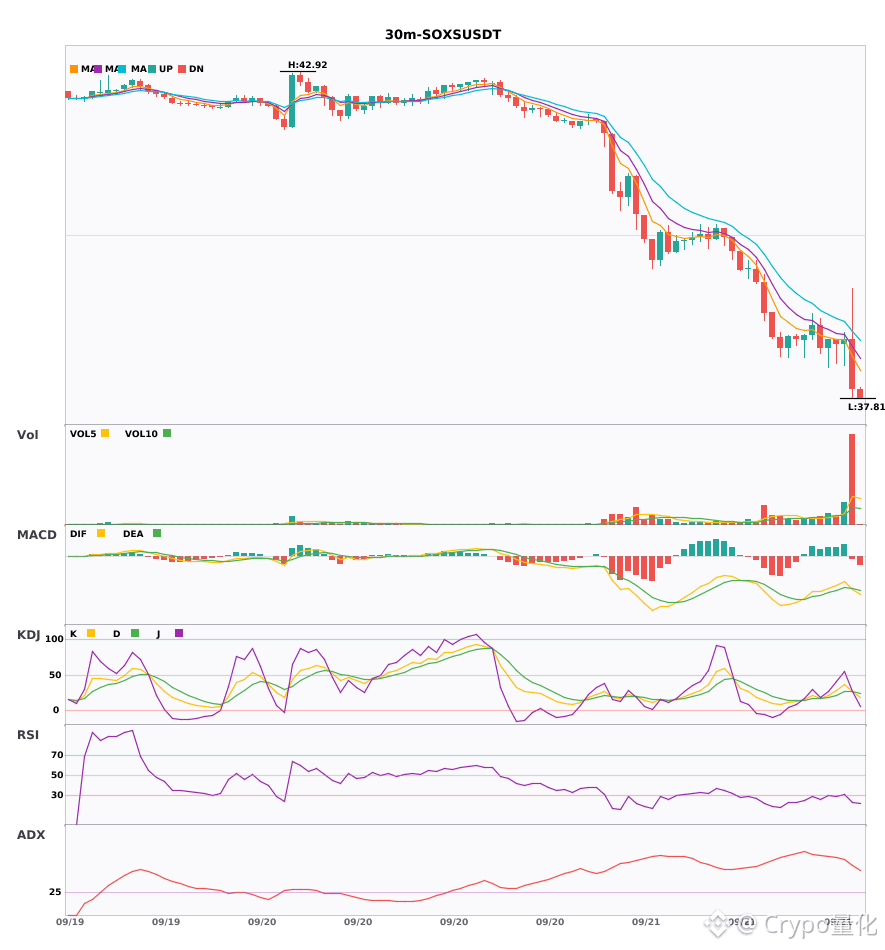
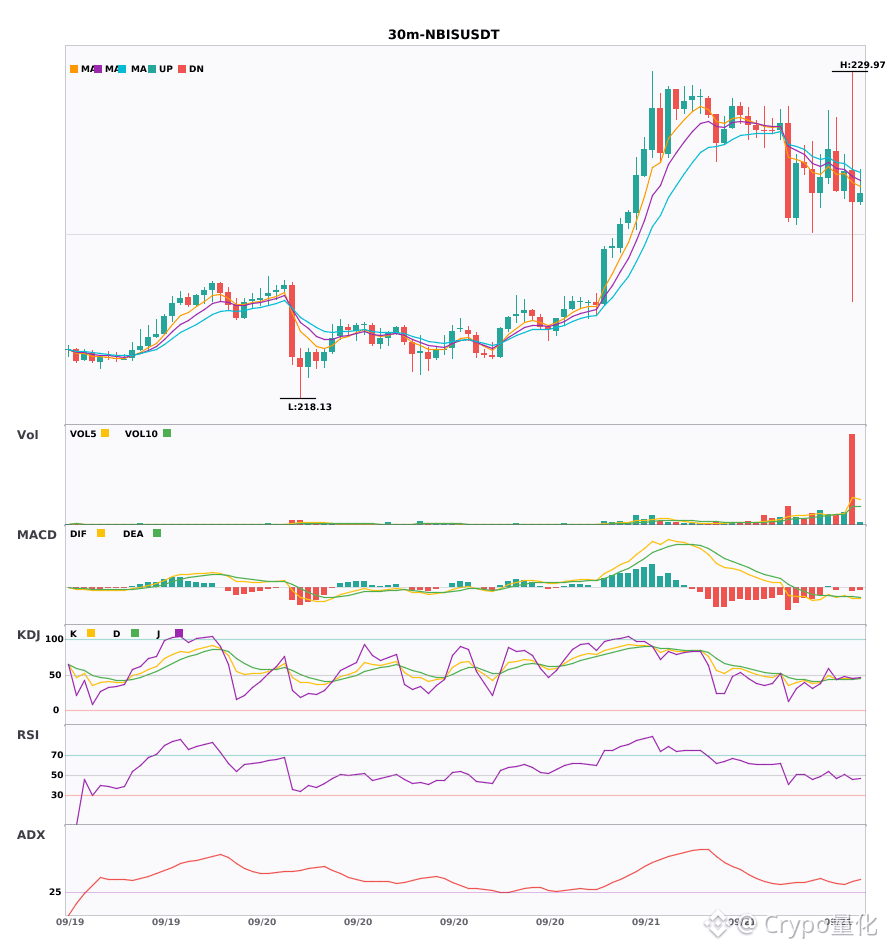
$AAOI / $SOXS / $NBIS 30 minutes technical analysis synchronously weakens; watch out for risks
📉 $AAOI | 30-minute bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (36) clearly shows a trending market | MACD DIF breaks below the zero line, trend turns bearish | EMA5 crosses below EMA8, short-term turns bearish | KDJ is running strongly, bulls still dominant (K is 51.8, D is 56.6) | Volume spikes (6.7x)
Price change: -0.9500%
📉 $SOXS | 30-minute bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (54) is a very strong trend (be cautious of an overheated pullback) | MACD dead cross below zero, bearish momentum accelerates | EMA5 is below EMA8 and EMA13; bearish alignment | KDJ runs weakly, bears dominant (K is 26.6, D is 26.5) | Volume spikes (5.2x)
Price change: -2.0400%
📌 Market update: Binance Will Support the Direxion Daily Semiconductor Bear 3X Shares (SOXS), Direxion Daily MU Bull 2X Shares (MUU), ProShares UltraPro QQQ (TQQQ), and ProShares UltraPro Short QQQ (SQQQ) Cash Dividend Distribution via bStocks
📉 $NBIS | 30-minute bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (38) clearly shows a trending market | MACD dead cross below zero, bearish momentum accelerates | EMA5 is below EMA8 and EMA13; bearish alignment | KDJ runs weakly, bears dominant (K is 44.5, D is 44.3) | Volume spikes (4.8x)
Price change: -0.5000%
━━━━━━━━━━━━━━━━━━
#技术分析 #AAOI #SOXS #NBIS
📌 The above content is for reference only and does not constitute investment advice
$AAOI / $SOXS / $NBIS 30 minutes technical analysis synchronously weakens; watch out for risks
📉 $AAOI | 30-minute bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (36) clearly shows a trending market | MACD DIF breaks below the zero line, trend turns bearish | EMA5 crosses below EMA8, short-term turns bearish | KDJ is running strongly, bulls still dominant (K is 51.8, D is 56.6) | Volume spikes (6.7x)
Price change: -0.9500%
📉 $SOXS | 30-minute bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (54) is a very strong trend (be cautious of an overheated pullback) | MACD dead cross below zero, bearish momentum accelerates | EMA5 is below EMA8 and EMA13; bearish alignment | KDJ runs weakly, bears dominant (K is 26.6, D is 26.5) | Volume spikes (5.2x)
Price change: -2.0400%
📌 Market update: Binance Will Support the Direxion Daily Semiconductor Bear 3X Shares (SOXS), Direxion Daily MU Bull 2X Shares (MUU), ProShares UltraPro QQQ (TQQQ), and ProShares UltraPro Short QQQ (SQQQ) Cash Dividend Distribution via bStocks
📉 $NBIS | 30-minute bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (38) clearly shows a trending market | MACD dead cross below zero, bearish momentum accelerates | EMA5 is below EMA8 and EMA13; bearish alignment | KDJ runs weakly, bears dominant (K is 44.5, D is 44.3) | Volume spikes (4.8x)
Price change: -0.5000%
━━━━━━━━━━━━━━━━━━
#技术分析 #AAOI #SOXS #NBIS
📌 The above content is for reference only and does not constitute investment advice
📉 $AAOI | 30-minute bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (36) clearly shows a trending market | MACD DIF breaks below the zero line, trend turns bearish | EMA5 crosses below EMA8, short-term turns bearish | KDJ is running strongly, bulls still dominant (K is 51.8, D is 56.6) | Volume spikes (6.7x)
Price change: -0.9500%
📉 $SOXS | 30-minute bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (54) is a very strong trend (be cautious of an overheated pullback) | MACD dead cross below zero, bearish momentum accelerates | EMA5 is below EMA8 and EMA13; bearish alignment | KDJ runs weakly, bears dominant (K is 26.6, D is 26.5) | Volume spikes (5.2x)
Price change: -2.0400%
📌 Market update: Binance Will Support the Direxion Daily Semiconductor Bear 3X Shares (SOXS), Direxion Daily MU Bull 2X Shares (MUU), ProShares UltraPro QQQ (TQQQ), and ProShares UltraPro Short QQQ (SQQQ) Cash Dividend Distribution via bStocks
📉 $NBIS | 30-minute bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (38) clearly shows a trending market | MACD dead cross below zero, bearish momentum accelerates | EMA5 is below EMA8 and EMA13; bearish alignment | KDJ runs weakly, bears dominant (K is 44.5, D is 44.3) | Volume spikes (4.8x)
Price change: -0.5000%
━━━━━━━━━━━━━━━━━━
#技术分析 #AAOI #SOXS #NBIS
📌 The above content is for reference only and does not constitute investment advice
226
·
--
Three 30-minute-level bearish early warnings: $AAOI / $SOXS / $NBIS🔥
════════════════════
🟢 $AAOI 30-minute bearish signal
⚠️ Technicals: ADX (36) clearly indicates a trending market | MACD DIF breaks below the zero line, trend turns bearish | EMA5 crosses below EMA8, short-term turns bearish | KDJ runs strongly, bulls dominate (K is 51.8, D is 56.6) | Volume surge (6.7x)
════════════════════
🟢 $SOXS 30-minute bearish signal
⚠️ Technicals: ADX (54) very strong trend (watch for overheated pullback) | MACD below zero with a dead cross, shorts accelerate | EMA5 < EMA8 < EMA13, bearish alignment | KDJ runs weakly, shorts dominate (K is 26.6, D is 26.5) | Volume surge (5.2x)
📢 Market update: Binance will support the cash dividend distribution via bStocks for Direxion Daily Semiconductor Bear 3X Shares (SOXS), Direxion Daily MU Bull 2X Shares (MUU), ProShares UltraPro QQQ (TQQQ), and ProShares UltraPro Short QQQ (SQQQ)
════════════════════
🟢 $NBIS 30-minute bearish signal
⚠️ Technicals: ADX (38) clearly indicates a trending market | MACD dead cross below zero, shorts accelerate | EMA5 < EMA8 < EMA13, bearish alignment | KDJ runs weakly, shorts dominate (K is 44.5, D is 44.3) | Volume surge (4.8x)
════════════════════
🔔 Follow to get the first-hand market moves and anomalies 🔔
#技术分析 #AAOI #SOXS #NBIS
📌 When trading, pay attention to whether the candlestick patterns match
Three 30-minute-level bearish early warnings: $AAOI / $SOXS / $NBIS 🔥
════════════════════
🟢 $AAOI 30-minute bearish signal
⚠️ Technicals: ADX (36) clearly indicates a trending market | MACD DIF breaks below the zero line, trend turns bearish | EMA5 crosses below EMA8, short-term turns bearish | KDJ runs strongly, bulls dominate (K is 51.8, D is 56.6) | Volume surge (6.7x)
════════════════════
🟢 $SOXS 30-minute bearish signal
⚠️ Technicals: ADX (54) very strong trend (watch for overheated pullback) | MACD below zero with a dead cross, shorts accelerate | EMA5 < EMA8 < EMA13, bearish alignment | KDJ runs weakly, shorts dominate (K is 26.6, D is 26.5) | Volume surge (5.2x)
📢 Market update: Binance will support the cash dividend distribution via bStocks for Direxion Daily Semiconductor Bear 3X Shares (SOXS), Direxion Daily MU Bull 2X Shares (MUU), ProShares UltraPro QQQ (TQQQ), and ProShares UltraPro Short QQQ (SQQQ)
════════════════════
🟢 $NBIS 30-minute bearish signal
⚠️ Technicals: ADX (38) clearly indicates a trending market | MACD dead cross below zero, shorts accelerate | EMA5 < EMA8 < EMA13, bearish alignment | KDJ runs weakly, shorts dominate (K is 44.5, D is 44.3) | Volume surge (4.8x)
════════════════════
🔔 Follow to get the first-hand market moves and anomalies 🔔
#技术分析 #AAOI #SOXS #NBIS
📌 When trading, pay attention to whether the candlestick patterns match
════════════════════
🟢 $AAOI 30-minute bearish signal
⚠️ Technicals: ADX (36) clearly indicates a trending market | MACD DIF breaks below the zero line, trend turns bearish | EMA5 crosses below EMA8, short-term turns bearish | KDJ runs strongly, bulls dominate (K is 51.8, D is 56.6) | Volume surge (6.7x)
════════════════════
🟢 $SOXS 30-minute bearish signal
⚠️ Technicals: ADX (54) very strong trend (watch for overheated pullback) | MACD below zero with a dead cross, shorts accelerate | EMA5 < EMA8 < EMA13, bearish alignment | KDJ runs weakly, shorts dominate (K is 26.6, D is 26.5) | Volume surge (5.2x)
📢 Market update: Binance will support the cash dividend distribution via bStocks for Direxion Daily Semiconductor Bear 3X Shares (SOXS), Direxion Daily MU Bull 2X Shares (MUU), ProShares UltraPro QQQ (TQQQ), and ProShares UltraPro Short QQQ (SQQQ)
════════════════════
🟢 $NBIS 30-minute bearish signal
⚠️ Technicals: ADX (38) clearly indicates a trending market | MACD dead cross below zero, shorts accelerate | EMA5 < EMA8 < EMA13, bearish alignment | KDJ runs weakly, shorts dominate (K is 44.5, D is 44.3) | Volume surge (4.8x)
════════════════════
🔔 Follow to get the first-hand market moves and anomalies 🔔
#技术分析 #AAOI #SOXS #NBIS
📌 When trading, pay attention to whether the candlestick patterns match
13
·
--
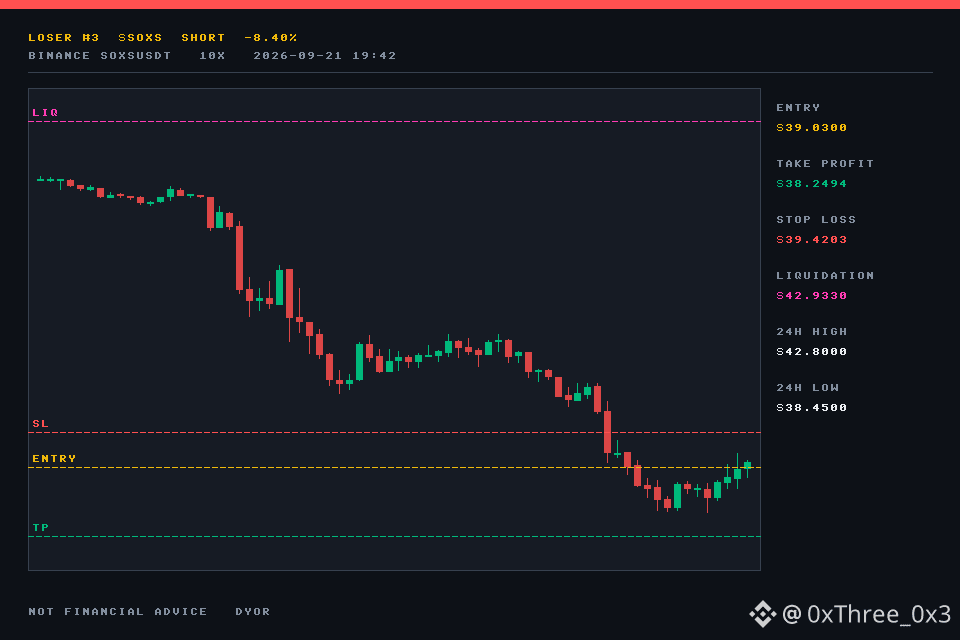
$SOXS This volatility isn’t small. In the past 24h, the rise/fall is -8.40%, and the current price is around $39.0300.
My take: bearish. Weakness is likely to keep pressing down; I’ll take a look at it on a 10x view. Today’s price range is $38.4500 - $42.8000.
Planned levels: entry $39.0300, take profit $38.2494, stop loss $39.4203, liquidation reference $42.9330. Time point 09-21 19:42.
Don’t chase too aggressively—wait for the next 15m candlestick confirmation for more confidence.
#SOXS #BinanceSquare #CryptoSignal #Futures
$SOXS This volatility isn’t small. In the past 24h, the rise/fall is -8.40%, and the current price is around $39.0300.
My take: bearish. Weakness is likely to keep pressing down; I’ll take a look at it on a 10x view. Today’s price range is $38.4500 - $42.8000.
Planned levels: entry $39.0300, take profit $38.2494, stop loss $39.4203, liquidation reference $42.9330. Time point 09-21 19:42.
Don’t chase too aggressively—wait for the next 15m candlestick confirmation for more confidence.
#SOXS #BinanceSquare #CryptoSignal #Futures
My take: bearish. Weakness is likely to keep pressing down; I’ll take a look at it on a 10x view. Today’s price range is $38.4500 - $42.8000.
Planned levels: entry $39.0300, take profit $38.2494, stop loss $39.4203, liquidation reference $42.9330. Time point 09-21 19:42.
Don’t chase too aggressively—wait for the next 15m candlestick confirmation for more confidence.
#SOXS #BinanceSquare #CryptoSignal #Futures
1
·
--
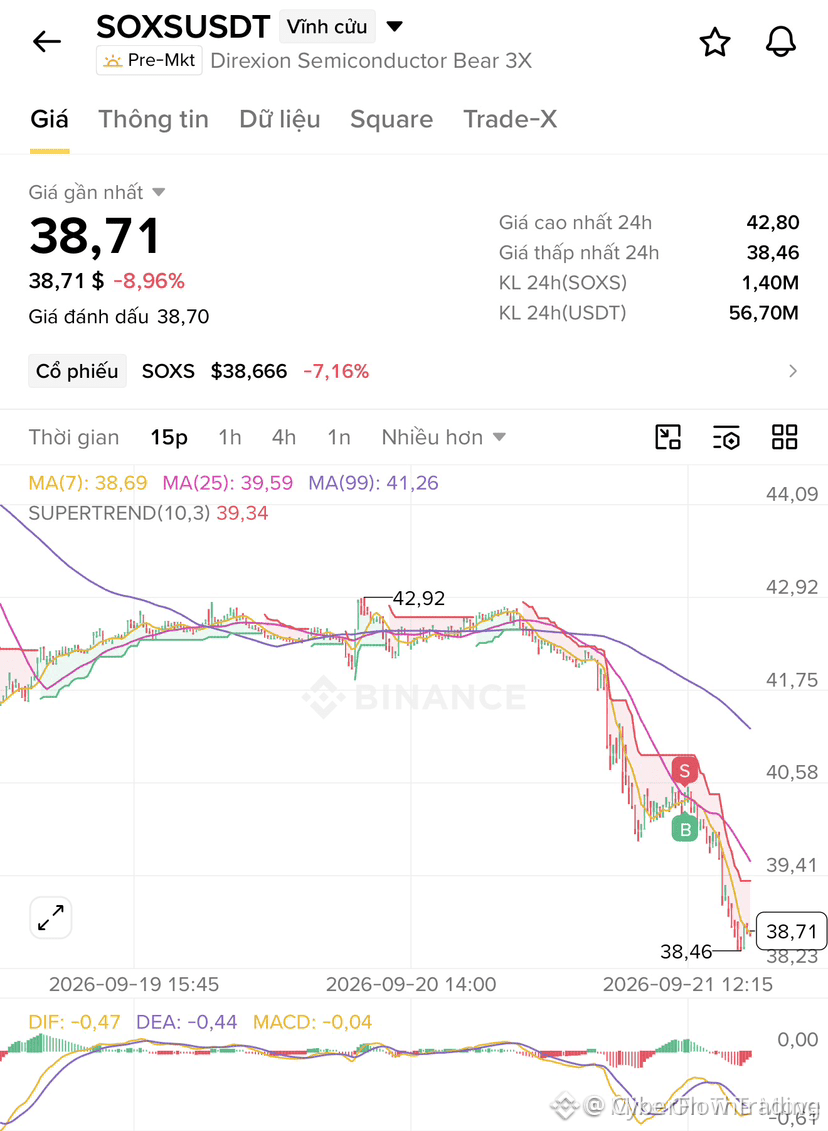
$SOXS fell from 42.8 to 38.47, then bounced back to 38.55. In just one hour, this needle covered the same range that others took a full day to move—down 9.12% at the close.
The trading value of 54 million isn’t small, but the pullback strength was clearly insufficient. After the shorts slammed it down, the longs didn’t catch it much. Funding rate is +0.0177%, within the normal range. Bulls and bears were not thrown out of balance—this was purely a liquidity stampede. The key support is at 38.47, the lower shadow. If that breaks, it becomes an acceleration phase. On the upside, resistance is around 42.8, the previous swing low from this leg’s selloff.
Set the stop-loss 0.5 points below 38.47. First look for a rebound to 40.3, and take half of it from there. Then we’ll see whether 42.8 can be touched before deciding the next move.
The pinned comparison post at the top of the homepage reviews how this same pattern has played out a few times—after reading it, you’ll have a better sense of what to expect.
#SOXS
$SOXS fell from 42.8 to 38.47, then bounced back to 38.55. In just one hour, this needle covered the same range that others took a full day to move—down 9.12% at the close.
The trading value of 54 million isn’t small, but the pullback strength was clearly insufficient. After the shorts slammed it down, the longs didn’t catch it much. Funding rate is +0.0177%, within the normal range. Bulls and bears were not thrown out of balance—this was purely a liquidity stampede. The key support is at 38.47, the lower shadow. If that breaks, it becomes an acceleration phase. On the upside, resistance is around 42.8, the previous swing low from this leg’s selloff.
Set the stop-loss 0.5 points below 38.47. First look for a rebound to 40.3, and take half of it from there. Then we’ll see whether 42.8 can be touched before deciding the next move.
The pinned comparison post at the top of the homepage reviews how this same pattern has played out a few times—after reading it, you’ll have a better sense of what to expect.
#SOXS
The trading value of 54 million isn’t small, but the pullback strength was clearly insufficient. After the shorts slammed it down, the longs didn’t catch it much. Funding rate is +0.0177%, within the normal range. Bulls and bears were not thrown out of balance—this was purely a liquidity stampede. The key support is at 38.47, the lower shadow. If that breaks, it becomes an acceleration phase. On the upside, resistance is around 42.8, the previous swing low from this leg’s selloff.
Set the stop-loss 0.5 points below 38.47. First look for a rebound to 40.3, and take half of it from there. Then we’ll see whether 42.8 can be touched before deciding the next move.
The pinned comparison post at the top of the homepage reviews how this same pattern has played out a few times—after reading it, you’ll have a better sense of what to expect.
#SOXS
112
·
--
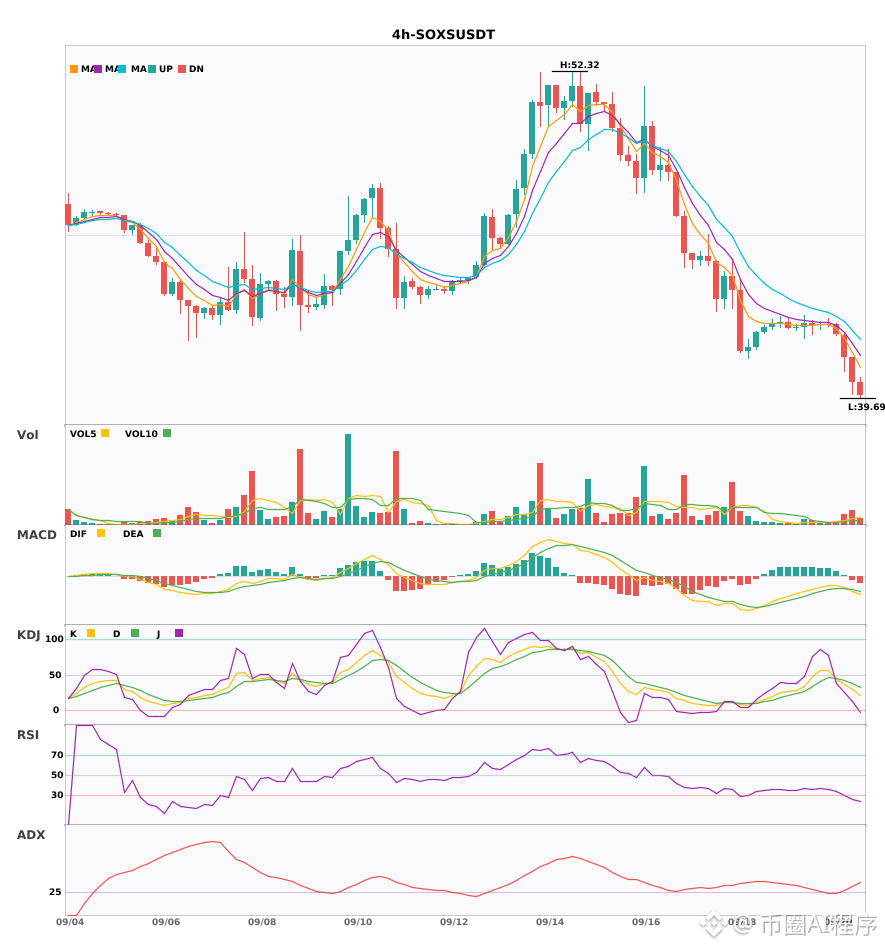
$SOXS 4 hour daily line same-direction bearish multi-period resonance following trend short🔥
════════════════════
🟢 $SOXS 4 hour Bearish Signal
⚠️ Technical Analysis: Daily line bearish resonance confirmed | 4-hour entry MACD dead cross below zero, bearish momentum accelerating | EMA5 < EMA8 < EMA13 bearish alignment | KDJ running weakly, bearish advantage (K is 29.9, D is 38.3) | Volume surge (3.3x)
════════════════════
🔔 Watch for the first-hand market movement 🔔
#多周期共振 #SOXS
📌 When trading, pay attention to whether the candlestick pattern matches
$SOXS 4 hour daily line same-direction bearish multi-period resonance following trend short🔥
════════════════════
🟢 $SOXS 4 hour Bearish Signal
⚠️ Technical Analysis: Daily line bearish resonance confirmed | 4-hour entry MACD dead cross below zero, bearish momentum accelerating | EMA5 < EMA8 < EMA13 bearish alignment | KDJ running weakly, bearish advantage (K is 29.9, D is 38.3) | Volume surge (3.3x)
════════════════════
🔔 Watch for the first-hand market movement 🔔
#多周期共振 #SOXS
📌 When trading, pay attention to whether the candlestick pattern matches
════════════════════
🟢 $SOXS 4 hour Bearish Signal
⚠️ Technical Analysis: Daily line bearish resonance confirmed | 4-hour entry MACD dead cross below zero, bearish momentum accelerating | EMA5 < EMA8 < EMA13 bearish alignment | KDJ running weakly, bearish advantage (K is 29.9, D is 38.3) | Volume surge (3.3x)
════════════════════
🔔 Watch for the first-hand market movement 🔔
#多周期共振 #SOXS
📌 When trading, pay attention to whether the candlestick pattern matches
181

·
--
$SOXS 24 hours saw a drop of 4.53%, and the price reached 40.44. Meanwhile, its perpetual contract funding rate is 0.
This structure tells me that the decline is driven by the underlying (spot) stock layer, not by extreme sentiment in the futures/derivatives market. $SOXS is an ETF that delivers triple short exposure to the semiconductor index; its current price movement directly reflects short-term pullback pressure across global tech stocks—especially the semiconductor sector. With the funding rate at zero, it means that during the decline led by spot, neither side of the contract market paid additional borrowing costs, and there are no clear signs of a squeeze.
Single-signal inference. With no additional news catalyst or open interest (OI) abnormality to back it up, I currently define this as a normal pullback triggered by macro sector rotation. The neutral funding rate suggests that the long and short forces are temporarily balanced, with neither side being overly punished.
The strongest point of contrary evidence is this: if the semiconductor sector receives strong buying at this level, or if key technology company earnings come in above expectations, $SOXS would rebound quickly. Then the current rationale for the decline would be falsified. In addition, if its funding rate suddenly turns negative and the price continues to fall, that would indicate that short sentiment is starting to become crowded, which could trigger a rebound.
Trading conclusion: it is not suitable to chase a short position right now.
Trading tag: #TradFi #链上美股 #SOXS
Where do you think this framework is most likely to be wrong?
$SOXS 24 hours saw a drop of 4.53%, and the price reached 40.44. Meanwhile, its perpetual contract funding rate is 0.
This structure tells me that the decline is driven by the underlying (spot) stock layer, not by extreme sentiment in the futures/derivatives market. $SOXS is an ETF that delivers triple short exposure to the semiconductor index; its current price movement directly reflects short-term pullback pressure across global tech stocks—especially the semiconductor sector. With the funding rate at zero, it means that during the decline led by spot, neither side of the contract market paid additional borrowing costs, and there are no clear signs of a squeeze.
Single-signal inference. With no additional news catalyst or open interest (OI) abnormality to back it up, I currently define this as a normal pullback triggered by macro sector rotation. The neutral funding rate suggests that the long and short forces are temporarily balanced, with neither side being overly punished.
The strongest point of contrary evidence is this: if the semiconductor sector receives strong buying at this level, or if key technology company earnings come in above expectations, $SOXS would rebound quickly. Then the current rationale for the decline would be falsified. In addition, if its funding rate suddenly turns negative and the price continues to fall, that would indicate that short sentiment is starting to become crowded, which could trigger a rebound.
Trading conclusion: it is not suitable to chase a short position right now.
Trading tag: #TradFi #链上美股 #SOXS
Where do you think this framework is most likely to be wrong?
This structure tells me that the decline is driven by the underlying (spot) stock layer, not by extreme sentiment in the futures/derivatives market. $SOXS is an ETF that delivers triple short exposure to the semiconductor index; its current price movement directly reflects short-term pullback pressure across global tech stocks—especially the semiconductor sector. With the funding rate at zero, it means that during the decline led by spot, neither side of the contract market paid additional borrowing costs, and there are no clear signs of a squeeze.
Single-signal inference. With no additional news catalyst or open interest (OI) abnormality to back it up, I currently define this as a normal pullback triggered by macro sector rotation. The neutral funding rate suggests that the long and short forces are temporarily balanced, with neither side being overly punished.
The strongest point of contrary evidence is this: if the semiconductor sector receives strong buying at this level, or if key technology company earnings come in above expectations, $SOXS would rebound quickly. Then the current rationale for the decline would be falsified. In addition, if its funding rate suddenly turns negative and the price continues to fall, that would indicate that short sentiment is starting to become crowded, which could trigger a rebound.
Trading conclusion: it is not suitable to chase a short position right now.
Trading tag: #TradFi #链上美股 #SOXS
Where do you think this framework is most likely to be wrong?
296
·
--
Bullish
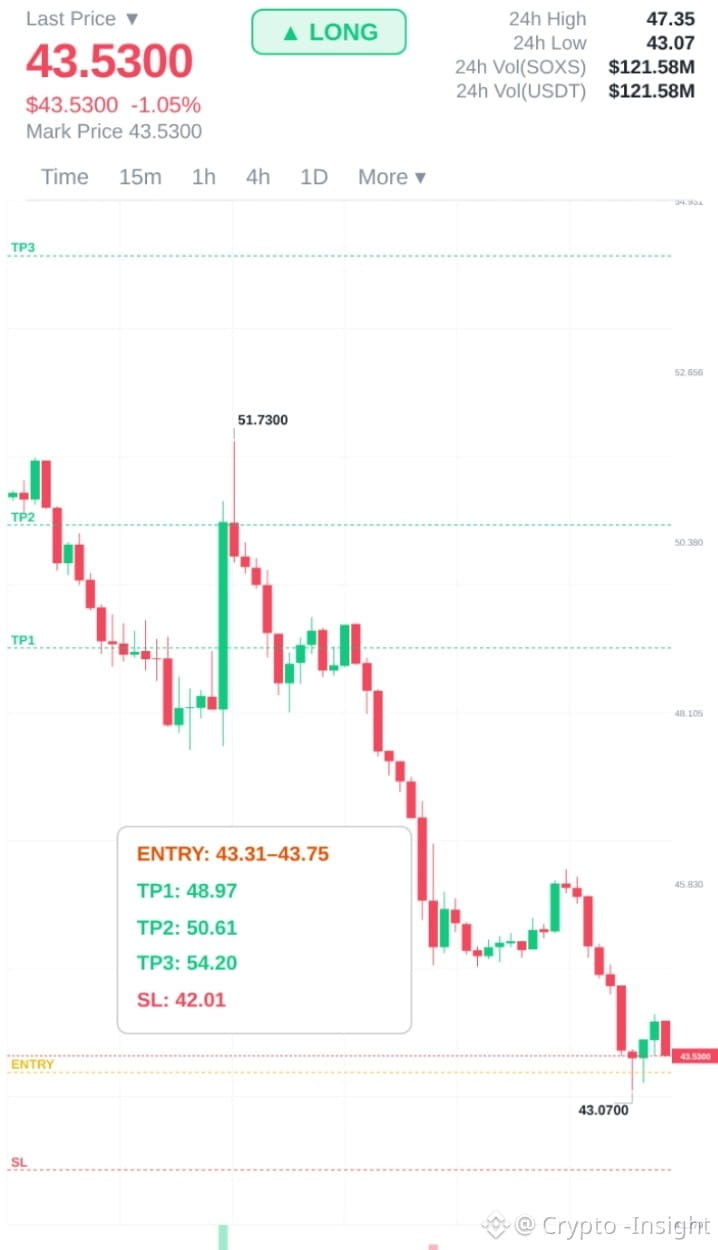
$SOXS Bulls Are Defending The Breakout Zone…!!
#SOXS is holding bullish momentum around 43.5300 with buyers defending the 43.31 to 43.75 zone and resistance building near 47.35 If momentum continues the next targets could be 48.97 and 50.61 while 43.07 remains the key support zone$UNI
{spot}(UNIUSDT)
$STRK
{spot}(STRKUSDT)
{future}(SOXSUSDT)
$SOXS Bulls Are Defending The Breakout Zone…!!
#SOXS is holding bullish momentum around 43.5300 with buyers defending the 43.31 to 43.75 zone and resistance building near 47.35 If momentum continues the next targets could be 48.97 and 50.61 while 43.07 remains the key support zone$UNI
$STRK
#SOXS is holding bullish momentum around 43.5300 with buyers defending the 43.31 to 43.75 zone and resistance building near 47.35 If momentum continues the next targets could be 48.97 and 50.61 while 43.07 remains the key support zone$UNI
$STRK
1
96
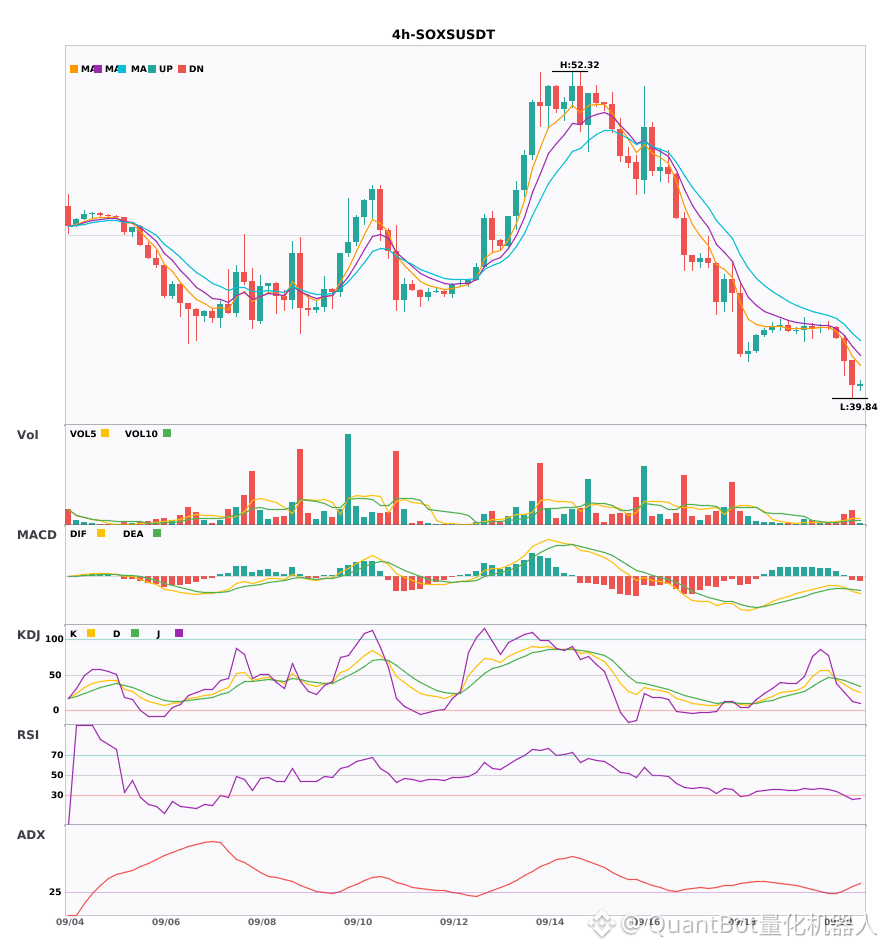
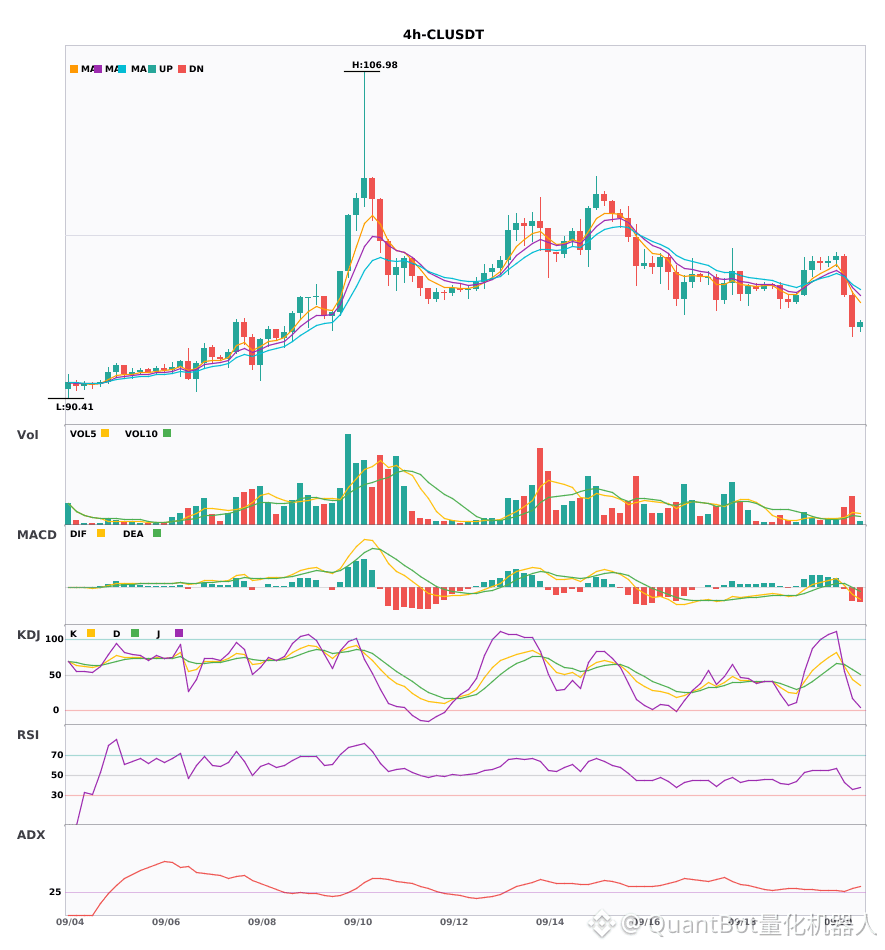
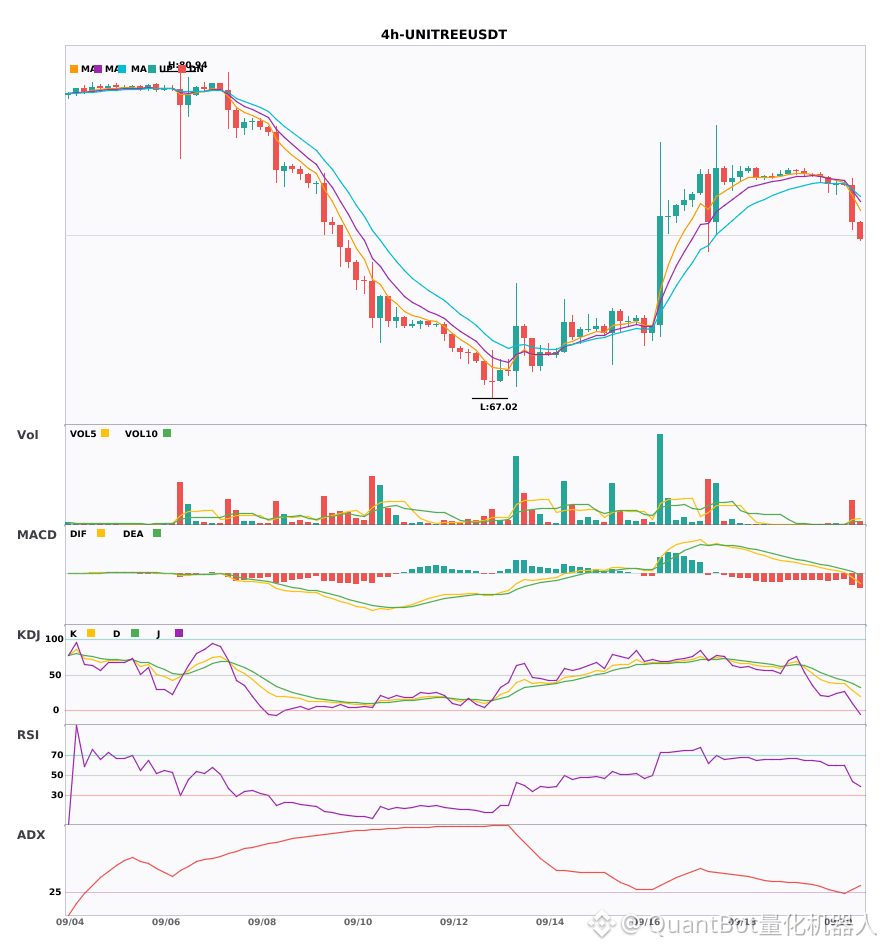
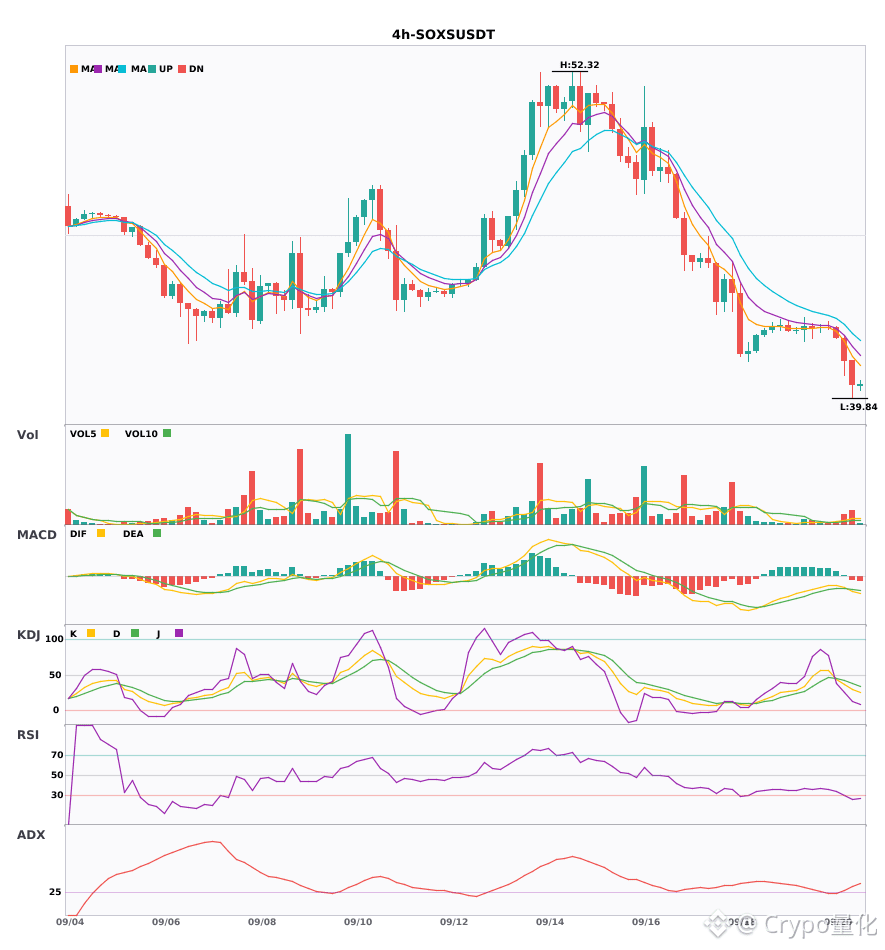
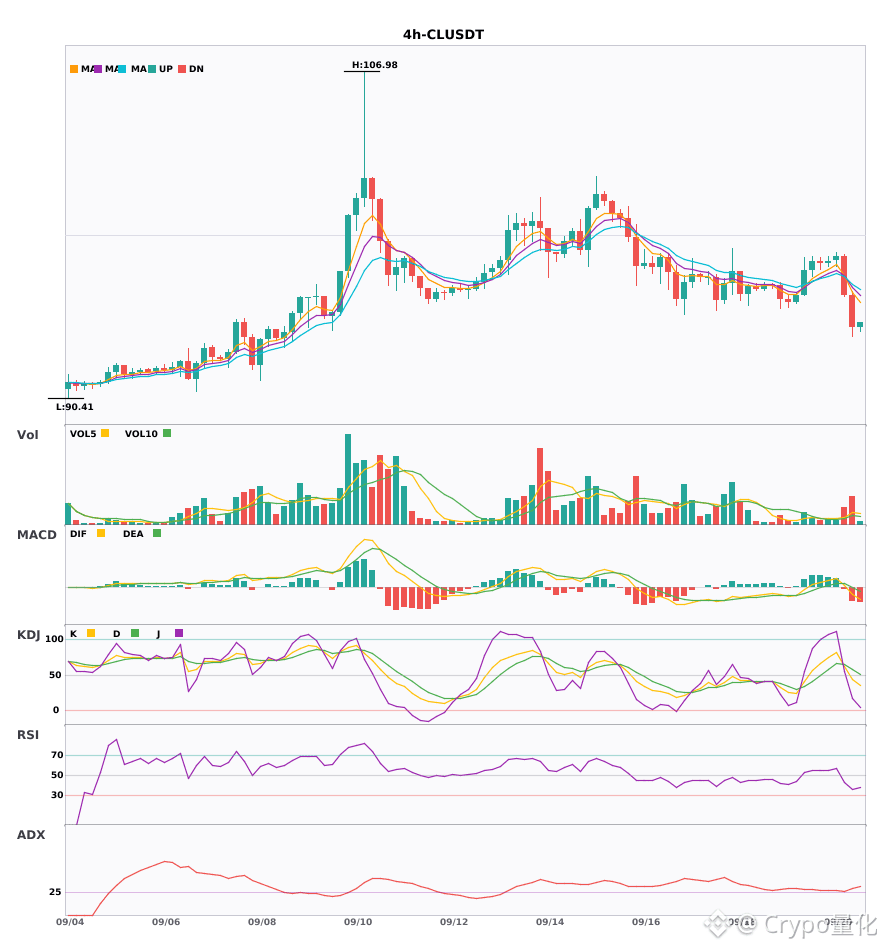
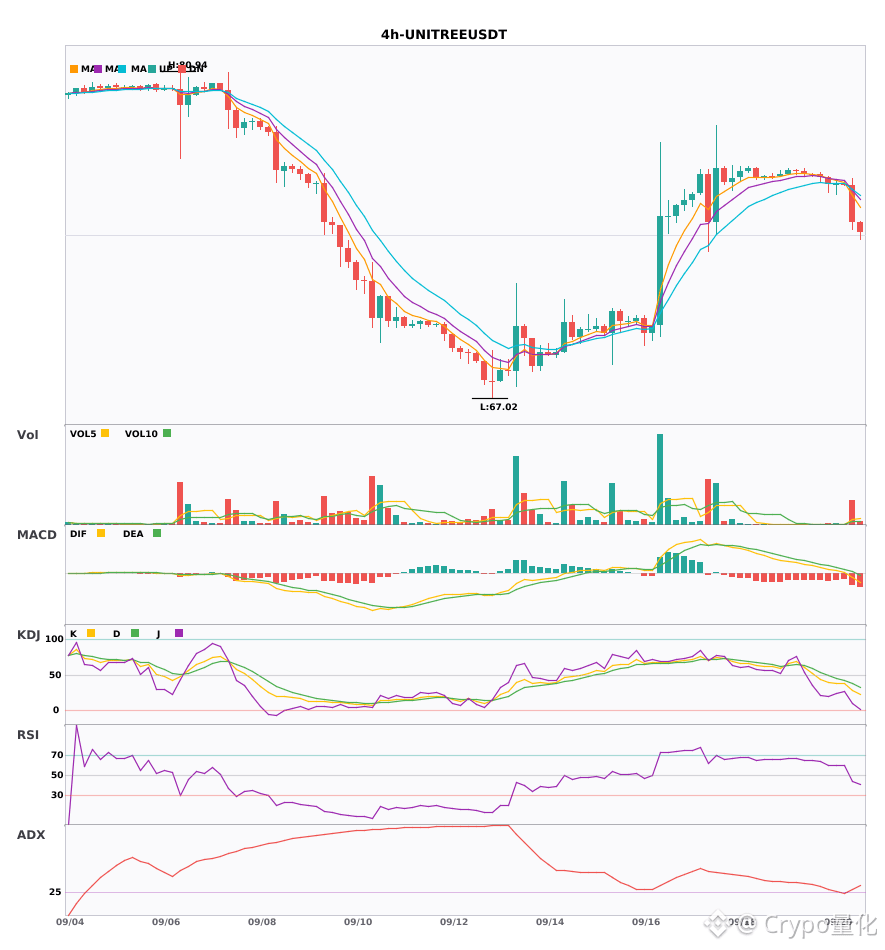
Three 4-hour level bearish warnings: $SOXS / $CL / $UNITREE
📉 $SOXS | 4-hour bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (31) clearly shows a trending market | MACD forms a bearish dead cross below zero, and bearish momentum accelerates | EMA5 < EMA8 < EMA13, bearish alignment | KDJ is weak, with bears in control (K is 29.9, D is 38.3) | Volume spikes (3.3x)
Price change: -2.2800%
📉 $CL | 4-hour bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX reports 33, the trend is clear; MACD DIF breaks below the zero line, turning bearish; EMA5 crosses below EMA8, turning bearish in the short term; volume expands to 3.0x.
Price change: -1.6900%
📉 $UNITREE | 4-hour bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (31) clearly shows a trending market | MACD DIF breaks below the zero line, turning bearish | EMA5 < EMA8 < EMA13, bearish alignment | KDJ is weak, with bears in control (K is 28.8, D is 38.2) | Volume explodes (7.8x)
Price change: -2.0800%
━━━━━━━━━━━━━━━━━━
#技术分析 #SOXS #CL #UNITREE
📌 The content above is for reference only and does not constitute investment advice
Three 4-hour level bearish warnings: $SOXS / $CL / $UNITREE
📉 $SOXS | 4-hour bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (31) clearly shows a trending market | MACD forms a bearish dead cross below zero, and bearish momentum accelerates | EMA5 < EMA8 < EMA13, bearish alignment | KDJ is weak, with bears in control (K is 29.9, D is 38.3) | Volume spikes (3.3x)
Price change: -2.2800%
📉 $CL | 4-hour bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX reports 33, the trend is clear; MACD DIF breaks below the zero line, turning bearish; EMA5 crosses below EMA8, turning bearish in the short term; volume expands to 3.0x.
Price change: -1.6900%
📉 $UNITREE | 4-hour bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (31) clearly shows a trending market | MACD DIF breaks below the zero line, turning bearish | EMA5 < EMA8 < EMA13, bearish alignment | KDJ is weak, with bears in control (K is 28.8, D is 38.2) | Volume explodes (7.8x)
Price change: -2.0800%
━━━━━━━━━━━━━━━━━━
#技术分析 #SOXS #CL #UNITREE
📌 The content above is for reference only and does not constitute investment advice
📉 $SOXS | 4-hour bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (31) clearly shows a trending market | MACD forms a bearish dead cross below zero, and bearish momentum accelerates | EMA5 < EMA8 < EMA13, bearish alignment | KDJ is weak, with bears in control (K is 29.9, D is 38.3) | Volume spikes (3.3x)
Price change: -2.2800%
📉 $CL | 4-hour bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX reports 33, the trend is clear; MACD DIF breaks below the zero line, turning bearish; EMA5 crosses below EMA8, turning bearish in the short term; volume expands to 3.0x.
Price change: -1.6900%
📉 $UNITREE | 4-hour bearish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (31) clearly shows a trending market | MACD DIF breaks below the zero line, turning bearish | EMA5 < EMA8 < EMA13, bearish alignment | KDJ is weak, with bears in control (K is 28.8, D is 38.2) | Volume explodes (7.8x)
Price change: -2.0800%
━━━━━━━━━━━━━━━━━━
#技术分析 #SOXS #CL #UNITREE
📌 The content above is for reference only and does not constitute investment advice
21
·
--
$SOXS / $CL / $UNITREE 4 hour level leaning bearish, pressured on the short term 🔥
════════════════════
🟢 $SOXS 4 hour bearish signal
⚠️ Technicals: ADX(31) is clearly a trending market | MACD forms a dead cross below zero, bearish momentum accelerates | EMA5 < EMA8 < EMA13, bearish alignment | KDJ weak performance, bears dominant (K is 29.9, D is 38.3) | Volume surges (3.3x)
════════════════════
🟢 $CL 4 hour bearish signal
⚠️ Technicals: ADX value is 33, clearly a trending market; MACD DIF breaks below the zero line and turns bearish, EMA5 crosses below EMA8 with short-term bearish movement, and volume explodes 3x.
════════════════════
🟢 $UNITREE 4 hour bearish signal
⚠️ Technicals: ADX(31) is clearly a trending market | MACD DIF breaks below the zero line, trend turns bearish | EMA5 < EMA8 < EMA13 bearish alignment | KDJ weak performance, bears dominant (K is 28.8, D is 38.2) | Volume surges (7.8x)
════════════════════
🔔 Follow for first-hand price-action spikes 🔔
#技术分析 #SOXS #CL #UNITREE
📌 When trading, pay attention to whether the candlestick pattern matches
$SOXS / $CL / $UNITREE 4 hour level leaning bearish, pressured on the short term 🔥
════════════════════
🟢 $SOXS 4 hour bearish signal
⚠️ Technicals: ADX(31) is clearly a trending market | MACD forms a dead cross below zero, bearish momentum accelerates | EMA5 < EMA8 < EMA13, bearish alignment | KDJ weak performance, bears dominant (K is 29.9, D is 38.3) | Volume surges (3.3x)
════════════════════
🟢 $CL 4 hour bearish signal
⚠️ Technicals: ADX value is 33, clearly a trending market; MACD DIF breaks below the zero line and turns bearish, EMA5 crosses below EMA8 with short-term bearish movement, and volume explodes 3x.
════════════════════
🟢 $UNITREE 4 hour bearish signal
⚠️ Technicals: ADX(31) is clearly a trending market | MACD DIF breaks below the zero line, trend turns bearish | EMA5 < EMA8 < EMA13 bearish alignment | KDJ weak performance, bears dominant (K is 28.8, D is 38.2) | Volume surges (7.8x)
════════════════════
🔔 Follow for first-hand price-action spikes 🔔
#技术分析 #SOXS #CL #UNITREE
📌 When trading, pay attention to whether the candlestick pattern matches
════════════════════
🟢 $SOXS 4 hour bearish signal
⚠️ Technicals: ADX(31) is clearly a trending market | MACD forms a dead cross below zero, bearish momentum accelerates | EMA5 < EMA8 < EMA13, bearish alignment | KDJ weak performance, bears dominant (K is 29.9, D is 38.3) | Volume surges (3.3x)
════════════════════
🟢 $CL 4 hour bearish signal
⚠️ Technicals: ADX value is 33, clearly a trending market; MACD DIF breaks below the zero line and turns bearish, EMA5 crosses below EMA8 with short-term bearish movement, and volume explodes 3x.
════════════════════
🟢 $UNITREE 4 hour bearish signal
⚠️ Technicals: ADX(31) is clearly a trending market | MACD DIF breaks below the zero line, trend turns bearish | EMA5 < EMA8 < EMA13 bearish alignment | KDJ weak performance, bears dominant (K is 28.8, D is 38.2) | Volume surges (7.8x)
════════════════════
🔔 Follow for first-hand price-action spikes 🔔
#技术分析 #SOXS #CL #UNITREE
📌 When trading, pay attention to whether the candlestick pattern matches
426
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#MultiversXPlansHardForkRecovery
68 views
50 Discussing
2
#CircleLaunchesInstitutionalBTCBackedBorrowing
1,417 views
212 Discussing
3
#BitcoinHits$85K
4,617 views
175 Discussing
4
#ZetaChainVotesToMigrateZETAToSolana
1,403 views
141 Discussing
5
#ECBStartsBlockchainEuroSettlement
8,851 views
432 Discussing
6
#SouthAfricaProposesCryptoExchangeControls
19,569 views
618 Discussing
7
#SolanaCutsTargetSlotTimeTo250ms
22,434 views
537 Discussing
8
#EthereumSurpasses$2700
18,095 views
212 Discussing
9
#CanaryFilesSecondAmendmentForStakedSEIETF
40,838 views
883 Discussing
10
#SaylorHintsStrategyBitcoinBuy
2.4M views
13,831 Discussing