
#gpucloud
gpucloud
309 views
7 Discussing
Hot
Latest

·
--
Article
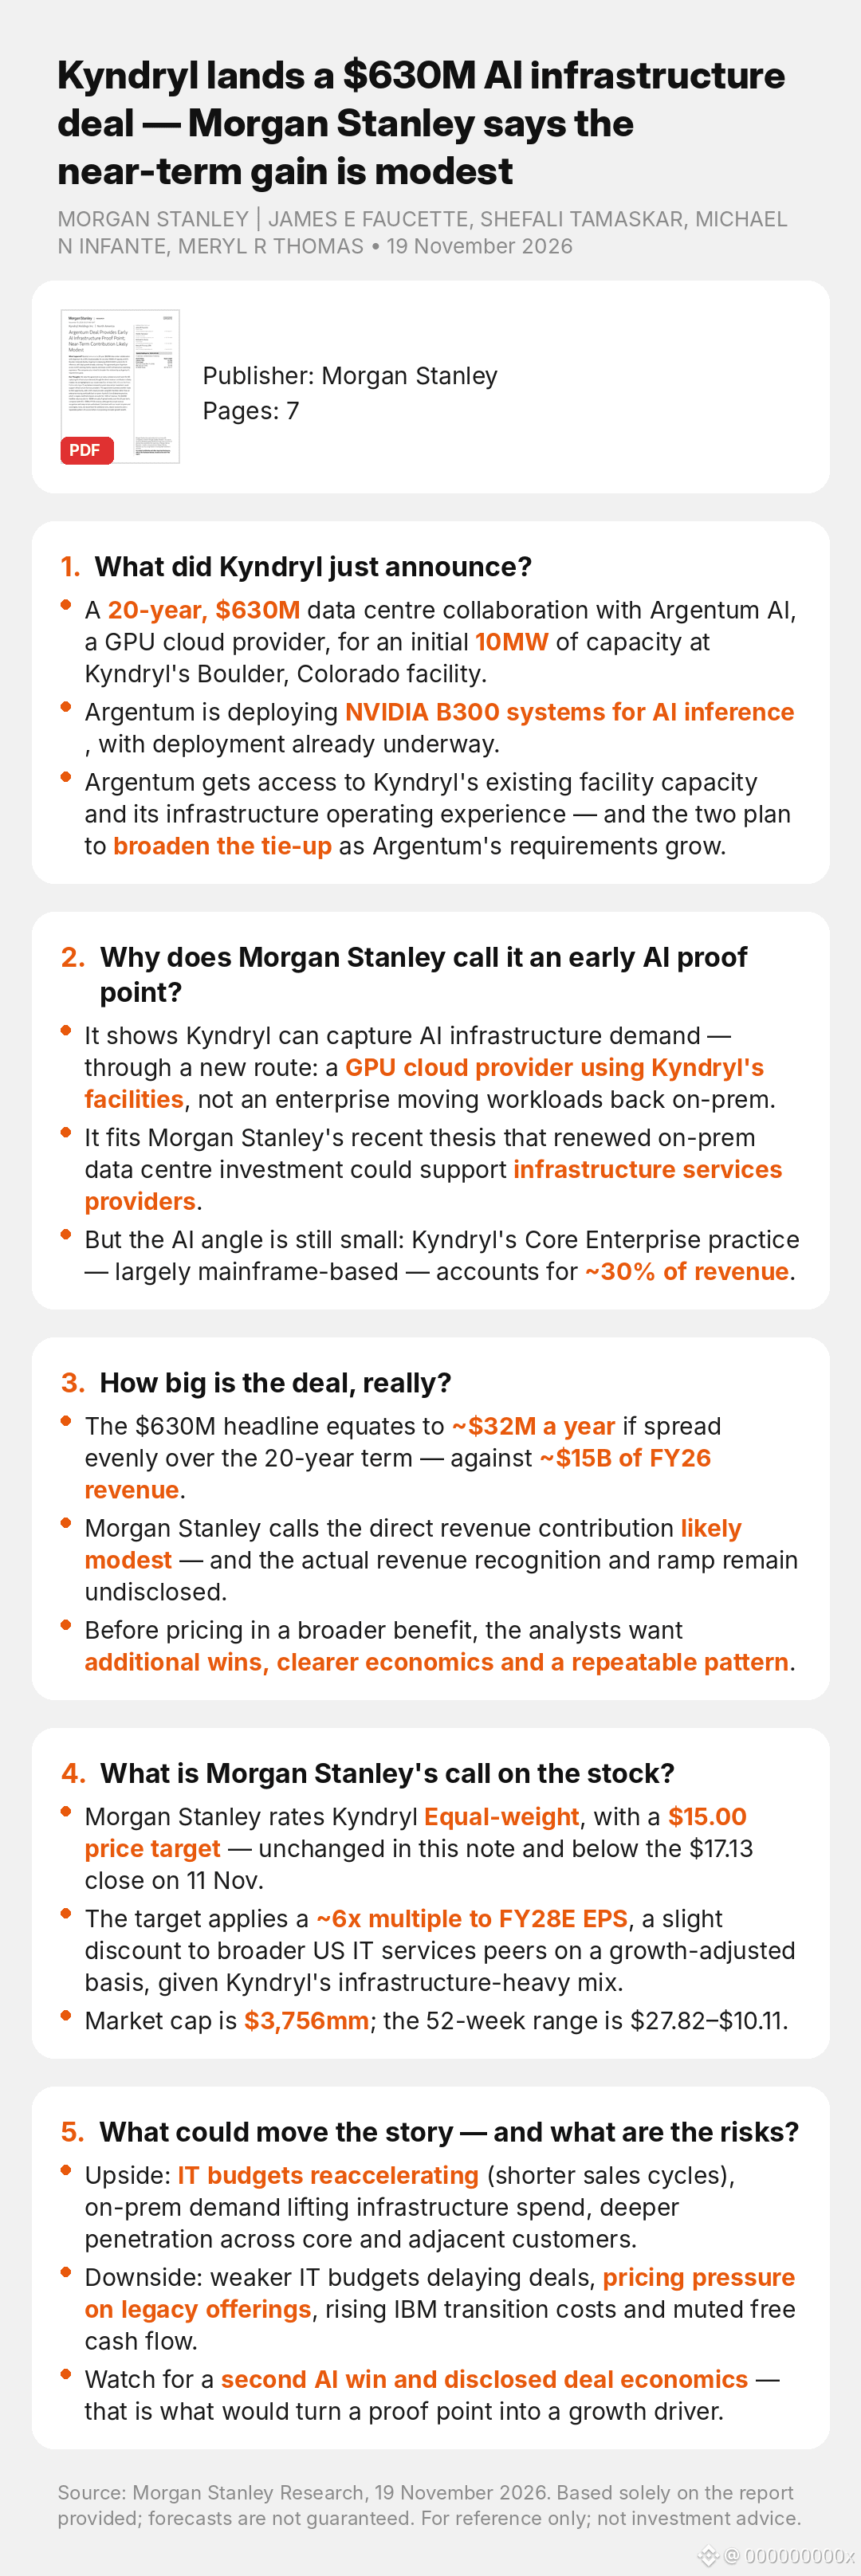
Kyndryl lands a $630M AI infrastructure deal — Morgan Stanley says the near-term gain is modestKyndryl lands a $630M AI infrastructure deal — Morgan Stanley says the near-term gain is modest
$KD
MORGAN STANLEY | JAMES E FAUCETTE, SHEFALI TAMASKAR, MICHAEL N INFANTE, MERYL R THOMAS • 19 November 2026
1. What did Kyndryl just announce?
• A 20-year, $630M data centre collaboration with Argentum AI, a GPU cloud provider, for an initial 10MW of capacity at Kyndryl's Boulder, Colorado facility.
• Argentum is deploying NVIDIA B300 systems for AI inference, with deployment already underway.
• Argentum gets access to Kyndryl's existing facility capacity and its infrastructure operating experience — and the two plan to broaden the tie-up as Argentum's requirements grow.
2. Why does Morgan Stanley call it an early AI proof point?
• It shows Kyndryl can capture AI infrastructure demand — through a new route: a GPU cloud provider using Kyndryl's facilities, not an enterprise moving workloads back on-prem.
• It fits Morgan Stanley's recent thesis that renewed on-prem data centre investment could support infrastructure services providers.
• But the AI angle is still small: Kyndryl's Core Enterprise practice — largely mainframe-based — accounts for ~30% of revenue.
3. How big is the deal, really?
• The $630M headline equates to ~$32M a year if spread evenly over the 20-year term — against ~$15B of FY26 revenue.
• Morgan Stanley calls the direct revenue contribution likely modest — and the actual revenue recognition and ramp remain undisclosed.
• Before pricing in a broader benefit, the analysts want additional wins, clearer economics and a repeatable pattern.
4. What is Morgan Stanley's call on the stock?
• Morgan Stanley rates Kyndryl Equal-weight, with a $15.00 price target — unchanged in this note and below the $17.13 close on 11 Nov.
• The target applies a ~6x multiple to FY28E EPS, a slight discount to broader US IT services peers on a growth-adjusted basis, given Kyndryl's infrastructure-heavy mix.
• Market cap is $3,756mm; the 52-week range is $27.82–$10.11.
5. What could move the story — and what are the risks?
• Upside: IT budgets reaccelerating (shorter sales cycles), on-prem demand lifting infrastructure spend, deeper penetration across core and adjacent customers.
• Downside: weaker IT budgets delaying deals, pricing pressure on legacy offerings, rising IBM transition costs and muted free cash flow.
• Watch for a second AI win and disclosed deal economics — that is what would turn a proof point into a growth driver.
#AI #DataCenters #GPUCloud #ITServices #Inference
Source: Morgan Stanley, "Argentum Deal Provides Early AI Infrastructure Proof Point; Near-Term Contribution Likely Modest", 19 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Visit unhidea.com for more of the latest sell-side research interpretations: https://unhidea.com/en/
Kyndryl lands a $630M AI infrastructure deal — Morgan Stanley says the near-term gain is modest
Kyndryl lands a $630M AI infrastructure deal — Morgan Stanley says the near-term gain is modest
$KD
MORGAN STANLEY | JAMES E FAUCETTE, SHEFALI TAMASKAR, MICHAEL N INFANTE, MERYL R THOMAS • 19 November 2026
1. What did Kyndryl just announce?
• A 20-year, $630M data centre collaboration with Argentum AI, a GPU cloud provider, for an initial 10MW of capacity at Kyndryl's Boulder, Colorado facility.
• Argentum is deploying NVIDIA B300 systems for AI inference, with deployment already underway.
• Argentum gets access to Kyndryl's existing facility capacity and its infrastructure operating experience — and the two plan to broaden the tie-up as Argentum's requirements grow.
2. Why does Morgan Stanley call it an early AI proof point?
• It shows Kyndryl can capture AI infrastructure demand — through a new route: a GPU cloud provider using Kyndryl's facilities, not an enterprise moving workloads back on-prem.
• It fits Morgan Stanley's recent thesis that renewed on-prem data centre investment could support infrastructure services providers.
• But the AI angle is still small: Kyndryl's Core Enterprise practice — largely mainframe-based — accounts for ~30% of revenue.
3. How big is the deal, really?
• The $630M headline equates to ~$32M a year if spread evenly over the 20-year term — against ~$15B of FY26 revenue.
• Morgan Stanley calls the direct revenue contribution likely modest — and the actual revenue recognition and ramp remain undisclosed.
• Before pricing in a broader benefit, the analysts want additional wins, clearer economics and a repeatable pattern.
4. What is Morgan Stanley's call on the stock?
• Morgan Stanley rates Kyndryl Equal-weight, with a $15.00 price target — unchanged in this note and below the $17.13 close on 11 Nov.
• The target applies a ~6x multiple to FY28E EPS, a slight discount to broader US IT services peers on a growth-adjusted basis, given Kyndryl's infrastructure-heavy mix.
• Market cap is $3,756mm; the 52-week range is $27.82–$10.11.
5. What could move the story — and what are the risks?
• Upside: IT budgets reaccelerating (shorter sales cycles), on-prem demand lifting infrastructure spend, deeper penetration across core and adjacent customers.
• Downside: weaker IT budgets delaying deals, pricing pressure on legacy offerings, rising IBM transition costs and muted free cash flow.
• Watch for a second AI win and disclosed deal economics — that is what would turn a proof point into a growth driver.
#AI #DataCenters #GPUCloud #ITServices #Inference
Source: Morgan Stanley, "Argentum Deal Provides Early AI Infrastructure Proof Point; Near-Term Contribution Likely Modest", 19 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Visit unhidea.com for more of the latest sell-side research interpretations: https://unhidea.com/en/
$KD
MORGAN STANLEY | JAMES E FAUCETTE, SHEFALI TAMASKAR, MICHAEL N INFANTE, MERYL R THOMAS • 19 November 2026
1. What did Kyndryl just announce?
• A 20-year, $630M data centre collaboration with Argentum AI, a GPU cloud provider, for an initial 10MW of capacity at Kyndryl's Boulder, Colorado facility.
• Argentum is deploying NVIDIA B300 systems for AI inference, with deployment already underway.
• Argentum gets access to Kyndryl's existing facility capacity and its infrastructure operating experience — and the two plan to broaden the tie-up as Argentum's requirements grow.
2. Why does Morgan Stanley call it an early AI proof point?
• It shows Kyndryl can capture AI infrastructure demand — through a new route: a GPU cloud provider using Kyndryl's facilities, not an enterprise moving workloads back on-prem.
• It fits Morgan Stanley's recent thesis that renewed on-prem data centre investment could support infrastructure services providers.
• But the AI angle is still small: Kyndryl's Core Enterprise practice — largely mainframe-based — accounts for ~30% of revenue.
3. How big is the deal, really?
• The $630M headline equates to ~$32M a year if spread evenly over the 20-year term — against ~$15B of FY26 revenue.
• Morgan Stanley calls the direct revenue contribution likely modest — and the actual revenue recognition and ramp remain undisclosed.
• Before pricing in a broader benefit, the analysts want additional wins, clearer economics and a repeatable pattern.
4. What is Morgan Stanley's call on the stock?
• Morgan Stanley rates Kyndryl Equal-weight, with a $15.00 price target — unchanged in this note and below the $17.13 close on 11 Nov.
• The target applies a ~6x multiple to FY28E EPS, a slight discount to broader US IT services peers on a growth-adjusted basis, given Kyndryl's infrastructure-heavy mix.
• Market cap is $3,756mm; the 52-week range is $27.82–$10.11.
5. What could move the story — and what are the risks?
• Upside: IT budgets reaccelerating (shorter sales cycles), on-prem demand lifting infrastructure spend, deeper penetration across core and adjacent customers.
• Downside: weaker IT budgets delaying deals, pricing pressure on legacy offerings, rising IBM transition costs and muted free cash flow.
• Watch for a second AI win and disclosed deal economics — that is what would turn a proof point into a growth driver.
#AI #DataCenters #GPUCloud #ITServices #Inference
Source: Morgan Stanley, "Argentum Deal Provides Early AI Infrastructure Proof Point; Near-Term Contribution Likely Modest", 19 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Visit unhidea.com for more of the latest sell-side research interpretations: https://unhidea.com/en/
NVDA+3.10%
MSUS-3.94%
102
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BTCReboundsAbove$60KAmidWhaleDipBuying
5,597 views
59 Discussing
2
#NvidiaLoses$2.7TrillionInMonthAndAHalf
44,691 views
209 Discussing
3
#GlobalStocksFaceLongestLosingStreakSince2023
402,328 views
2,668 Discussing
4
#BlackRockIBITPostsRecord$541MSingleDayOutflow
59,781 views
146 Discussing
5
#AnthropicPlungesTowardIPOPriceonDay2
215,608 views
1,713 Discussing
6
#TwentyOneCapitalAdds172.25BTC
105,300 views
1,117 Discussing
7
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
14,573 views
67 Discussing
8
#HKBillProposesHK$100KFineForUnauthorizedCryptoTitles
3,621 views
30 Discussing
9
#BitMineFaces$10.1BUnrealizedETHLoss
6,986 views
32 Discussing
10
#StrategyReports$35BNetReserves
3,741 views
24 Discussing