

#ai云
ai云
469 views
7 Discussing
Hot
Latest

·
--
Snagging on the BTC front: Nasdaq-listed Bitcoin mining firm Bitdeer (Bit Little Deer) mined 292.3 BTC for the week ending October 2, and sold all of it during the same period, resulting in a net gain of 0—maintaining zero holdings on its books. Estimated at about 84,800 (at current prices), this batch is roughly worth about US$24.8 million (not the actual transaction price).
Zero holdings have been set since late February this year—mine what you produce and sell it; cash is prioritized to feed AI cloud services and power infrastructure. In its August operating report: AI cloud ARR is about US$86 million, with 4,328 GPUs deployed and a utilization rate of 92%; however, Q2 gross profit was still negative at about US$8.5 million. Long-term debt is about US$1.8 billion, with cash of about US$496 million. The Malaysia 21.7MW data center is expected to be delivered in 2027 Q1, with plans to house NVIDIA GB300.
On one side, companies like MARA have started to refill their BTC holdings; on the other, Bitdeer is treating coins as cash flow to support AI. Whether the turnaround story can hold up depends on when gross profit turns positive.
$BTDR $BTC #挖矿 #AI云 #Bitdeer
81
·
--
Don’t just stare at how many points it’s up after hours.
Oracle (ORCL) delivered FY27 Q1 results after the close in the US East time on 9/10:
Total revenue of about $19.3 billion, up about +30% year over year, slightly above the LSEG estimate of about $19.14 billion;
Non-GAAP EPS of about $1.92 versus the estimate of about $1.74.
The official press release + Reuters line up.
What really tightens the market’s nerves are two things.
First is cloud infrastructure (IaaS) of about $7.4 billion, up about +121% YoY;
Total cloud of about $11.6 billion, about +62%.
Second is RPO rising to about $66.4 billion (up about $20.9 billion YoY); it also signed more than $30 billion of AI cloud contracts in the quarter.
CFO’s framing: Most of the new large deals are structured as prepaid / customer-provided hardware, and don’t add extra to the company’s planned financing.
The cash flow section is even more critical.
Operating cash flow is about $23.1 billion, but capex is about $28.5 billion, so free cash flow is still about −$5.4 billion.
Reuters notes the market originally expected it to burn more aggressively (about −$9.56 billion); about $11.36 billion in spending was cushioned by customer prepayments.
In the same period, it also completed about $20 billion of ATM share issuance.
Guidance: Full-year revenue at least $90 billion, non-GAAP EPS mentioned 8.10; Q2 revenue growth guidance 30%–34%.
Market: US East 9/10 close around 152.94 (about −5.38%);
Yahoo full day (including after-hours) around 159.1—roughly a 4% pullback relative to the close.
Don’t describe the intraday drop and the after-hours rebound as the same sentence.
I think this piece should be treated as a “order quality vs cash-burn speed” scorecard,
not a “AI must surge” slogan.
Next watch: how quickly RPO turns into revenue, and whether the prepaid model can keep easing financing pressure.
Recheck this round on Binance (Beijing time ~07:17): BTC≈76604 / ETH≈2437.
Not investment advice.
#ORCL #AI云 $ORCL

382

·
--
The AI Cloud line has moved again—this time, it’s Nebius.
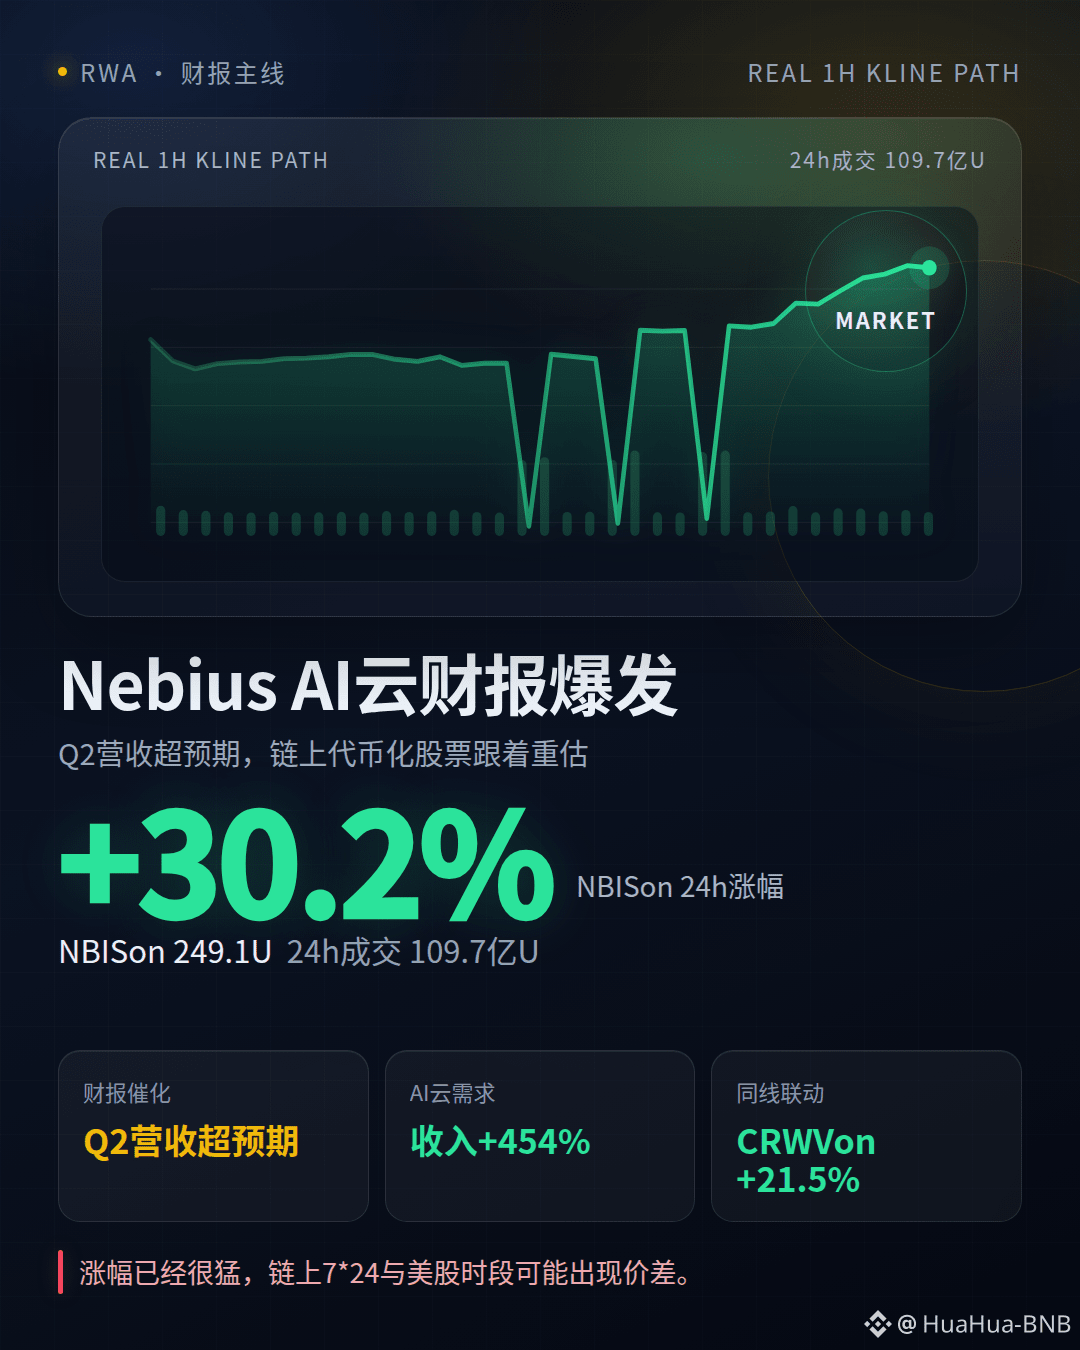
$NBISon (Nebius tokenized stocks, Ondo BSC) is up about +30.2% over the past 24h. Current price is around 249.1U, and 24h trading volume is about 10.97 billion U; the same-name bStocks version, NBISB, is also near +30%. Looking at the real 1h candles, from the low around August 7 at ~79.8 it was pulled all the way up to today’s high around ~250—it’s extremely dramatic.
Behind this isn’t just a random pump of a single coin. Nebius’ Q2 earnings just came out. Multiple media outlets reported that revenue beat expectations; demand for AI cloud has surged. In Blockspace’s figures, Q2 revenue is stated as +454%. On the same AI infrastructure track, CRWVon is also up +21.5% over 24h, and SMCIon is up about +19.8%.
My take: this time on-chain isn’t just hype about a name first—it’s repricing based on earnings reports and AI compute demand. The issue is that the move has already been very strong: tokenized stocks trade 7*24, and there will be price gaps versus U.S. stock trading hours, while on-chain liquidity is also thinner. Don’t get carried away by +30%—after the earnings-related positives are fully priced in, pullbacks can happen quickly.
Do you think this AI Cloud wave is a new main trend, or just an earnings-season sentiment pulse?#bStocks #RWA #AI云
201
·
--
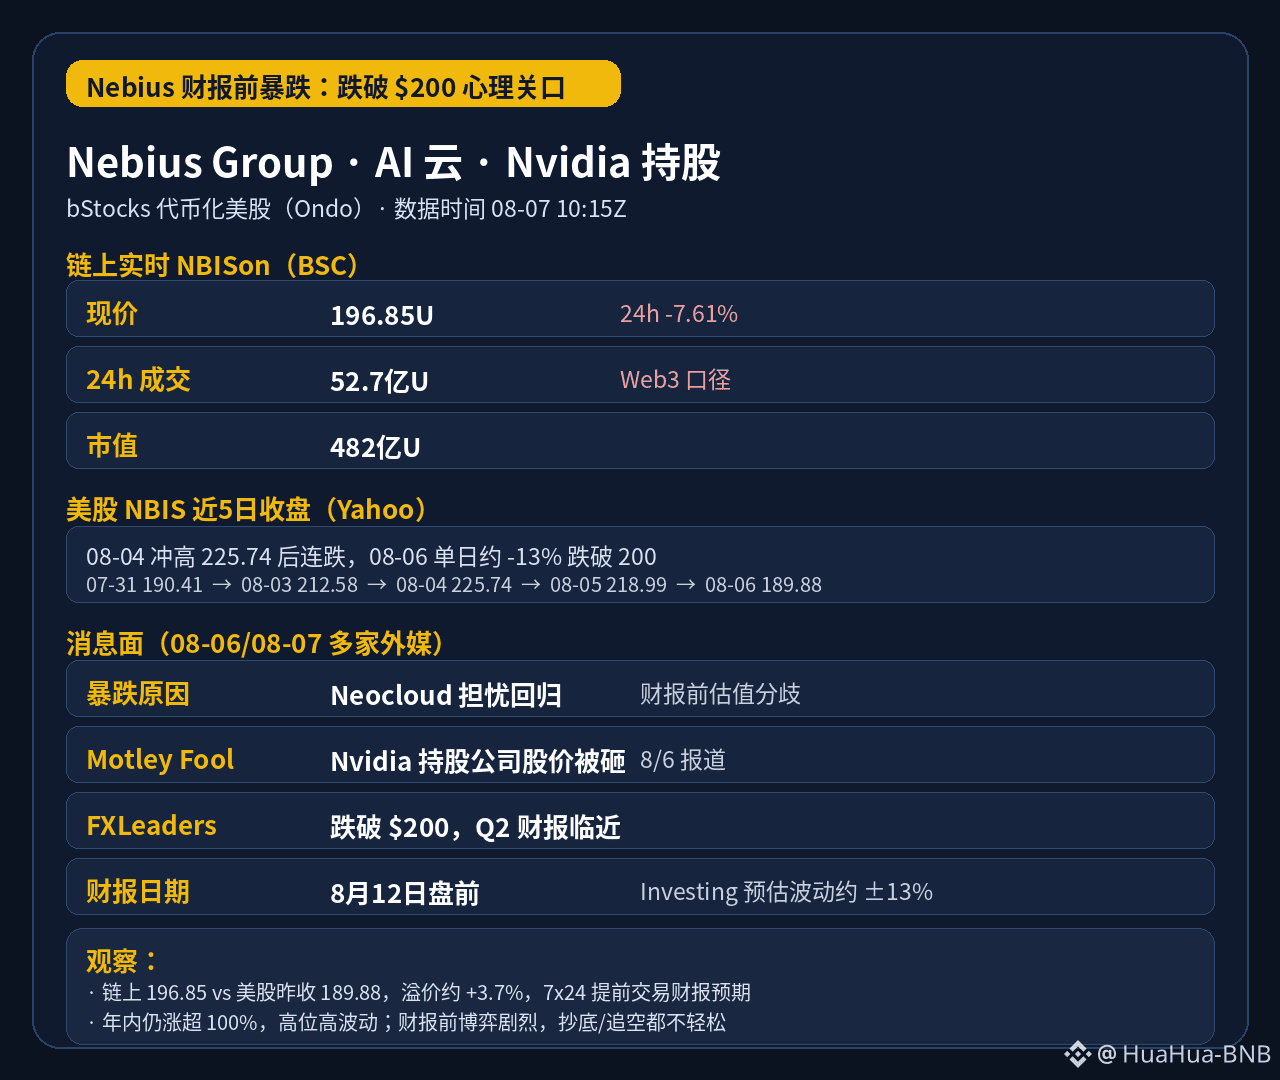
$NBISon Yesterday, Nvidia-holding AI cloud company Nebius saw its single-day drop of about 13%, falling below the $200 psychological level. On-chain twins also dropped nearly 8% 😳
📊 A few key data points (08-07 10:15Z):
• On-chain NBISon: 196.85U, 24h -7.61%, trading volume ~5.27 billion U
• US NBIS over the last 5 days: 190.41 → 212.58 → 225.74 (8/4 high) → 218.99 → 189.88
• On-chain vs US close yesterday: premium ~+3.7%, 7x24 trading ahead of earnings expectations
📰 News: Foreign media reports this round of decline is due to "Neocloud worry about returning"—the AI cloud company's valuation is too high, and funds exited early ahead of the earnings report. The earnings will be released before market open on 8/12. Some institutions estimate that price movement on earnings day could reach ±13%.
My take: This is a typical high-level, high-volatility asset—its gains over the year have been huge, and a single big bearish candle can wipe out a week’s increase. Ahead of earnings, long-short battles will be intense. Buying the dip and chasing shorts won’t be easy either. Let’s first see whether the valuation logic can be convincingly explained in the earnings.
Risk warning: Tokenized stock ≠ holding the underlying directly. The 7x24 price differs from US market hours; volatility before earnings can be extreme—don’t get pulled around by a single day’s big bearish/bullish candle. This is only market observation and does not constitute investment advice.
Do you think the 8/12 earnings will be "bad news already priced in" or will it squeeze valuation bubbles? Let’s discuss in the comments 👇
#bStocks #RWA #AI cloud
74
·
--

Article
【Nebius Group 2026 Q2 Earnings】One chart to understand: Revenue of $582 million up 454%, and AI cloud expansion enters a high-investment stage$NBIS In this Q2 earnings report, the most worth paying attention to isn’t the company’s 454% year-over-year revenue growth by itself, but the fact that it has already entered a very typical AI infrastructure expansion phase: revenue growth is fast, adjusted EBITDA turns positive, yet capital expenditures, debt, and interest costs are also rising quickly.
Read it in one sentence: This season’s highlight for Nebius is that AI cloud revenue is entering a phase of rapid realization; the risks are that capital expenditures and financing costs are also very high, and the market will next place more emphasis on whether “growth can turn into cash returns.”
Follow me—I'll continue to post updates to help you grasp the key quarterly earnings of major companies in Hong Kong and the US in one chart.
【Nebius Group 2026 Q2 Earnings】One chart to understand: Revenue of $582 million up 454%, and AI cloud expansion enters a high-investment stage
$NBIS In this Q2 earnings report, the most worth paying attention to isn’t the company’s 454% year-over-year revenue growth by itself, but the fact that it has already entered a very typical AI infrastructure expansion phase: revenue growth is fast, adjusted EBITDA turns positive, yet capital expenditures, debt, and interest costs are also rising quickly.
Read it in one sentence: This season’s highlight for Nebius is that AI cloud revenue is entering a phase of rapid realization; the risks are that capital expenditures and financing costs are also very high, and the market will next place more emphasis on whether “growth can turn into cash returns.”
Follow me—I'll continue to post updates to help you grasp the key quarterly earnings of major companies in Hong Kong and the US in one chart.
130
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BNBSurpasses$790
19,529 views
148 Discussing
2
#ZamaRises15.99%ToIntradayHigh$0.09
17,821 views
106 Discussing
3
#BitcoinSpotETFsDraw$6.34BInflowsInQ3
6,101 views
91 Discussing
4
#EthereumValidatorExitQueueJumps392%
96,967 views
933 Discussing
5
#IMFApprovesElSalvador$138MWithBitcoinWaiver
13,852 views
63 Discussing
6
#SECHaltsCryptoETFReviewsAmidFundingLapse
261,738 views
1,801 Discussing
7
#ZcashETFPostsFirstWeeklyOutflow$93.6M
95,809 views
254 Discussing
8
#GreekPoliceBustCryptoScamRingArrest17
380,909 views
2,440 Discussing
9
#BitcoinRejectedAt$87K
224,984 views
321 Discussing
10
#FedOctoberRateHikeOddsFallTo17%
388,711 views
2,564 Discussing