

Ariyan Albe
90 Publications
Ariyan Albe
Signaler
Bloquer l’utilisateur
Market Analyst
Trade occasionnellement
3.2 an(s)
0 Suivis
0 Abonnés
41 J’aime
Publications
·
--
#MicronReportQ4Earnings $MU
Micron Printed $54.23B and the Stock Shrugged: The Guide Is the Real Story
Options were pricing a move of roughly 7% to 10% around this report, and Micron delivered a quarter that should have used it: revenue of $54.23B against about $51.07B expected, adjusted EPS of $33.42 against roughly $31.72, and a gross margin of 87.0% on a non-GAAP basis. The stock barely moved after hours. That tells me the market already owned the quarter, so the beat was not the trade.
What was not fully owned is the guide. Q1 revenue is guided to $61.5B plus or minus $1.5B against roughly $56.64B in consensus, about 8.6% higher, and EPS to $38.15 against $35.40. Management also said the vast majority of calendar 2027 HBM bit supply is already contracted at significantly higher prices, which goes straight at the FY2027 visibility question, although no HBM revenue figure was given. Two caveats I would not skip. Q4 was a 14-week quarter, and adjusted for the extra week sequential growth is closer to 21.5% than the headline 30.8%. Q1 gross margin is also guided below Q4's level while R&D and factory spending keep rising.
On valuation, fiscal 2026 EPS was $75.52 on $133.19B of revenue. At 1,098.01, MU trades around 14.5x that, and only about 7.2x the annualized Q1 EPS guide of $38.15 times four. A market paying seven times run-rate earnings for a business with contracted supply is saying it does not trust the margin to last. That is the honest debate: peak-cycle earnings or a new baseline.
The hourly chart shows the same tension. MU sits at 1,098.01 with RSI at 63.41, and the 14, 21 and 35 averages are bunched at 1,069.16, 1,069.63 and 1,068.64, about 2.7% below price. After the print it dipped under the 1,042.16 support to roughly 1,025 and recovered about 7% within a day. Now it is pressing 1,101.30 resistance, just under the late-September highs, with the MACD histogram at 3.15.
My bias is bullish while hourly closes hold above the 1,069 cluster. I want to buy pullbacks into 1,069 to 1,070, not the first tag of 1,101.30 with RSI already in the low 60s
255
·
--
BREAKING: Bitwise has introduced the first U.S. spot $NEAR ETF.
The firm recently increased its NEAR base-case price target to $155, while the bull-case estimate reaches $562.
BREAKING: Bitwise has introduced the first U.S. spot $NEAR ETF.
The firm recently increased its NEAR base-case price target to $155, while the bull-case estimate reaches $562.
The firm recently increased its NEAR base-case price target to $155, while the bull-case estimate reaches $562.
85
·
--
QNT BULLISH
Add more
$QNT
QNTUSDT
Perp
288.27
+20.22%
IT WILL BE HARD PUMP ANY TIME ENTRY
TP:350$,450$,700$,1000$
QNT BULLISH
Add more
$QNT
QNTUSDT
Perp
288.27
+20.22%
IT WILL BE HARD PUMP ANY TIME ENTRY
TP:350$,450$,700$,1000$
Add more
$QNT
QNTUSDT
Perp
288.27
+20.22%
IT WILL BE HARD PUMP ANY TIME ENTRY
TP:350$,450$,700$,1000$
8
·
--
After $DOGE , SHIB , $PEPE , $BONK , & $FLOKI
WHO IS NEXT #100x #memecoin IN NEXT #bullrun ???
After $DOGE , SHIB , $PEPE , $BONK , & $FLOKI
WHO IS NEXT #100x #memecoin IN NEXT #bullrun ???
WHO IS NEXT #100x #memecoin IN NEXT #bullrun ???
69
·
--
WHAT IF $ETH IS STILL FAR FROM REACHING ITS TRUE POTENTIAL?
Vitalik aims to reshape Ethereum into a genuine “world cryptographic computer,” blending security, privacy, and large-scale computation.
With Hegota in 2027, followed by recursive STARKs, formal verification, and a quantum-resistant design, Ethereum might scale to a new level.
Personally, I believe $ETH is undervalued. ETH at $10,000? It could happen.
#trading #ETH
75
·
--
$ETH shorts are UP +13,000% on Bitfinex.
The largest Ethereum short positioning in recent history.
This could trigger the biggest short squeeze EVER!
$ETH shorts are UP +13,000% on Bitfinex.
The largest Ethereum short positioning in recent history.
This could trigger the biggest short squeeze EVER!
The largest Ethereum short positioning in recent history.
This could trigger the biggest short squeeze EVER!
63
·
--
Should I buy $MUBARAK now? Or should I wait for the price to drop? Please give me advice Bro. #MUBARAK
Should I buy $MUBARAK now? Or should I wait for the price to drop? Please give me advice Bro. #MUBARAK
49
·
--
$BTC JUST GOT REJECTED FROM THE TOP OF THE CHANNEL. 👀
BTC pushed into the upper boundary around $88K–$89K and immediately faced rejection.
The structure is now at a critical point:
UPPER CHANNEL REJECTION ⚠️
$82K AREA = KEY SUPPORT
LOSE SUPPORT → DEEPER PULLBACK 🔻
RECLAIM $88K → CONTINUATION 🚀
The $88K–$89K zone is clearly where sellers showed up.
Now we watch the reaction. 👀
148
·
--
$CRDO is showing that AI infrastructure isn’t just about GPUs connectivity is becoming a major bottleneck.
Credo Technology jumped 4.5% to $175.89 after posting a huge fiscal Q1 2027 quarter. Revenue hit $479M, up 114.7% YoY, while adjusted EPS came in at $1.20, beating the $1.17 consensus.
The momentum is carrying into the next quarter too. Management guided for $525M–$535M in Q2 revenue, with the midpoint implying roughly 10.6% sequential growth.
non-GAAP net income surged 140% YoY to $236.3M. FY2026 revenue had already reached nearly $1.3B, up about 206% YoY.
The bigger thesis is bandwidth. As AI clusters scale, high-speed optical connectivity becomes increasingly critical for moving data between GPUs, servers and networking infrastructure.
$CRDO is becoming a serious AI connectivity play, but the valuation and expectations are rising alongside the growth.
64
·
--
MARKETS PRICING IN 95% PROBABILITY OF FED RATE HIKE AS PERSISTENT INFLATION PUTS CHAIRMAN KEVIN WARSH UNDER POLITICAL SCRUTINY 📊
Rate Hike Expectation: Market consensus places a near-certain 95% probability on the Federal Reserve executing a rate hike as inflation remains stubbornly above the 2% target.
Independence Test: The aggressive monetary tightening serves as a high-stakes test of central bank independence for Fed Chair Kevin Warsh amid intense political pressure from President Trump to lower rates.
Upcoming Timeline: The next critical FOMC rate decision is slated for October 28-less than a week before the midterm elections-with financial markets already pricing in a 43% chance of a second consecutive hike.
Macro Implications: Surging borrowing costs and political friction heighten cross-market volatility, impacting global equities, bond yields, and digital assets. #FedRateWatch
$LSK $SYN $ARB
68
·
--
🚨ULTRA BULLISH: $COP IS ONE OF THE MOST BULLISH STOCKS OUT THERE TODAY!!
1) Monthly Bull Flag breakout done, 4 years consolidation in this one.
2) 2 and a half year cup and handle pattern breakout done.
This should now be targeting 200, even 300 in next one year timeframe or even earlier, up 40% in three months, this is no stranger to big moves.
1) Monthly Bull Flag breakout done, 4 years consolidation in this one.
2) 2 and a half year cup and handle pattern breakout done.
This should now be targeting 200, even 300 in next one year timeframe or even earlier, up 40% in three months, this is no stranger to big moves.
89
·
--
🚨 MASSIVE DUMP IN MARKET
Bitcoin dropped below $75,000
ETH falls below $2,400
$250 Million longs liquidated in 30 minutes.
🚨 MASSIVE DUMP IN MARKET
Bitcoin dropped below $75,000
ETH falls below $2,400
$250 Million longs liquidated in 30 minutes.
Bitcoin dropped below $75,000
ETH falls below $2,400
$250 Million longs liquidated in 30 minutes.
5
·
--
Bitcoin is pumping ahead of the Clarity Act vote.
Bitcoin is pumping ahead of the Clarity Act vote.
25
·
--
JUST IN: $108 million in crypto longs liquidated in the past hour.
JUST IN: $108 million in crypto longs liquidated in the past hour.
2
·
--
Bitcoin has dropped below $76,000 after Republicans rejected the Democrat Crypto Clarity Act offer.
Bitcoin has dropped below $76,000 after Republicans rejected the Democrat Crypto Clarity Act offer.
34
·
--
🇺🇸 FED WILL PUMP $15,500,000,000 INTO THE MARKETS IN 3 WEEKS.
Bullish for Bitcoin!
🇺🇸 FED WILL PUMP $15,500,000,000 INTO THE MARKETS IN 3 WEEKS.
Bullish for Bitcoin!
Bullish for Bitcoin!
42
·
--
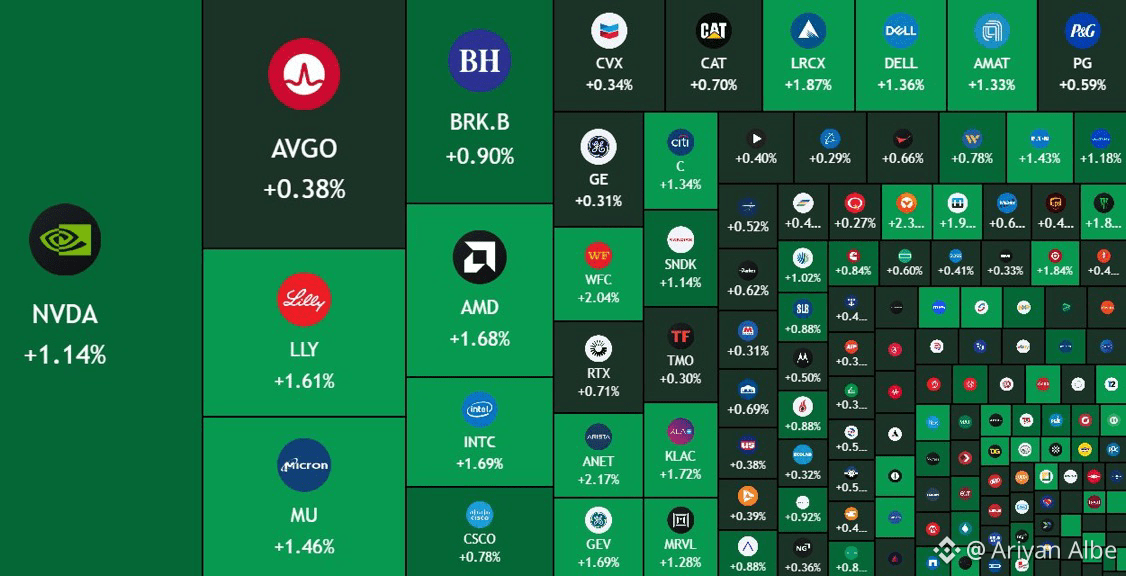
🔥PUMP:
$600,000,000,000 added to the US stock market at open.$NVDAB $NVDA.US $AAPL.US
🔥PUMP:
$600,000,000,000 added to the US stock market at open.$NVDAB $NVDA.US $AAPL.US
$600,000,000,000 added to the US stock market at open.$NVDAB $NVDA.US $AAPL.US
151
·
--
Someone has opened $73 Million in $BTC and $ETH shorts ahead of today's Clarity vote.
Does he know something?
Someone has opened $73 Million in $BTC and $ETH shorts ahead of today's Clarity vote.
Does he know something?
Does he know something?
80
·
--
🚨 BREAKING
TRUMP'S INSIDER JUST OPENED A $98,000,000.00 25X $ETH LONG
IF $ETH PRICE HITS $2,429 = LIQUIDATION
DOES HE KNOW SOMETHING OR LARGE LIQUIDATION SOON?
🚨 BREAKING
TRUMP'S INSIDER JUST OPENED A $98,000,000.00 25X $ETH LONG
IF $ETH PRICE HITS $2,429 = LIQUIDATION
DOES HE KNOW SOMETHING OR LARGE LIQUIDATION SOON?
TRUMP'S INSIDER JUST OPENED A $98,000,000.00 25X $ETH LONG
IF $ETH PRICE HITS $2,429 = LIQUIDATION
DOES HE KNOW SOMETHING OR LARGE LIQUIDATION SOON?
65
Connectez-vous pour découvrir plus de contenu
Rejoignez la communauté mondiale des adeptes de cryptomonnaies sur Binance Square
⚡️ Suviez les dernières informations importantes sur les cryptomonnaies.
💬 Jugé digne de confiance par la plus grande plateforme d’échange de cryptomonnaies au monde.
👍 Découvrez les connaissances que partagent les créateurs vérifiés.
Adresse e-mail/Nº de téléphone
Sujets d’actualité
BNBSurpasses$790
17,761 vues
143 mentions
$BNB strategic long plan -> FOCUS NOW
BNB has created 2 strong lows after taking out internal liquidity
I'm expecting a move towards swing high $815-$830 and looking for a long on a retest of the green box
#BNBSurpasses$790 #bnb
Ghost Writer
·6 mentions J’aime
·9k vues
ZamaRises15.99%ToIntradayHigh$0.09
15,132 vues
105 mentions
BitcoinSpotETFsDraw$6.34BInflowsInQ3
5,718 vues
90 mentions