

乌安达奥
245 Posts
乌安达奥
Report
Block User
Just me the digital trial of virtual currency
Open Trade
Occasional Trader
2.1 Years
19 Following
13 Followers
23 Liked
Posts
Portfolio
All
Quotes
Videos
·
--
See translation
📉 Le CAC 40 sous pression !
Nouvelle séance difficile pour le marché parisien : -0,80 % lundi, à 7 834,10 points, après un plongeon jusqu’à 7 796,58 points.
Le signal est clair : les vendeurs gardent la main et la pression baissière s’intensifie. La zone des 7 800 points devient désormais un niveau clé : une cassure nette pourrait ouvrir la voie à une correction plus profonde, tandis qu’un rebond au-dessus de cette zone permettrait de calmer les tensions.
👉 La prudence reste donc de mise : le prochain mouvement pourrait être décisif.
#CAC40 #Bourse #Trading
98
·
--
Meta and Microsoft are seeking to reduce their dependence on Anthropic’s Claude by prioritizing their own in-house AI tools. This shift shows that tech giants want greater control over their technologies, reduce their dependence on external providers, and strengthen their position in the race for artificial intelligence.
#Meta #Microsoft #ArtificialIntelligence
#Meta #Microsoft #ArtificialIntelligence
94
·
--
Elon Musk announced on X that SpaceX could be renamed “SpaceXSI”, claiming that the term “SI” (superintelligence) would be preferable to “AI”. This statement could reflect the growing importance of artificial intelligence and superintelligence in Musk’s technology strategy.
#SpaceX #ElonMusk #ArtificialIntelligence
#SpaceX #ElonMusk #ArtificialIntelligence
88
·
--
📊 Analysis – CAC 40
The CAC 40 rebounded by +1.01% to 7,914.07 points this Friday morning, after having sharply fallen the previous day to 7,820.98 points, its lowest level since March 31. This rebound reflects a return to buying, but the market remains marked by the recent high volatility.
To watch: the CAC 40’s ability to stay above 7,900 points could be important to confirm this recovery move.
#CAC40 #BourseParis #FinancialMarkets
44
·
--
📊 Resume analysis
Capgemini shares hit a 8-month high after strong Accenture results. According to Citi, these figures reassured investors about demand in the IT services sector, easing concerns about a slowdown in technology spending. This momentum could support sentiment around Capgemini and similar companies.
#Capgemini #Technology #StockMarket
ACNUS+0.02%
83
·
--
Market recap analysis:
Bond markets are under heavy pressure. The yield on the US 10-year Treasury reaches 5.34%, its highest level since 2002. This rise reflects an increase in the cost of financing and may weigh on stocks, bonds, and risk assets, especially crypto. The situation in Washington, Paris, London, and Tokyo shows that tensions are now global.
#FinancialMarkets #Bonds #Trading
IEFETF+0.00%
101
·
--
Summary analysis:
Unicaja announces the upcoming departure of its non-executive president, José Sevilla, who will not seek a renewal of his term. This transition may draw investors’ attention to the bank’s future governance and strategy. In the short term, the market will mainly watch shareholders’ reactions and the outlook related to his successor.
#Unicaja #Banks #FinancialMarkets
47
·
--
📊 Mortgage rate outlook analysis:
The rise in U.S. mortgage rates, with the 30-year fixed rate at its highest level in nearly three years, could weigh on housing demand. Higher borrowing costs can reduce households’ purchasing power and slow home sales. This also remains an important signal for markets, as elevated rates can keep financial conditions restrictive.
#USA #RealEstate #FinancialMarkets
47
·
--
Inflation in Peru accelerates in September, reaching its highest level in three years. Rising energy costs are adding further pressure on prices, which could complicate the central bank’s decisions regarding its monetary policy.
#Peru #Inflation #Economy
Inflation in Peru accelerates in September, reaching its highest level in three years. Rising energy costs are adding further pressure on prices, which could complicate the central bank’s decisions regarding its monetary policy.
#Peru #Inflation #Economy
#Peru #Inflation #Economy
61
·
--
Stock market recap analysis:
The CAC 40 falls sharply by -1.7% to 7,826 points, its lowest level since late March. This drop is mainly due to the sharp rise in the yield on the French 10-year OAT (government bond), which reaches 4.96%, its highest level since the early 2000s. The rise in rates heightens concerns about French public finances and weighs on equity markets.
#CAC40 #Bourse #France
1
·
--
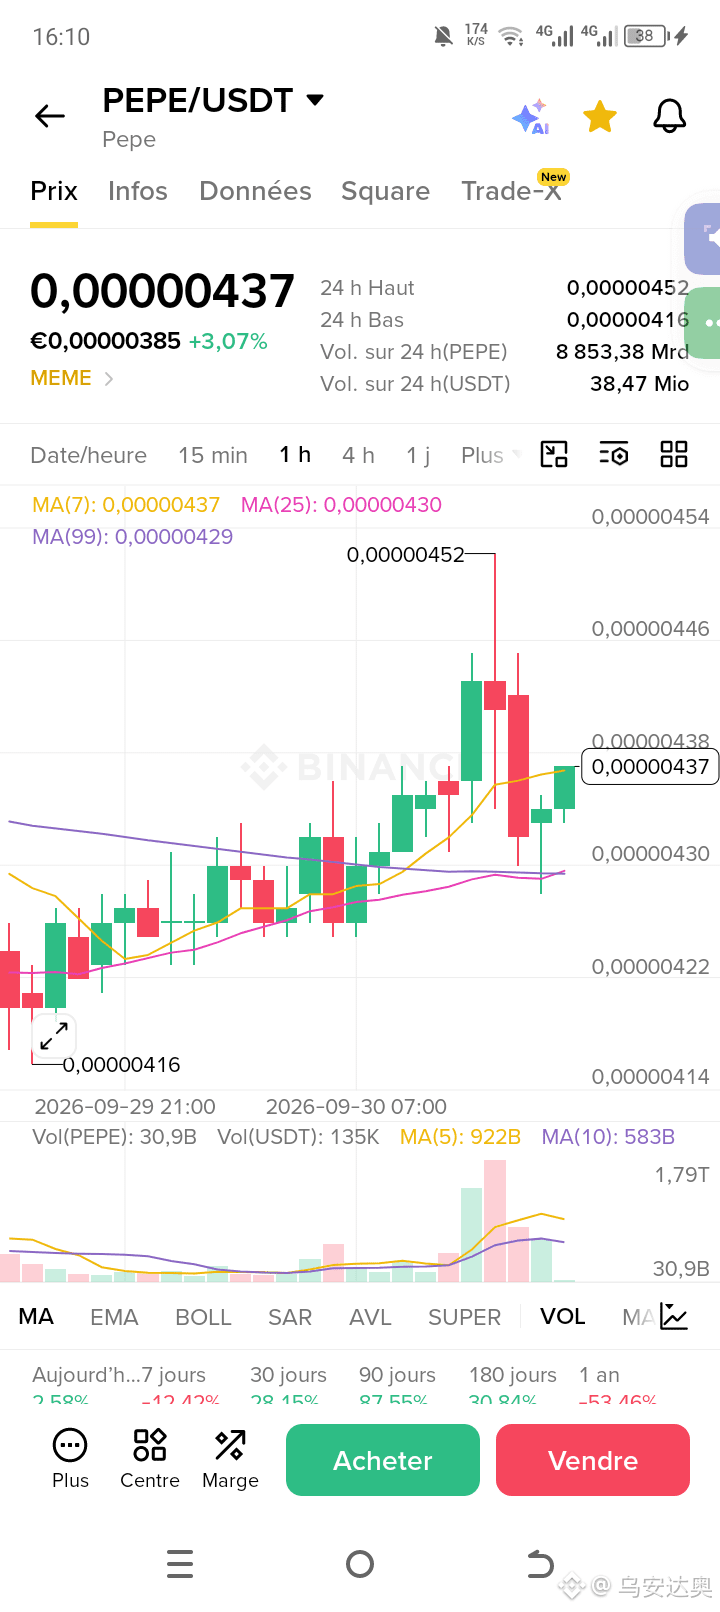
📊 PEPE/USDT — 1H Analysis
Slightly bullish trend: the price is above the MA25 and MA99, but 0,00000438 remains an immediate resistance.
$PEPE
{alpha}()
🟢 LONG order
Entry: 0,00000438 – 0,00000440
TP1: 0,00000446
TP2: 0,00000452
SL: 0,00000430
🔴 SHORT order (if rejection is confirmed below 0,00000438)
Entry: 0,00000435 – 0,00000437
TP1: 0,00000430
TP2: 0,00000422
SL: 0,00000446
⚠️ Wait for the 1H candle confirmation before entering.
#PEPE #PEPEUSDT #CryptoTrading
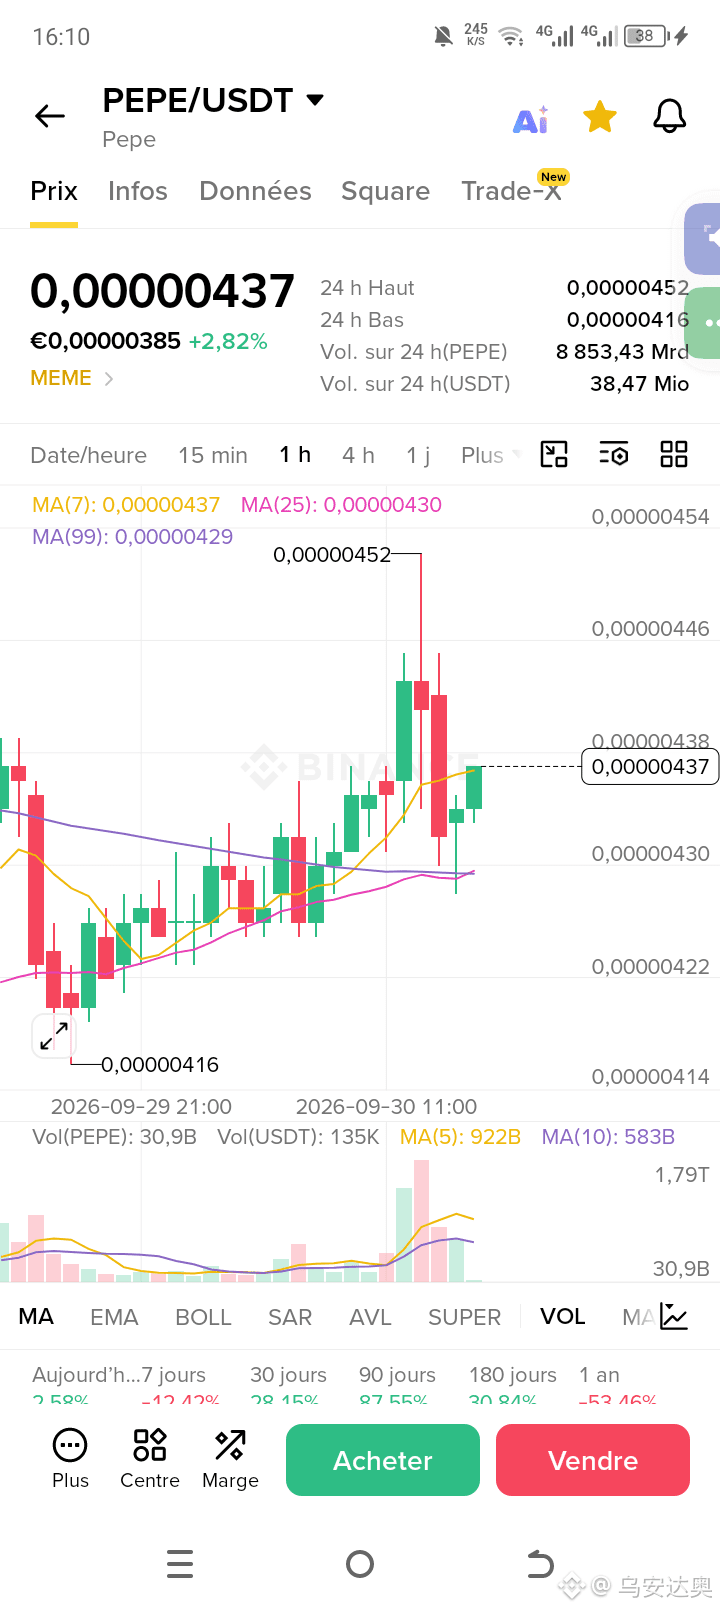
📊 PEPE/USDT — 1H Analysis
Slightly bullish trend: the price is above the MA25 and MA99, but 0,00000438 remains an immediate resistance.
$PEPE
🟢 LONG order
Entry: 0,00000438 – 0,00000440
TP1: 0,00000446
TP2: 0,00000452
SL: 0,00000430
🔴 SHORT order (if rejection is confirmed below 0,00000438)
Entry: 0,00000435 – 0,00000437
TP1: 0,00000430
TP2: 0,00000422
SL: 0,00000446
⚠️ Wait for the 1H candle confirmation before entering.
#PEPE #PEPEUSDT #CryptoTrading
262
·
--
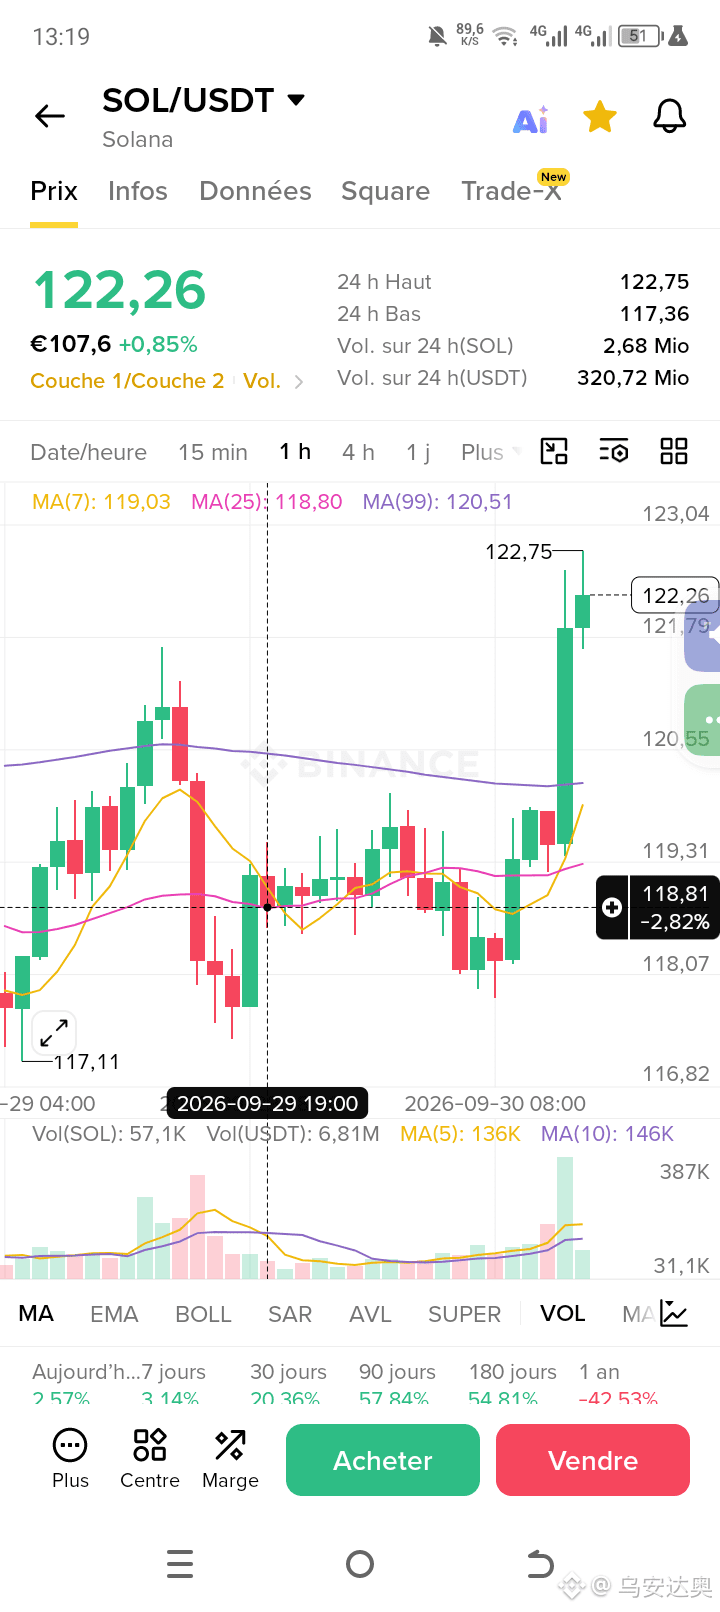
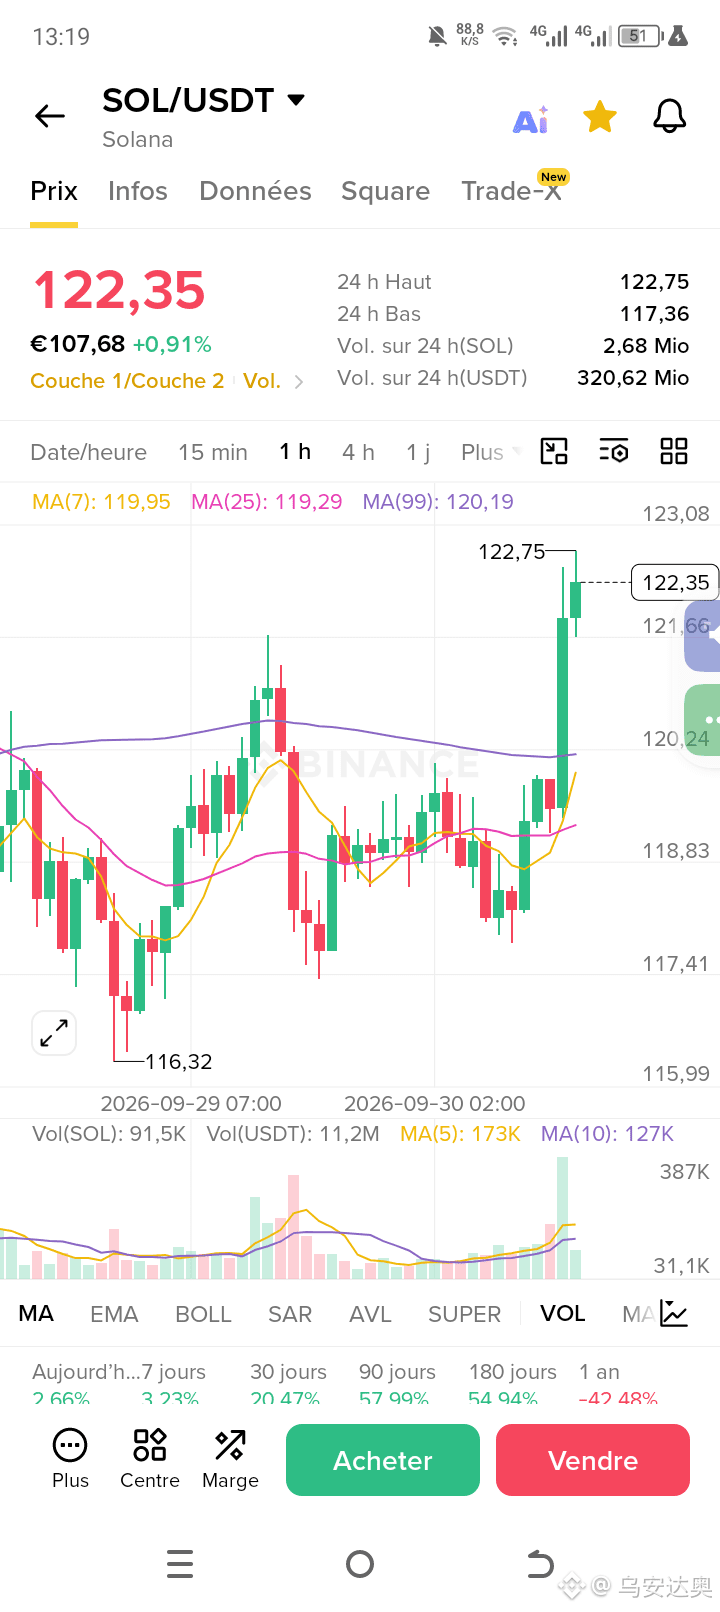
📊 SOL/USDT — 1H$SOL
{future}(SOLUSDT)
Bullish trend: price above the 7/25/99 MAs and strong impulse with volume.
🟢 BUY (pullback): 121.50 – 121.80
🛑 SL: 120.40
🎯 TP1: 123.50
🎯 TP2: 124.50
🎯 TP3: 126.00
🔥 Breakout BUY only if SOL breaks 122.75 with confirmation.
#SOL #CryptoTrading #Binance
📊 SOL/USDT — 1H$SOL
Bullish trend: price above the 7/25/99 MAs and strong impulse with volume.
🟢 BUY (pullback): 121.50 – 121.80
🛑 SL: 120.40
🎯 TP1: 123.50
🎯 TP2: 124.50
🎯 TP3: 126.00
🔥 Breakout BUY only if SOL breaks 122.75 with confirmation.
#SOL #CryptoTrading #Binance
Bullish trend: price above the 7/25/99 MAs and strong impulse with volume.
🟢 BUY (pullback): 121.50 – 121.80
🛑 SL: 120.40
🎯 TP1: 123.50
🎯 TP2: 124.50
🎯 TP3: 126.00
🔥 Breakout BUY only if SOL breaks 122.75 with confirmation.
#SOL #CryptoTrading #Binance
184
·
--
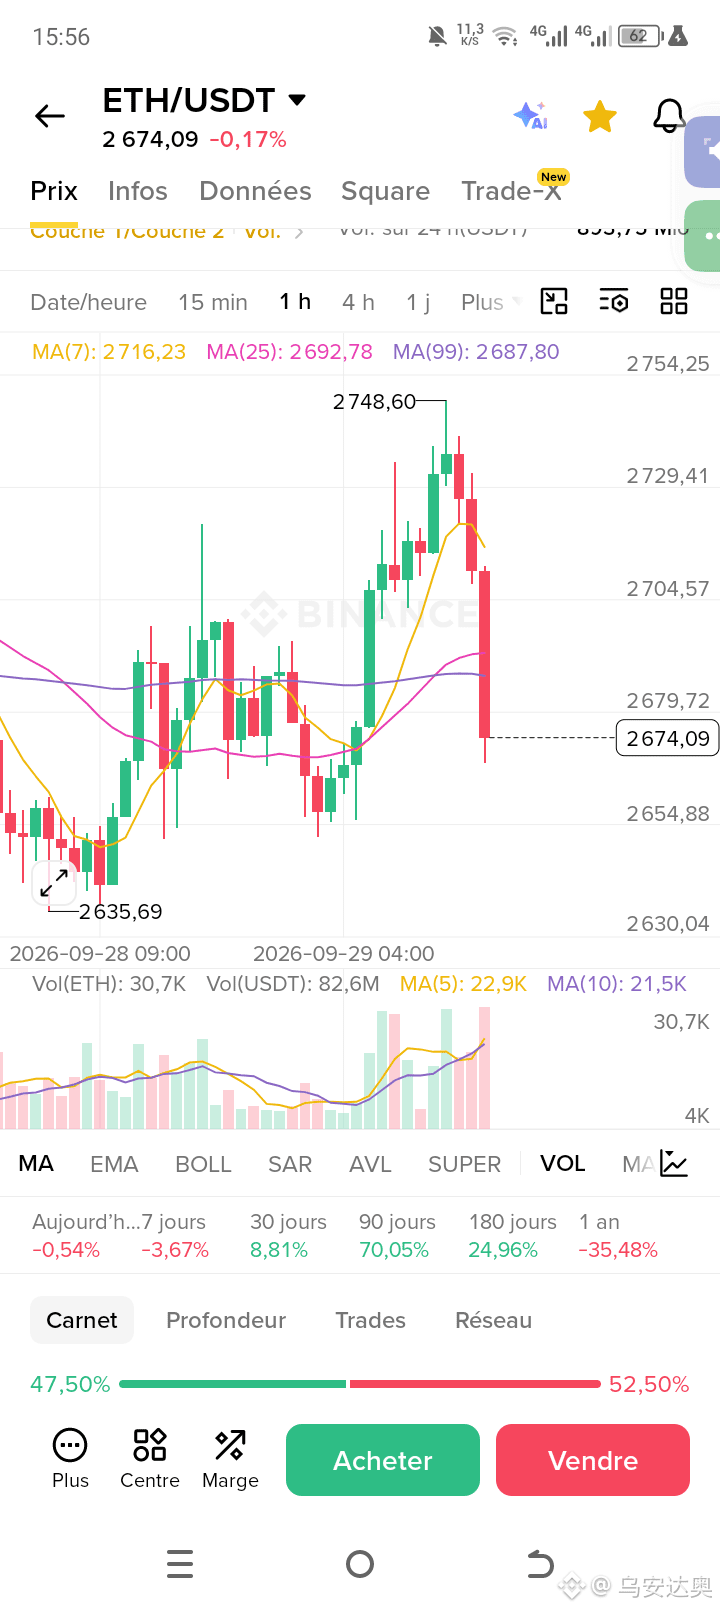
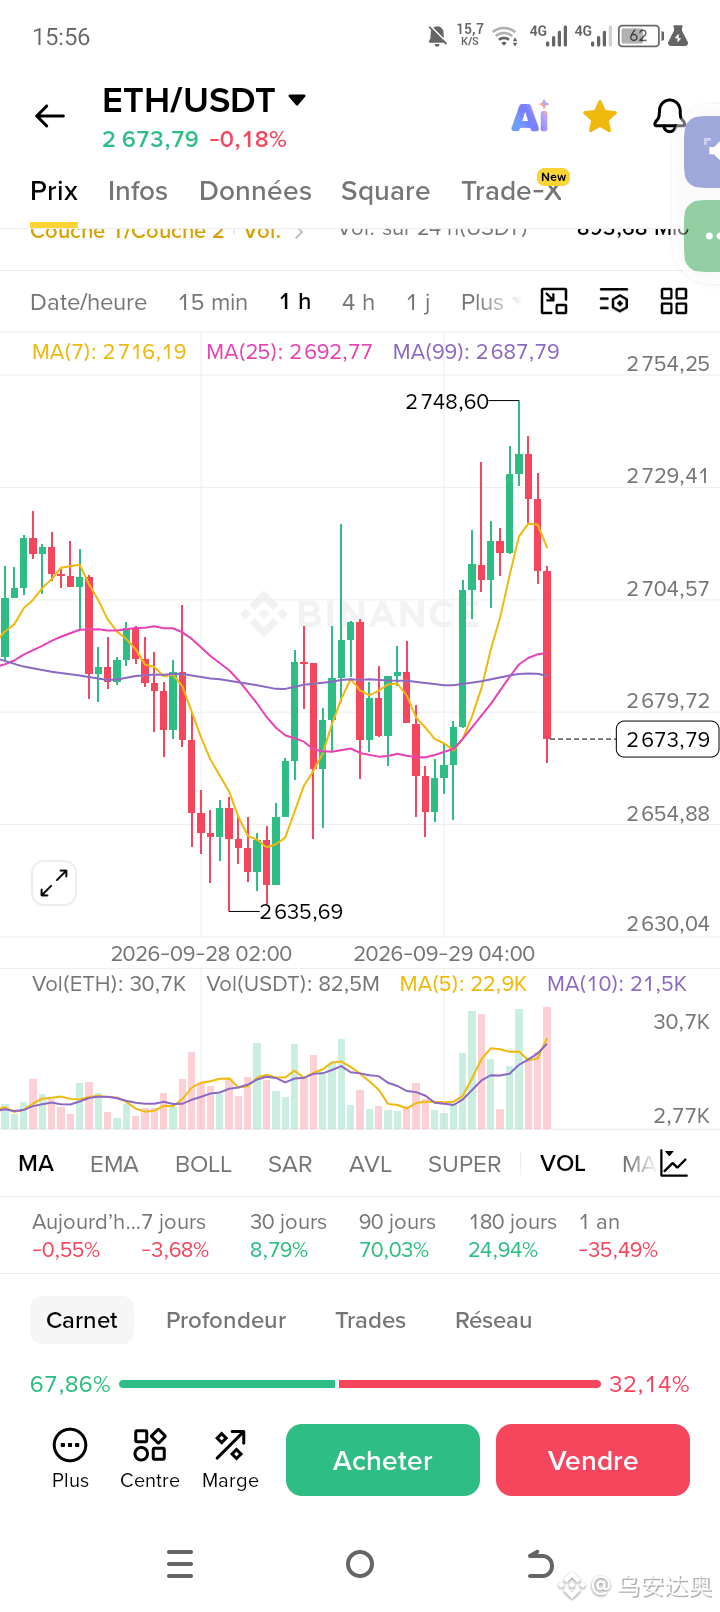
📊 ETH/USDT — 1H$ETH
{future}(ETHUSDT)
Short-term bearish trend: the price is below the MA(7), MA(25) and MA(99), with a strong red candle.
Possible orders:
🔴 SELL : 2673–2685
🛑 SL : 2706
🎯 TP1 : 2655
🎯 TP2 : 2636
Alternative scenario:
🟢 BUY only if the price goes back above 2705
🛑 SL : 2685
🎯 TP : 2729 → 2748
⚠️ Wait for confirmation before entering, especially after the strong red candle.
#ETH #ETHUSDT #CryptoTrading
📊 ETH/USDT — 1H$ETH
Short-term bearish trend: the price is below the MA(7), MA(25) and MA(99), with a strong red candle.
Possible orders:
🔴 SELL : 2673–2685
🛑 SL : 2706
🎯 TP1 : 2655
🎯 TP2 : 2636
Alternative scenario:
🟢 BUY only if the price goes back above 2705
🛑 SL : 2685
🎯 TP : 2729 → 2748
⚠️ Wait for confirmation before entering, especially after the strong red candle.
#ETH #ETHUSDT #CryptoTrading
152
·
--
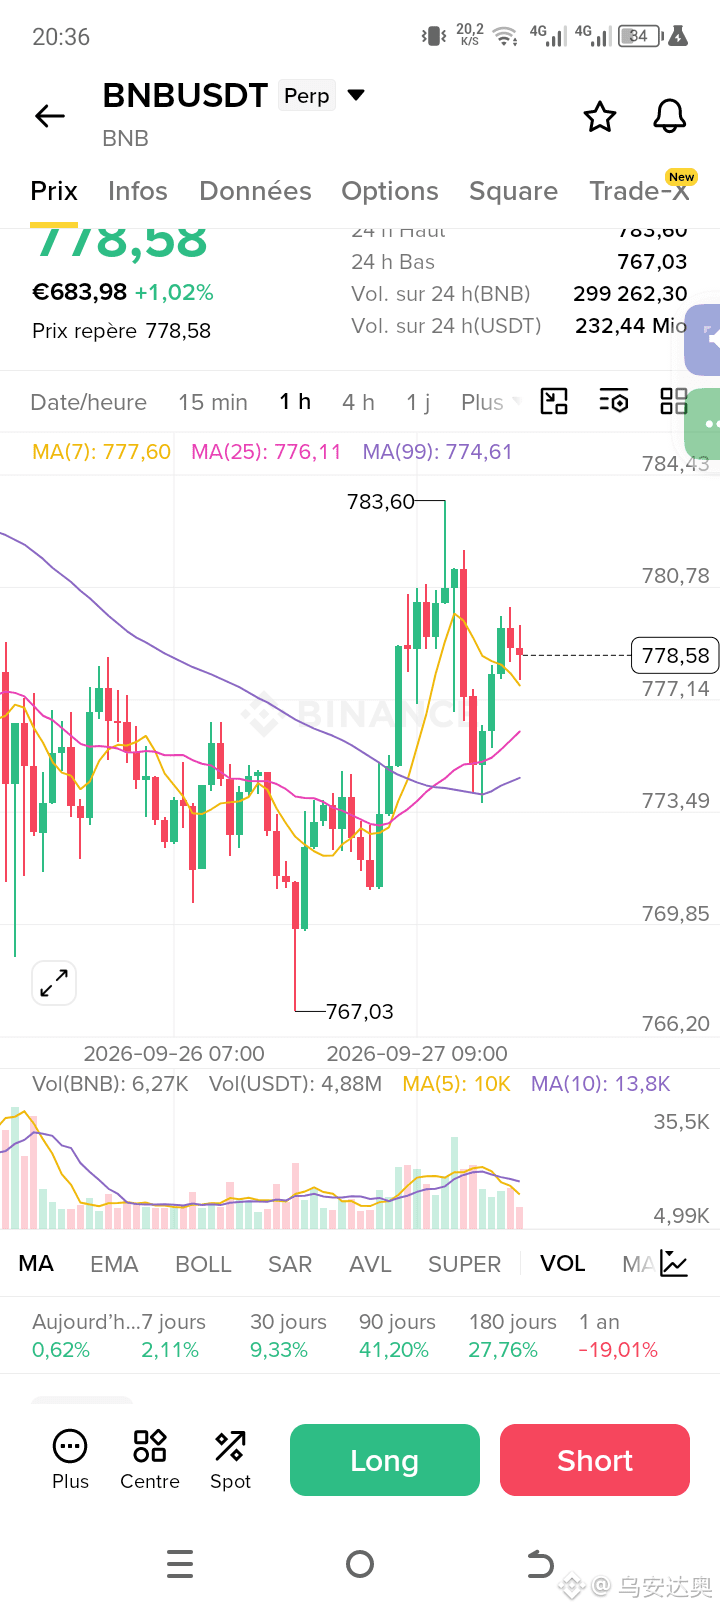
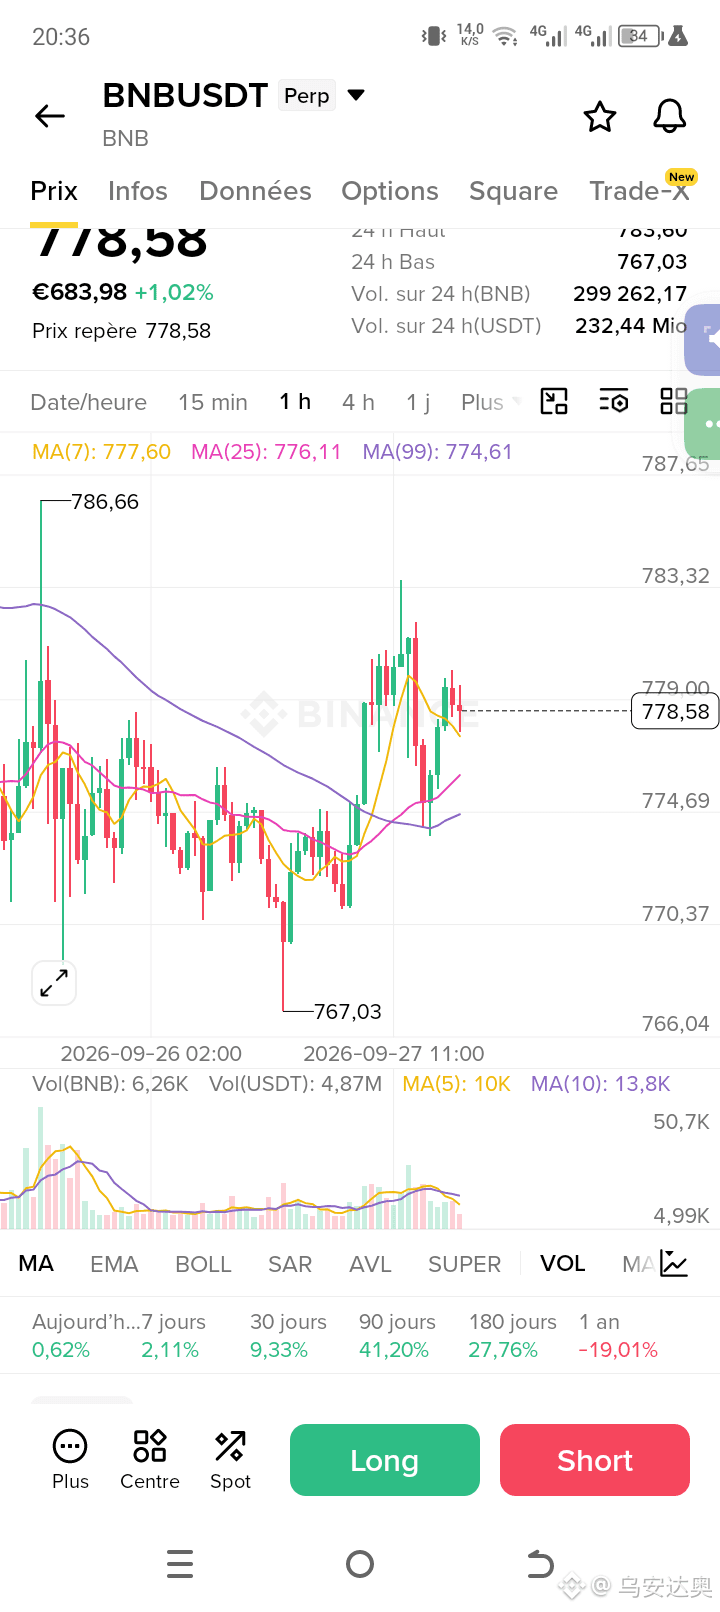
📊 BNB/USDT – 1H$BNB
{future}(BNBUSDT)
LONG 🟢
Entry : 777,20 – 778,00
SL : 774,50
TP1 : 780,80
TP2 : 783,50
SHORT 🔴
Entry : 780,80 – 781,50 if rejection
SL : 784,20
TP1 : 777,20
TP2 : 773,50
⚠️ Wait for candle confirmation before entering.
#BNB #CryptoTrading #Futures
📊 BNB/USDT – 1H$BNB
LONG 🟢
Entry : 777,20 – 778,00
SL : 774,50
TP1 : 780,80
TP2 : 783,50
SHORT 🔴
Entry : 780,80 – 781,50 if rejection
SL : 784,20
TP1 : 777,20
TP2 : 773,50
⚠️ Wait for candle confirmation before entering.
#BNB #CryptoTrading #Futures
LONG 🟢
Entry : 777,20 – 778,00
SL : 774,50
TP1 : 780,80
TP2 : 783,50
SHORT 🔴
Entry : 780,80 – 781,50 if rejection
SL : 784,20
TP1 : 777,20
TP2 : 773,50
⚠️ Wait for candle confirmation before entering.
#BNB #CryptoTrading #Futures
148
·
--
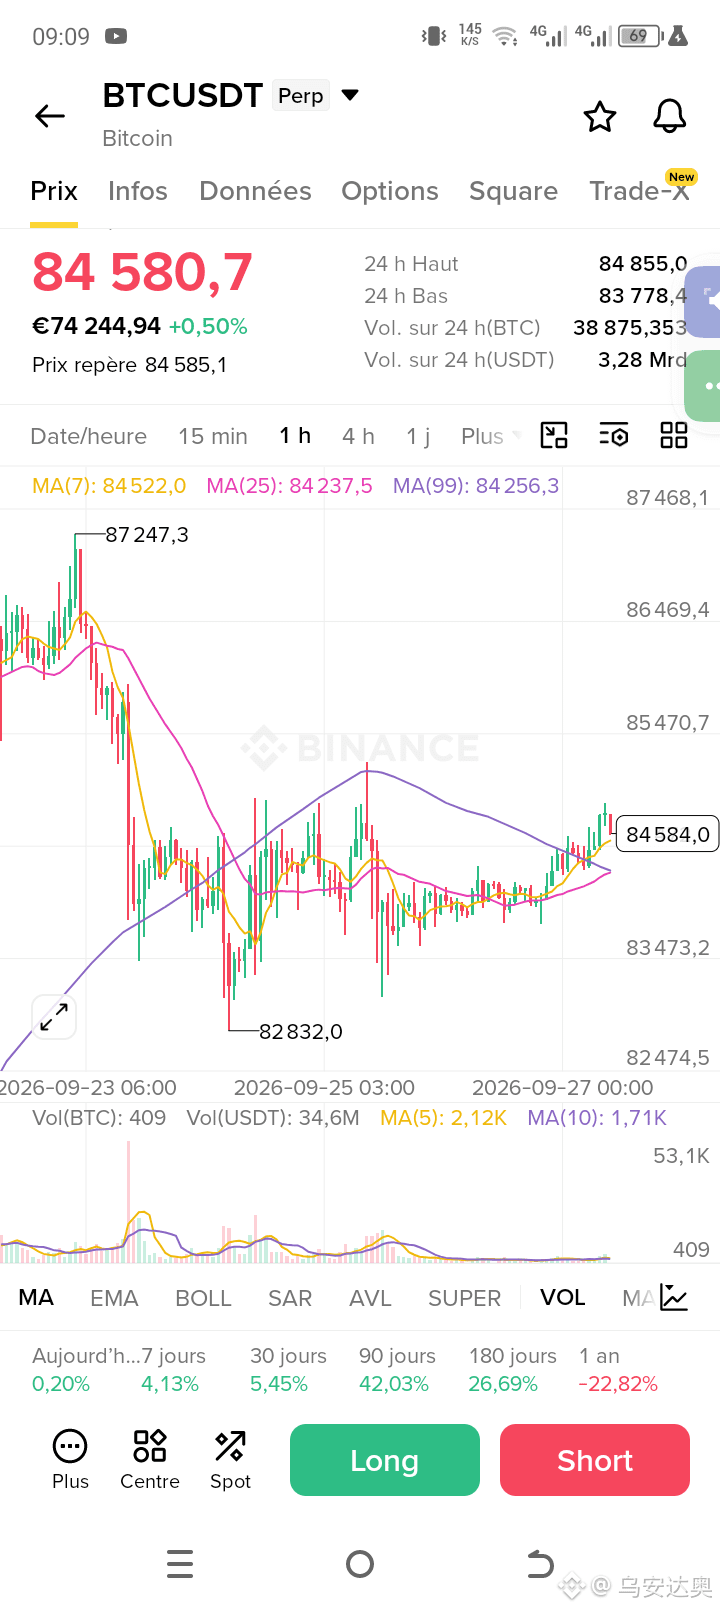
📊 BTC/USDT — 1H
Bias: slightly bullish: the price is above the MA 7/25/99 and is trying to bounce back.
🟢 LONG
Entry: 84,450 – 84,650
SL: 83,950
TP1: 85,470
TP2: 86,450
🔴 SHORT only if rejection is confirmed below 84,450
Entry: 84,350
SL: 84,850
TP1: 83,500
TP2: 82,850
⚠️ Wait for the 1H candle confirmation before entering and manage risk.
#BTC #Crypto #Trading
{future}(BTCUSDT)
$BTC
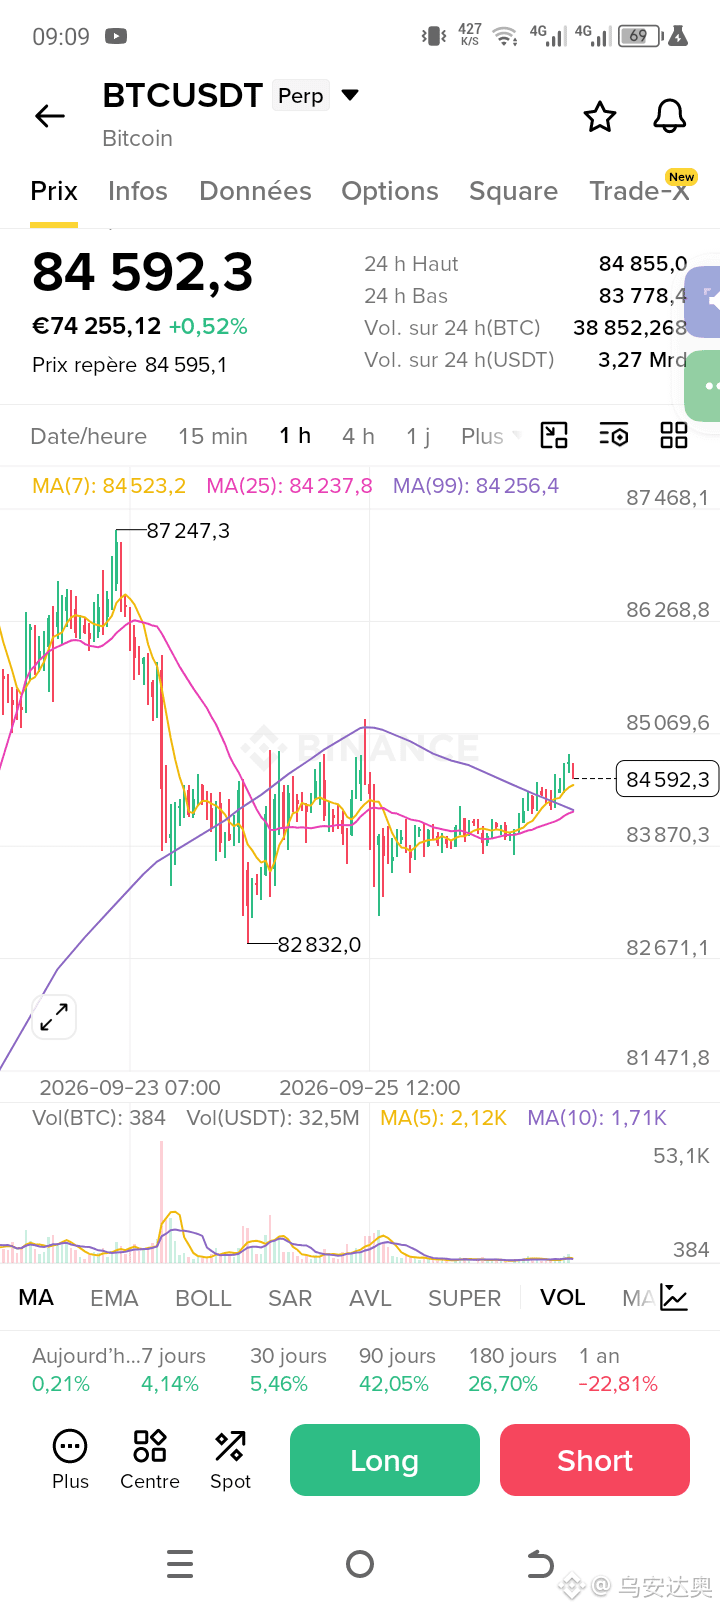
📊 BTC/USDT — 1H
Bias: slightly bullish: the price is above the MA 7/25/99 and is trying to bounce back.
🟢 LONG
Entry: 84,450 – 84,650
SL: 83,950
TP1: 85,470
TP2: 86,450
🔴 SHORT only if rejection is confirmed below 84,450
Entry: 84,350
SL: 84,850
TP1: 83,500
TP2: 82,850
⚠️ Wait for the 1H candle confirmation before entering and manage risk.
#BTC #Crypto #Trading
$BTC
131
·
--
Analysis: Soybean futures advance on the CBOT, supported by hopes for commercial progress between the United States and China. Traders remain cautious, however, as the details of any potential agreements will be crucial to confirm the trend. The market therefore remains sensitive to diplomatic announcements and prospects for Chinese demand.
#Soy #Agriculture #FinancialMarkets
#Soy #Agriculture #FinancialMarkets
64
·
--
📉 Analysis of the CAC 40
The CAC 40 continues its decline this Thursday, falling by -0.75% to 8,062 points, after already losing -0.39% on Wednesday. The drop to 8,049 points highlights persistent selling pressure on the Paris market.
Investors remain cautious, and the 8,000-point zone could become an important level to watch going forward.
#CAC40 #StockMarket #Markets
120
·
--
📉 Market analysis: natural gas
Natural gas futures contracts in Europe and the UK remain at their lowest levels in three weeks following a sharp drop at the beginning of the week. The market remains split between hopes for de-escalation in the Middle East, which could reduce energy tensions, and still insufficient winter storage levels in Europe. This situation could keep price volatility elevated.
#NaturalGas #Energy #Markets
112
·
--
📊 Analysis
Bitcoin shows a strong rebound in momentum, with a move above 87 000 $ and a gain of +13% over one week after its low around $75,000. This rise reflects a marked return of buyers. The 87,000–90,000 $ zone could now be important to confirm the continuation of the move or trigger profit-taking.
#Bitcoin #Crypto #BTC
116
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BinanceLaunchesBinanceIntelligence
405,927 views
3,094 Discussing
#BinanceLaunchesBinanceIntelligence
⚡ AI Meets Crypto Trading: Binance Intelligence is Live! ⚡
Trading just got a massive upgrade with Binance's new AI suite:
1️⃣ Binance AI: Personalized market dashboards & 4-hour macro market audio briefings.
2️⃣ Binance AI Pro: Build and run automated strategies using simple natural language prompts.
3️⃣ Binance Agent OS: Developer framework for autonomous financial AI agents.
Describe your strategy ➔ Paper test ➔ Execute 24/7.
Are you building your next trading strategy with AI? Drop your thoughts below! 👇
#BinanceLaunchesBinanceIntelligence #BinanceSquare #CryptoAI #Trading $EDEN
Hazi BNB
·1 Likes
·886 views
BitcoinTargets2026OpenAt$87570
2,400 views
75 Discussing
BitcoinRejectedAt$87KThirdTime
2,403 views
62 Discussing