
邪修King
79 Posts
邪修King
Report
Block User
玩AI | 玩美股 | 玩日常 | 玩币 | 玩研究 |
Open Trade
NIGHT Holder
High-Frequency Trader
5.8 Years
163 Following
174 Followers
42 Liked
Posts
Portfolio
All
Quotes
·
--
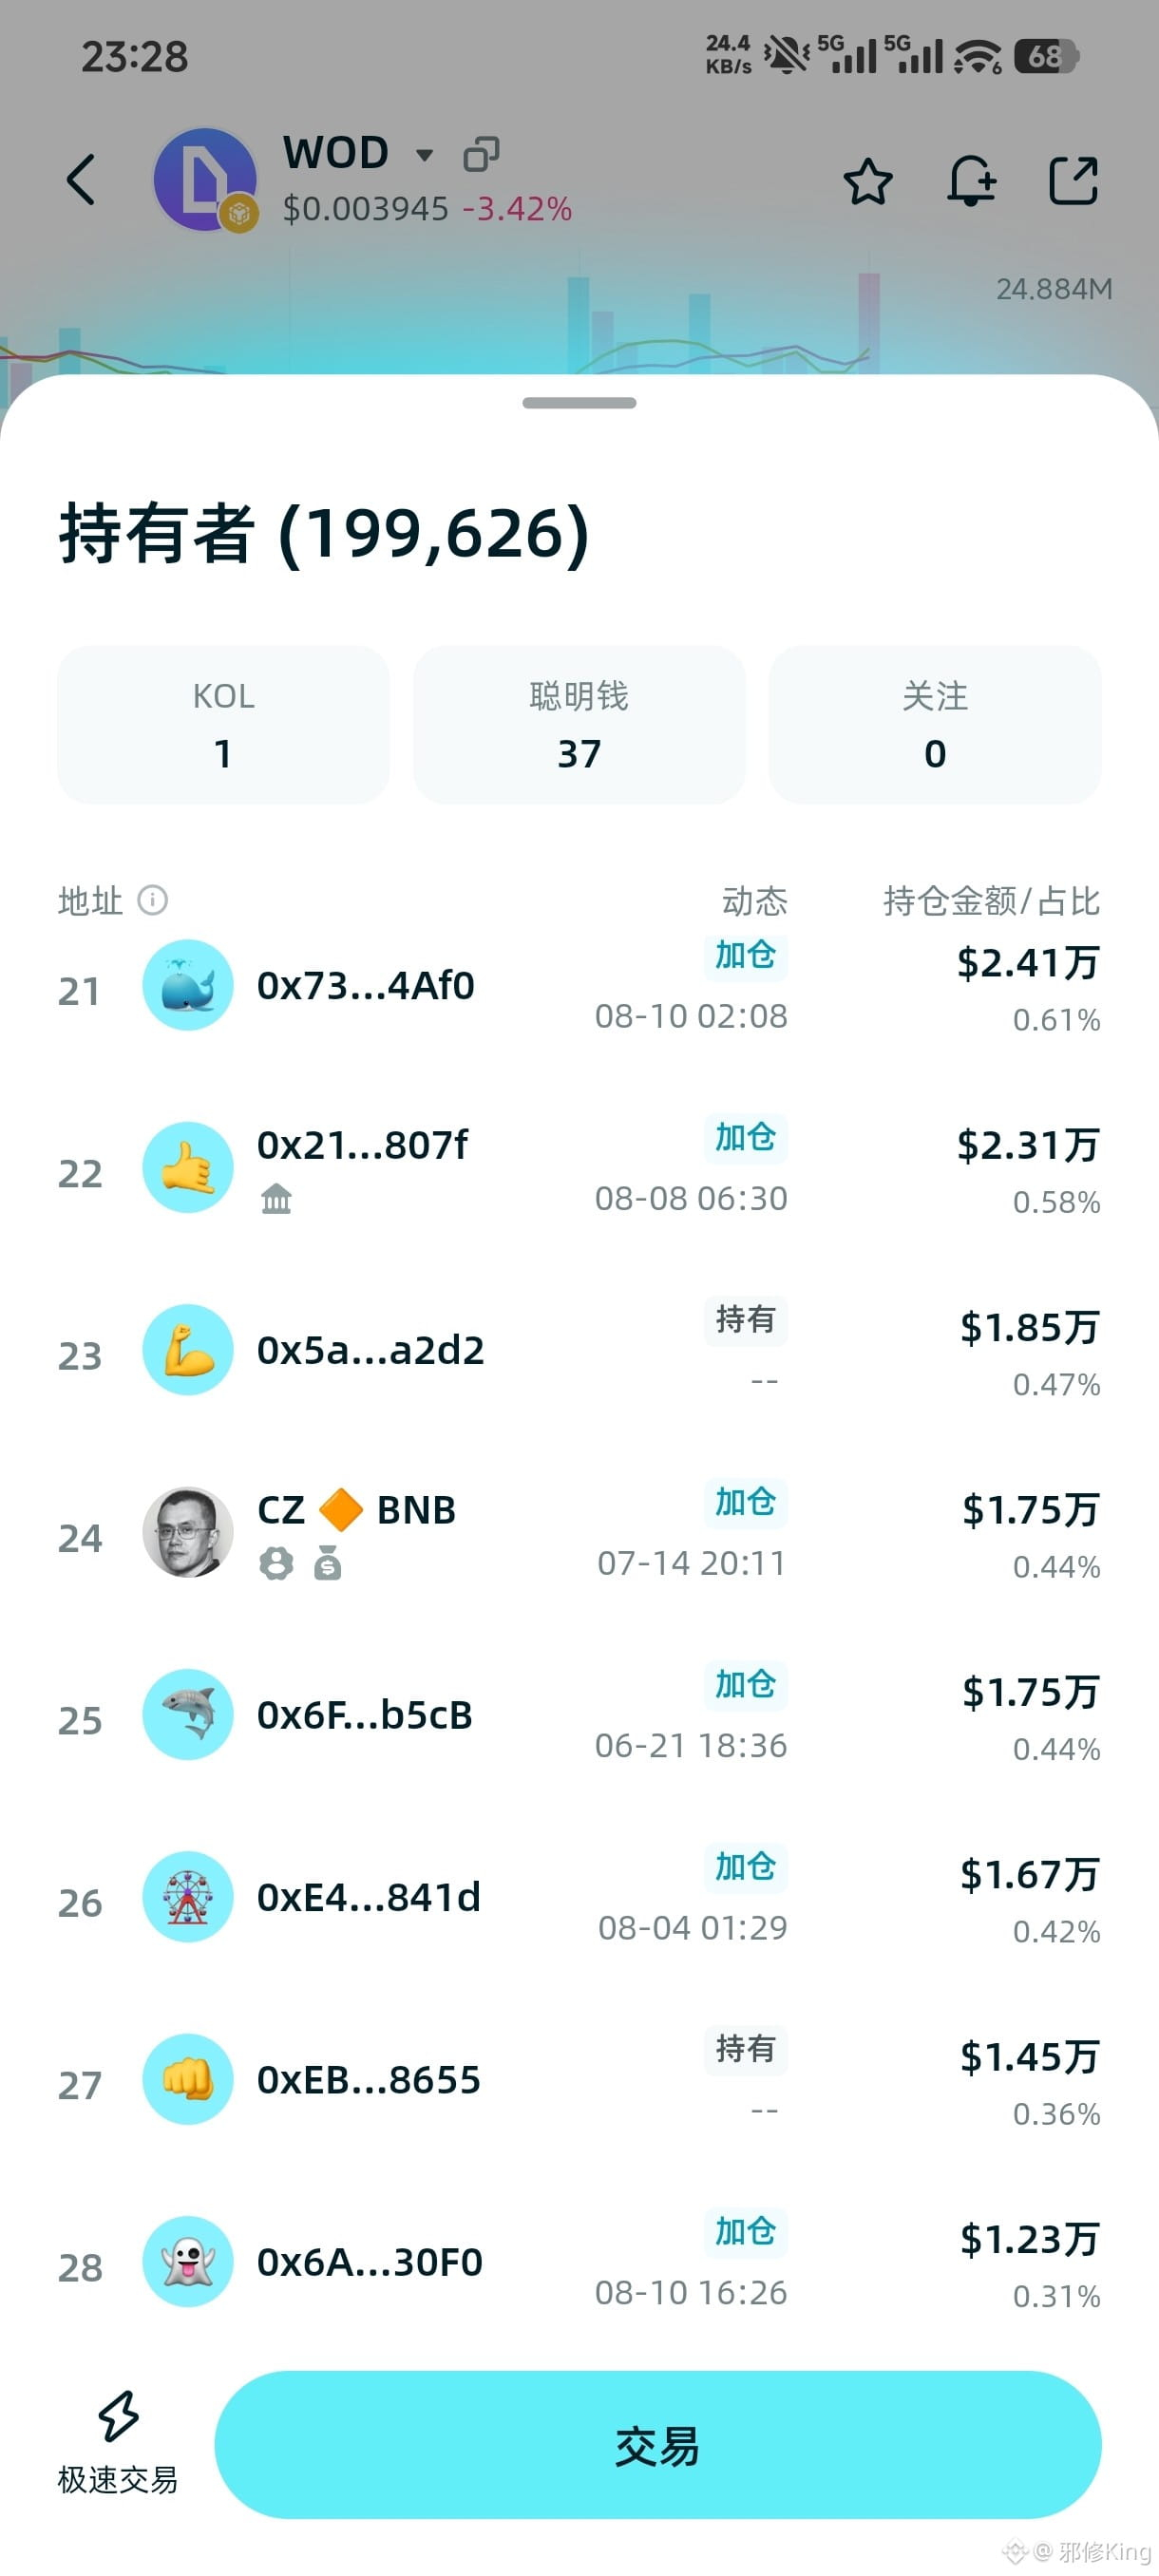
Hasn't anyone noticed this thing that CZ has quietly been building a position and holding it?
A while back, Binance Wallet also did a promotion for ALLOX.
So what big move are they cooking up again?
$WOD
{alpha}(560xb994882a1b9bd98a71dd6ea5f61577c42848b0e8)
Hasn't anyone noticed this thing that CZ has quietly been building a position and holding it?
A while back, Binance Wallet also did a promotion for ALLOX.
So what big move are they cooking up again?
$WOD
A while back, Binance Wallet also did a promotion for ALLOX.
So what big move are they cooking up again?
$WOD
2
1
2
532
·
--
Bullish
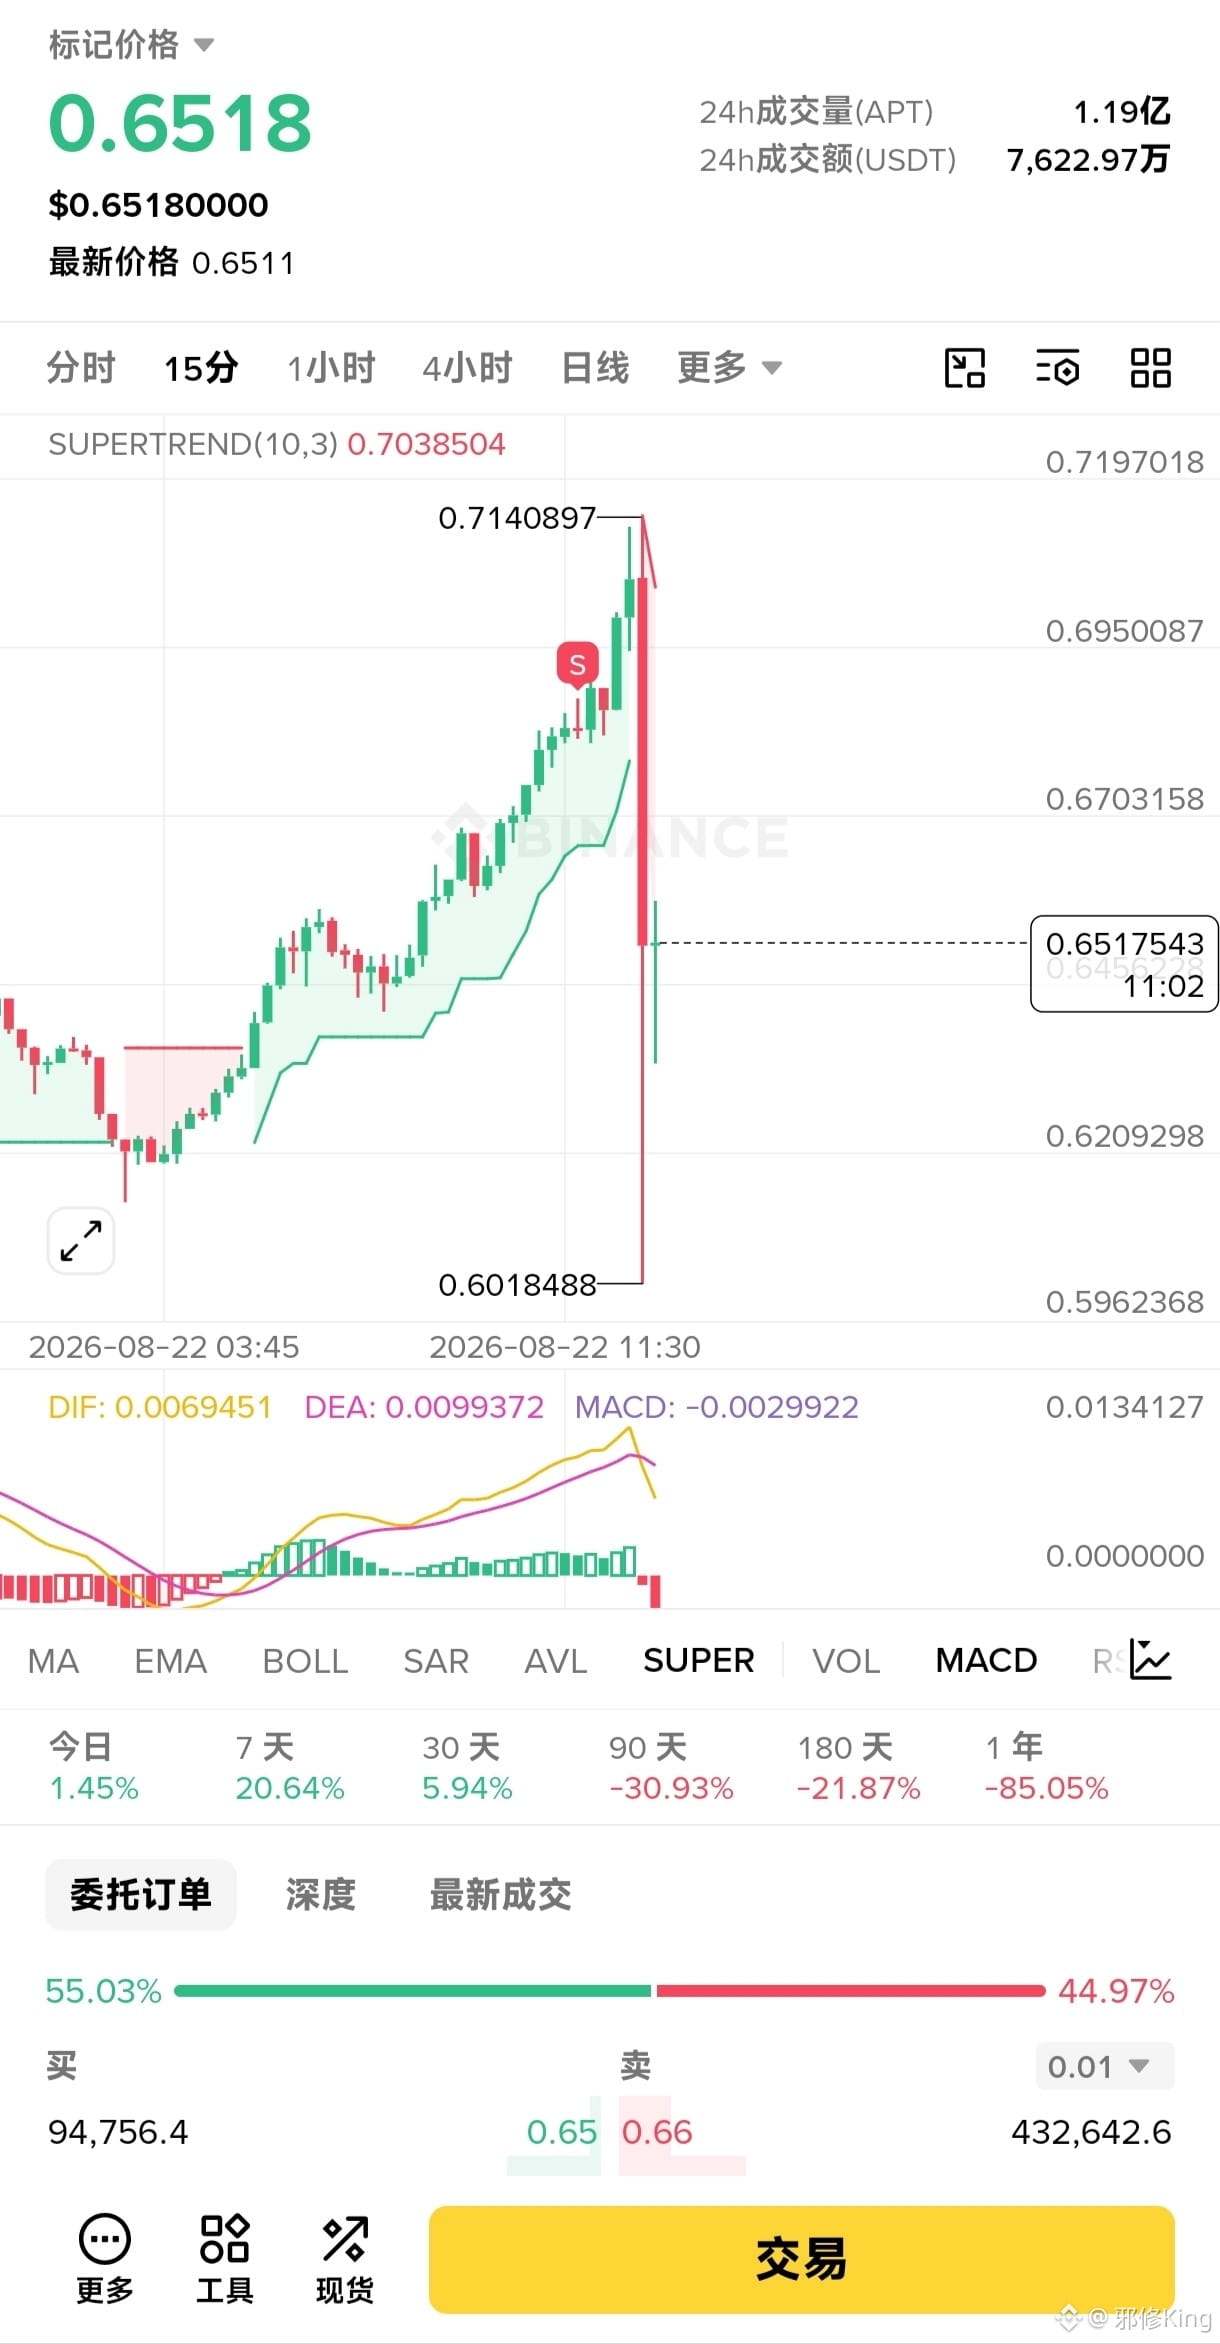
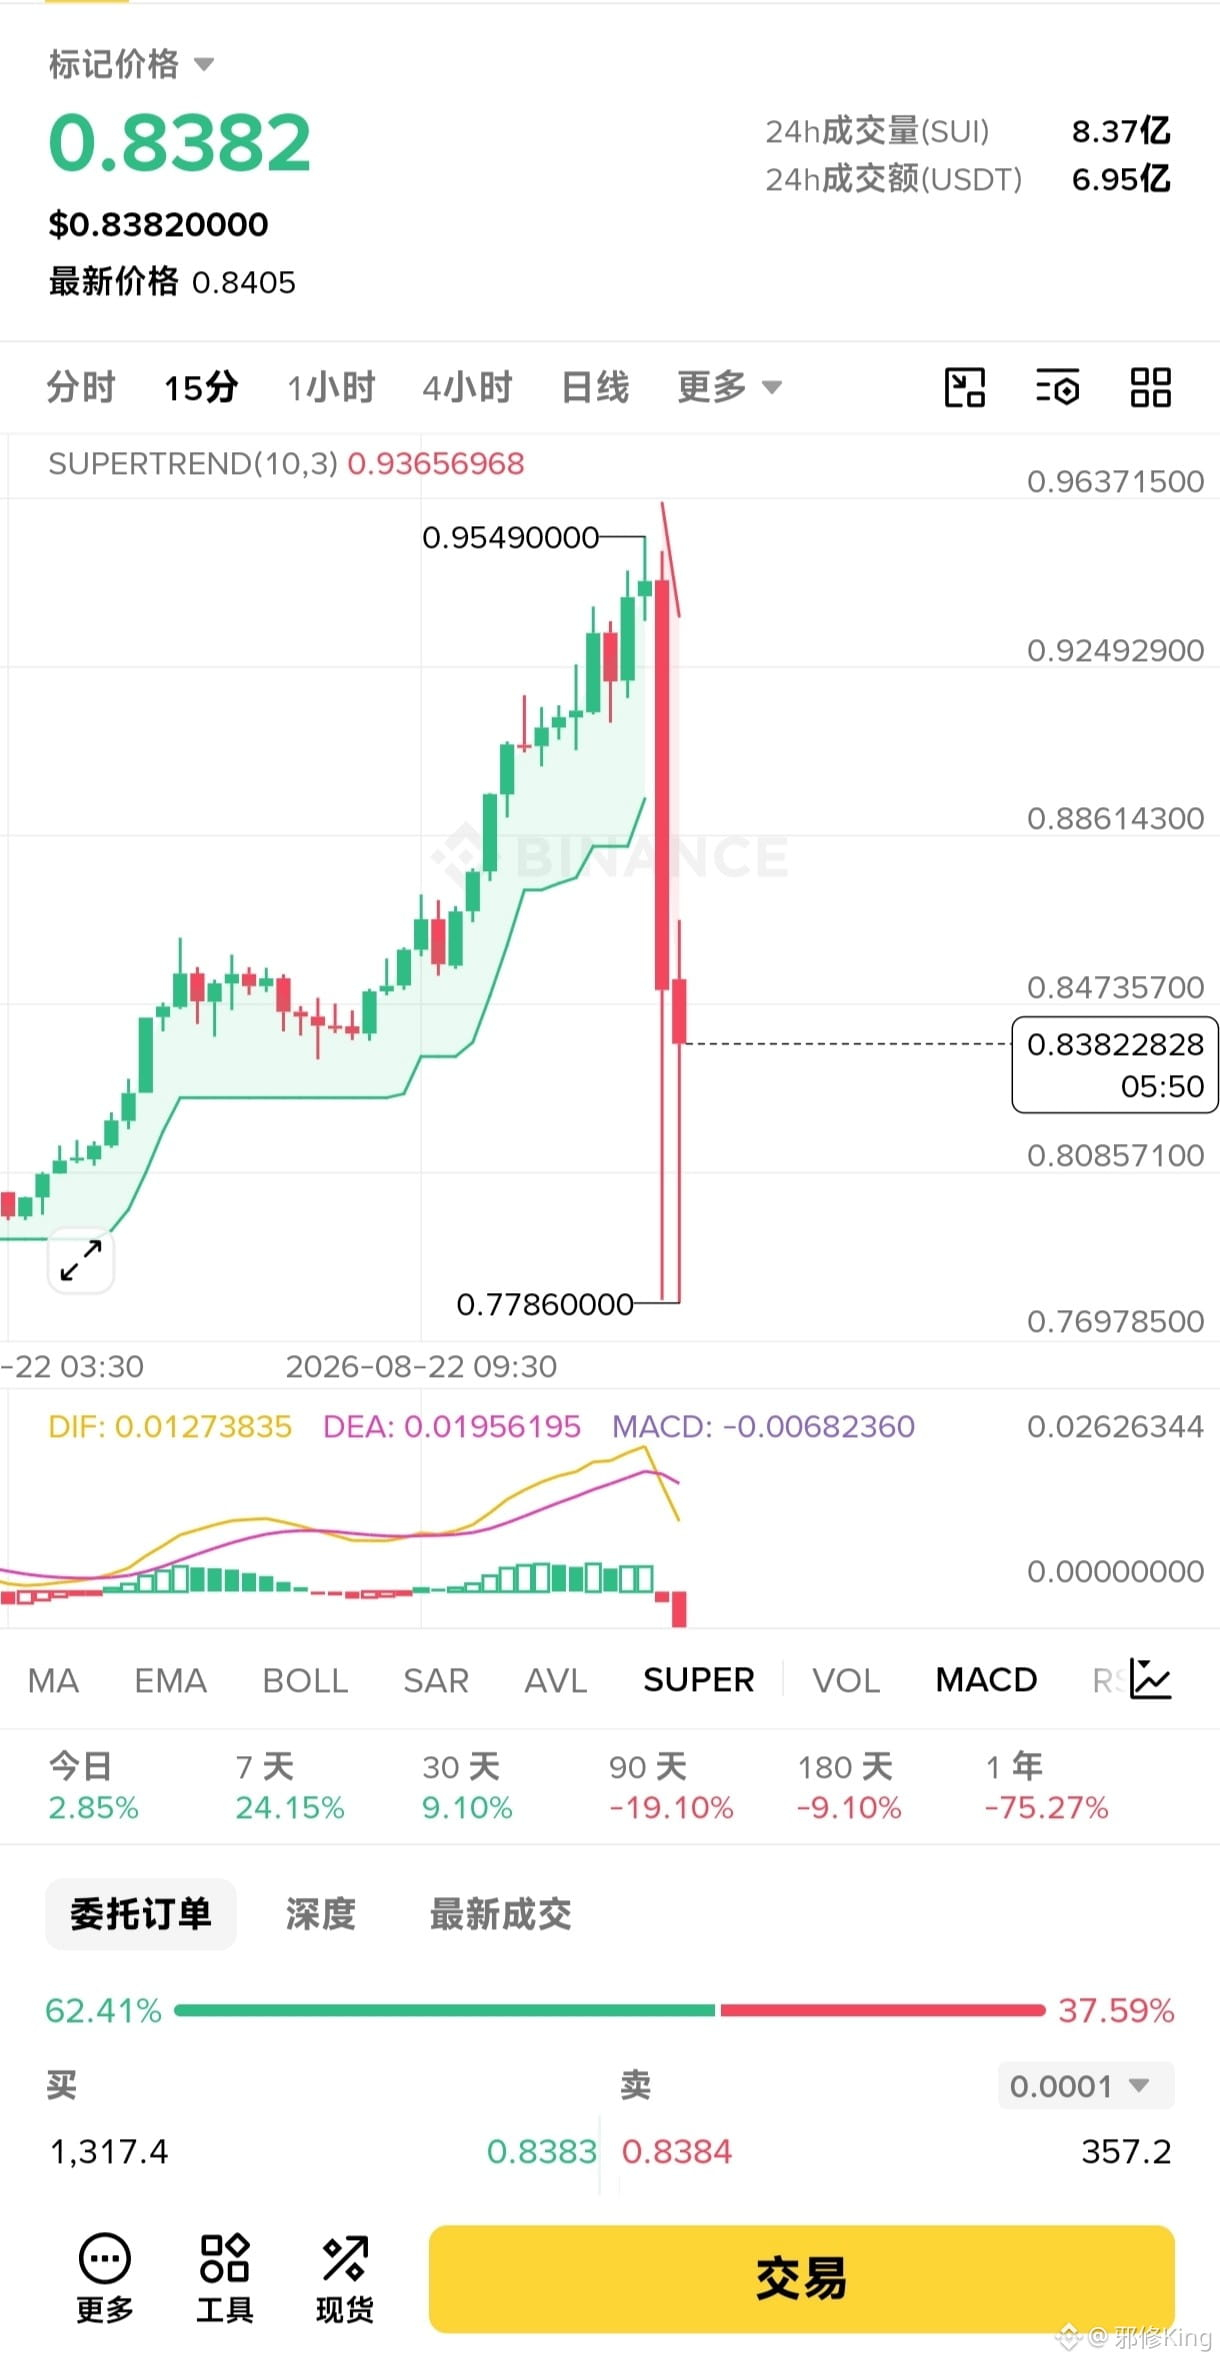
Many big shots didn’t get on the train, and they’re forcefully demanding a back-and-pickup to restart.
In that moment, all of yesterday’s gains got wiped out.
A big shot said: “Go up your damn ‘up’; I haven’t even gotten on yet—come back and let me eat my limit order.”
$HYPE $ASTER
{future}(ASTERUSDT)
Many big shots didn’t get on the train, and they’re forcefully demanding a back-and-pickup to restart.
In that moment, all of yesterday’s gains got wiped out.
A big shot said: “Go up your damn ‘up’; I haven’t even gotten on yet—come back and let me eat my limit order.”
$HYPE $ASTER
In that moment, all of yesterday’s gains got wiped out.
A big shot said: “Go up your damn ‘up’; I haven’t even gotten on yet—come back and let me eat my limit order.”
$HYPE $ASTER
529
·
--
Bullish
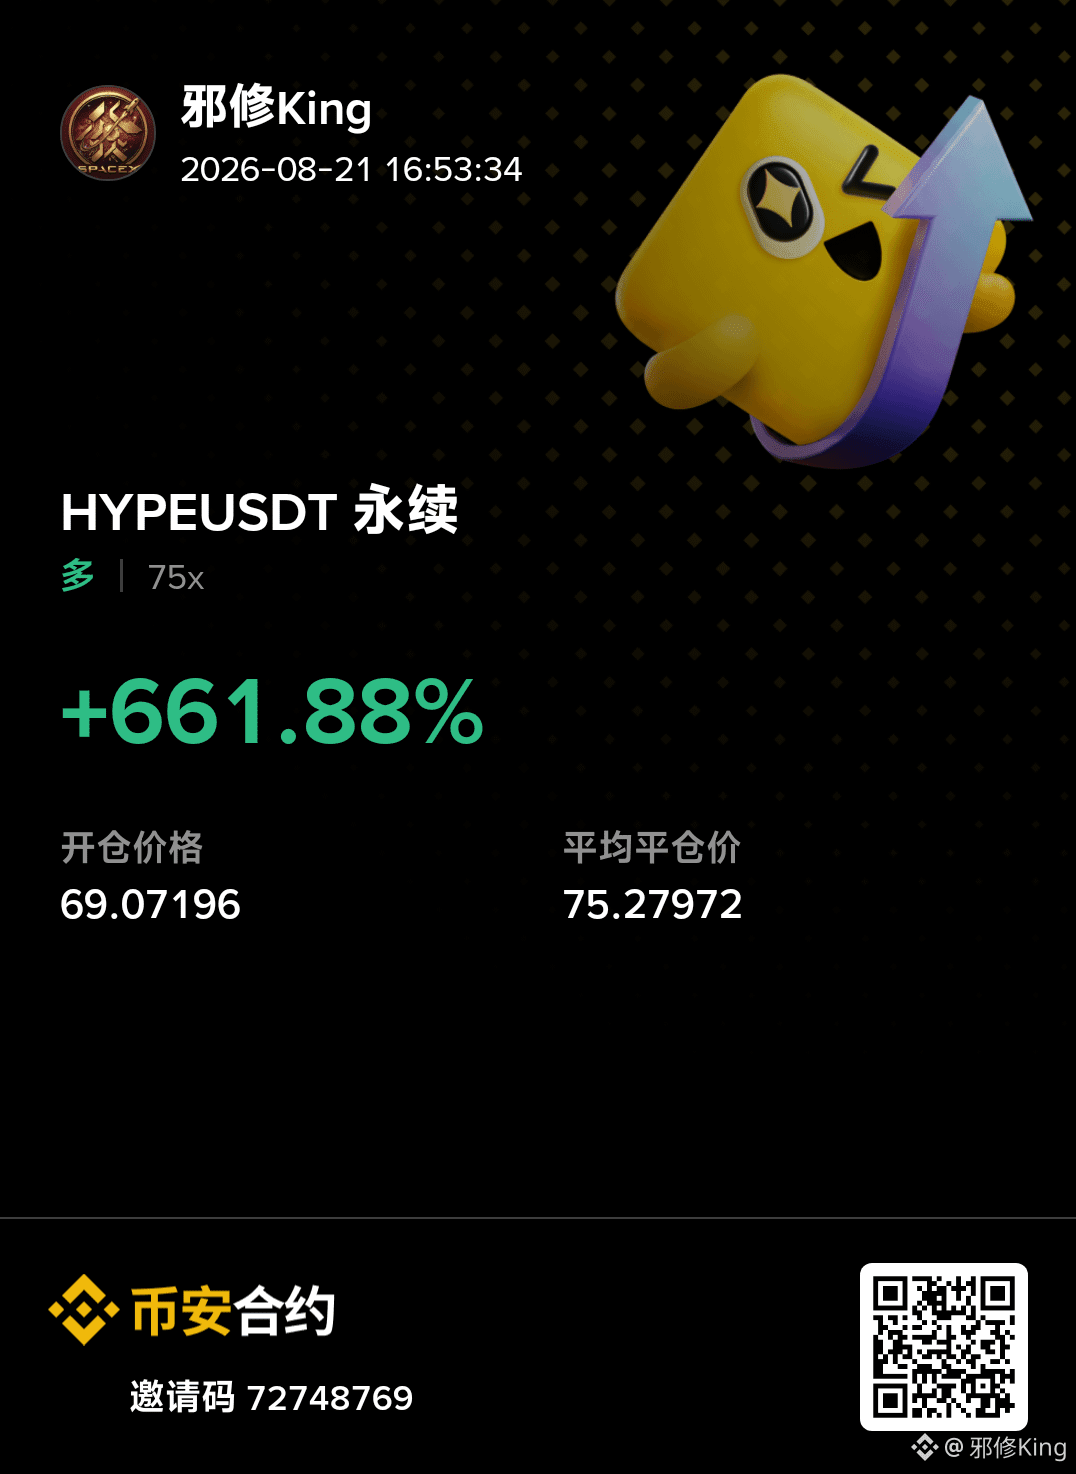
I ran, I ran—today’s increase is way too scary.
https://www.binance.com/cn/futures/ref/72748769
I ran, I ran—today’s increase is way too scary.
https://www.binance.com/cn/futures/ref/72748769
https://www.binance.com/cn/futures/ref/72748769
109
·
--
Bullish
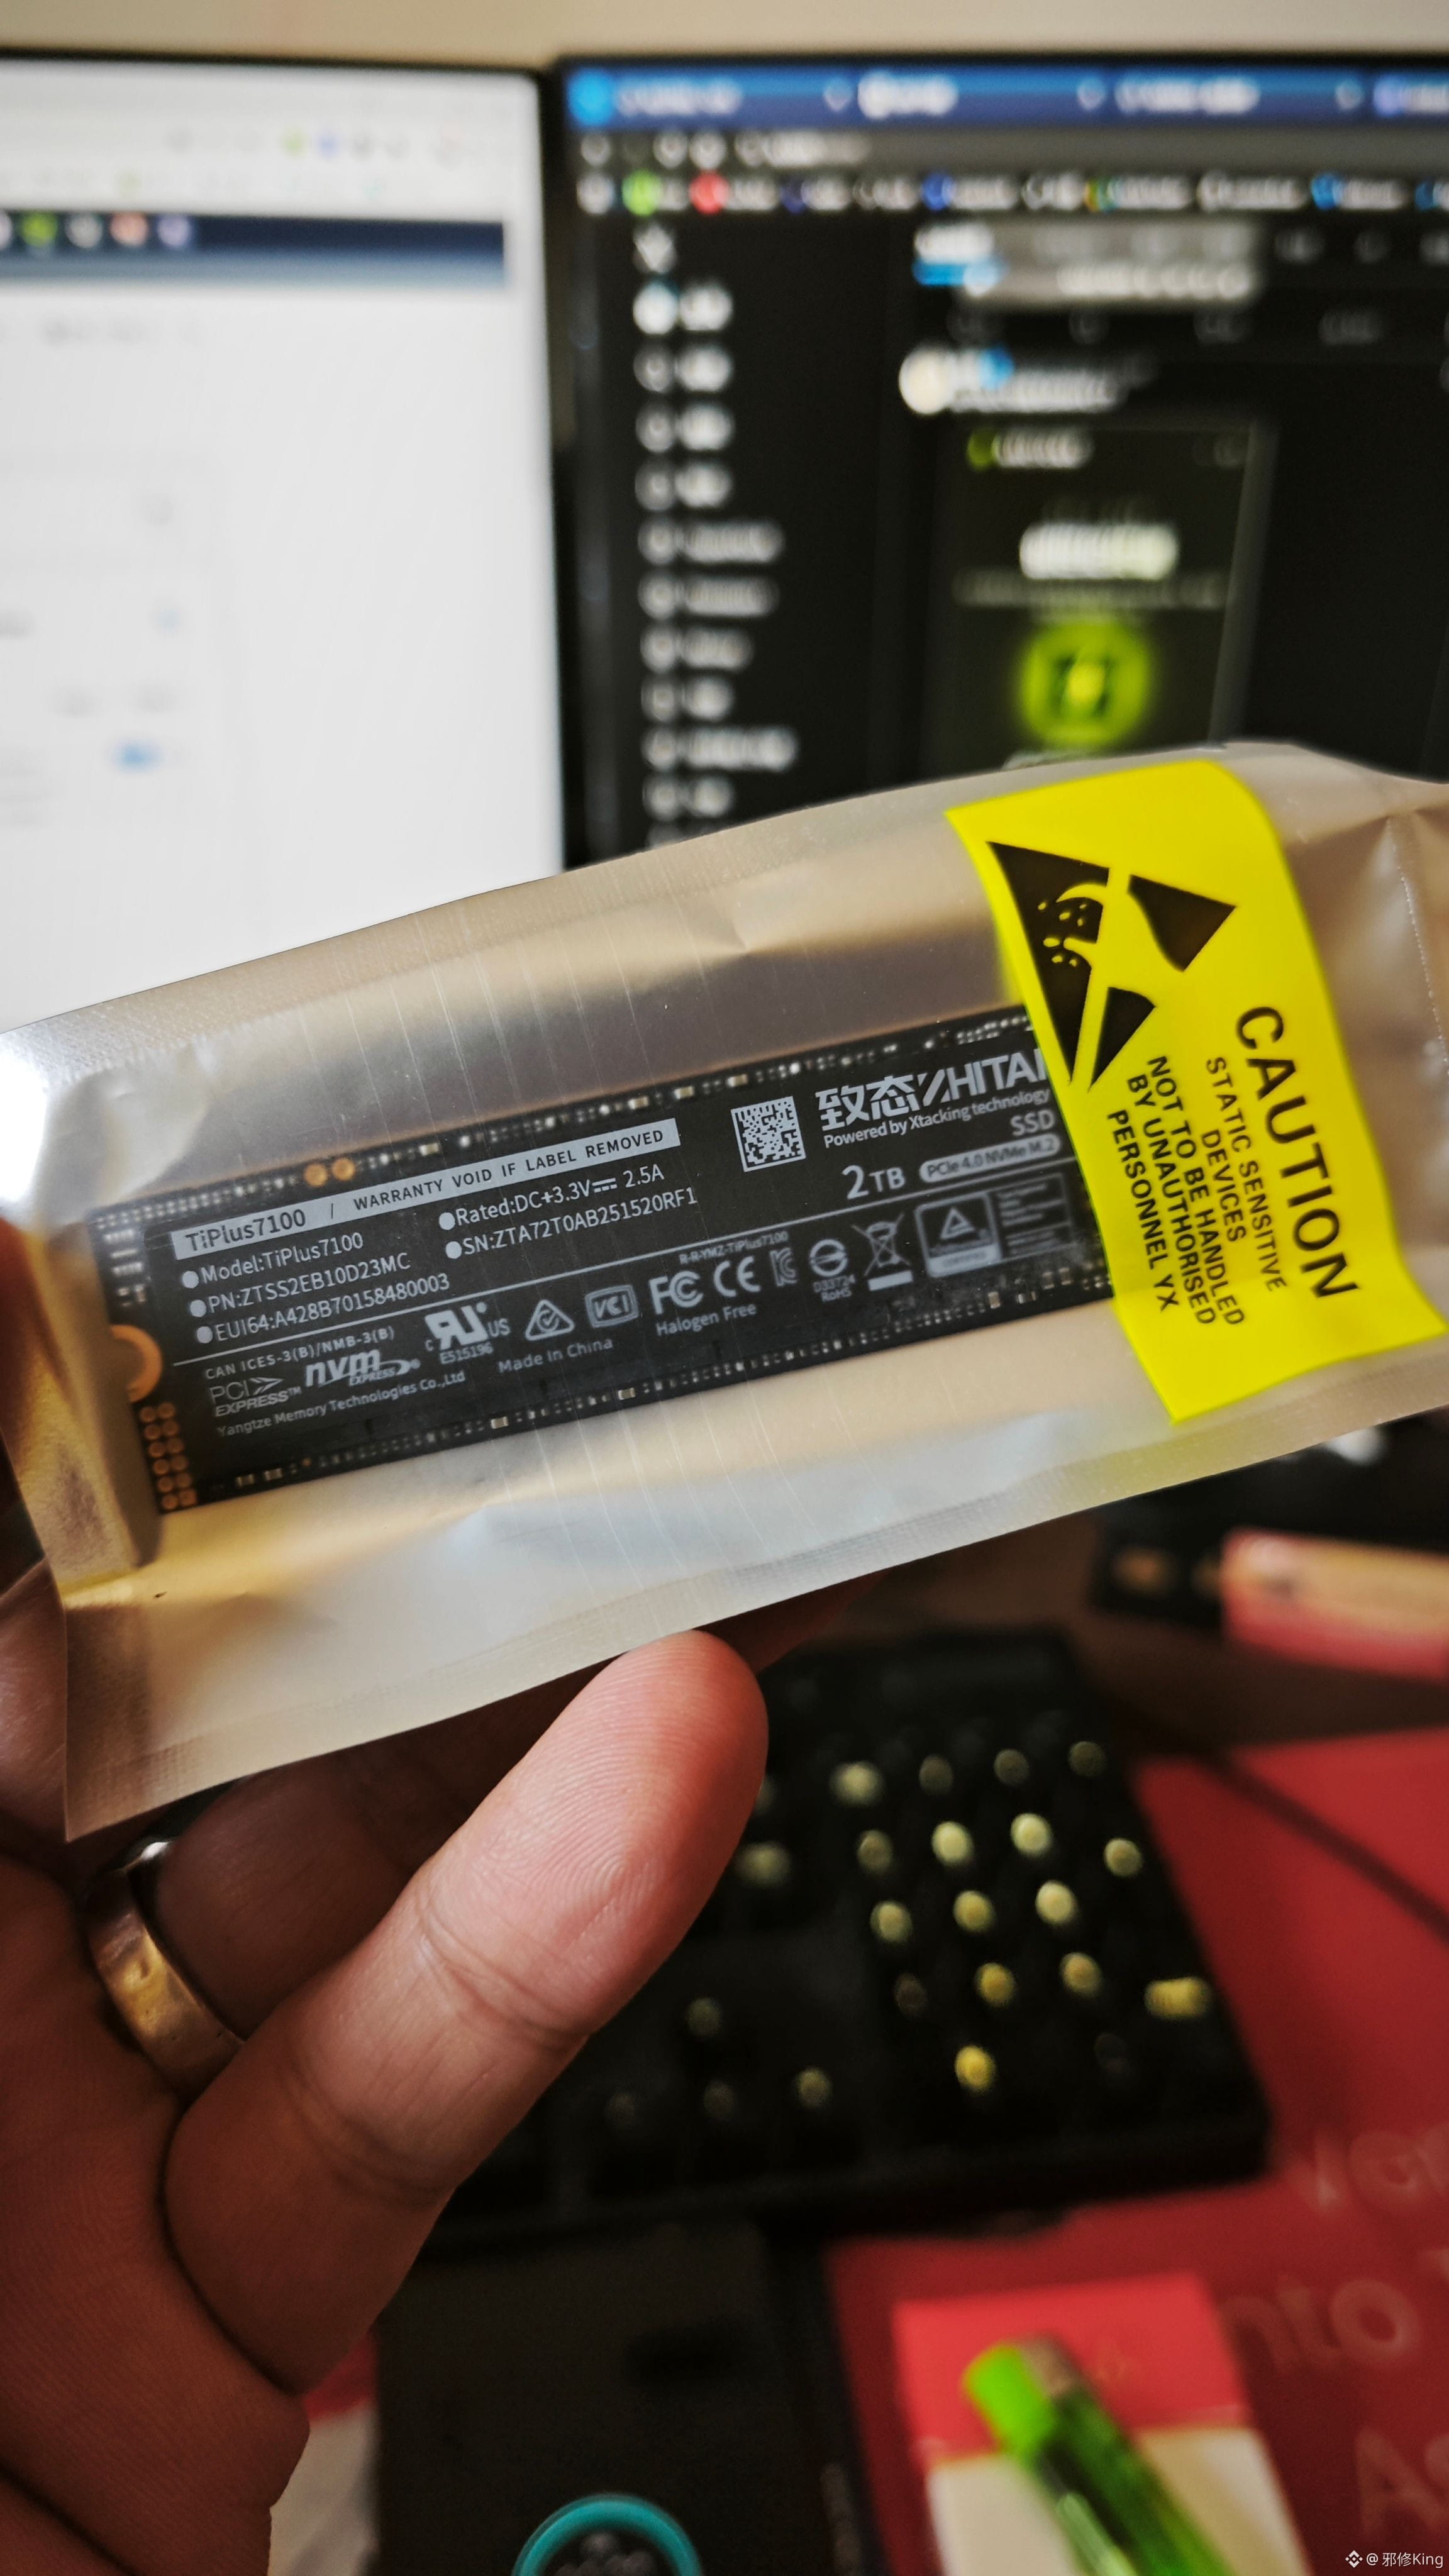
$MUon $MUB People say storage is no good now, it’s not working. Then why don’t you lower the terminal prices?
Back when hard drives were 400–500, now it’s 2000 yuan. If it weren’t a necessity, I really wouldn’t want to buy.
{future}(MUUSDT)
$MUon $MUB People say storage is no good now, it’s not working. Then why don’t you lower the terminal prices?
Back when hard drives were 400–500, now it’s 2000 yuan. If it weren’t a necessity, I really wouldn’t want to buy.
Back when hard drives were 400–500, now it’s 2000 yuan. If it weren’t a necessity, I really wouldn’t want to buy.
201
·
--
Bullish
$TSLA
{future}(TSLAUSDT)
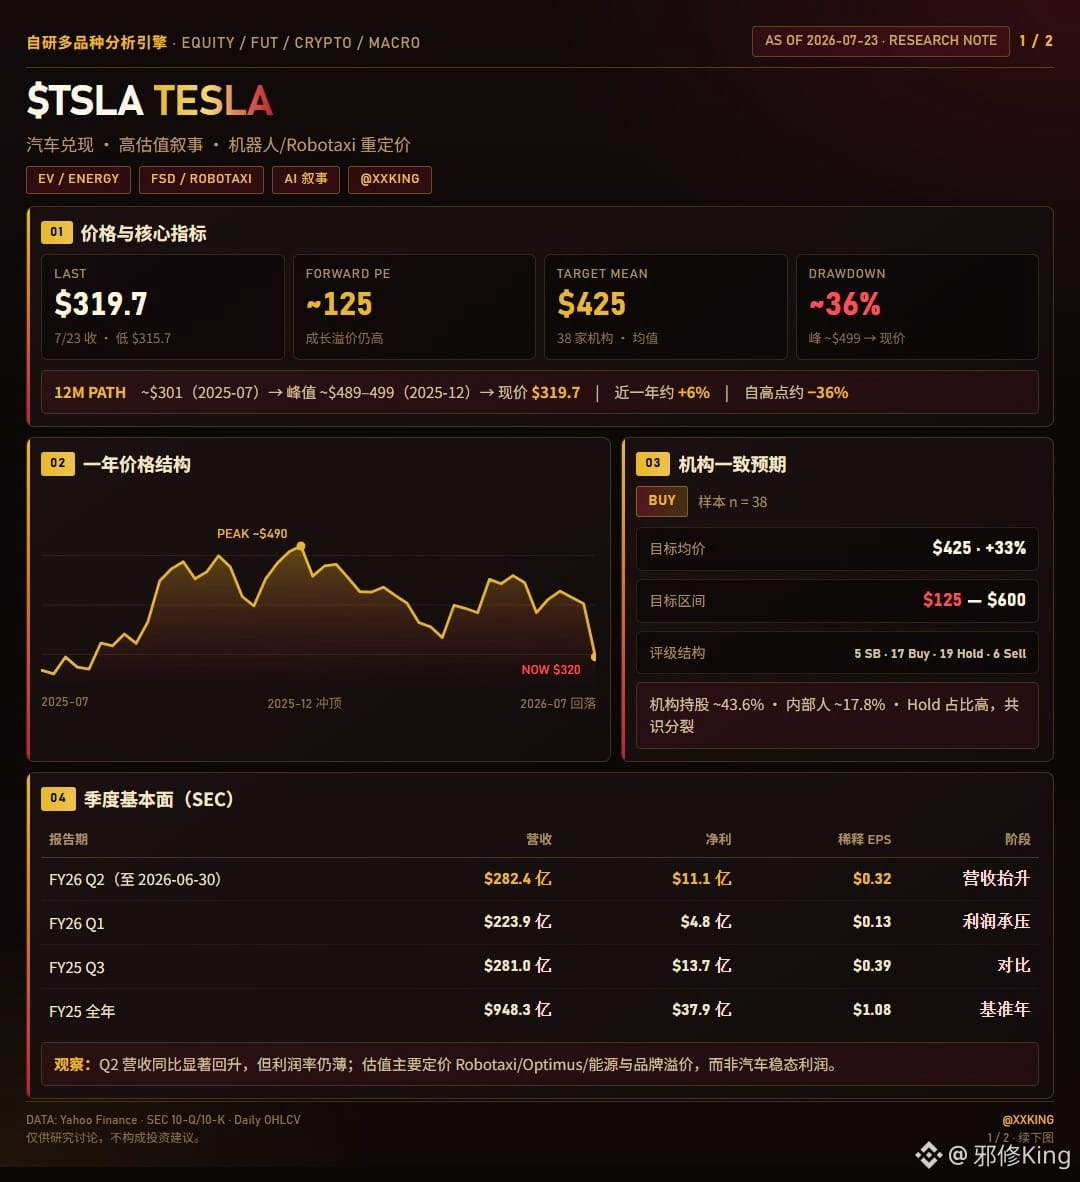
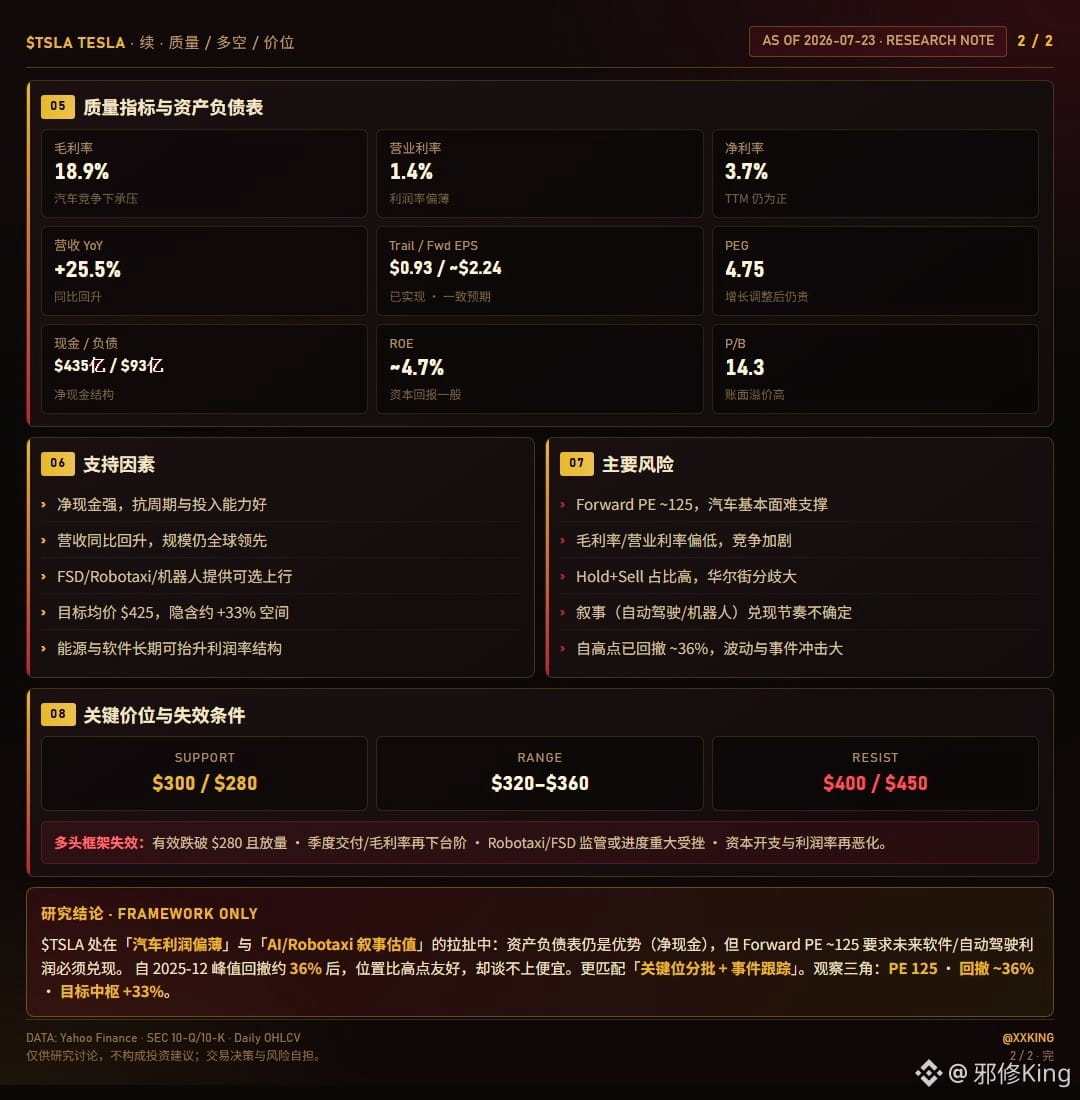
It's done. Research notes do not constitute investment advice.
Current price ~$319.7, down about 36% from the peak at the end of 2025.
Forward PE is around 125, and the Street’s target central value is $425 (38 analysts, overall more bullish), though many are Hold/Sell; the target range is $125–$600.
Last quarter: revenue of $28.2B, net income of $1.1B, EPS of 0.32; gross margin around 19%, and operating margin only about 1.4%.
The balance sheet is still solid: cash $43.5B, liabilities $9.3B.
What I care about most are three things:
1) Whether $300 / $280 can hold
2) Whether gross margin and deliveries can avoid slipping further
3) Whether the Robotaxi/FSD progress can justify the valuation
Full data is split into 2 charts: top half—price, earnings, and results; bottom half—quality, bull/bear levels.
#TSLA
$TSLA
It's done. Research notes do not constitute investment advice.
Current price ~$319.7, down about 36% from the peak at the end of 2025.
Forward PE is around 125, and the Street’s target central value is $425 (38 analysts, overall more bullish), though many are Hold/Sell; the target range is $125–$600.
Last quarter: revenue of $28.2B, net income of $1.1B, EPS of 0.32; gross margin around 19%, and operating margin only about 1.4%.
The balance sheet is still solid: cash $43.5B, liabilities $9.3B.
What I care about most are three things:
1) Whether $300 / $280 can hold
2) Whether gross margin and deliveries can avoid slipping further
3) Whether the Robotaxi/FSD progress can justify the valuation
Full data is split into 2 charts: top half—price, earnings, and results; bottom half—quality, bull/bear levels.
#TSLA
It's done. Research notes do not constitute investment advice.
Current price ~$319.7, down about 36% from the peak at the end of 2025.
Forward PE is around 125, and the Street’s target central value is $425 (38 analysts, overall more bullish), though many are Hold/Sell; the target range is $125–$600.
Last quarter: revenue of $28.2B, net income of $1.1B, EPS of 0.32; gross margin around 19%, and operating margin only about 1.4%.
The balance sheet is still solid: cash $43.5B, liabilities $9.3B.
What I care about most are three things:
1) Whether $300 / $280 can hold
2) Whether gross margin and deliveries can avoid slipping further
3) Whether the Robotaxi/FSD progress can justify the valuation
Full data is split into 2 charts: top half—price, earnings, and results; bottom half—quality, bull/bear levels.
#TSLA
156
·
--
Bullish
$MUB
{spot}(MUBUSDT)
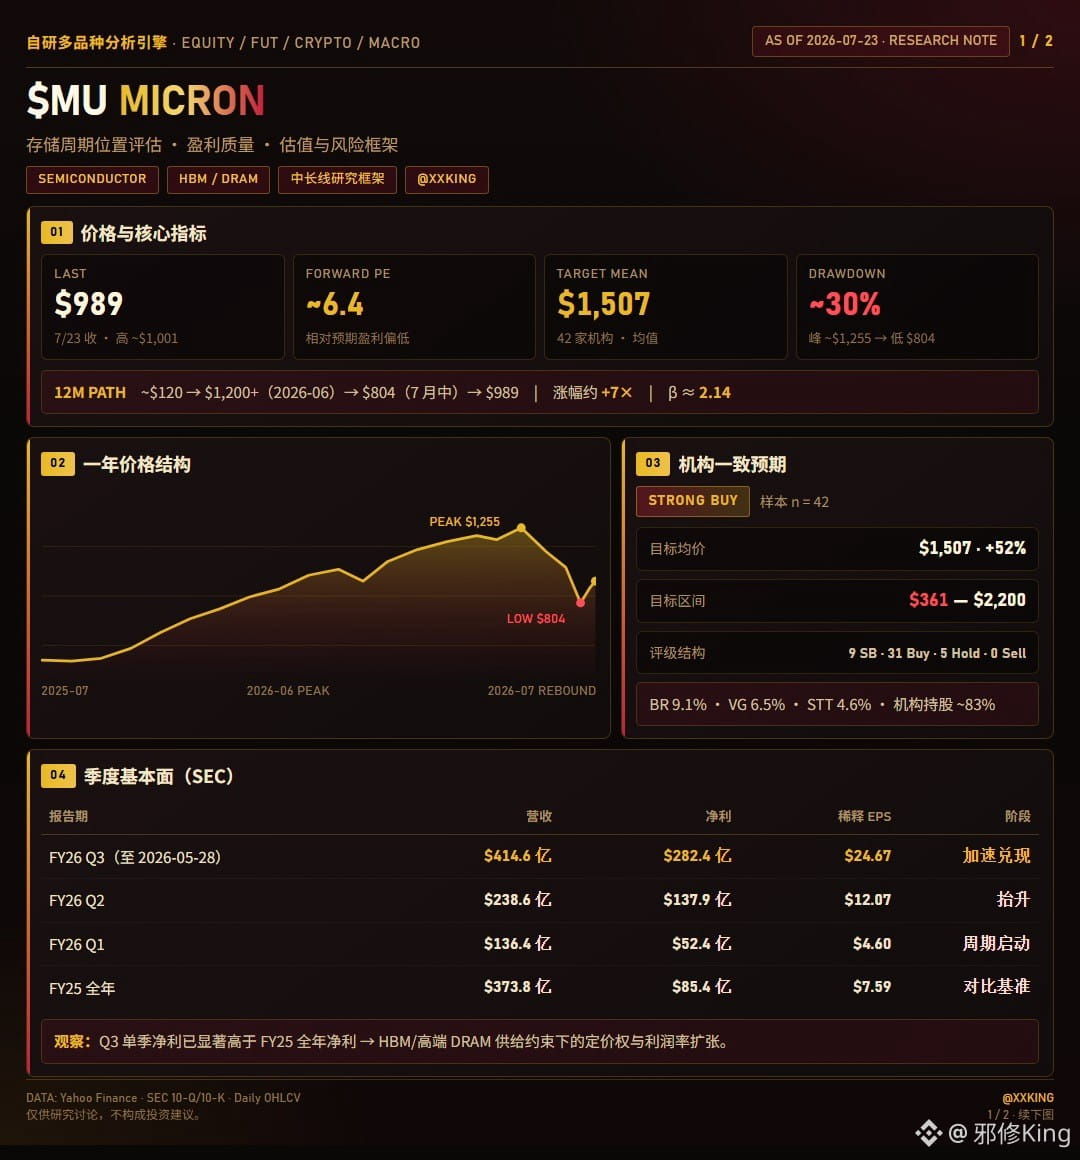
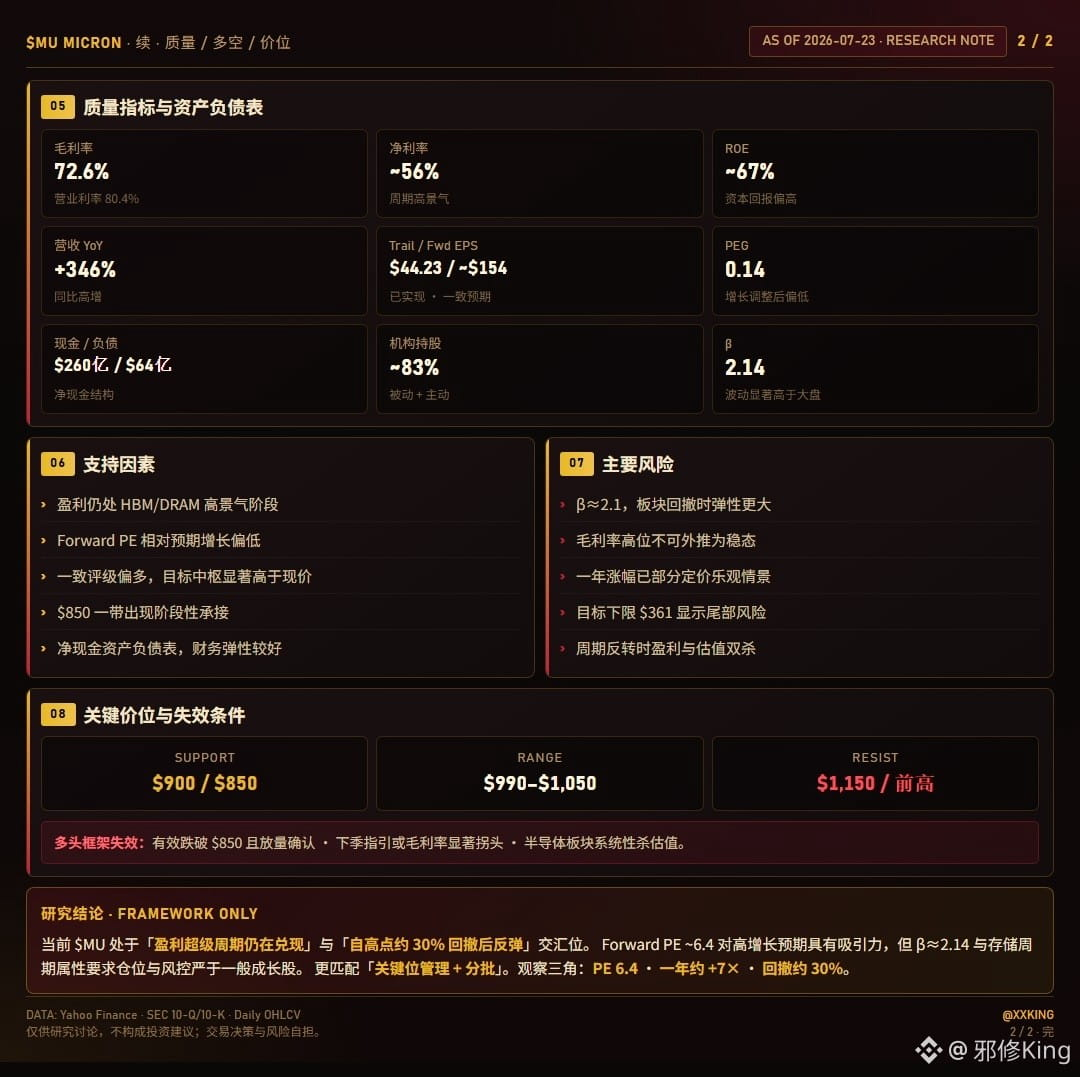
Done with the analysis—conclusion up front:
Current price is about ~$989. After a ~30% pullback from the peak, it’s rebounding.
Forward PE is around 6.4. The Wall Street target price mid-point is $1507 (42 firms, overall tilted bullish).
On the fundamentals side, it’s still very strong: last quarter revenue was 41.5 billion, and net profit was 28.2 billion—single-quarter profit already surpasses the full prior year.
HBM/memory demand remains strong, but β is 2.1, so volatility will be much higher than most typical growth stocks.
I care most about three things:
1) Whether $850 can hold
2) Whether the next-quarter guidance and gross margin show a turn
3) Whether the semiconductor sector will hit valuation together
Full data, bull/bear views, and price-level framework are in the long-form chart.
Research notes only—does not constitute investment advice.
#MU
$MUB
Done with the analysis—conclusion up front:
Current price is about ~$989. After a ~30% pullback from the peak, it’s rebounding.
Forward PE is around 6.4. The Wall Street target price mid-point is $1507 (42 firms, overall tilted bullish).
On the fundamentals side, it’s still very strong: last quarter revenue was 41.5 billion, and net profit was 28.2 billion—single-quarter profit already surpasses the full prior year.
HBM/memory demand remains strong, but β is 2.1, so volatility will be much higher than most typical growth stocks.
I care most about three things:
1) Whether $850 can hold
2) Whether the next-quarter guidance and gross margin show a turn
3) Whether the semiconductor sector will hit valuation together
Full data, bull/bear views, and price-level framework are in the long-form chart.
Research notes only—does not constitute investment advice.
#MU
Done with the analysis—conclusion up front:
Current price is about ~$989. After a ~30% pullback from the peak, it’s rebounding.
Forward PE is around 6.4. The Wall Street target price mid-point is $1507 (42 firms, overall tilted bullish).
On the fundamentals side, it’s still very strong: last quarter revenue was 41.5 billion, and net profit was 28.2 billion—single-quarter profit already surpasses the full prior year.
HBM/memory demand remains strong, but β is 2.1, so volatility will be much higher than most typical growth stocks.
I care most about three things:
1) Whether $850 can hold
2) Whether the next-quarter guidance and gross margin show a turn
3) Whether the semiconductor sector will hit valuation together
Full data, bull/bear views, and price-level framework are in the long-form chart.
Research notes only—does not constitute investment advice.
#MU
224
·
--
Bullish
$SPCX
{future}(SPCXUSDT)
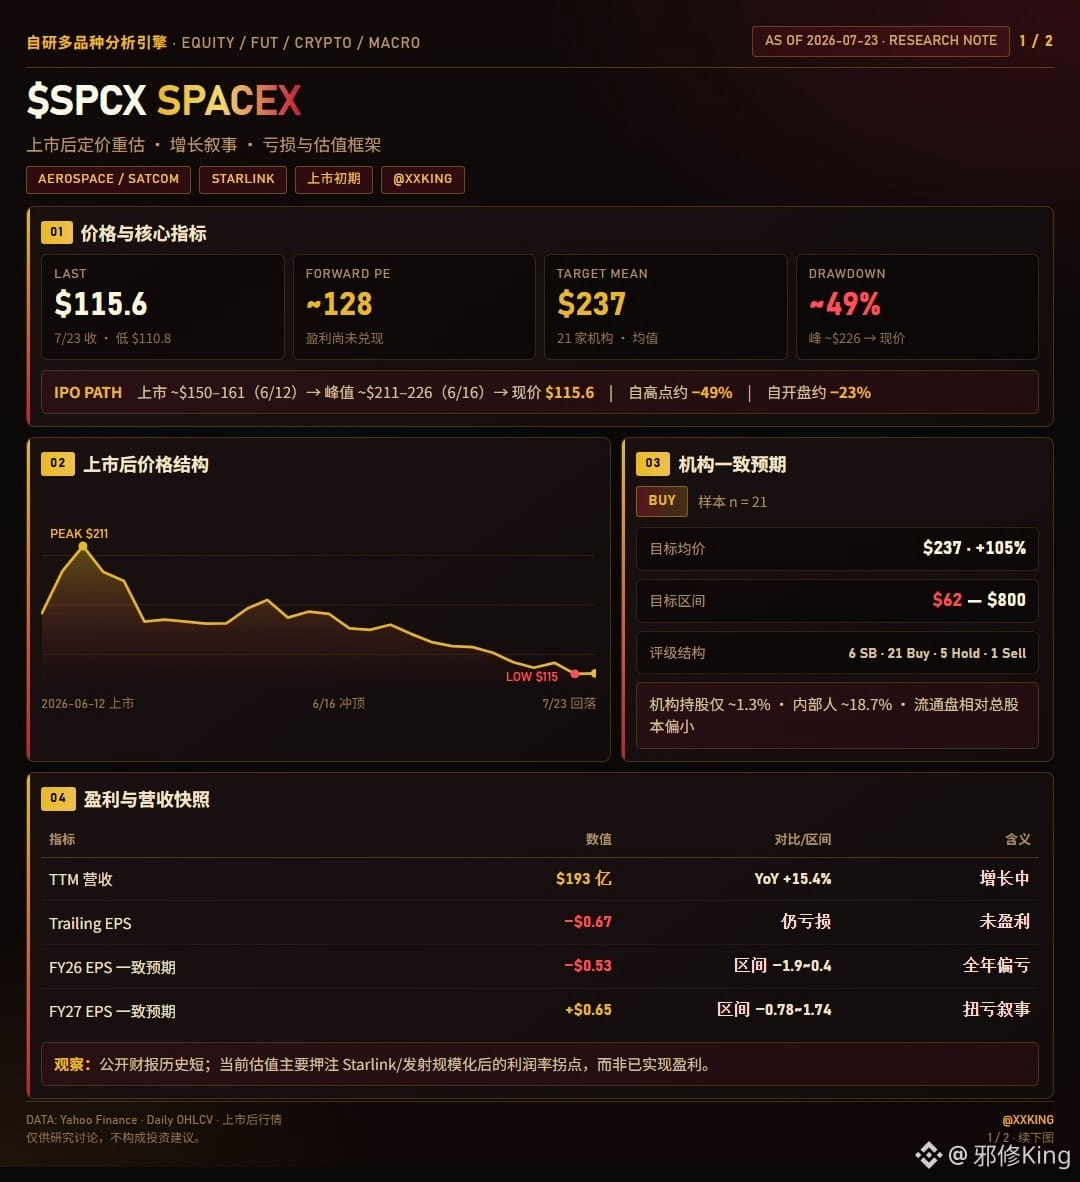
All dismantled
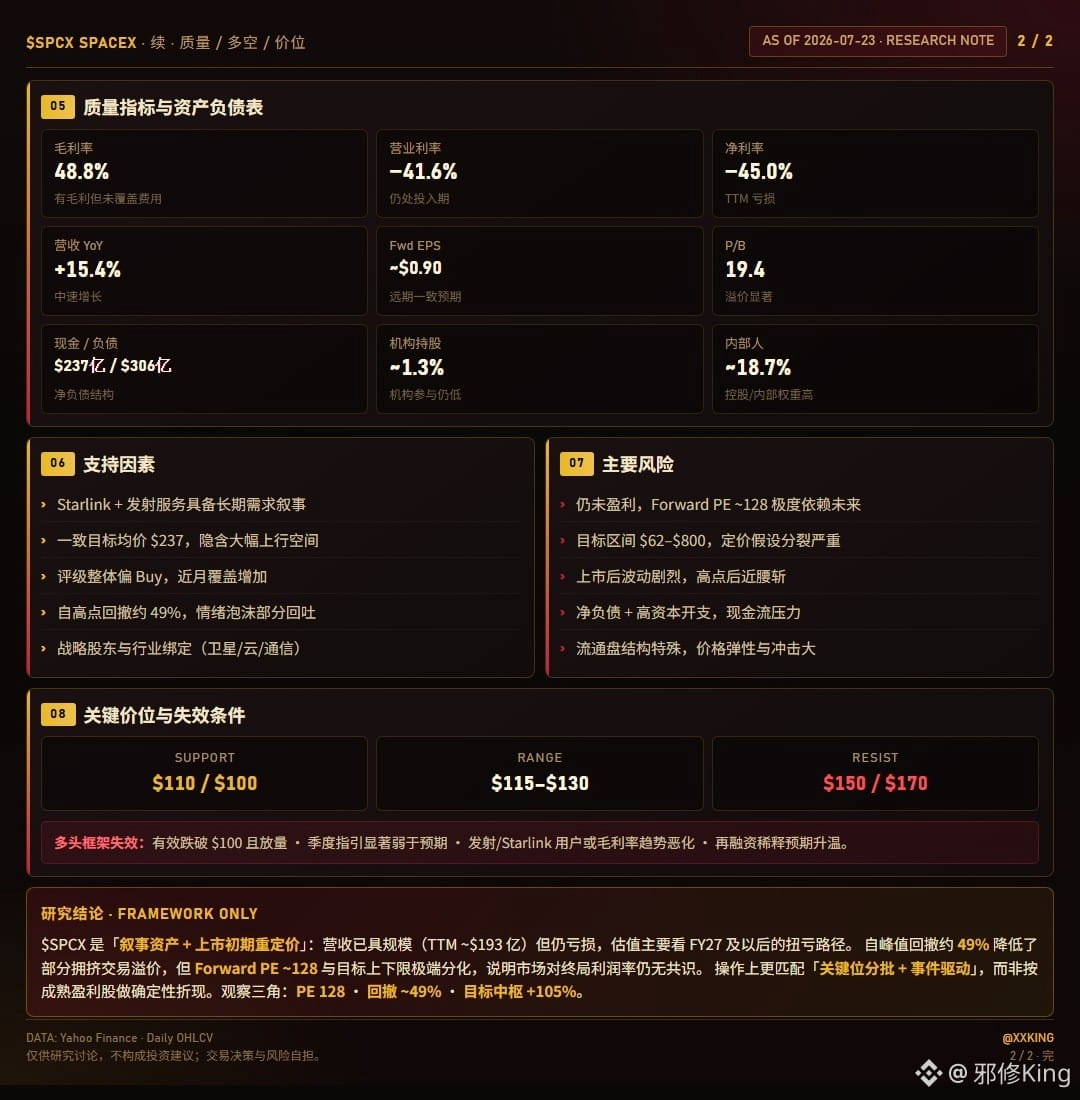
Current price ~$115.6. It’s been listed for about a month and a half, and has pulled back roughly 49% from the peak.
Forward PE is about 128. Wall Street’s target consensus center is $237 (21 firms, overall leaning bullish), but the target range is $62–$800—there’s a lot of disagreement.
On the revenue side, there’s scale: TTM revenue is about $19.3B, up 15% year over year.
On the profit side, things are still tough: trailing EPS is −0.67, operating margin is about −42%. Cash is $23.7B and liabilities are $30.6B.
I care about three things most:
1) Whether $110 / $100 can hold
2) Whether next-quarter guidance and Starlink/launch pacing have been delivered
3) Whether it will be repriced again due to refinancing/dilution
Full data is split into 2 charts: first half—price/financial reports; second half—quality and long/short price levels.
Research notes only; not investment advice.
#SPCX
$SPCX
All dismantled
Current price ~$115.6. It’s been listed for about a month and a half, and has pulled back roughly 49% from the peak.
Forward PE is about 128. Wall Street’s target consensus center is $237 (21 firms, overall leaning bullish), but the target range is $62–$800—there’s a lot of disagreement.
On the revenue side, there’s scale: TTM revenue is about $19.3B, up 15% year over year.
On the profit side, things are still tough: trailing EPS is −0.67, operating margin is about −42%. Cash is $23.7B and liabilities are $30.6B.
I care about three things most:
1) Whether $110 / $100 can hold
2) Whether next-quarter guidance and Starlink/launch pacing have been delivered
3) Whether it will be repriced again due to refinancing/dilution
Full data is split into 2 charts: first half—price/financial reports; second half—quality and long/short price levels.
Research notes only; not investment advice.
#SPCX
All dismantled
Current price ~$115.6. It’s been listed for about a month and a half, and has pulled back roughly 49% from the peak.
Forward PE is about 128. Wall Street’s target consensus center is $237 (21 firms, overall leaning bullish), but the target range is $62–$800—there’s a lot of disagreement.
On the revenue side, there’s scale: TTM revenue is about $19.3B, up 15% year over year.
On the profit side, things are still tough: trailing EPS is −0.67, operating margin is about −42%. Cash is $23.7B and liabilities are $30.6B.
I care about three things most:
1) Whether $110 / $100 can hold
2) Whether next-quarter guidance and Starlink/launch pacing have been delivered
3) Whether it will be repriced again due to refinancing/dilution
Full data is split into 2 charts: first half—price/financial reports; second half—quality and long/short price levels.
Research notes only; not investment advice.
#SPCX
263
·
--
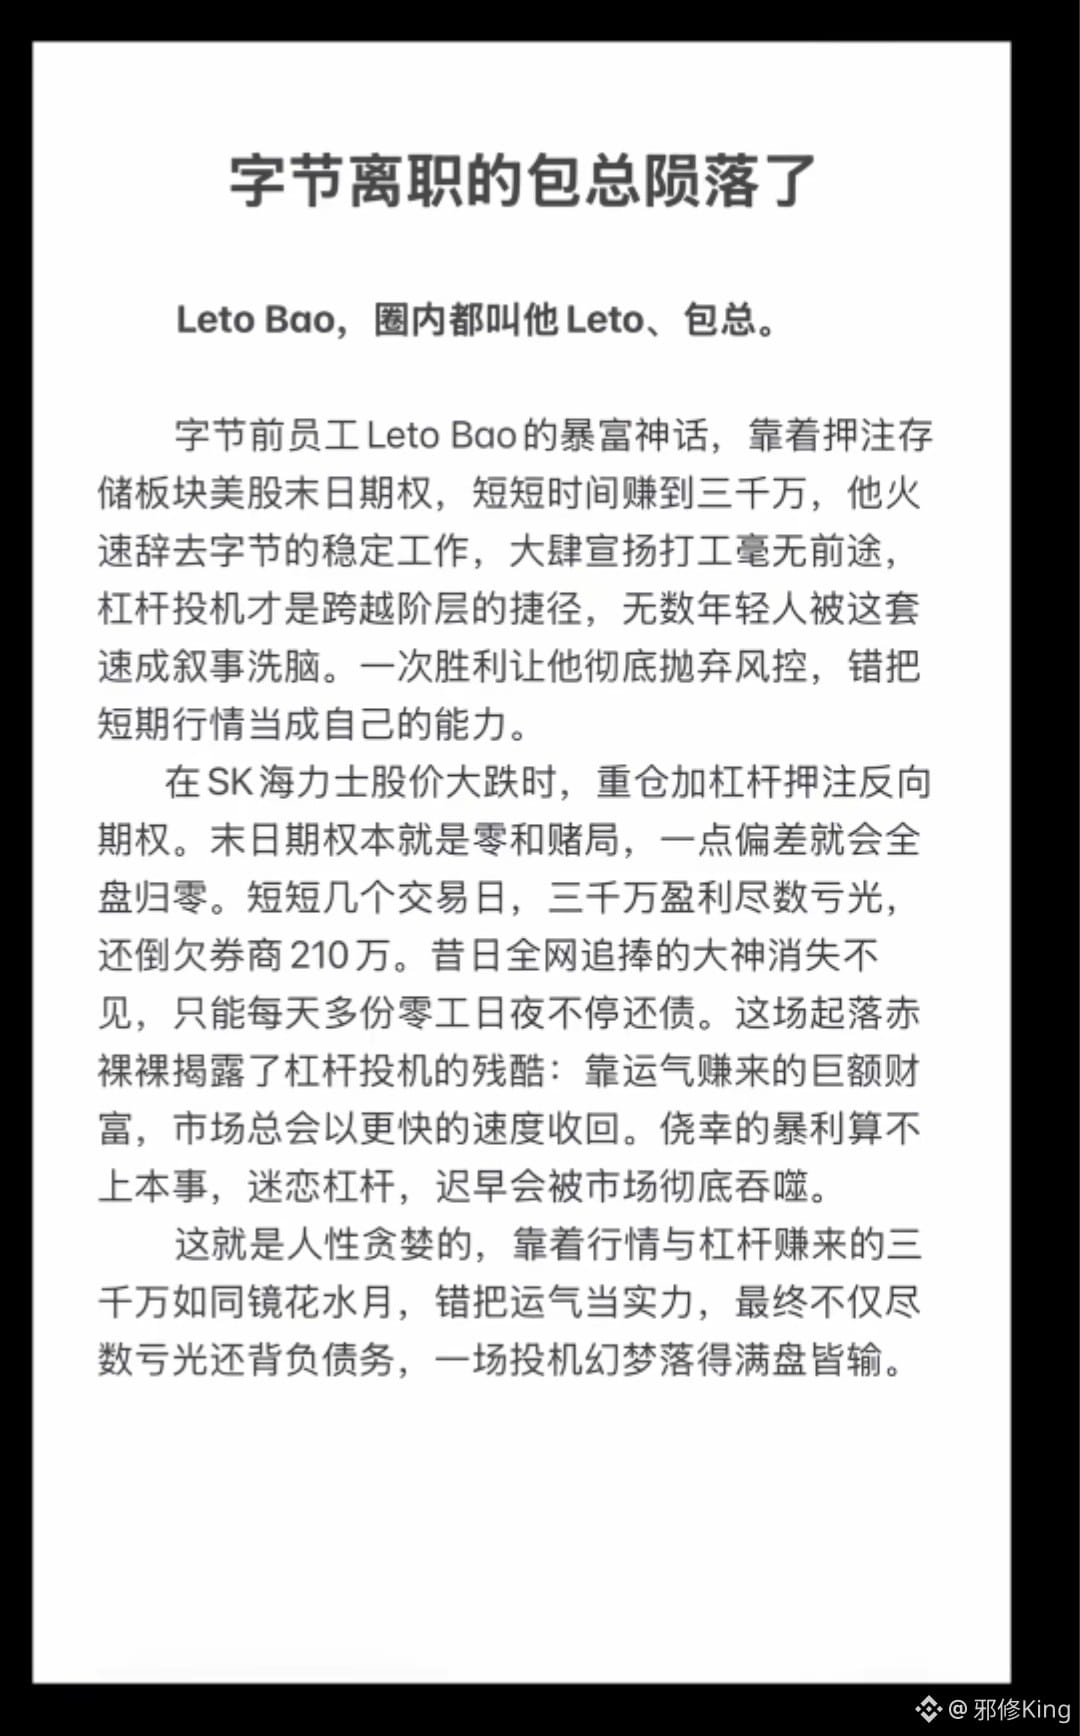
For real? Is this lucky period so short? No wonder we can’t see him explaining concepts~~
Whether it’s true or not, money earned on luck will eventually be paid back with实力 (real ability). The value of this saying is still rising!!!
We didn’t earn A9-A10, but we did preserve A7-A8~~$SPCXB
{spot}(SPCXBUSDT)
For real? Is this lucky period so short? No wonder we can’t see him explaining concepts~~
Whether it’s true or not, money earned on luck will eventually be paid back with实力 (real ability). The value of this saying is still rising!!!
We didn’t earn A9-A10, but we did preserve A7-A8~~$SPCXB
Whether it’s true or not, money earned on luck will eventually be paid back with实力 (real ability). The value of this saying is still rising!!!
We didn’t earn A9-A10, but we did preserve A7-A8~~$SPCXB
604
·
--
Verifying my Binance Square account for YZi Labs Amplify via EchoHunt: EH-6N3SHU
Verifying my Binance Square account for YZi Labs Amplify via EchoHunt: EH-6N3SHU
71
·
--
Bullish
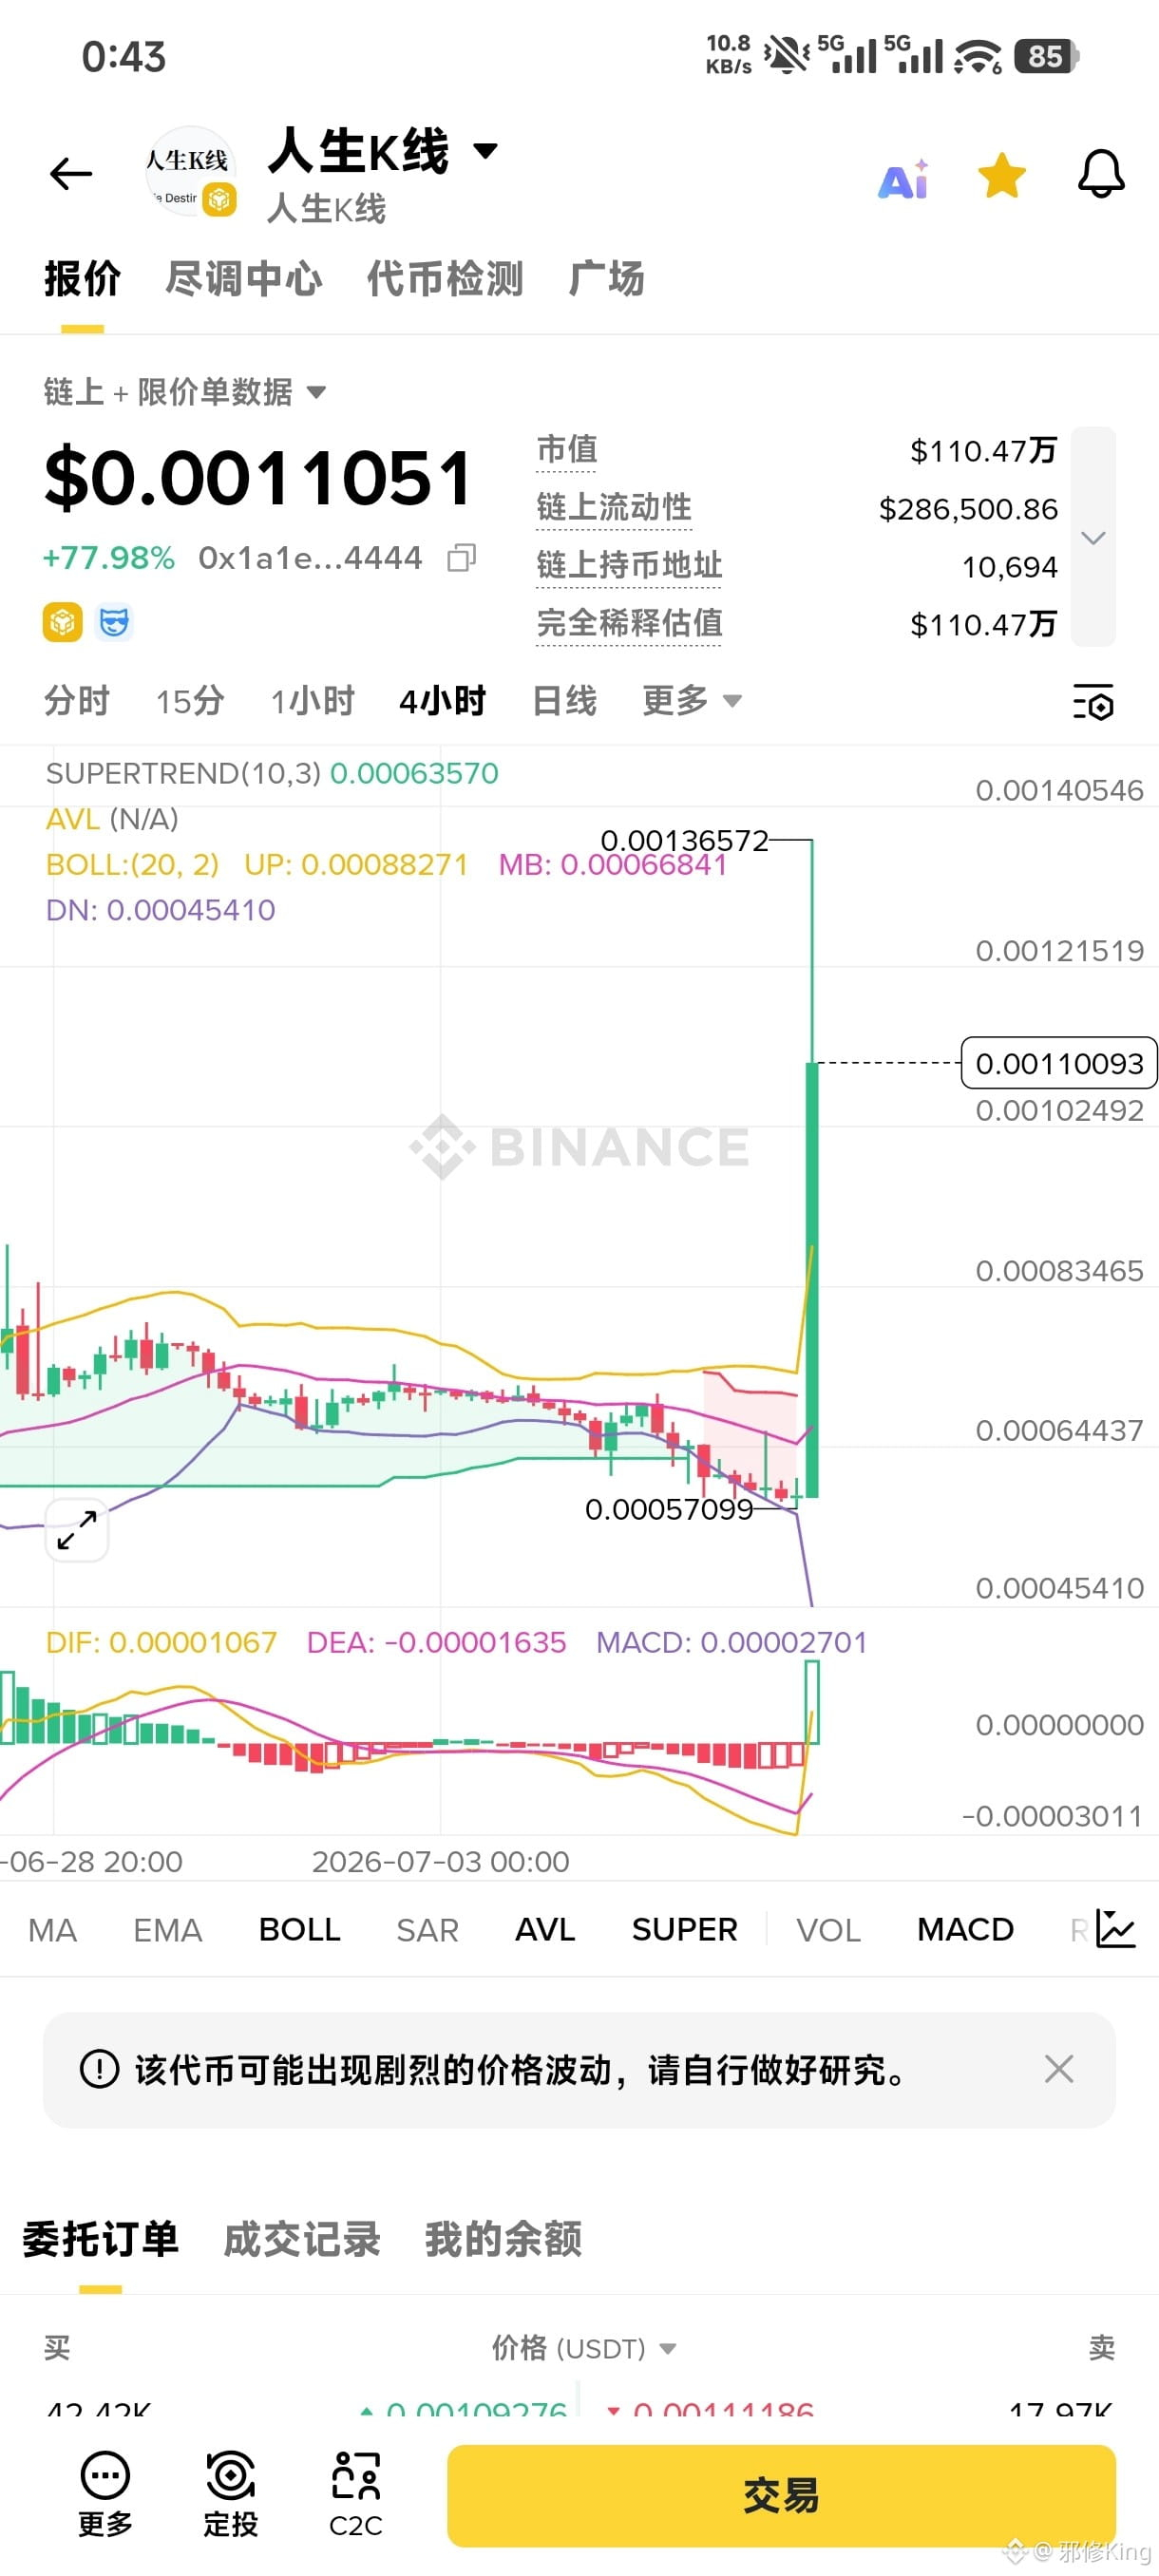
What happened on $人生K线 —so exciting, is the meme really back?
What happened on $人生K线 —so exciting, is the meme really back?
1.6k
·
--
$SPCX is fully loaded either long or short, just remember one thing: money earned through luck will eventually be lost through skill, plus doubling down on debt! Whether long or short, there are arguments for both, and they’re all valid. Floating a loss of 10 million, in the end, profit is profit, but how many people actually have 10 million in this? It’s either photoshopped or a scam; honestly, old A8 is too easy to fool!!!
$SPCX is fully loaded either long or short, just remember one thing: money earned through luck will eventually be lost through skill, plus doubling down on debt! Whether long or short, there are arguments for both, and they’re all valid. Floating a loss of 10 million, in the end, profit is profit, but how many people actually have 10 million in this? It’s either photoshopped or a scam; honestly, old A8 is too easy to fool!!!
420
·
--
Bullish
#晒出你的交易 $SPCXB let's stack up 1000 lots and see how much it pumps in a few years.
#晒出你的交易 $SPCXB let's stack up 1000 lots and see how much it pumps in a few years.
335
·
--
Bearish
Time to DCA
Time to DCA


Binance Announcement
·
--
Important Announcement Regarding the Cancellation of the SPCXx IPO Campaign and Subsequent Arrangements
This is a general announcement; the products and services mentioned here may not be available in your region.
Dear users:
Thank you for participating in the Binance Wallet SPCXx IPO Campaign. Due to circumstances beyond our control, this event cannot proceed, and we sincerely apologize for this. We have arranged the following solutions:
1. Full refund
All USDC locked by participating users will be fully refunded to your Binance wallet via the original route, no action required. Refunds are being processed in batches and are expected to be completed by June 12, 2026.
2. $1,000,000 SPCXB airdrop
Dear users:
Thank you for participating in the Binance Wallet SPCXx IPO Campaign. Due to circumstances beyond our control, this event cannot proceed, and we sincerely apologize for this. We have arranged the following solutions:
1. Full refund
All USDC locked by participating users will be fully refunded to your Binance wallet via the original route, no action required. Refunds are being processed in batches and are expected to be completed by June 12, 2026.
2. $1,000,000 SPCXB airdrop
11
·
--
Bullish
105
·
--
Bullish
My damn Ai, the parameters are fine, but after 11 days of profit, you flat-out liquidate my position. You're totally a crypto noob, aren't you?
{future}(BSBUSDT)
My damn Ai, the parameters are fine, but after 11 days of profit, you flat-out liquidate my position. You're totally a crypto noob, aren't you?
邪修King
·
--
$BSB said to hit the short's kill zone, $ATOM who went all in still isn't running.
279
·
--
$BSB said to hit the short's kill zone, $ATOM who went all in still isn't running.
$BSB said to hit the short's kill zone, $ATOM who went all in still isn't running.
1
234
·
--
$ATOM $BSB $ADA
{future}(ATOMUSDT)
It's time to hit that short squeeze line, don't say I didn't warn you!
$ATOM $BSB $ADA
It's time to hit that short squeeze line, don't say I didn't warn you!
It's time to hit that short squeeze line, don't say I didn't warn you!
379
·
--
Bullish
$GRASS Gotta run first, I was planning to set up a position, but AI opened too many trades, so the spot's all yours!
$GRASS Gotta run first, I was planning to set up a position, but AI opened too many trades, so the spot's all yours!
154
·
--
Bullish
Is this about to pump? I've been stacking for several days now $GRASS
Can I break even ➕ the setup?
Is this about to pump? I've been stacking for several days now $GRASS
Can I break even ➕ the setup?
Can I break even ➕ the setup?
201
·
--
Bearish
$BSB Thanks to the paper hands for shorting, we're about to hit 100x haha
$BSB Thanks to the paper hands for shorting, we're about to hit 100x haha
4
691
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
USMidterms-WhatAreMarketsExpecting?
2,841 views
97 Discussing
UBS: Rising Democratic 'Blue Wave' Expectations Deepen Market Risk Aversion
Binance News
·0 Likes
·519 views
USOctoberNFP-AreRateCutsStillPossible
194,628 views
1,459 Discussing
AMDBeatsExpectations-AINarrativeContinues
488 views
48 Discussing