

大嗯BNB
3.9k Posts
大嗯BNB
 Square Verified+
Report
Block User
坚持长期价值投资 与志同道合的区块链爱好者,一起探讨交流 | #BNB坚持持有者 主流价值币定投 | 关注#ALPHA板块 撸毛 | 推x: @daenbnb
永远在学习的路上

BTC Holder
High-Frequency Trader
1.2 Years
1.9K+ Following
44.3K+ Followers
32.2K+ Liked
Posts
All
Quotes
Videos
Live
PINNED
·
--
@hpr2008
Listening to the Waves
@听澜321
Listening to the Waves
Listening to the Waves
听澜321
·
--
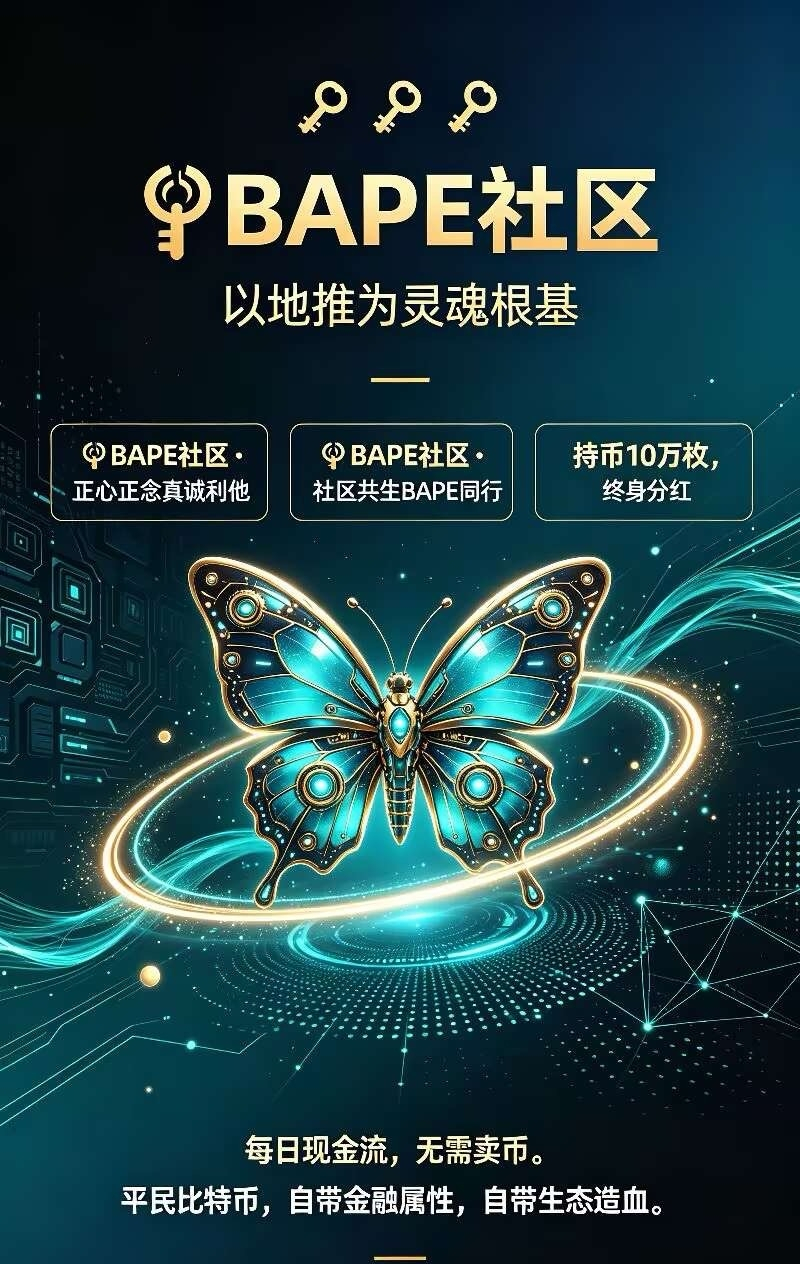
🌺 BAPE is bringing online and offline together to fire the first shot in its all-channel growth strategy!
Staying true to our original vision, we set out to explore new horizons; united in purpose, we open a new chapter—
BAPE invites you to witness the start of a new cycle in its all-channel ecosystem.
【Livestream location】Binance Square | Livestream room @听澜321
【Event time】November 1, 2026, 12:00 (UTC+8)
Reserve your spot in advance and join us on time!
Here’s how we’ve spent BAPE’s 200-plus days…
Over 200 days is no short time.
The market has had its ups and downs. We haven’t chanted a single slogan—we’ve simply made every step count:
building on transparent on-chain mechanisms, bringing the community together through self-governance, and paving the way with nationwide grassroots outreach.
We don’t chase trends or gamble on luck. We believe in one thing: a solid foundation comes before taking flight.
Today, we’re continuing to build awareness online while rolling out our grassroots outreach network across the board.
Breaking into new audiences and deepening our roots go hand in hand, with both channels working together to create an all-channel impact.
This isn’t a sudden burst of momentum. It’s the natural beginning after more than 200 days of quietly building strength~
At this AMA, we’ll get straight to the point:
How to understand the advantages of our mechanisms, how to put our grassroots strategy into action, how to make our traffic strategy work, and how to safeguard long-term value.
No beating around the bush or piling on buzzwords—just clear, in-depth explanations packed with practical insights…
We’ve also prepared exclusive prize draws and a major airdrop for the livestream,
just to show our appreciation for the fans who tune in and support us 🥰
#美国中期选举倒计时,美股博弈窗口已开启?
276
PINNED
·
--
Verified
On October 29, two sets of data came out at the same time, and both pointed in a direction that was "unfriendly to risk assets."
Q3 GDP grew at an annualized rate of 3.4%, versus expectations of 3.1% and a previous reading of 2.2%—a sharp acceleration in economic growth, meaning the Fed has no need to rush into rate cuts. The data even provide a firmer basis for a December rate hike.
Core PCE rose 0.32% month over month and 3.1% year over year (previously 3.0%)—slightly above expectations and still above the Fed's 2% target. The data somewhat called into question Warsh's comment last night that "the medicine of monetary policy is taking effect."
At the same time, Alphabet (Google's parent company) crashed after hours following its earnings report, dragged down by AI spending and negative cash flow. Its shares fell about 10%, wiping out roughly $400 billion in market value in a single day. Nasdaq futures promptly dropped more than 1%.
With these three negative factors hitting at once, where was BTC?
Around 79,800 to 80,300, basically moving sideways around the 80,000 level.
This is more worth noting than "it went up today"—it shows that under the combined pressure of GDP beating expectations (theoretically raising the risk of rate hikes), hotter-than-expected inflation (theoretically the same), and a plunge in the world's largest tech stock (theoretically weighing on risk assets across the board), BTC held the 80,000 support level, which had been tested repeatedly three times.
This wasn't a coincidence. The cost-basis anchor for 842,000 BTC in the 79,821–80,400 range has attracted real buying every time it was tested over the past two weeks. Today was another such instance.
Looking ahead: GDP at 3.4% and core PCE at 0.32% provide a data-based case for a December rate hike. There are still two data releases before the December 9 FOMC meeting—the October CPI on November 12 and October PCE on November 25—and they will be key indicators to watch. If both come in soft, the odds of a pause in December will rise again, giving BTC a chance to challenge the 84,000–87,000 range.
Whether BTC can hold 80,000 through this data-heavy stretch is the clearest structural question over the next 40 days.
Did anyone here add to their position near 80,000 today? Share your reasoning.
$BTC
{future}(BTCUSDT)
On October 29, two sets of data came out at the same time, and both pointed in a direction that was "unfriendly to risk assets."
Q3 GDP grew at an annualized rate of 3.4%, versus expectations of 3.1% and a previous reading of 2.2%—a sharp acceleration in economic growth, meaning the Fed has no need to rush into rate cuts. The data even provide a firmer basis for a December rate hike.
Core PCE rose 0.32% month over month and 3.1% year over year (previously 3.0%)—slightly above expectations and still above the Fed's 2% target. The data somewhat called into question Warsh's comment last night that "the medicine of monetary policy is taking effect."
At the same time, Alphabet (Google's parent company) crashed after hours following its earnings report, dragged down by AI spending and negative cash flow. Its shares fell about 10%, wiping out roughly $400 billion in market value in a single day. Nasdaq futures promptly dropped more than 1%.
With these three negative factors hitting at once, where was BTC?
Around 79,800 to 80,300, basically moving sideways around the 80,000 level.
This is more worth noting than "it went up today"—it shows that under the combined pressure of GDP beating expectations (theoretically raising the risk of rate hikes), hotter-than-expected inflation (theoretically the same), and a plunge in the world's largest tech stock (theoretically weighing on risk assets across the board), BTC held the 80,000 support level, which had been tested repeatedly three times.
This wasn't a coincidence. The cost-basis anchor for 842,000 BTC in the 79,821–80,400 range has attracted real buying every time it was tested over the past two weeks. Today was another such instance.
Looking ahead: GDP at 3.4% and core PCE at 0.32% provide a data-based case for a December rate hike. There are still two data releases before the December 9 FOMC meeting—the October CPI on November 12 and October PCE on November 25—and they will be key indicators to watch. If both come in soft, the odds of a pause in December will rise again, giving BTC a chance to challenge the 84,000–87,000 range.
Whether BTC can hold 80,000 through this data-heavy stretch is the clearest structural question over the next 40 days.
Did anyone here add to their position near 80,000 today? Share your reasoning.
$BTC
BTC-5.05%
GOOGUS-2.14%
132
4
660
·
--
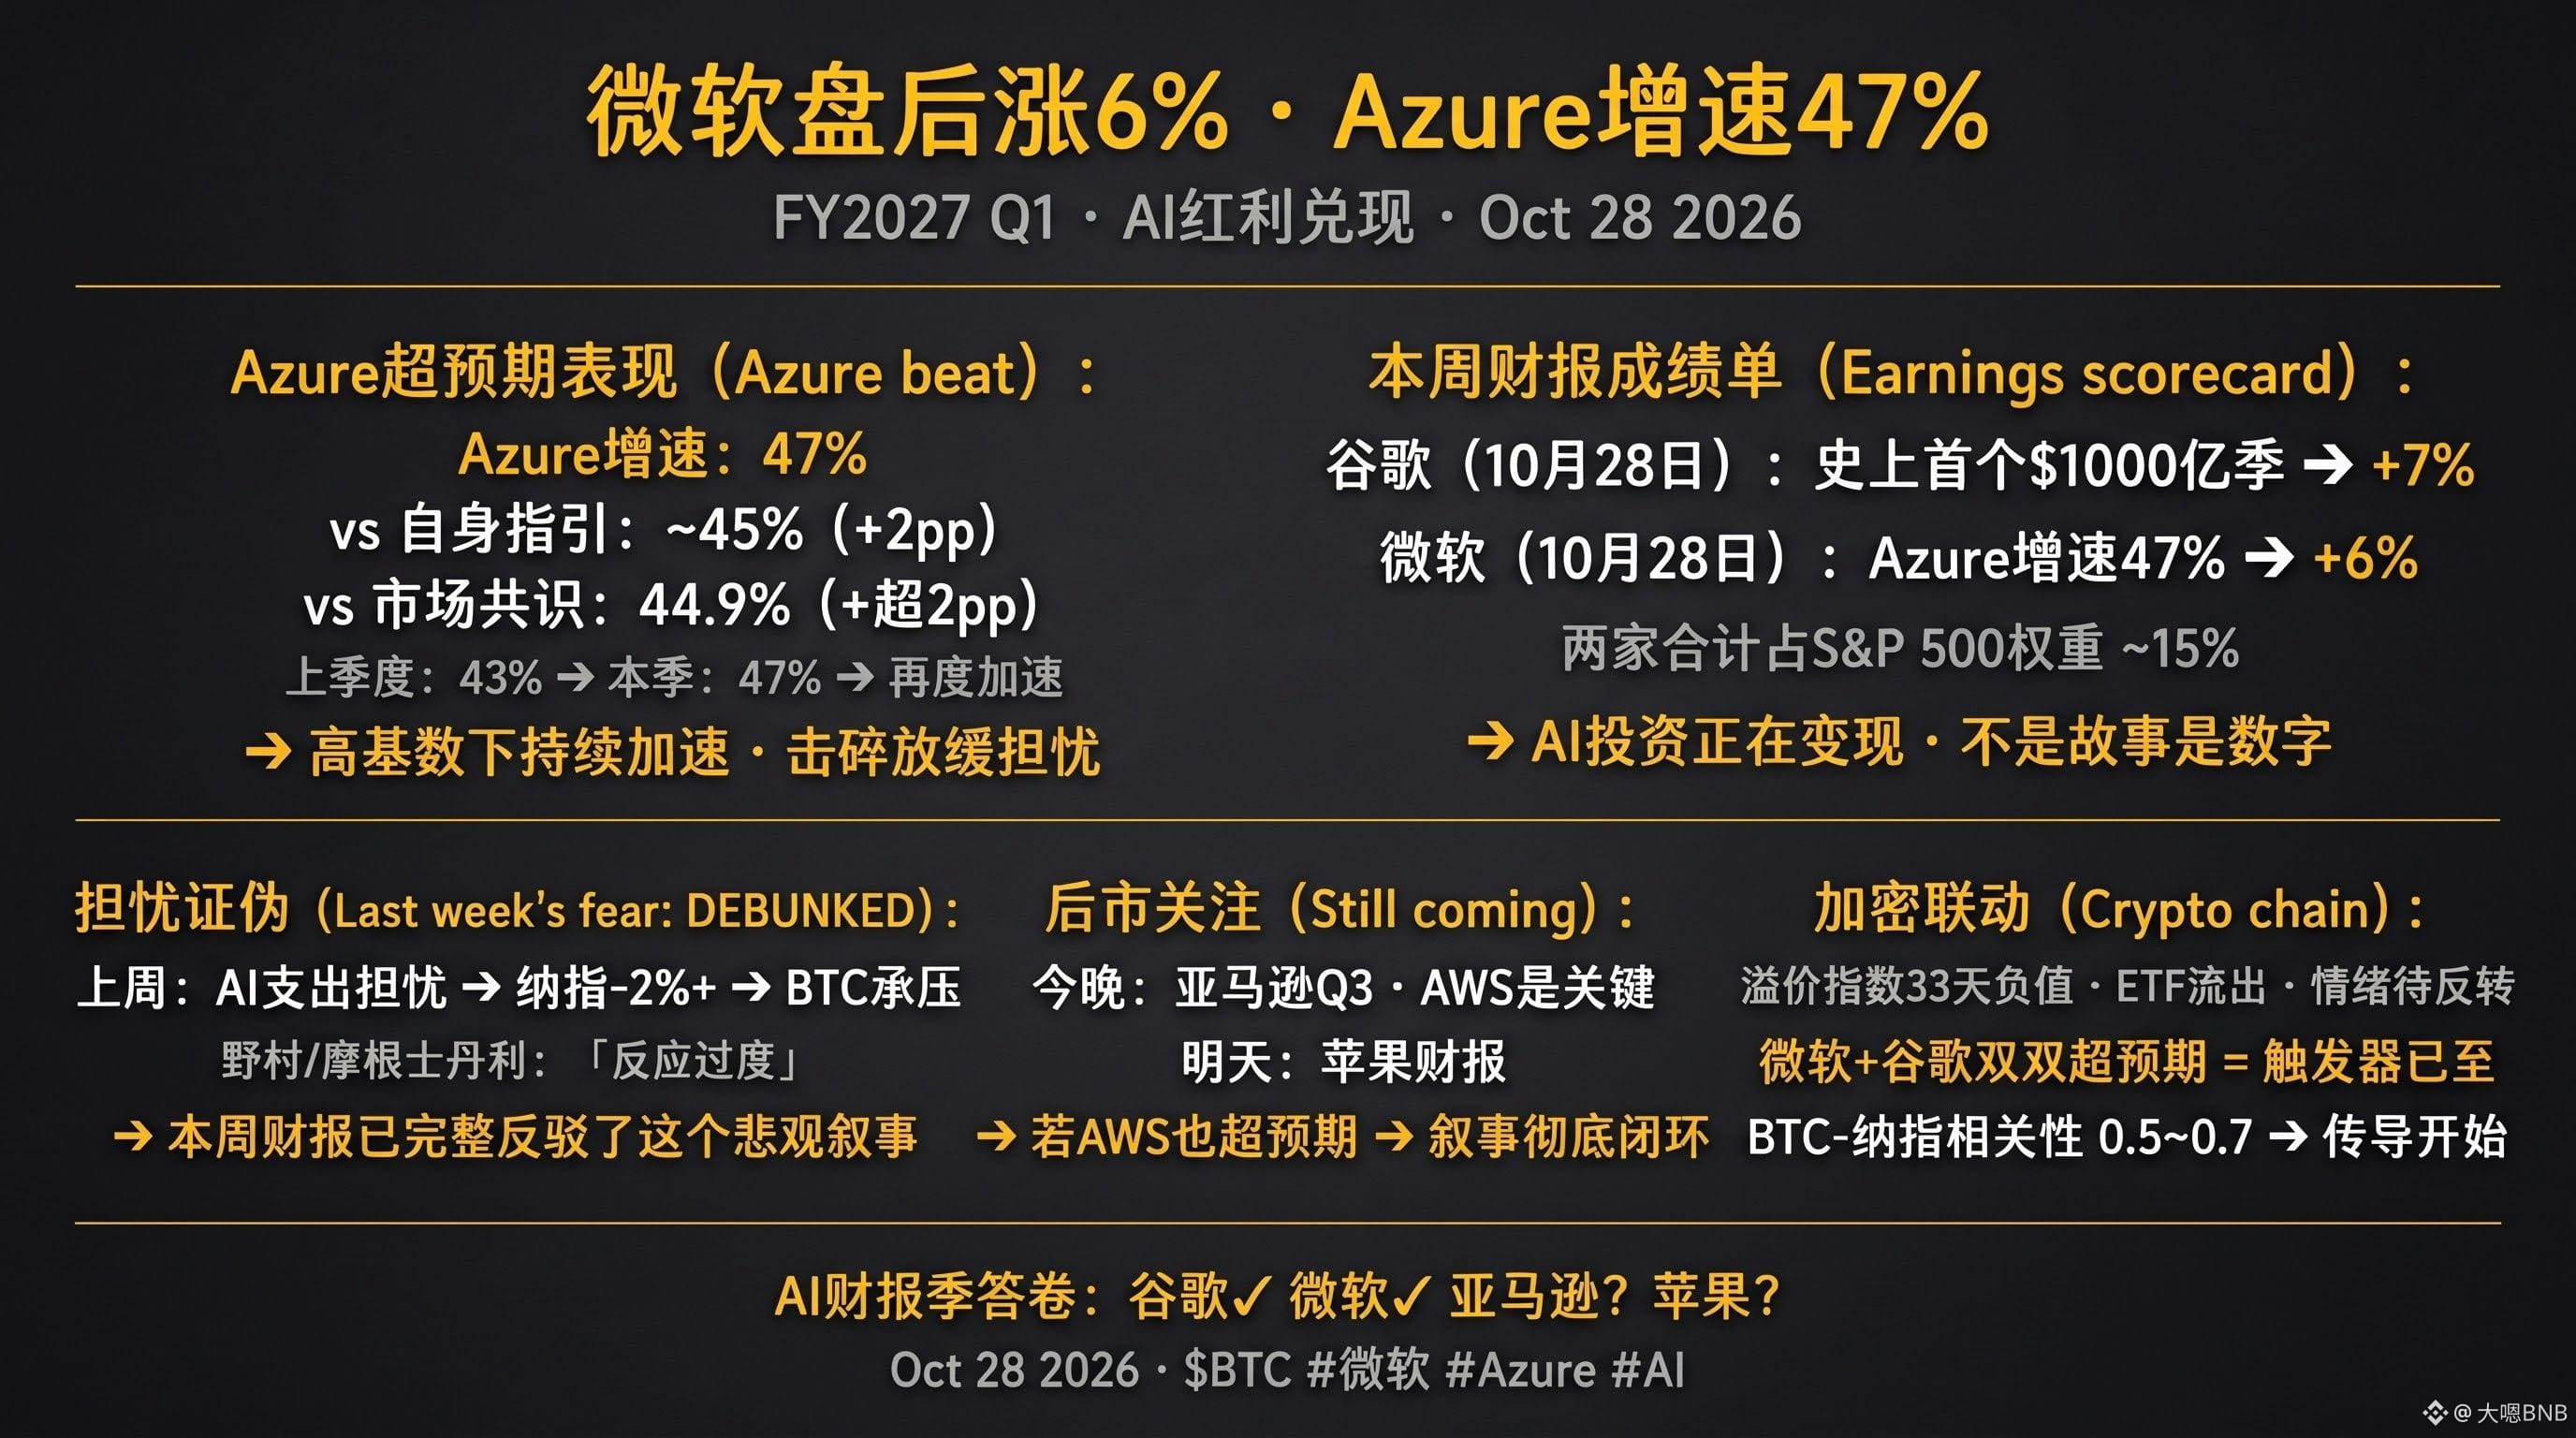
Microsoft (MSFT) reported FY2027 Q1 earnings (July–September), and its stock rose as much as 6% after hours.
The numbers speak for themselves: Azure growth was 47%, 2 percentage points above its own guidance of “around 45%” and more than 2 percentage points above the market consensus of 44.9%. That marks another acceleration after 43% last quarter. The answer to the market’s biggest concern—whether Azure growth could hold up against a high base—was a clear yes.
Here’s the full earnings picture for the week:
Google (yesterday): Its first-ever $100 billion quarter, EPS of $2.87—well above expectations—Cloud up 34%, and shares up 7% after hours.
Microsoft (today): Azure up 47% (2 percentage points above guidance), and shares up 6% after hours.
Together, the two companies account for about 15% of the S&P 500. As two of the AI narrative’s central champions, they sent the same signal in the same week: AI investment is starting to pay off. This isn’t just a story—it’s in the earnings numbers.
That’s a direct rebuttal to last week’s market narrative. After Alphabet’s earnings, concerns about capital spending sent the Nasdaq down more than 2% for the week, and BTC fell back into the $80,000 range. Nomura and Morgan Stanley both said the “market reaction was overdone”—and now the earnings numbers have validated that view.
Amazon reports Q3 earnings tonight (AWS is the key), followed by Apple tomorrow. If AWS also beats expectations, the recovery in the AI narrative will be complete.
The implications for crypto markets are straightforward: Nasdaq sentiment is likely to improve tonight, and its 0.5–0.7 correlation with BTC should carry through. The Coinbase premium index has been negative for 33 consecutive days, and ETFs have seen persistent net outflows—these headwinds have been waiting for exactly this kind of trigger for a systemic sentiment reversal.
Microsoft and Google both beat expectations. The trigger has arrived.
$BTC #Microsoft #Azure #AIearningsseason #纳指
$MSFTB
{spot}(MSFTBUSDT)
$GOOGLB
{spot}(GOOGLBUSDT)
Microsoft (MSFT) reported FY2027 Q1 earnings (July–September), and its stock rose as much as 6% after hours.
The numbers speak for themselves: Azure growth was 47%, 2 percentage points above its own guidance of “around 45%” and more than 2 percentage points above the market consensus of 44.9%. That marks another acceleration after 43% last quarter. The answer to the market’s biggest concern—whether Azure growth could hold up against a high base—was a clear yes.
Here’s the full earnings picture for the week:
Google (yesterday): Its first-ever $100 billion quarter, EPS of $2.87—well above expectations—Cloud up 34%, and shares up 7% after hours.
Microsoft (today): Azure up 47% (2 percentage points above guidance), and shares up 6% after hours.
Together, the two companies account for about 15% of the S&P 500. As two of the AI narrative’s central champions, they sent the same signal in the same week: AI investment is starting to pay off. This isn’t just a story—it’s in the earnings numbers.
That’s a direct rebuttal to last week’s market narrative. After Alphabet’s earnings, concerns about capital spending sent the Nasdaq down more than 2% for the week, and BTC fell back into the $80,000 range. Nomura and Morgan Stanley both said the “market reaction was overdone”—and now the earnings numbers have validated that view.
Amazon reports Q3 earnings tonight (AWS is the key), followed by Apple tomorrow. If AWS also beats expectations, the recovery in the AI narrative will be complete.
The implications for crypto markets are straightforward: Nasdaq sentiment is likely to improve tonight, and its 0.5–0.7 correlation with BTC should carry through. The Coinbase premium index has been negative for 33 consecutive days, and ETFs have seen persistent net outflows—these headwinds have been waiting for exactly this kind of trigger for a systemic sentiment reversal.
Microsoft and Google both beat expectations. The trigger has arrived.
$BTC #Microsoft #Azure #AIearningsseason #纳指
$MSFTB
$GOOGLB
大嗯BNB
·
--
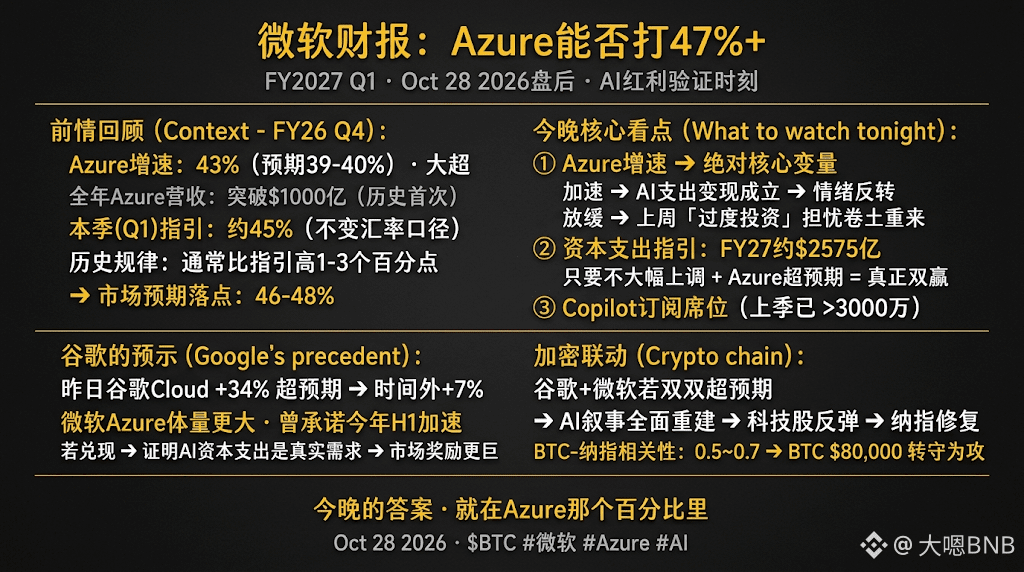
BullishTonight, Microsoft’s earnings report is the most important test of the week.
Google delivered its first-ever $100 billion quarter last night, and its shares rose 7% after hours, rebuilding the AI narrative. Tonight (October 28), Microsoft reports FY2027 Q1 earnings (July–September), and it’s now up to Microsoft to carry the baton.
First, what is the market waiting for?
Azure growth is the only key variable. Last quarter (FY26 Q4), Azure grew 43%, and revenue for the full year surpassed the $100 billion mark, a record high. Microsoft’s own Q1 guidance is “about 45% on a constant-currency basis.” Based on its track record over the past two years of “typically beating its own guidance by 1–3 percentage points,” the market expects a result of roughly **46–48%**.
Why does this Azure figure matter so much?
Because Azure is the clearest financial reflection of whether demand for AI computing is being “monetized for real.” Microsoft 365 Copilot has surpassed 30 million paid seats, and from Anthropic’s TPU deal to OpenAI’s cloud-computing contracts, nearly every top AI company relies on Azure for computing. If Azure growth accelerates further, it means AI capital spending is translating into actual revenue; if it slows, last week’s “capital spending concerns” will resurface.
Another figure to watch: capital spending guidance.
Last quarter, Microsoft guided to about $257.5 billion in FY27 capital spending (equivalent to 77.6% of revenue over the past 12 months). The last time around, this figure was so large that it weighed on the stock’s reaction. Tonight, if that figure isn’t raised substantially and Azure beats expectations, that would be a true win-win combination.
The example set by Google last night:
Google Cloud grew 34% year over year, beating expectations; Search was steady; and net income surged to $34.97 billion—sending shares up 7% after hours. Microsoft’s situation is more distinctive: Azure is larger than Google Cloud, and Microsoft explicitly promised six months ago that it would “accelerate in H1 FY27.” If that acceleration materializes, the market’s reward could be even greater.
For the crypto market: Google and Microsoft both beat earnings expectations → the AI narrative is fully rebuilt → the Nasdaq recovers → BTC follows with a 0.5–0.7 correlation to the Nasdaq → a push toward $80,000.
We’ll have the answer tonight. Whether Azure can top 47% is the figure most worth watching.
$MSFTB $BTC
#微软财报能否兑现ai红利
2
1
619
·
--
#BinancePick
Tonight, I called two Q3 earnings reports correctly—both came in above expectations.
#BinancePick
Tonight, I called two Q3 earnings reports correctly—both came in above expectations.
Tonight, I called two Q3 earnings reports correctly—both came in above expectations.
182
·
--
Verified
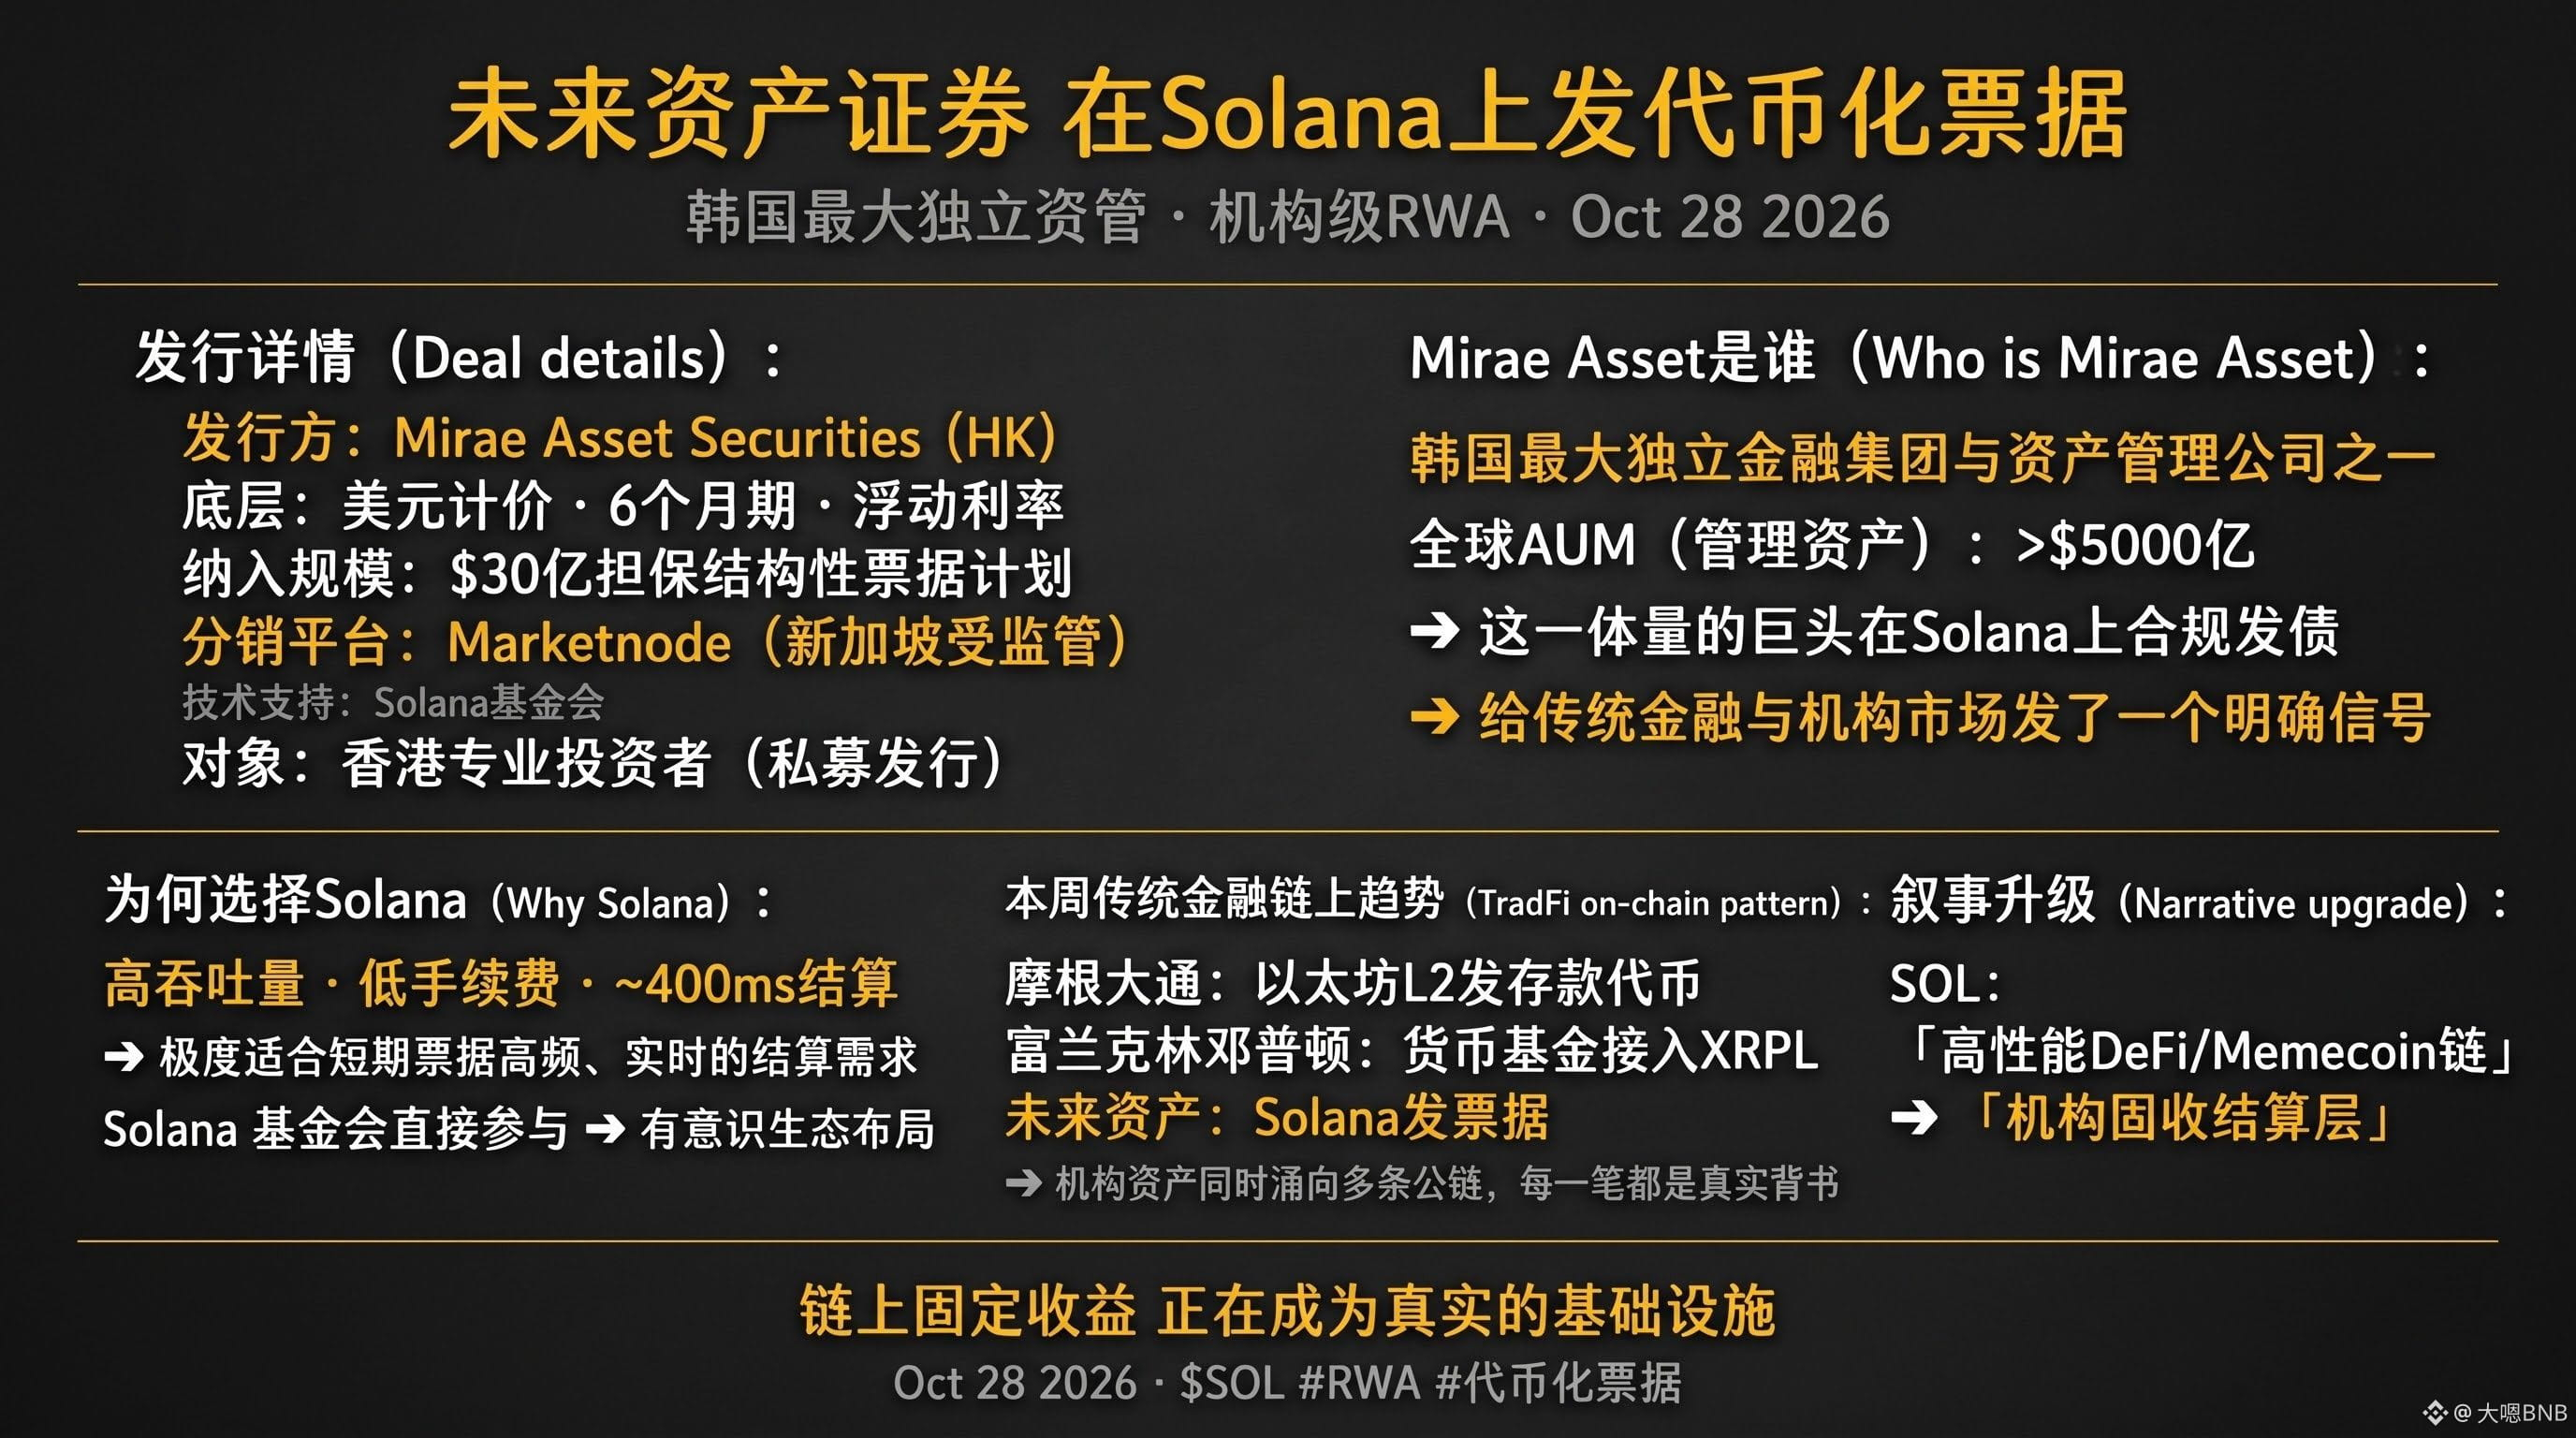
Mirae Asset Securities (HK), the Hong Kong subsidiary of South Korea’s Mirae Asset Securities, announced that it has completed the issuance of a tokenized financing note on the Solana blockchain for eligible institutional investors.
Here are the details: The note is denominated in U.S. dollars, has a six-month term and a floating interest rate, and is issued under the company’s $3 billion Guaranteed Structured Note Programme. Marketnode, a regulated digital market infrastructure operator in Singapore, served as the appointed distributor. The Solana Foundation provided technical support, while Mirae Asset handled token issuance, payments, and lifecycle management. The note was offered exclusively through a private placement to professional investors as defined under Hong Kong’s Securities and Futures Ordinance.
The significance of this announcement lies not in the size of the note, but in the choice of Solana.
On-chain issuance of traditional debt instruments has mostly taken place on Ethereum (JPMorgan’s Kinexys and BlackRock’s BUIDL) or private permissioned blockchains (Quorum and Canton Network). Mirae Asset chose Solana over ETH for clear technical reasons: Solana’s high throughput, low fees, and fast settlement (~400ms) make it better suited to fixed-income instruments such as short-term notes, which require frequent settlement. More importantly, the Solana Foundation’s direct involvement shows this wasn’t an arbitrary choice—it was a deliberate move to build within the ecosystem.
Mirae Asset is one of South Korea’s largest independent asset managers, with global AUM of more than $500 billion. A firm of this scale completing a compliant debt issuance on Solana sends a signal to traditional financial institutions: Solana isn’t just a home for meme coins and DeFi; it can support institutional-grade fixed-income infrastructure.
In the broader context, JPMorgan launched a deposit token this week on Base, an Ethereum L2; Franklin Templeton brought a tokenized MMF to XRPL; and now Mirae Asset has issued a note on Solana. Tokenized assets from traditional finance are flowing onto multiple public blockchains at once, with each transaction adding real institutional validation to its respective chain.
The narrative around SOL is evolving from “a high-performance DeFi chain” to “an institutional fixed-income settlement layer.”
$SOL #solana
{future}(SOLUSDT)
Mirae Asset Securities (HK), the Hong Kong subsidiary of South Korea’s Mirae Asset Securities, announced that it has completed the issuance of a tokenized financing note on the Solana blockchain for eligible institutional investors.
Here are the details: The note is denominated in U.S. dollars, has a six-month term and a floating interest rate, and is issued under the company’s $3 billion Guaranteed Structured Note Programme. Marketnode, a regulated digital market infrastructure operator in Singapore, served as the appointed distributor. The Solana Foundation provided technical support, while Mirae Asset handled token issuance, payments, and lifecycle management. The note was offered exclusively through a private placement to professional investors as defined under Hong Kong’s Securities and Futures Ordinance.
The significance of this announcement lies not in the size of the note, but in the choice of Solana.
On-chain issuance of traditional debt instruments has mostly taken place on Ethereum (JPMorgan’s Kinexys and BlackRock’s BUIDL) or private permissioned blockchains (Quorum and Canton Network). Mirae Asset chose Solana over ETH for clear technical reasons: Solana’s high throughput, low fees, and fast settlement (~400ms) make it better suited to fixed-income instruments such as short-term notes, which require frequent settlement. More importantly, the Solana Foundation’s direct involvement shows this wasn’t an arbitrary choice—it was a deliberate move to build within the ecosystem.
Mirae Asset is one of South Korea’s largest independent asset managers, with global AUM of more than $500 billion. A firm of this scale completing a compliant debt issuance on Solana sends a signal to traditional financial institutions: Solana isn’t just a home for meme coins and DeFi; it can support institutional-grade fixed-income infrastructure.
In the broader context, JPMorgan launched a deposit token this week on Base, an Ethereum L2; Franklin Templeton brought a tokenized MMF to XRPL; and now Mirae Asset has issued a note on Solana. Tokenized assets from traditional finance are flowing onto multiple public blockchains at once, with each transaction adding real institutional validation to its respective chain.
The narrative around SOL is evolving from “a high-performance DeFi chain” to “an institutional fixed-income settlement layer.”
$SOL #solana
653
·
--
Bullish
Tonight, Microsoft’s earnings report is the most important test of the week.
Google delivered its first-ever $100 billion quarter last night, and its shares rose 7% after hours, rebuilding the AI narrative. Tonight (October 28), Microsoft reports FY2027 Q1 earnings (July–September), and it’s now up to Microsoft to carry the baton.
First, what is the market waiting for?
Azure growth is the only key variable. Last quarter (FY26 Q4), Azure grew 43%, and revenue for the full year surpassed the $100 billion mark, a record high. Microsoft’s own Q1 guidance is “about 45% on a constant-currency basis.” Based on its track record over the past two years of “typically beating its own guidance by 1–3 percentage points,” the market expects a result of roughly **46–48%**.
Why does this Azure figure matter so much?
Because Azure is the clearest financial reflection of whether demand for AI computing is being “monetized for real.” Microsoft 365 Copilot has surpassed 30 million paid seats, and from Anthropic’s TPU deal to OpenAI’s cloud-computing contracts, nearly every top AI company relies on Azure for computing. If Azure growth accelerates further, it means AI capital spending is translating into actual revenue; if it slows, last week’s “capital spending concerns” will resurface.
Another figure to watch: capital spending guidance.
Last quarter, Microsoft guided to about $257.5 billion in FY27 capital spending (equivalent to 77.6% of revenue over the past 12 months). The last time around, this figure was so large that it weighed on the stock’s reaction. Tonight, if that figure isn’t raised substantially and Azure beats expectations, that would be a true win-win combination.
The example set by Google last night:
Google Cloud grew 34% year over year, beating expectations; Search was steady; and net income surged to $34.97 billion—sending shares up 7% after hours. Microsoft’s situation is more distinctive: Azure is larger than Google Cloud, and Microsoft explicitly promised six months ago that it would “accelerate in H1 FY27.” If that acceleration materializes, the market’s reward could be even greater.
For the crypto market: Google and Microsoft both beat earnings expectations → the AI narrative is fully rebuilt → the Nasdaq recovers → BTC follows with a 0.5–0.7 correlation to the Nasdaq → a push toward $80,000.
We’ll have the answer tonight. Whether Azure can top 47% is the figure most worth watching.
$MSFTB $BTC
{future}(BTCUSDT)
{spot}(MSFTBUSDT)
#微软财报能否兑现ai红利
Tonight, Microsoft’s earnings report is the most important test of the week.
Google delivered its first-ever $100 billion quarter last night, and its shares rose 7% after hours, rebuilding the AI narrative. Tonight (October 28), Microsoft reports FY2027 Q1 earnings (July–September), and it’s now up to Microsoft to carry the baton.
First, what is the market waiting for?
Azure growth is the only key variable. Last quarter (FY26 Q4), Azure grew 43%, and revenue for the full year surpassed the $100 billion mark, a record high. Microsoft’s own Q1 guidance is “about 45% on a constant-currency basis.” Based on its track record over the past two years of “typically beating its own guidance by 1–3 percentage points,” the market expects a result of roughly **46–48%**.
Why does this Azure figure matter so much?
Because Azure is the clearest financial reflection of whether demand for AI computing is being “monetized for real.” Microsoft 365 Copilot has surpassed 30 million paid seats, and from Anthropic’s TPU deal to OpenAI’s cloud-computing contracts, nearly every top AI company relies on Azure for computing. If Azure growth accelerates further, it means AI capital spending is translating into actual revenue; if it slows, last week’s “capital spending concerns” will resurface.
Another figure to watch: capital spending guidance.
Last quarter, Microsoft guided to about $257.5 billion in FY27 capital spending (equivalent to 77.6% of revenue over the past 12 months). The last time around, this figure was so large that it weighed on the stock’s reaction. Tonight, if that figure isn’t raised substantially and Azure beats expectations, that would be a true win-win combination.
The example set by Google last night:
Google Cloud grew 34% year over year, beating expectations; Search was steady; and net income surged to $34.97 billion—sending shares up 7% after hours. Microsoft’s situation is more distinctive: Azure is larger than Google Cloud, and Microsoft explicitly promised six months ago that it would “accelerate in H1 FY27.” If that acceleration materializes, the market’s reward could be even greater.
For the crypto market: Google and Microsoft both beat earnings expectations → the AI narrative is fully rebuilt → the Nasdaq recovers → BTC follows with a 0.5–0.7 correlation to the Nasdaq → a push toward $80,000.
We’ll have the answer tonight. Whether Azure can top 47% is the figure most worth watching.
$MSFTB $BTC
#微软财报能否兑现ai红利
1
1
318
·
--
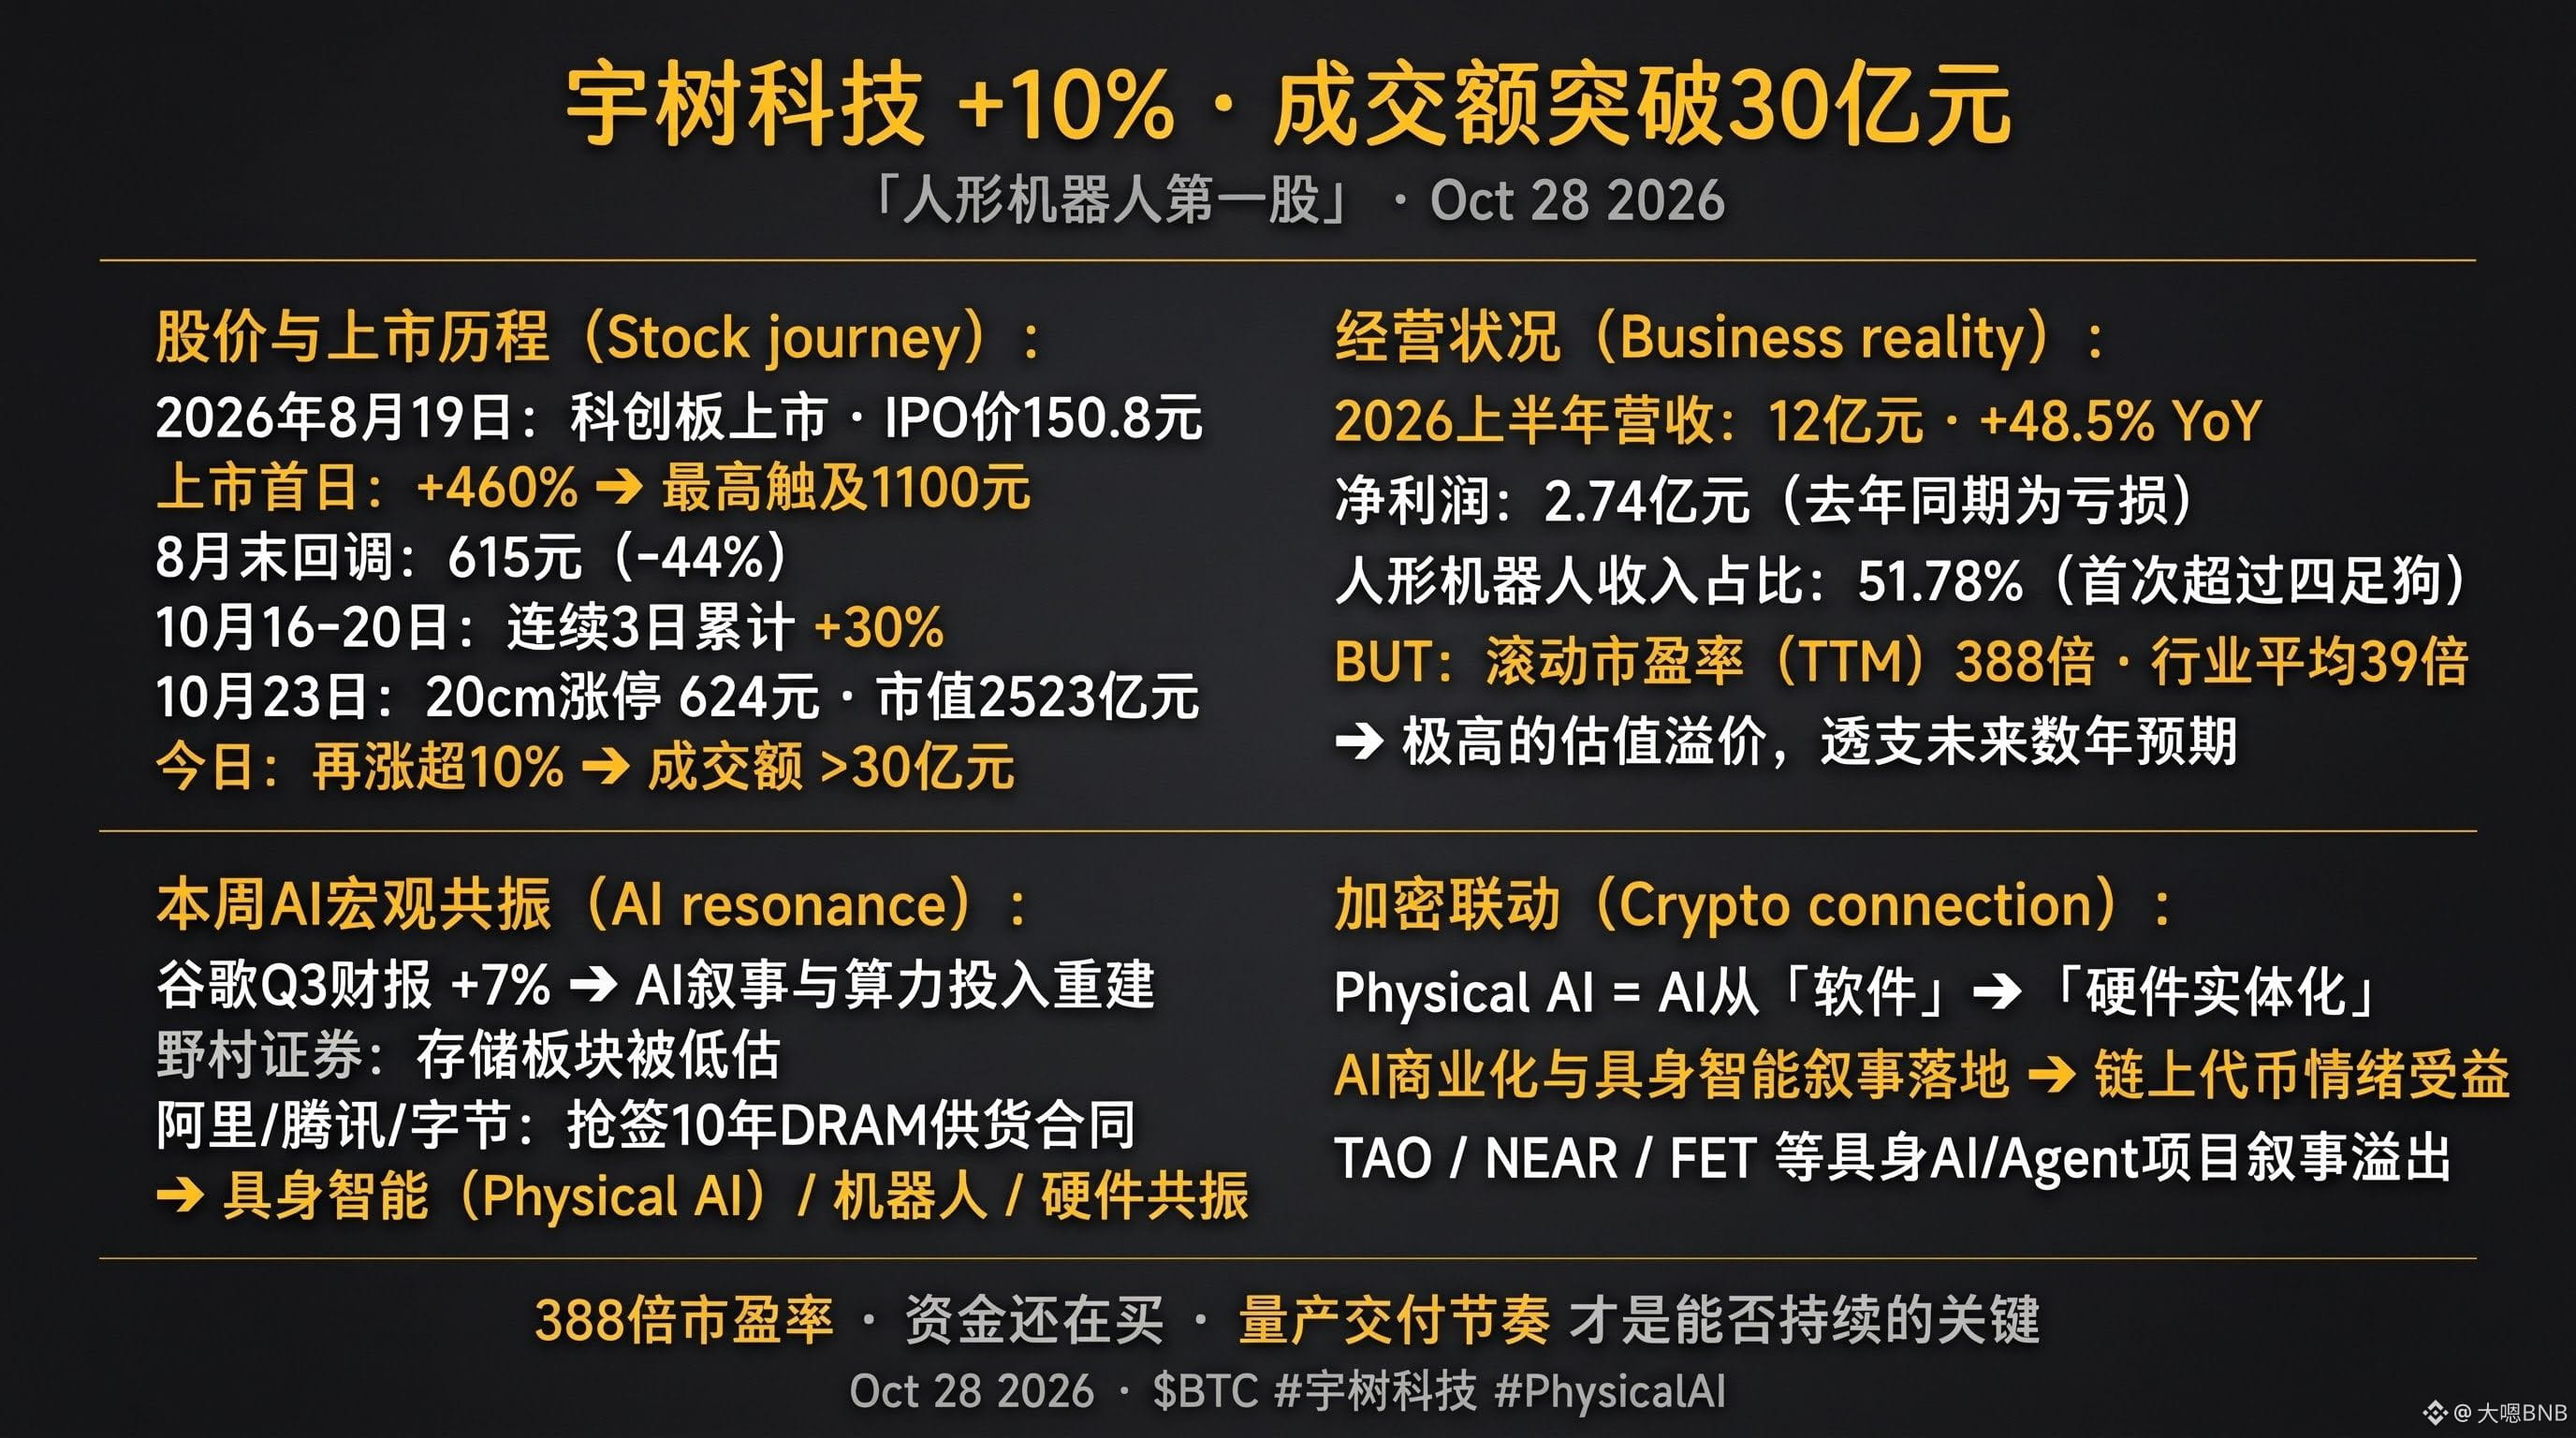
Unitree Robotics (688836) shares surged more than 10%, with turnover topping 3 billion yuan.
What is Unitree? The “first humanoid robot stock” just listed on Shanghai’s STAR Market on August 19. Its IPO was priced at 150.8 yuan, and it soared 460% on its first day of trading, briefly touching 1,100 yuan. The market then cooled off for a while, and by the end of August the stock had pulled back to 615 yuan, a decline of around 44%. But it has picked up again since October: from October 16–20, it gained more than 30% over three consecutive trading days; on October 23, it hit the 20% daily limit-up at 624 yuan, giving it a market cap of 252.3 billion yuan. Today it rose more than 10% again, with turnover exceeding 3 billion yuan.
First, some background figures. Unitree’s revenue for the first half of 2026 was 1.2 billion yuan, up 48.5% year over year. More importantly, it returned to profitability: compared with a loss in the same period last year, it posted net profit of 274 million yuan this year. Humanoid robots now account for 51.78% of its total revenue, overtaking quadruped robots as its largest source of revenue.
But the valuation is also very high—the company itself stated in an October 20 announcement that its trailing P/E ratio was 388, compared with an industry average of 39. Whether that’s expensive is another question; the money is flowing in regardless.
To put today’s gains in the context of the week as a whole: Google’s Q3 earnings report last night far exceeded expectations (+7%), reviving the AI narrative across the board and lifting sentiment around the Nasdaq. Nomura’s report arguing that the memory-chip shortage will last until 2028 and that valuations in the sector are undervalued has just come out. Alibaba, Tencent, and ByteDance are rushing to sign 10-year DRAM contracts. Today, themes related to Unitree in Japan—physical AI, robotics, and computing power—have all converged.
The connection to the crypto market: Unitree’s core thesis is the embodiment of AI as it moves from software into hardware (Physical AI). Its relationship with BTC and the crypto market is not one of direct price correlation, but rather of narrative validation: AI demand is real, is being commercialized, and is gradually being realized—from computing power to robotics. As this narrative continues to be validated by capital, the entire AI-related sector, including AI tokens in crypto such as TAO, NEAR, and FET, will benefit from the spillover in sentiment.
Whether the rally can continue depends on the pace of mass production and delivery. At the World Physical AI Conference on October 22, Unitree’s Wang Xingxing outlined three priorities: large-scale mass production, in-house development of small physical AI models, and ultra-large-scale computing clusters. All three require spending, but they also underpin future valuations.
With a P/E ratio of 388, would you buy in?
$NVDAB $MSFTB
2
371
·
--
Google delivered this week’s most important report card tonight.
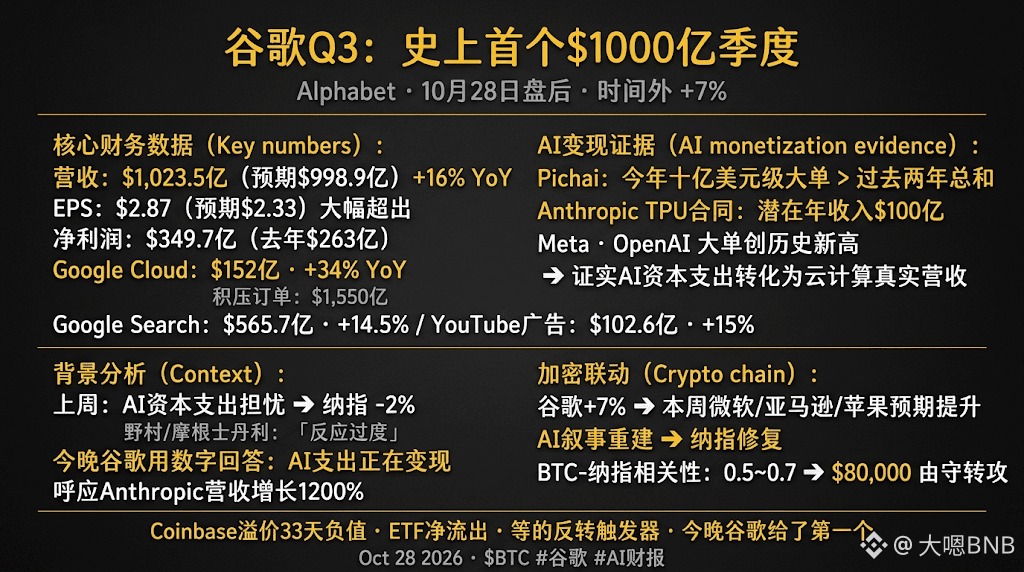
After the market closed on October 28, Alphabet (Google’s parent company) released its Q3 earnings:
Revenue: $102.35 billion—the first quarter ever to top $100 billion—beating expectations of $99.89 billion and up 16% year over year.
EPS: $2.87, well above expectations of $2.33.
Net income: $34.97 billion, compared with $26.3 billion in the same period last year.
Google Cloud: $15.2 billion, up 34% year over year and beating expectations of $14.7 billion, with a cloud backlog of $155 billion.
YouTube ad revenue: $10.26 billion, up 15% year over year.
Shares rose more than 7% after hours.
The significance of these numbers becomes clear in the context of this week.
After Alphabet’s earnings last week, fears over excessive capital spending triggered a sell-off—the Nasdaq fell 2%, AI stocks were broadly repriced lower, and BTC followed, retreating to the $80,000 range. Nomura and Morgan Stanley both said the “market reaction was overdone.”
Tonight, Alphabet answered the market’s concerns with numbers: AI capital spending is starting to pay off. Google Cloud has a $155 billion backlog, including a TPU contract with Anthropic with potential annual revenue of up to $10 billion. Major deals with Meta and OpenAI also hit record highs this quarter. CEO Pichai said, “The number of billion-dollar deals Google Cloud has signed this year exceeds the total for the past two years.”
This directly echoes Anthropic’s disclosure two days ago that its revenue had grown 1,200%—returns are starting to come in from the money invested in AI services.
The transmission chain to crypto markets:
Google +7% → stronger expectations for this week’s Microsoft/Amazon/Apple earnings → AI narrative fully rebuilt → Nasdaq sentiment recovers → BTC follows, with a 0.5–0.7 correlation to the Nasdaq → $80,000 support shifts from defense to offense.
The Coinbase premium index has been negative for 33 consecutive days, and ETFs have seen net outflows—these signals are waiting for a reversal catalyst. Tonight, Google provided the first one.
$BTC $GOOGLB
{spot}(GOOGLBUSDT)
#谷歌财报能否守住基本盘
Google delivered this week’s most important report card tonight.
After the market closed on October 28, Alphabet (Google’s parent company) released its Q3 earnings:
Revenue: $102.35 billion—the first quarter ever to top $100 billion—beating expectations of $99.89 billion and up 16% year over year.
EPS: $2.87, well above expectations of $2.33.
Net income: $34.97 billion, compared with $26.3 billion in the same period last year.
Google Cloud: $15.2 billion, up 34% year over year and beating expectations of $14.7 billion, with a cloud backlog of $155 billion.
YouTube ad revenue: $10.26 billion, up 15% year over year.
Shares rose more than 7% after hours.
The significance of these numbers becomes clear in the context of this week.
After Alphabet’s earnings last week, fears over excessive capital spending triggered a sell-off—the Nasdaq fell 2%, AI stocks were broadly repriced lower, and BTC followed, retreating to the $80,000 range. Nomura and Morgan Stanley both said the “market reaction was overdone.”
Tonight, Alphabet answered the market’s concerns with numbers: AI capital spending is starting to pay off. Google Cloud has a $155 billion backlog, including a TPU contract with Anthropic with potential annual revenue of up to $10 billion. Major deals with Meta and OpenAI also hit record highs this quarter. CEO Pichai said, “The number of billion-dollar deals Google Cloud has signed this year exceeds the total for the past two years.”
This directly echoes Anthropic’s disclosure two days ago that its revenue had grown 1,200%—returns are starting to come in from the money invested in AI services.
The transmission chain to crypto markets:
Google +7% → stronger expectations for this week’s Microsoft/Amazon/Apple earnings → AI narrative fully rebuilt → Nasdaq sentiment recovers → BTC follows, with a 0.5–0.7 correlation to the Nasdaq → $80,000 support shifts from defense to offense.
The Coinbase premium index has been negative for 33 consecutive days, and ETFs have seen net outflows—these signals are waiting for a reversal catalyst. Tonight, Google provided the first one.
$BTC $GOOGLB
#谷歌财报能否守住基本盘
1
18
20.5k
·
--
Bullish
Verified
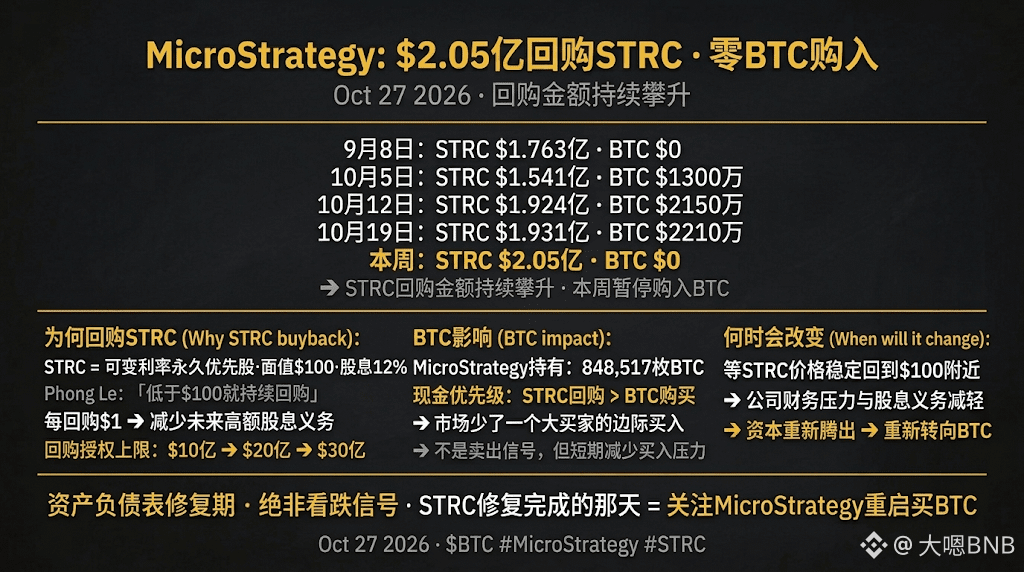
This week, Strategy didn’t buy Bitcoin, but spent $205 million buying back STRC.
This isn’t the first time, but the amounts keep growing—a trend worth discussing on its own.
Let’s look back at the figures from the past few weeks:
September 8: $176.3 million in STRC buybacks, zero BTC purchased
October 5: $154.1 million in STRC buybacks, just $13 million in BTC purchased
October 12: $192.4 million in STRC buybacks, $21.5 million in BTC purchased
October 19: $193.1 million in STRC buybacks, $22.1 million in BTC purchased
This week: $205 million in STRC buybacks, zero BTC purchased
Every week, STRC buybacks have amounted to $150 million to over $200 million, while BTC purchases have been minimal or nonexistent. This is a completely different operating rhythm from the Strategy of 2025, which was “buying BTC in a big way every week.”
Why is Strategy buying back STRC on such a large scale?
STRC is Strategy’s variable-rate preferred stock, with a face value of $100 and an annual dividend rate of 12%. CEO Phong Le has said explicitly that as long as STRC trades below $100, the company will continue buying it back “regularly and in a disciplined manner.” Strategy’s rationale is that buying back its own preferred stock at a discount reduces its future dividend obligations with every dollar spent.
This is purely a balance-sheet management move, not a bearish signal on BTC.
Strategy increased its buyback authorization from $1 billion to $2 billion, and now to **$3 billion**. This means they’ve committed a substantial amount to this strategy: STRC buybacks are the priority, while BTC purchases come second.
The direct implication for BTC prices: Strategy is one of the largest corporate BTC buyers in the market, holding 848,517 BTC (more than 4% of the total supply). When its cash is prioritized for STRC buybacks rather than BTC purchases, the market loses a major buyer. This isn’t a sell signal, but it does reduce marginal buying pressure.
Once STRC stabilizes back near $100, that capital can be freed up and redirected toward BTC.
Whether that happens depends on when STRC completes its recovery.
$BTC
{future}(BTCUSDT)
#strategy未购比特币斥资2.05亿美元回购strc
This week, Strategy didn’t buy Bitcoin, but spent $205 million buying back STRC.
This isn’t the first time, but the amounts keep growing—a trend worth discussing on its own.
Let’s look back at the figures from the past few weeks:
September 8: $176.3 million in STRC buybacks, zero BTC purchased
October 5: $154.1 million in STRC buybacks, just $13 million in BTC purchased
October 12: $192.4 million in STRC buybacks, $21.5 million in BTC purchased
October 19: $193.1 million in STRC buybacks, $22.1 million in BTC purchased
This week: $205 million in STRC buybacks, zero BTC purchased
Every week, STRC buybacks have amounted to $150 million to over $200 million, while BTC purchases have been minimal or nonexistent. This is a completely different operating rhythm from the Strategy of 2025, which was “buying BTC in a big way every week.”
Why is Strategy buying back STRC on such a large scale?
STRC is Strategy’s variable-rate preferred stock, with a face value of $100 and an annual dividend rate of 12%. CEO Phong Le has said explicitly that as long as STRC trades below $100, the company will continue buying it back “regularly and in a disciplined manner.” Strategy’s rationale is that buying back its own preferred stock at a discount reduces its future dividend obligations with every dollar spent.
This is purely a balance-sheet management move, not a bearish signal on BTC.
Strategy increased its buyback authorization from $1 billion to $2 billion, and now to **$3 billion**. This means they’ve committed a substantial amount to this strategy: STRC buybacks are the priority, while BTC purchases come second.
The direct implication for BTC prices: Strategy is one of the largest corporate BTC buyers in the market, holding 848,517 BTC (more than 4% of the total supply). When its cash is prioritized for STRC buybacks rather than BTC purchases, the market loses a major buyer. This isn’t a sell signal, but it does reduce marginal buying pressure.
Once STRC stabilizes back near $100, that capital can be freed up and redirected toward BTC.
Whether that happens depends on when STRC completes its recovery.
$BTC
#strategy未购比特币斥资2.05亿美元回购strc
5
1
13
16k
·
--
Bullish
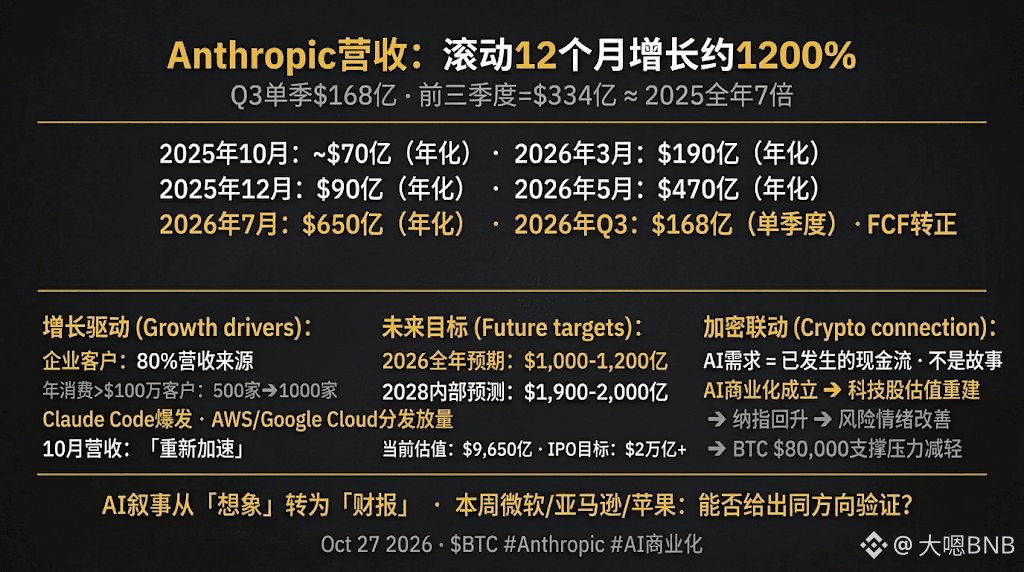
Anthropic (the parent company of Claude) disclosed its Q3 revenue to investors on October 14: $16.8 billion, up 45% from $11.6 billion in Q2 and nearly four times the $4.7 billion in Q1. Total revenue for the first three quarters was about $33.4 billion—already seven times its full-year 2025 revenue.
Depending on which starting point you use, growth on a trailing 12-month basis is roughly 600%–1,200%.
This isn't the kind of “high growth” commonly seen at tech companies. It's on an entirely different scale.
The timeline makes this even clearer:
October 2025: approximately $7 billion in annualized revenue
December 2025: $9 billion
March 2026: $19 billion (annualized)
May 2026: $47 billion (annualized)
July 2026: $65 billion (annualized)
Q3 2026: $16.8 billion (for the quarter)
What's driving this? Enterprise customers. 80% of revenue comes from enterprise and B2B customers, and the number of enterprise customers spending over $1 million annually grew from 500 in February to 1,000 in April. Claude Code's explosive popularity among developers has been a major catalyst, while distribution channels through AWS and Google Cloud continue to scale.
Worth noting: At its October 14 investor meeting, Anthropic said that October revenue was “accelerating again,” and that it had achieved positive FCF (free cash flow) in Q3.
Internal revenue forecast for 2028: $190–200 billion.
For crypto markets, the significance of this news isn't that “Claude is impressive.” It's that AI demand isn't just a story—it's already generating cash flow.
Over the past few weeks, markets have been questioning whether AI capital spending can be monetized. Anthropic's revenue trajectory gives a very clear answer: enterprises are already paying real money for AI services, and they're paying more and more, with that acceleration continuing to build.
The AI narrative is gaining confidence as it shifts from “speculation” to “earnings reports.”
This shift is a long-term positive for BTC: AI commercialization takes hold → tech stock valuations recover → the Nasdaq rebounds → risk sentiment improves → pressure on BTC's $80,000 support eases.
Can this week's earnings reports from Microsoft, Amazon, and Apple confirm the same trend?
$BTC
{future}(BTCUSDT)
#Anthropi
#anthropic滚动12个月营收增长约1200%
Anthropic (the parent company of Claude) disclosed its Q3 revenue to investors on October 14: $16.8 billion, up 45% from $11.6 billion in Q2 and nearly four times the $4.7 billion in Q1. Total revenue for the first three quarters was about $33.4 billion—already seven times its full-year 2025 revenue.
Depending on which starting point you use, growth on a trailing 12-month basis is roughly 600%–1,200%.
This isn't the kind of “high growth” commonly seen at tech companies. It's on an entirely different scale.
The timeline makes this even clearer:
October 2025: approximately $7 billion in annualized revenue
December 2025: $9 billion
March 2026: $19 billion (annualized)
May 2026: $47 billion (annualized)
July 2026: $65 billion (annualized)
Q3 2026: $16.8 billion (for the quarter)
What's driving this? Enterprise customers. 80% of revenue comes from enterprise and B2B customers, and the number of enterprise customers spending over $1 million annually grew from 500 in February to 1,000 in April. Claude Code's explosive popularity among developers has been a major catalyst, while distribution channels through AWS and Google Cloud continue to scale.
Worth noting: At its October 14 investor meeting, Anthropic said that October revenue was “accelerating again,” and that it had achieved positive FCF (free cash flow) in Q3.
Internal revenue forecast for 2028: $190–200 billion.
For crypto markets, the significance of this news isn't that “Claude is impressive.” It's that AI demand isn't just a story—it's already generating cash flow.
Over the past few weeks, markets have been questioning whether AI capital spending can be monetized. Anthropic's revenue trajectory gives a very clear answer: enterprises are already paying real money for AI services, and they're paying more and more, with that acceleration continuing to build.
The AI narrative is gaining confidence as it shifts from “speculation” to “earnings reports.”
This shift is a long-term positive for BTC: AI commercialization takes hold → tech stock valuations recover → the Nasdaq rebounds → risk sentiment improves → pressure on BTC's $80,000 support eases.
Can this week's earnings reports from Microsoft, Amazon, and Apple confirm the same trend?
$BTC
#Anthropi
#anthropic滚动12个月营收增长约1200%
3
10
10.6k
·
--
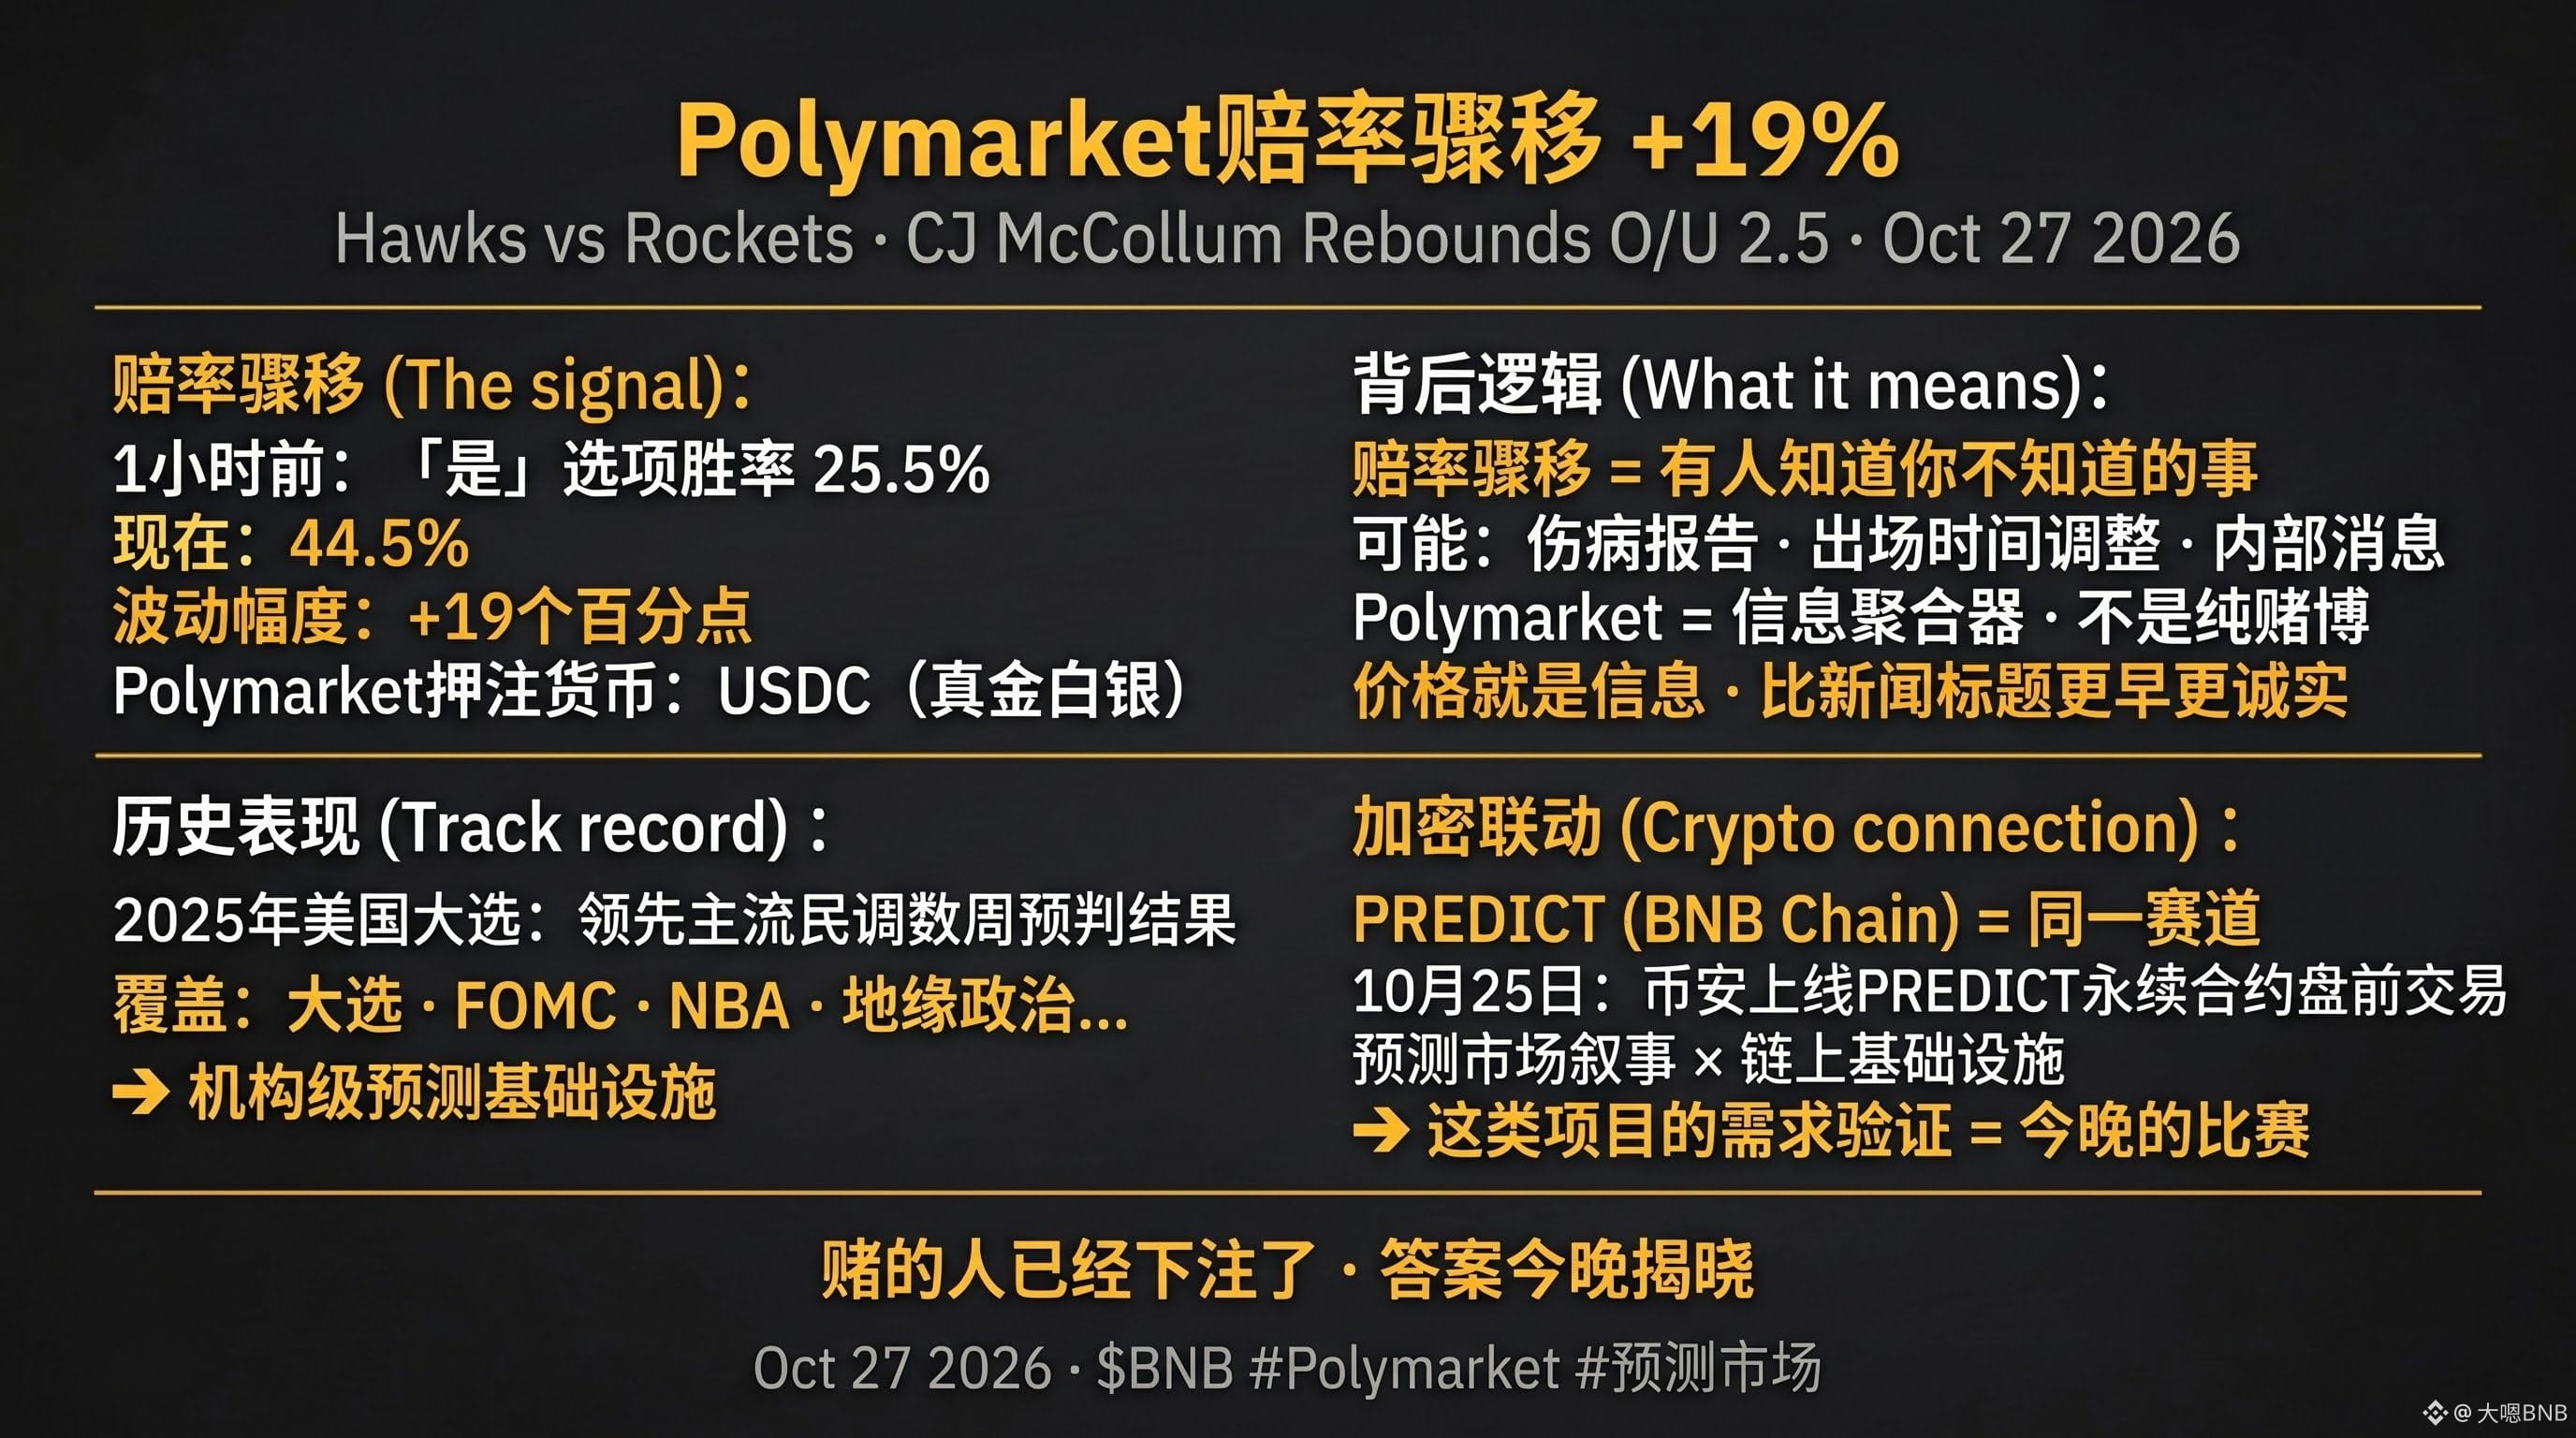
This movement wasn't random.
On October 27, in the “Hawks vs. Rockets” event on Polymarket, the odds of “Yes” in the “CJ McCollum: Rebounds O/U 2.5” submarket surged from 25.5% to 44.5% in just one hour—a jump of 19 percentage points.
Polymarket is an on-chain prediction market where all bets are made with real money in USDC. When odds move sharply in a short period, it usually means someone has information “closer to the truth” and is putting money behind that view—perhaps an injury report, a change in expected playing time, or some other inside information.
The market acts as an information aggregator, not just a gambling platform. A sudden 19-point swing is itself a signal: someone knows something you don't.
The connection between this and crypto markets runs deeper than it might seem.
Over the past year, Polymarket's trading volume has made it institutional-grade prediction infrastructure, covering everything from U.S. elections and FOMC decisions to NBA games. During last year's U.S. election cycle, Polymarket's odds predicted the outcome weeks ahead of major polling organizations.
PREDICT (the project that started pre-market perpetual trading on Binance yesterday) is following the same path—an on-chain prediction market on BNB Chain, targeting sports, macroeconomic data, and geopolitical events.
The core value proposition of these prediction markets is that price is information. Odds move earlier than news headlines—and they're more honest.
Why did the market suddenly reprice its prediction for CJ McCollum's rebounds in the Hawks vs. Rockets game? We may not know until after tonight's game. But people have already placed their bets.
$PREDICT #predict
{future}(PREDICTUSDT)
This movement wasn't random.
On October 27, in the “Hawks vs. Rockets” event on Polymarket, the odds of “Yes” in the “CJ McCollum: Rebounds O/U 2.5” submarket surged from 25.5% to 44.5% in just one hour—a jump of 19 percentage points.
Polymarket is an on-chain prediction market where all bets are made with real money in USDC. When odds move sharply in a short period, it usually means someone has information “closer to the truth” and is putting money behind that view—perhaps an injury report, a change in expected playing time, or some other inside information.
The market acts as an information aggregator, not just a gambling platform. A sudden 19-point swing is itself a signal: someone knows something you don't.
The connection between this and crypto markets runs deeper than it might seem.
Over the past year, Polymarket's trading volume has made it institutional-grade prediction infrastructure, covering everything from U.S. elections and FOMC decisions to NBA games. During last year's U.S. election cycle, Polymarket's odds predicted the outcome weeks ahead of major polling organizations.
PREDICT (the project that started pre-market perpetual trading on Binance yesterday) is following the same path—an on-chain prediction market on BNB Chain, targeting sports, macroeconomic data, and geopolitical events.
The core value proposition of these prediction markets is that price is information. Odds move earlier than news headlines—and they're more honest.
Why did the market suddenly reprice its prediction for CJ McCollum's rebounds in the Hawks vs. Rockets game? We may not know until after tonight's game. But people have already placed their bets.
$PREDICT #predict
1
371
·
--
Partly True
The FOMC statement will be released today at 2 p.m. ET (2 a.m. on October 29, Beijing time).
The outcome is nearly locked in: CME FedWatch currently puts the odds of a pause at 90.6% and a rate hike at 9.4%.
But I think the most interesting thing isn’t today’s outcome—it’s what happened to those odds over the past month.
A month ago, on September 25, the odds of a rate hike in October were 64.2%.
Yesterday, they were 9.4%.
In just one month, expectations for an October rate hike flipped completely from “more likely than not” to “almost impossible.” This shift came after three pieces of data and one speech: September nonfarm payrolls added just 29,000 jobs (versus 90,000 expected), core PCE rose 0.2% month over month, below expectations, and Warsh explicitly refused to offer forward guidance in Bangkok. Together, they pushed the entire rate-hike timeline out to December.
What did BTC do during this period? It pulled back from a high of 87,000 to a low of 79,100, a decline of about 9%.
In other words, while the odds of a rate hike collapsed from 64% to 9%, BTC fell just 9%. Historically, that’s a relatively small move—such a dramatic hawkish-to-dovish shift in expectations would usually bring greater price volatility. Over the past month, BTC has shown resilience, not fragility, in the face of macro shocks.
After Warsh speaks today, the market will be watching one thing: how he talks about December.
If he keeps his language on December open-ended (along the lines of “we’ll depend on the data and rule nothing out”), that’s a neutral outcome the market has already priced in, and BTC is likely to continue trading sideways in the short term. If he sounds clearly dovish on December (for example, saying there has been substantial progress on inflation), that would be an additional positive signal, and BTC could have a chance to retest 82,000–84,000. If he takes a hawkish stance on December (something like “December is under consideration”), that would be a short-term headwind.
Following that thread: $1.22 billion in options expire on October 30, with max pain at 78,000. That means options sellers would prefer the price to stay near 78,000 around October 30—a structural force that could weigh on prices in the short term.
BTC’s current position isn’t one of panic ahead of a rate hike; it’s a final pause before the month-long macro shift is confirmed.
Once the results are out tonight, share what reactions you’re seeing in the plaza right away.
$BTC
{future}(BTCUSDT)
The FOMC statement will be released today at 2 p.m. ET (2 a.m. on October 29, Beijing time).
The outcome is nearly locked in: CME FedWatch currently puts the odds of a pause at 90.6% and a rate hike at 9.4%.
But I think the most interesting thing isn’t today’s outcome—it’s what happened to those odds over the past month.
A month ago, on September 25, the odds of a rate hike in October were 64.2%.
Yesterday, they were 9.4%.
In just one month, expectations for an October rate hike flipped completely from “more likely than not” to “almost impossible.” This shift came after three pieces of data and one speech: September nonfarm payrolls added just 29,000 jobs (versus 90,000 expected), core PCE rose 0.2% month over month, below expectations, and Warsh explicitly refused to offer forward guidance in Bangkok. Together, they pushed the entire rate-hike timeline out to December.
What did BTC do during this period? It pulled back from a high of 87,000 to a low of 79,100, a decline of about 9%.
In other words, while the odds of a rate hike collapsed from 64% to 9%, BTC fell just 9%. Historically, that’s a relatively small move—such a dramatic hawkish-to-dovish shift in expectations would usually bring greater price volatility. Over the past month, BTC has shown resilience, not fragility, in the face of macro shocks.
After Warsh speaks today, the market will be watching one thing: how he talks about December.
If he keeps his language on December open-ended (along the lines of “we’ll depend on the data and rule nothing out”), that’s a neutral outcome the market has already priced in, and BTC is likely to continue trading sideways in the short term. If he sounds clearly dovish on December (for example, saying there has been substantial progress on inflation), that would be an additional positive signal, and BTC could have a chance to retest 82,000–84,000. If he takes a hawkish stance on December (something like “December is under consideration”), that would be a short-term headwind.
Following that thread: $1.22 billion in options expire on October 30, with max pain at 78,000. That means options sellers would prefer the price to stay near 78,000 around October 30—a structural force that could weigh on prices in the short term.
BTC’s current position isn’t one of panic ahead of a rate hike; it’s a final pause before the month-long macro shift is confirmed.
Once the results are out tonight, share what reactions you’re seeing in the plaza right away.
$BTC
278
2
21
714
·
--
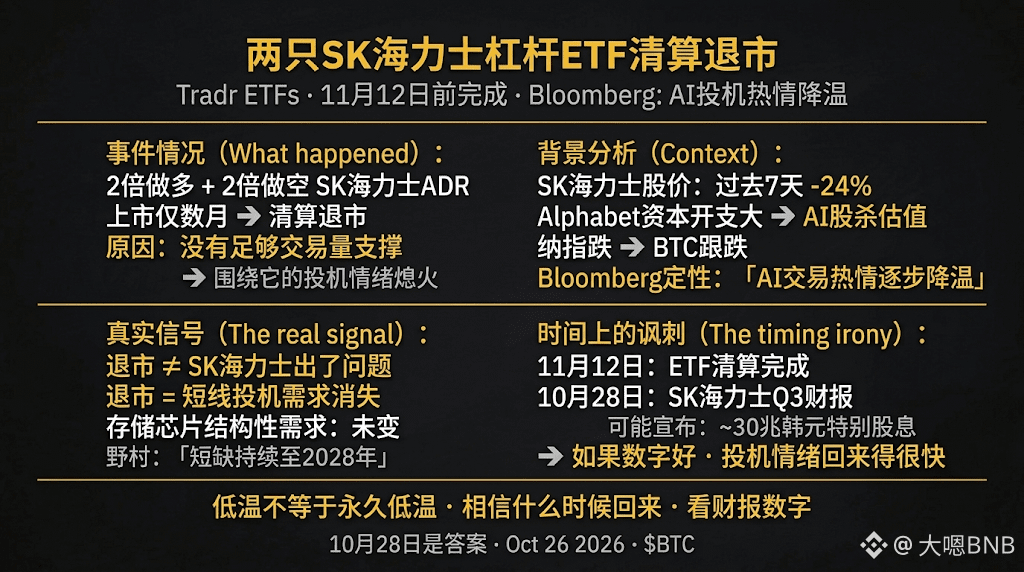
Two SK Hynix leveraged ETFs are being delisted, and there’s more to this than meets the eye.
Two leveraged products linked to SK Hynix’s American depositary receipts, issued by Tradr ETFs—the 2x long and 2x short funds—will be liquidated and delisted around November 12, just months after listing. Bloomberg characterized the move this way: “Investor enthusiasm for the AI trade is gradually cooling.”
First, what are these products? Single-stock leveraged ETFs are tools for high-frequency traders and short-term speculators, designed to magnify a single stock’s daily moves by two times. Issuing this kind of product signals that the issuer believes there’s enough short-term trading demand for the underlying stock. Delisting it signals that the demand has disappeared.
The funds aren’t being delisted because something is wrong with SK Hynix. Speculative sentiment around the stock has simply faded.
Put this in the context of this week’s macro backdrop, and the signal becomes clearer.
Over the past few weeks, the AI narrative has gone like this: Alphabet reports big capital spending → AI stocks get repriced lower → the Nasdaq falls → BTC follows. Meanwhile, SK Hynix’s own share price fell 24% in seven days. In this environment, the two leveraged ETFs didn’t have enough trading volume to sustain them, so delisting is a natural outcome.
But the timing is interesting: liquidation is set to be completed on November 12, while SK Hynix reports its Q3 earnings on October 28, when it may announce a special dividend of around 30 trillion won. If the earnings figures are good and the special dividend comes through, trading volumes in the KOSPI and ADRs will show how quickly speculative sentiment returns.
The delisting of these two leveraged ETFs is like a low-temperature reading for the AI trade. But a low reading doesn’t mean it will stay cold forever—the structural demand for memory chips hasn’t disappeared; the market just doesn’t believe in it right now.
What will bring that belief back? Not the headlines, but the earnings figures.
October 28 is the answer.
$BTC $SKHYB
{spot}(SKHYBUSDT)
{future}(BTCUSDT)
#SKHynix
Two SK Hynix leveraged ETFs are being delisted, and there’s more to this than meets the eye.
Two leveraged products linked to SK Hynix’s American depositary receipts, issued by Tradr ETFs—the 2x long and 2x short funds—will be liquidated and delisted around November 12, just months after listing. Bloomberg characterized the move this way: “Investor enthusiasm for the AI trade is gradually cooling.”
First, what are these products? Single-stock leveraged ETFs are tools for high-frequency traders and short-term speculators, designed to magnify a single stock’s daily moves by two times. Issuing this kind of product signals that the issuer believes there’s enough short-term trading demand for the underlying stock. Delisting it signals that the demand has disappeared.
The funds aren’t being delisted because something is wrong with SK Hynix. Speculative sentiment around the stock has simply faded.
Put this in the context of this week’s macro backdrop, and the signal becomes clearer.
Over the past few weeks, the AI narrative has gone like this: Alphabet reports big capital spending → AI stocks get repriced lower → the Nasdaq falls → BTC follows. Meanwhile, SK Hynix’s own share price fell 24% in seven days. In this environment, the two leveraged ETFs didn’t have enough trading volume to sustain them, so delisting is a natural outcome.
But the timing is interesting: liquidation is set to be completed on November 12, while SK Hynix reports its Q3 earnings on October 28, when it may announce a special dividend of around 30 trillion won. If the earnings figures are good and the special dividend comes through, trading volumes in the KOSPI and ADRs will show how quickly speculative sentiment returns.
The delisting of these two leveraged ETFs is like a low-temperature reading for the AI trade. But a low reading doesn’t mean it will stay cold forever—the structural demand for memory chips hasn’t disappeared; the market just doesn’t believe in it right now.
What will bring that belief back? Not the headlines, but the earnings figures.
October 28 is the answer.
$BTC $SKHYB
#SKHynix
2
511
·
--
SK Hynix earnings day: a date the market is seriously underestimating.
SK Hynix shares have plunged 24% over the past seven days. The drop is due to spreading concerns about AI capital spending, compounded by a valuation reset across the memory chip sector. But amid this sell-off, an important signal has been overlooked: on October 28, the day it reports earnings, the company may announce a special dividend of around ₩30 trillion (about $22 billion).
This isn’t just market speculation. Eugene Securities explicitly mentioned it in a report on August 24: SK Hynix announced a ₩40 trillion share buyback in August, with all repurchased shares to be canceled. It also raised its shareholder return commitment for 2025–2027 to more than 50% of FCF, and clearly signaled that a special cash dividend plan would be finalized at the October board meeting.
Now consider the broader data. Bank of America and Goldman Sachs have both weighed in: based on earnings forecasts for 2027–2028, SK Hynix is currently trading at just 2–3 times earnings. The normal valuation range during an upcycle for memory chips is 4–7 times earnings. Even without factoring in AI demand, a valuation based purely on the cycle puts the stock in historically undervalued territory.
Nomura Securities just said, “The memory chip shortage will last through 2028,” while AWS CEO Jassy said, “Capacity for 2027 is almost completely sold out.” Market concerns about AI investment have dragged chip stocks down, but the demand-side numbers haven’t changed.
The spillover chain to crypto:
Memory chips are a core component of AI computing infrastructure. SK Hynix is the world’s largest supplier of HBM (high-bandwidth memory), and all of Nvidia’s H-series and B-series GPUs rely on its products. A recovery in the memory sector → a renewed AI computing demand narrative → a rebound in Nasdaq AI heavyweights → BTC follows, given its 0.5–0.7 correlation with the Nasdaq.
More directly: a $22 billion special dividend flows into the market, and some of that capital will look for its next source of returns. Crypto assets have historically been one destination for this kind of money.
Of course, the special dividend has not yet been officially confirmed. The earnings figures themselves and the company’s guidance remain the top priorities on October 28.
October 28: SK Hynix earnings and the FOMC decision fall on the same day. The amount of information packed into that day will exceed what we’ve had over the past month combined.
Whether the trend can reverse comes down to these 48 hours.
$BTC #SKHynix
1
393
·
--
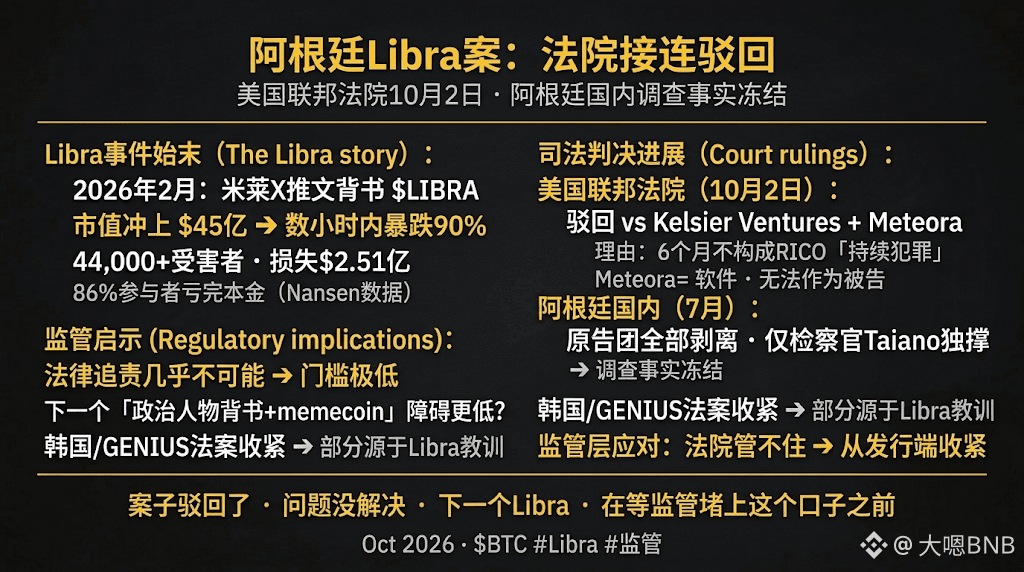
The dust around the Libra case is settling in a very subtle way.
On October 2, the U.S. District Court for the Southern District of New York formally dismissed the class-action lawsuit against Libra project operators Kelsier Ventures and DeFi platform Meteora. Judge Jennifer Rochon ruled that roughly six months of related activity was insufficient to constitute the “pattern of racketeering activity” required under RICO (the Racketeer Influenced and Corrupt Organizations Act); Meteora was software, not a partnership, and therefore could not be sued as a defendant.
Meanwhile, in Argentina, Judge Martínez de Giorgi had already removed all victim plaintiffs from the case in July. The investigation is now being pursued by just one person: prosecutor Taiano—who is known inside the courthouse as “tardano” (someone who is always late). Victims can no longer access the case files or request investigative measures.
The significance of this case for the entire crypto market goes far beyond the political fate of Milei himself.
Libra’s operation is a textbook example of this year’s most typical memecoin scheme: endorsement by a head of state → market cap surges to $4.5 billion → 90% crash → insiders cash out → $251 million in investor losses → 44,000+ victims. Nansen data shows that 86% of participants lost their entire investment.
What signal is being sent as the courts dismiss the cases one after another?
First, holding anyone accountable for memecoin manipulation under the current legal framework is extremely difficult. RICO requires proof of “ongoing organized criminal activity,” and a project lifecycle of six months is legally too short; smart contracts on Solana have been classified as “software,” making them impossible to hold accountable. This is a textbook example of regulatory gaps across the industry.
Second, this is actually a dangerous signal for the future “politician endorsement + memecoin” model: the legal costs are negligible, accountability is almost impossible, and the barriers to the next Libra-style project may actually be lower.
Third, some of the rationale behind tighter regulation of stablecoins such as USDT and USDC (South Korea’s Foreign Exchange Transactions Act and the GENIUS Act) comes from lessons learned from incidents like Libra—the regulators have seen that the courts can’t rein it in, so they can only tighten controls at the issuance and circulation stages.
The case has been dismissed, but the problem hasn’t been solved. Whether this can work depends not on the courts, but on whether the regulatory framework can close this loophole in the next cycle.
Do you think a head of state pumping a token without ultimately being held accountable is good or bad for the crypto market?
$BTC
{future}(BTCUSDT)
#阿根廷法院驳回米莱libra案
The dust around the Libra case is settling in a very subtle way.
On October 2, the U.S. District Court for the Southern District of New York formally dismissed the class-action lawsuit against Libra project operators Kelsier Ventures and DeFi platform Meteora. Judge Jennifer Rochon ruled that roughly six months of related activity was insufficient to constitute the “pattern of racketeering activity” required under RICO (the Racketeer Influenced and Corrupt Organizations Act); Meteora was software, not a partnership, and therefore could not be sued as a defendant.
Meanwhile, in Argentina, Judge Martínez de Giorgi had already removed all victim plaintiffs from the case in July. The investigation is now being pursued by just one person: prosecutor Taiano—who is known inside the courthouse as “tardano” (someone who is always late). Victims can no longer access the case files or request investigative measures.
The significance of this case for the entire crypto market goes far beyond the political fate of Milei himself.
Libra’s operation is a textbook example of this year’s most typical memecoin scheme: endorsement by a head of state → market cap surges to $4.5 billion → 90% crash → insiders cash out → $251 million in investor losses → 44,000+ victims. Nansen data shows that 86% of participants lost their entire investment.
What signal is being sent as the courts dismiss the cases one after another?
First, holding anyone accountable for memecoin manipulation under the current legal framework is extremely difficult. RICO requires proof of “ongoing organized criminal activity,” and a project lifecycle of six months is legally too short; smart contracts on Solana have been classified as “software,” making them impossible to hold accountable. This is a textbook example of regulatory gaps across the industry.
Second, this is actually a dangerous signal for the future “politician endorsement + memecoin” model: the legal costs are negligible, accountability is almost impossible, and the barriers to the next Libra-style project may actually be lower.
Third, some of the rationale behind tighter regulation of stablecoins such as USDT and USDC (South Korea’s Foreign Exchange Transactions Act and the GENIUS Act) comes from lessons learned from incidents like Libra—the regulators have seen that the courts can’t rein it in, so they can only tighten controls at the issuance and circulation stages.
The case has been dismissed, but the problem hasn’t been solved. Whether this can work depends not on the courts, but on whether the regulatory framework can close this loophole in the next cycle.
Do you think a head of state pumping a token without ultimately being held accountable is good or bad for the crypto market?
$BTC
#阿根廷法院驳回米莱libra案
2
5
4.7k
·
--
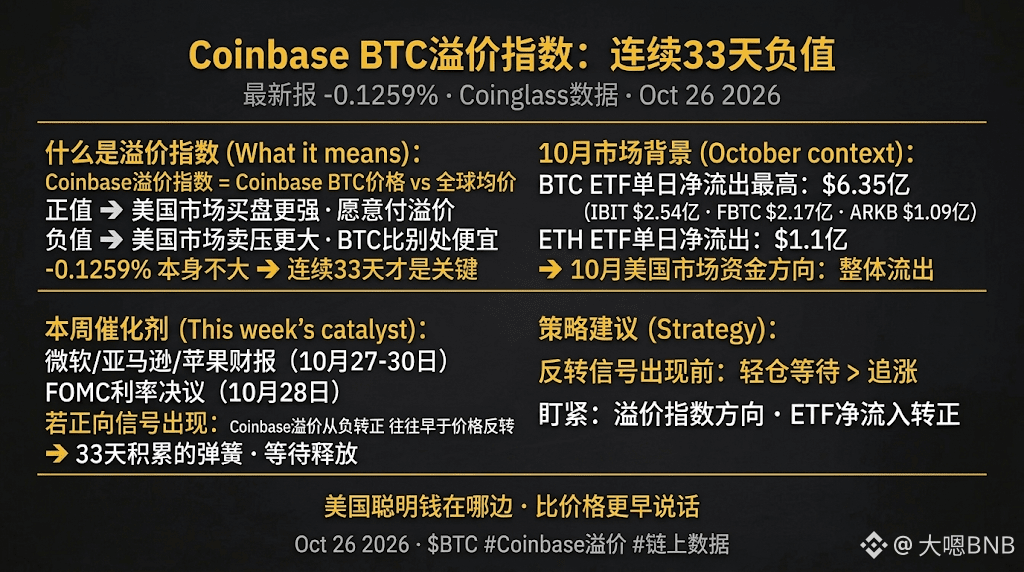
33 consecutive days—that’s a number worth taking a closer look at.
According to Coinglass data, the Coinbase Bitcoin Premium Index has recorded negative values for 33 consecutive days, with the latest reading at **-0.1259%** on October 26.
First, what does this indicator measure? The Coinbase Premium Index measures the difference between the BTC price on Coinbase and the global market average. A positive value indicates stronger buying demand in the U.S. market, with buyers willing to pay a premium; a negative value indicates relatively greater selling pressure in the U.S. market, with BTC trading slightly cheaper on Coinbase than on other exchanges.
-0.1259% is not a large figure in itself, but the 33 consecutive days are what matter.
This isn’t a one-day swing in sentiment; it’s a structural signal that has persisted for more than a month. The implication is specific: buying interest among U.S. retail and institutional investors on Coinbase has remained weaker than the global market average for over a month. Combined with the highest single-day net outflow from BTC ETFs this month reaching $635 million (outflows from IBIT/FBTC/ARKB on the same day), as well as $110 million in net outflows from ETH ETFs, fund flows in the U.S. market have been net negative overall in October.
Why look at this alongside this week’s macro backdrop?
This week brings earnings reports from Microsoft, Amazon, and Apple, along with the FOMC decision. If these events deliver positive signals and risk sentiment in the U.S. market recovers, the Coinbase Premium Index could turn positive quickly. Historically, reversals in this indicator have often appeared before price movements, because it reflects which side “smart money in the U.S.” is on.
Thirty-three days of negative premiums are a spring that’s been wound up for a long time, not a permanent downtrend.
Until a reversal signal appears, waiting on the sidelines with a small position is more sensible than chasing a rally.
$BTC $ETH $BNB
{future}(BNBUSDT)
{future}(ETHUSDT)
{future}(BTCUSDT)
33 consecutive days—that’s a number worth taking a closer look at.
According to Coinglass data, the Coinbase Bitcoin Premium Index has recorded negative values for 33 consecutive days, with the latest reading at **-0.1259%** on October 26.
First, what does this indicator measure? The Coinbase Premium Index measures the difference between the BTC price on Coinbase and the global market average. A positive value indicates stronger buying demand in the U.S. market, with buyers willing to pay a premium; a negative value indicates relatively greater selling pressure in the U.S. market, with BTC trading slightly cheaper on Coinbase than on other exchanges.
-0.1259% is not a large figure in itself, but the 33 consecutive days are what matter.
This isn’t a one-day swing in sentiment; it’s a structural signal that has persisted for more than a month. The implication is specific: buying interest among U.S. retail and institutional investors on Coinbase has remained weaker than the global market average for over a month. Combined with the highest single-day net outflow from BTC ETFs this month reaching $635 million (outflows from IBIT/FBTC/ARKB on the same day), as well as $110 million in net outflows from ETH ETFs, fund flows in the U.S. market have been net negative overall in October.
Why look at this alongside this week’s macro backdrop?
This week brings earnings reports from Microsoft, Amazon, and Apple, along with the FOMC decision. If these events deliver positive signals and risk sentiment in the U.S. market recovers, the Coinbase Premium Index could turn positive quickly. Historically, reversals in this indicator have often appeared before price movements, because it reflects which side “smart money in the U.S.” is on.
Thirty-three days of negative premiums are a spring that’s been wound up for a long time, not a permanent downtrend.
Until a reversal signal appears, waiting on the sidelines with a small position is more sensible than chasing a rally.
$BTC $ETH $BNB
2
341
·
--
Bullish
Verified
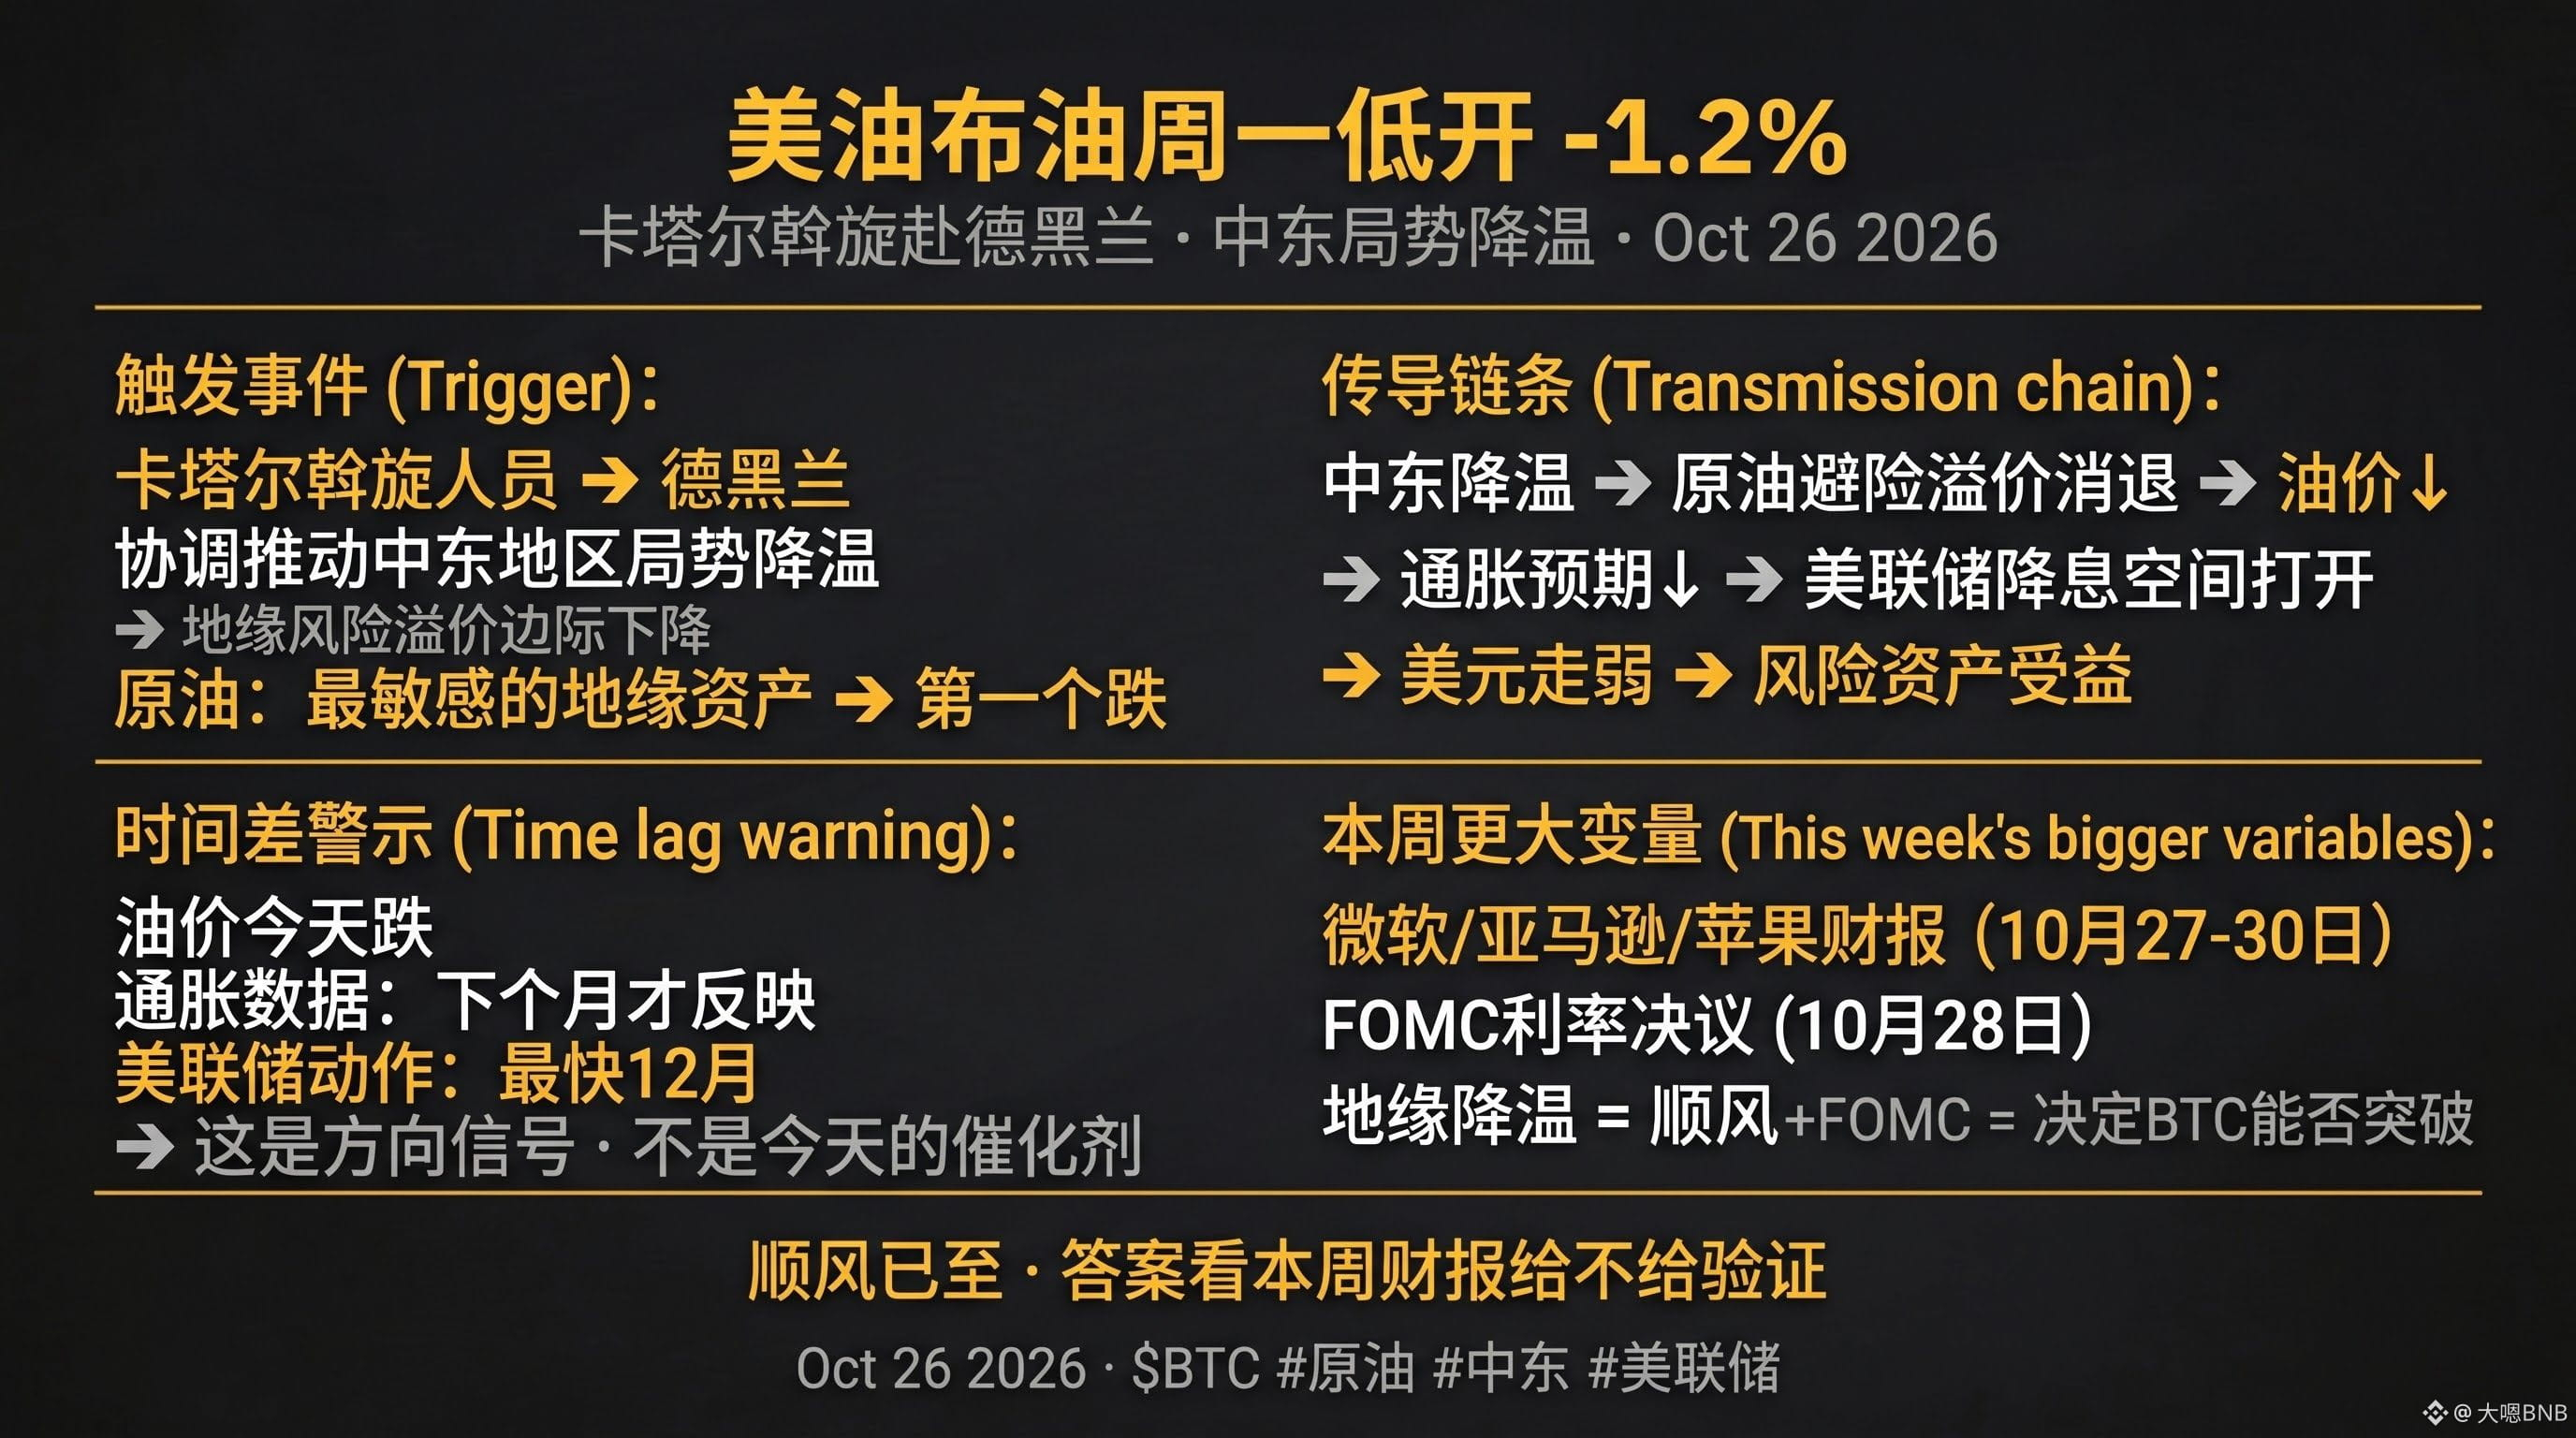
Oil prices kick off Monday with a drop.
On October 26, WTI and Brent opened 1.2% lower on Monday. The catalyst was straightforward: Qatari mediators traveled to Tehran to help ease tensions in the Middle East.
Last week, gold fell below $4,000 because U.S.-China trade talks eased tensions and safe-haven demand cooled. The same logic is playing out again: geopolitical risks are receding at the margin, and crude oil—one of the assets most sensitive to geopolitical premiums—was the first to fall.
Following this chain of events, the transmission goes like this:
Easing Middle East tensions → fading safe-haven premium in crude → lower oil prices → easing inflation expectations → more room for Fed rate cuts → a weaker dollar → gains for risk assets.
For BTC, the end of this chain points to a potentially bullish signal. But keep the timing lag in mind: oil prices are falling today, inflation data won’t reflect that until next month, and the earliest the Fed could act is December. This isn’t a catalyst for today’s price action; it’s a signal about the macro direction over the next one to two months.
More immediate variables are in focus this week: earnings from Microsoft, Amazon, and Apple, plus the FOMC decision. Lower oil prices provide a macro tailwind, but whether that translates into a market rally will depend on whether these events confirm the outlook.
Easing geopolitical tensions, falling oil prices, and a stress test for AI earnings—this is one of the most information-packed weeks for markets this year.
Do you think BTC will be above $83,000 after this week’s earnings and the FOMC meeting?
$BTC
{future}(BTCUSDT)
$CL
{future}(CLUSDT)
#CrudeOil #MiddleEastTensions #Inflation #FederalReserve
Oil prices kick off Monday with a drop.
On October 26, WTI and Brent opened 1.2% lower on Monday. The catalyst was straightforward: Qatari mediators traveled to Tehran to help ease tensions in the Middle East.
Last week, gold fell below $4,000 because U.S.-China trade talks eased tensions and safe-haven demand cooled. The same logic is playing out again: geopolitical risks are receding at the margin, and crude oil—one of the assets most sensitive to geopolitical premiums—was the first to fall.
Following this chain of events, the transmission goes like this:
Easing Middle East tensions → fading safe-haven premium in crude → lower oil prices → easing inflation expectations → more room for Fed rate cuts → a weaker dollar → gains for risk assets.
For BTC, the end of this chain points to a potentially bullish signal. But keep the timing lag in mind: oil prices are falling today, inflation data won’t reflect that until next month, and the earliest the Fed could act is December. This isn’t a catalyst for today’s price action; it’s a signal about the macro direction over the next one to two months.
More immediate variables are in focus this week: earnings from Microsoft, Amazon, and Apple, plus the FOMC decision. Lower oil prices provide a macro tailwind, but whether that translates into a market rally will depend on whether these events confirm the outlook.
Easing geopolitical tensions, falling oil prices, and a stress test for AI earnings—this is one of the most information-packed weeks for markets this year.
Do you think BTC will be above $83,000 after this week’s earnings and the FOMC meeting?
$BTC
$CL
#CrudeOil #MiddleEastTensions #Inflation #FederalReserve
1
1.7k
·
--
The FOMC meets tomorrow. The statement is due at 2 p.m. ET on October 28 (2 a.m. Beijing time on October 29).
BTC is currently around 80,800–81,000, rebounding from a weekend low of 79,146. Over the past 24 hours, the crypto market saw $810 million in liquidations, including $689 million in long positions. ETF net outflows have been significant this week. The market has all its bets riding on the next couple of days.
Here are three scenarios laid out clearly. We can compare them with what actually happens.
Scenario 1: A clean pause (most market-friendly)
The Fed holds rates at 3.75%–4.00%. Warsh strikes a dovish tone at the press conference, doesn’t proactively mention a December rate-hike timeline, and returns decision-making to a “data-dependent” approach.
In this case, 10-year Treasury yields fall, the dollar weakens, and BTC could quickly break above the top of its five-week range, challenging 84,500 and 87,300. The odds of this are currently around 20–25%.
Scenario 2: A hawkish pause (most likely, around 75%)
The Fed holds rates, but at the press conference Warsh explicitly says that further action is “still under consideration” at the December meeting, or reiterates that inflation has not yet reached its target, keeping the odds of a December rate hike elevated.
This is a neutral outcome: “not bearish enough to hurt, not bullish enough to help.” BTC may continue trading sideways in the 80,000–82,000 range, awaiting the next round of pricing around the November 3 midterm elections and the December FOMC meeting.
Scenario 3: An outright rate hike (around 7%, a low-probability black swan)
With CPI at 3.7% and monthly PPI at 1.3%, the Fed technically has data to support a hike. But Warsh explicitly said in Bangkok, “I don’t prejudge meetings”—so if they do hike, it would genuinely surprise the market. BTC would face a test of the lower support zone between 77,600 and 80,400.
There’s another variable along this same timeline: October 29 is the release date for PCE (the Fed’s most closely watched inflation gauge), October 30 is the expiry date for $1.11 billion in monthly BTC options, and November 3 is the U.S. midterm election.
The coming week will be the five most information-packed days of the year.
Which scenario are you betting on between tonight and the day after tomorrow? Let us know what you think.
$BTC
{future}(BTCUSDT)
$XRP
{future}(XRPUSDT)
The FOMC meets tomorrow. The statement is due at 2 p.m. ET on October 28 (2 a.m. Beijing time on October 29).
BTC is currently around 80,800–81,000, rebounding from a weekend low of 79,146. Over the past 24 hours, the crypto market saw $810 million in liquidations, including $689 million in long positions. ETF net outflows have been significant this week. The market has all its bets riding on the next couple of days.
Here are three scenarios laid out clearly. We can compare them with what actually happens.
Scenario 1: A clean pause (most market-friendly)
The Fed holds rates at 3.75%–4.00%. Warsh strikes a dovish tone at the press conference, doesn’t proactively mention a December rate-hike timeline, and returns decision-making to a “data-dependent” approach.
In this case, 10-year Treasury yields fall, the dollar weakens, and BTC could quickly break above the top of its five-week range, challenging 84,500 and 87,300. The odds of this are currently around 20–25%.
Scenario 2: A hawkish pause (most likely, around 75%)
The Fed holds rates, but at the press conference Warsh explicitly says that further action is “still under consideration” at the December meeting, or reiterates that inflation has not yet reached its target, keeping the odds of a December rate hike elevated.
This is a neutral outcome: “not bearish enough to hurt, not bullish enough to help.” BTC may continue trading sideways in the 80,000–82,000 range, awaiting the next round of pricing around the November 3 midterm elections and the December FOMC meeting.
Scenario 3: An outright rate hike (around 7%, a low-probability black swan)
With CPI at 3.7% and monthly PPI at 1.3%, the Fed technically has data to support a hike. But Warsh explicitly said in Bangkok, “I don’t prejudge meetings”—so if they do hike, it would genuinely surprise the market. BTC would face a test of the lower support zone between 77,600 and 80,400.
There’s another variable along this same timeline: October 29 is the release date for PCE (the Fed’s most closely watched inflation gauge), October 30 is the expiry date for $1.11 billion in monthly BTC options, and November 3 is the U.S. midterm election.
The coming week will be the five most information-packed days of the year.
Which scenario are you betting on between tonight and the day after tomorrow? Let us know what you think.
$BTC
$XRP
327
1
12
701
·
--
This is the most important 72-hour stretch of this year’s earnings season—bar none.
Three tech companies with a combined market cap of over $10 trillion will report earnings this week: Microsoft (October 27), Amazon (October 29), and Apple (October 30). Alphabet reports on October 27 as well. Together, the four companies make up around 25% of the S&P 500. The Nasdaq’s direction will be decided this week.
What’s the backdrop? For the past two weeks, the market has been haunted by one question: Where’s the return on AI investment? After Alphabet’s earnings, AI stocks were collectively hit with a valuation reset, the Nasdaq fell more than 2% in a week, and BTC followed suit. But Meta and Tesla’s earnings weren’t actually bad—Meta’s EPS of $7.40 comfortably beat expectations, and Tesla also came in slightly ahead. Last week’s sell-off was more of an emotional overreaction than a collapse in fundamentals.
Now a new group is taking the stage.
For Microsoft, the key questions are whether Azure can sustain its growth rate and what the real revenue figures are for AI Copilot’s commercialization. Azure growth came in below expectations last quarter, and the market punished the stock. If Microsoft can deliver a satisfactory growth rate and positive guidance this time, the turnaround in the AI narrative could start here.
Amazon’s story is more straightforward. Jassy has already said that “AWS capacity for 2027 is nearly sold out.” This week’s Q3 earnings report is the moment when the numbers will put that claim to the test. The market expects revenue of $179.2 billion, and analysts think it could beat expectations. More important are AWS’s quarterly revenue and profit margin—the clearest financial reflection of demand for AI infrastructure.
Apple is a little different: the focus isn’t AI, but actual sales of the iPhone 17 lineup and Services revenue. Whether Apple Intelligence subscriptions have started contributing to revenue will determine whether Apple can reclaim a voice in the AI narrative.
There’s another variable: the FOMC announces its rate decision on October 28. The market isn’t expecting a move, but if Chair Warsh’s wording is hawkish, it could pour cold water on this wave of Big Tech earnings. With both events landing in the same week, volatility is likely to be much higher than during a typical earnings week.
For crypto markets, the logic is clear: if all three tech giants beat expectations, the AI narrative will recover, the Nasdaq will rebound, and support for BTC around $80,000 will strengthen. If any one of them gives negative guidance, last week’s valuation reset may have been just the opening act.
This week’s earnings will provide the answer.
#股票财报季
$MSFTB
{spot}(MSFTBUSDT)
$AAPLB
{spot}(AAPLBUSDT)
$AMZNB
{spot}(AMZNBUSDT)
This is the most important 72-hour stretch of this year’s earnings season—bar none.
Three tech companies with a combined market cap of over $10 trillion will report earnings this week: Microsoft (October 27), Amazon (October 29), and Apple (October 30). Alphabet reports on October 27 as well. Together, the four companies make up around 25% of the S&P 500. The Nasdaq’s direction will be decided this week.
What’s the backdrop? For the past two weeks, the market has been haunted by one question: Where’s the return on AI investment? After Alphabet’s earnings, AI stocks were collectively hit with a valuation reset, the Nasdaq fell more than 2% in a week, and BTC followed suit. But Meta and Tesla’s earnings weren’t actually bad—Meta’s EPS of $7.40 comfortably beat expectations, and Tesla also came in slightly ahead. Last week’s sell-off was more of an emotional overreaction than a collapse in fundamentals.
Now a new group is taking the stage.
For Microsoft, the key questions are whether Azure can sustain its growth rate and what the real revenue figures are for AI Copilot’s commercialization. Azure growth came in below expectations last quarter, and the market punished the stock. If Microsoft can deliver a satisfactory growth rate and positive guidance this time, the turnaround in the AI narrative could start here.
Amazon’s story is more straightforward. Jassy has already said that “AWS capacity for 2027 is nearly sold out.” This week’s Q3 earnings report is the moment when the numbers will put that claim to the test. The market expects revenue of $179.2 billion, and analysts think it could beat expectations. More important are AWS’s quarterly revenue and profit margin—the clearest financial reflection of demand for AI infrastructure.
Apple is a little different: the focus isn’t AI, but actual sales of the iPhone 17 lineup and Services revenue. Whether Apple Intelligence subscriptions have started contributing to revenue will determine whether Apple can reclaim a voice in the AI narrative.
There’s another variable: the FOMC announces its rate decision on October 28. The market isn’t expecting a move, but if Chair Warsh’s wording is hawkish, it could pour cold water on this wave of Big Tech earnings. With both events landing in the same week, volatility is likely to be much higher than during a typical earnings week.
For crypto markets, the logic is clear: if all three tech giants beat expectations, the AI narrative will recover, the Nasdaq will rebound, and support for BTC around $80,000 will strengthen. If any one of them gives negative guidance, last week’s valuation reset may have been just the opening act.
This week’s earnings will provide the answer.
#股票财报季
$MSFTB
$AAPLB
$AMZNB
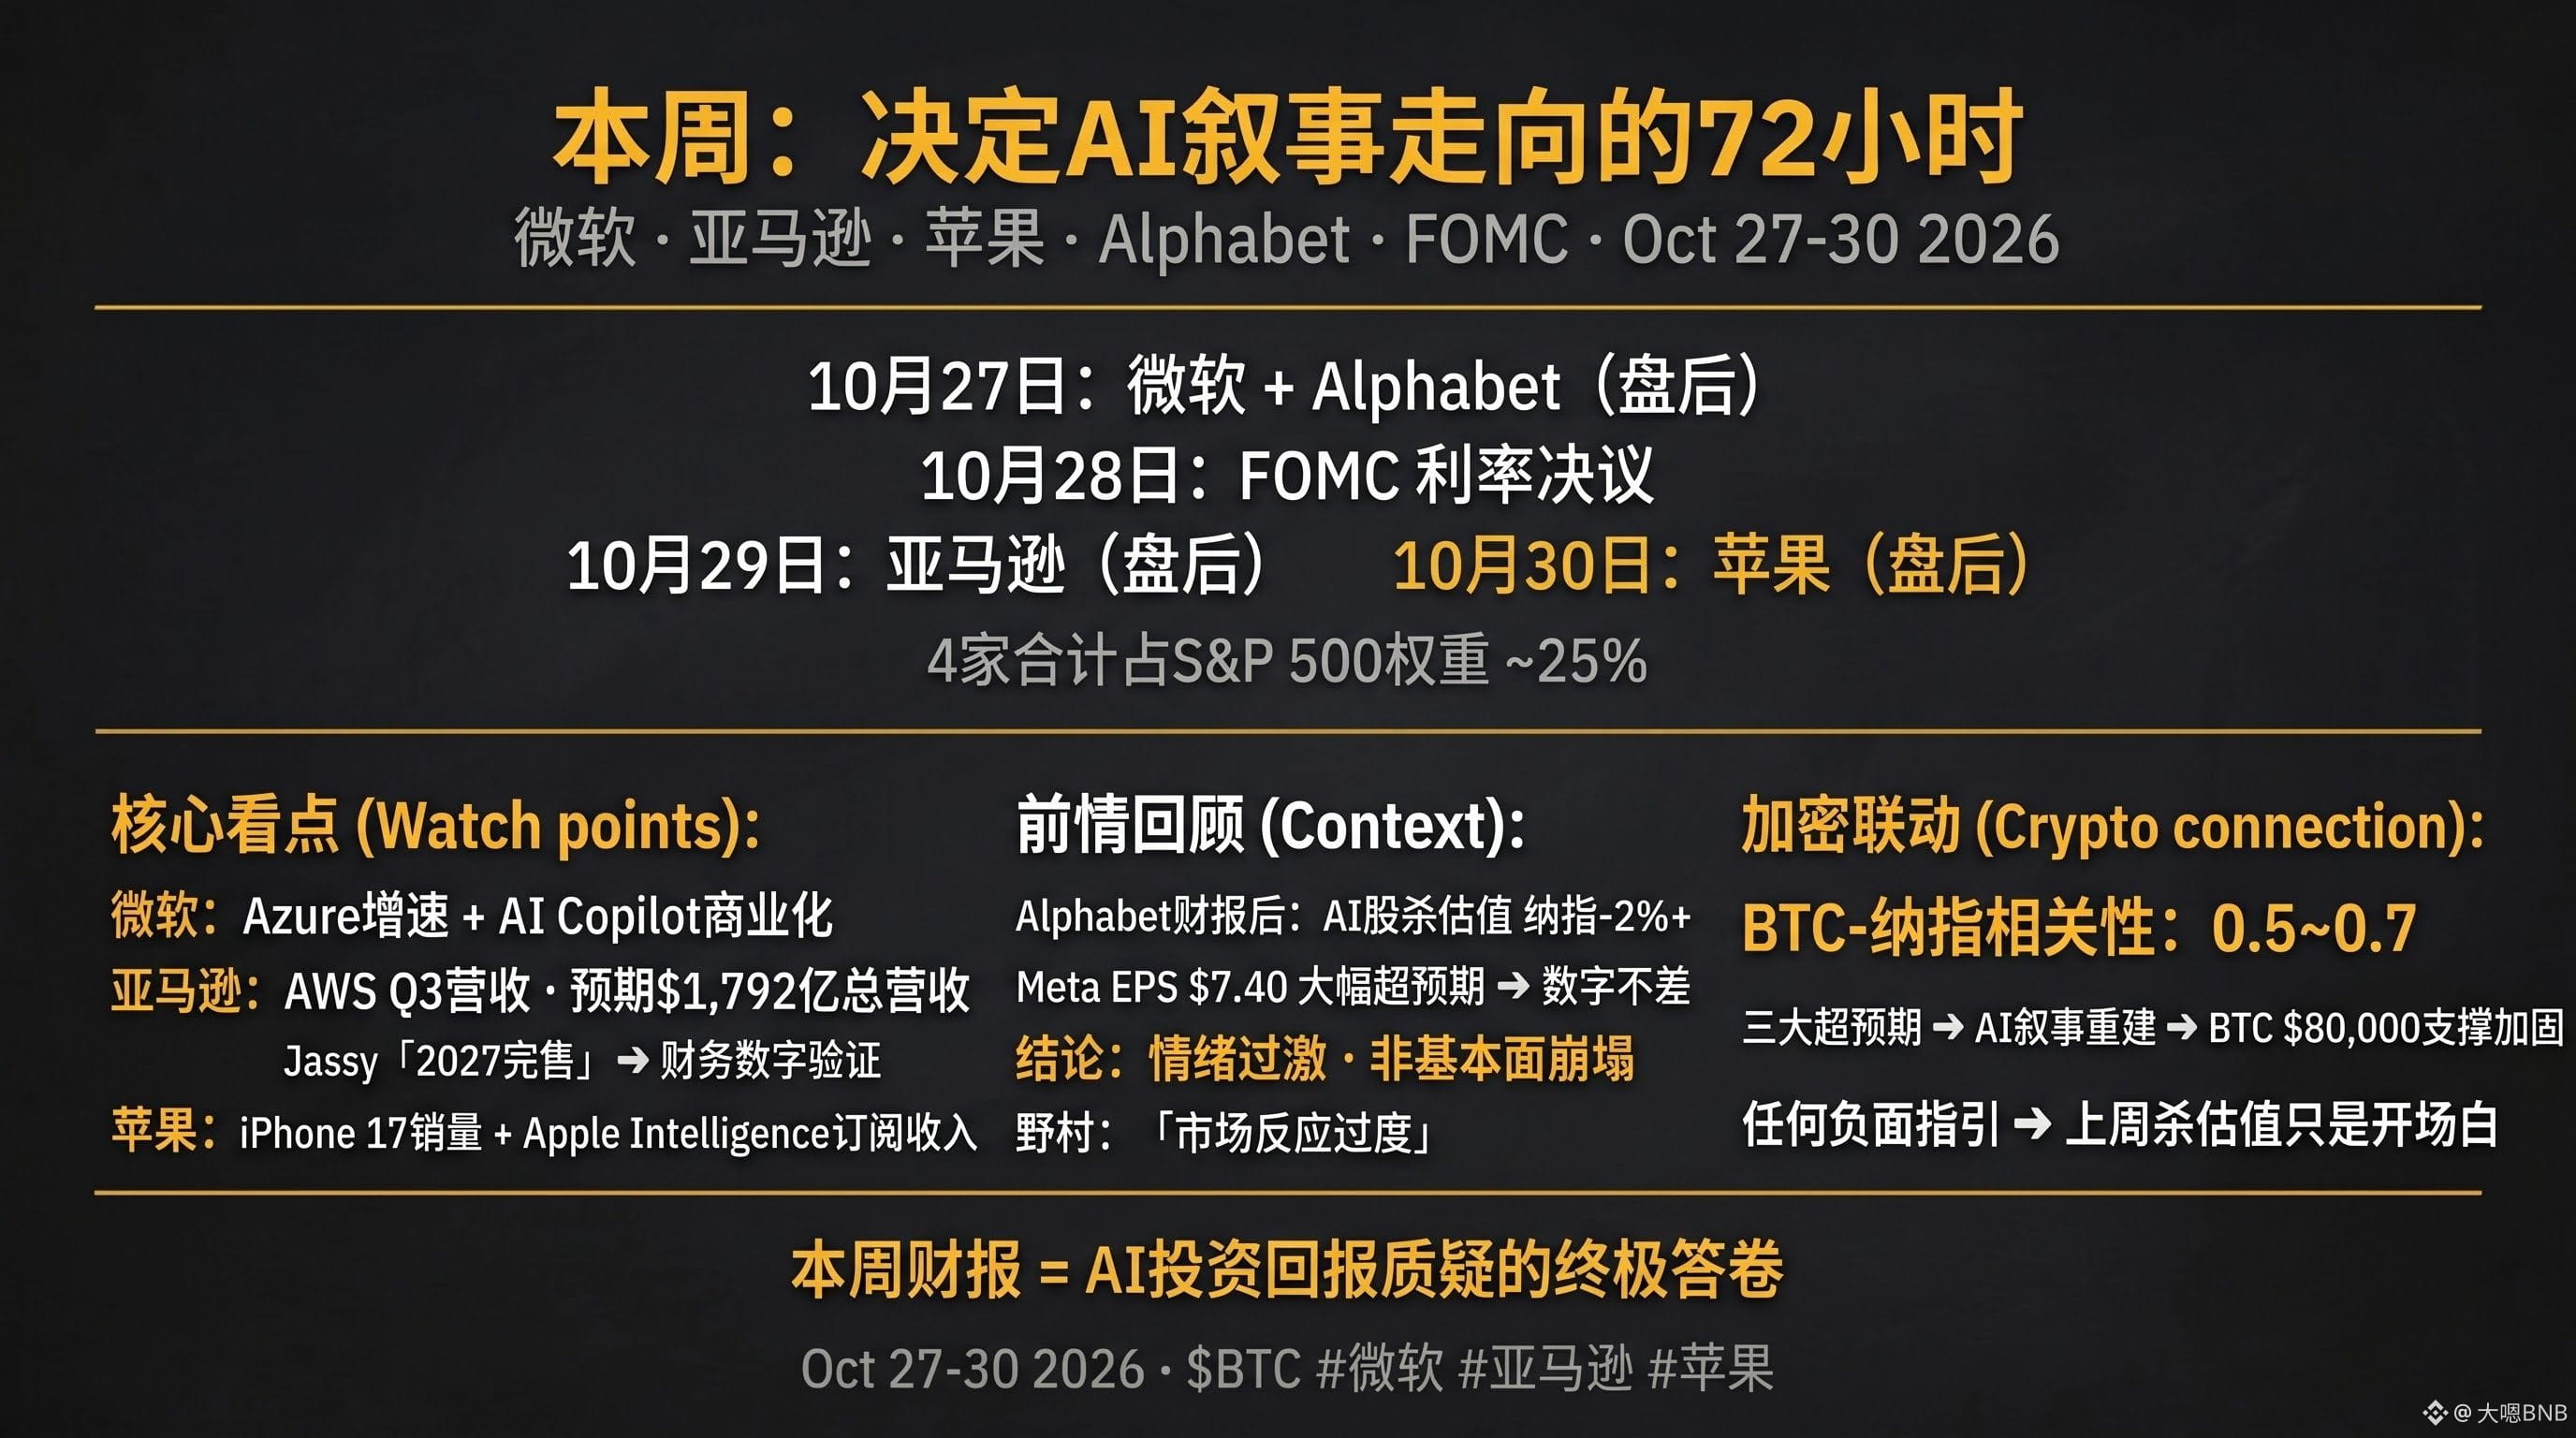
2
25
18.8k
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
UniswapA16zSeekDeFiExemptionFromIllinoisCryptoTax
16,901 views
635 Discussing
The debate over crypto taxation is heating up as Uniswap and Andreessen Horowitz ( a16z ) push for a DeFi exemption from Illinois proposed crypto tax rules. Their concern is that decentralized finance protocols and non custodial platforms could face unfair tax burdens potentially slowing innovation and making crypto development more difficult. DeFi platforms allow users to trade and manage digital assets without traditional intermediaries so applying conventional financial tax rules may create serious challenges. This could become an important moment for the US crypto industry as regulators must find a balance between fair taxation, investor protection, and innovation. 🚀
The main concern is that the proposed 0.2% tax is calculated on transaction value, not simply trading profits. Uniswap a16z and the DeFi Education Fund want wallet withdrawals and cross chain bridging excluded, while also opposing requirements to maintain private key records. Illinois has agreed to postpone implementation until July 1, 2027 subject to court approval. The outcome could influence how other US states approach DeFi taxation. The Defiant +2
What do you think 🤔 ? Should DeFi transactions be tax free to protect decentralization or should crypto platforms follow traditional tax rules ? 🤔
#UniswapA16zSeekDeFiExemptionFromIllinoisCryptoTax
Volatile
·3 Likes
·150 views
HKDollarStablecoinHKDAPToLaunchOnSolana
11,201 views
376 Discussing
$1.5BInLeveragedCryptoBetsLiquidated
28,916 views
228 Discussing