

玲姐AL
12.1k Posts
玲姐AL
Report
Block User
每日更新行业新闻、热门事件,撸毛活动与圈内八卦,一手热点,实操攻略,圈内瓜料全都有带你轻松看懂Web3,玩赚加密市场。
Open Trade

USD1 Holder
Frequent Trader
1.2 Years
1.3K+ Following
10.5K+ Followers
9.8K+ Liked
Posts
Portfolio
All
Quotes
PINNED
·
--
Bullish
I’m willing to give an AI Agent $100 to check market prices, buy data, and call models, but I wouldn’t hand over control of my entire wallet. AI can do work for me, but that doesn’t mean it will always get things right. If it makes a wrong judgment or calls a service it shouldn’t, and the money is already gone, who’s responsible?
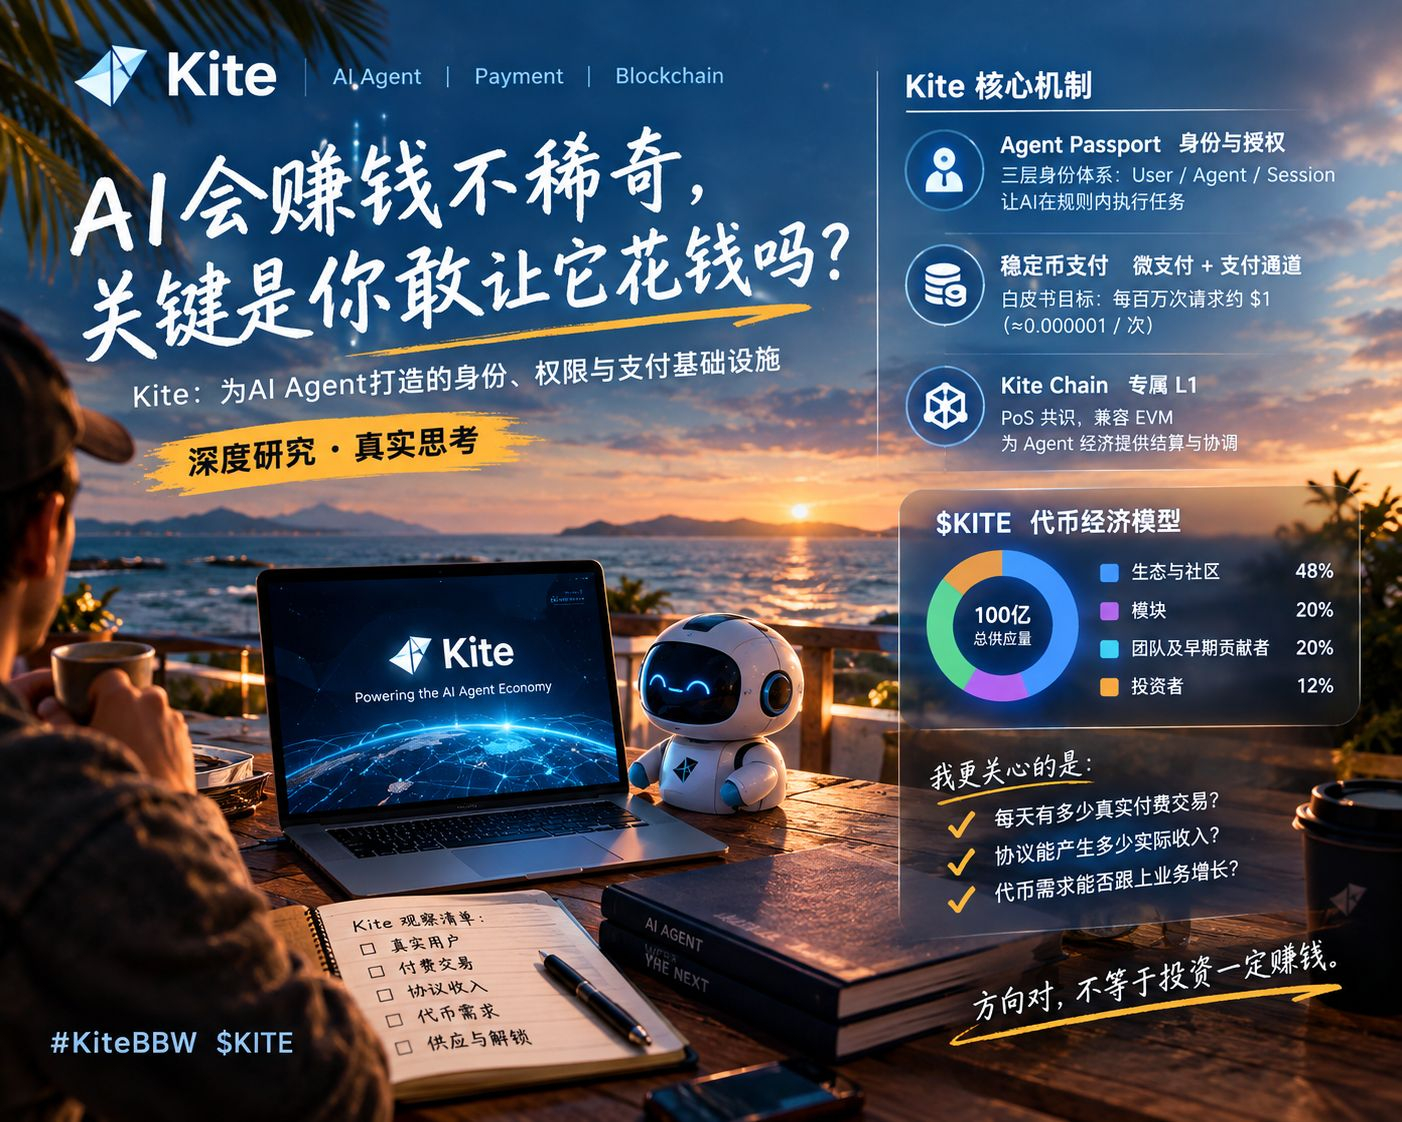
That’s also what I’ve focused on most while researching Kite.
Kite’s Agent Passport isn’t just about giving an AI a wallet. It brings identity, authorization, and payment limits together. Users can set a per-payment cap, an overall budget, a validity period, and which assets the Agent is allowed to use in advance. The Agent can only act within those authorized limits. For example, if I only authorize it to spend $100 on data services, there’s no need to hand over control of my other funds as well.
Kite’s mainnet launched in April 2026. It has a Chain ID of 2366, is EVM-compatible, and supports stablecoin settlement. The team has also shared testnet figures: more than 1.9 billion Agent interactions in total, with daily activity peaking at 30 million calls. Those numbers look impressive, but they’re from the testnet phase and don’t mean the mainnet already has a comparable volume of real paid business.
I also looked into the token model for $KITE . The maximum supply is 10 billion tokens: 48% is allocated to the ecosystem and community, 20% to modules, 20% to the team and early contributors, and 12% to investors. The value-capture mechanism laid out by the team involves charging commissions on AI service transactions, then converting part of the proceeds into KITE to support the development of modules and the network.
Whether this mechanism can genuinely support the token’s value will depend on real business activity. If Agents call lots of services every day, but few users are willing to keep paying, even a flurry of interactions may not translate into stable revenue. On the other hand, if businesses are willing to pay over the long term for data, models, and automation services, Kite may have a chance to turn its infrastructure into a viable business.
I’ll be keeping a close eye on three metrics: mainnet transaction growth, actual settlement volume, and protocol revenue. Whether all three grow together is more meaningful than simply looking at the number of addresses or the level of activity.
AI Agents could become a huge market, but I won’t assume that $KITE must be valuable just because the sector has potential. Even the best payment infrastructure can hardly support token demand on its own
#KiteBBW $KITE
7
4
356
·
--
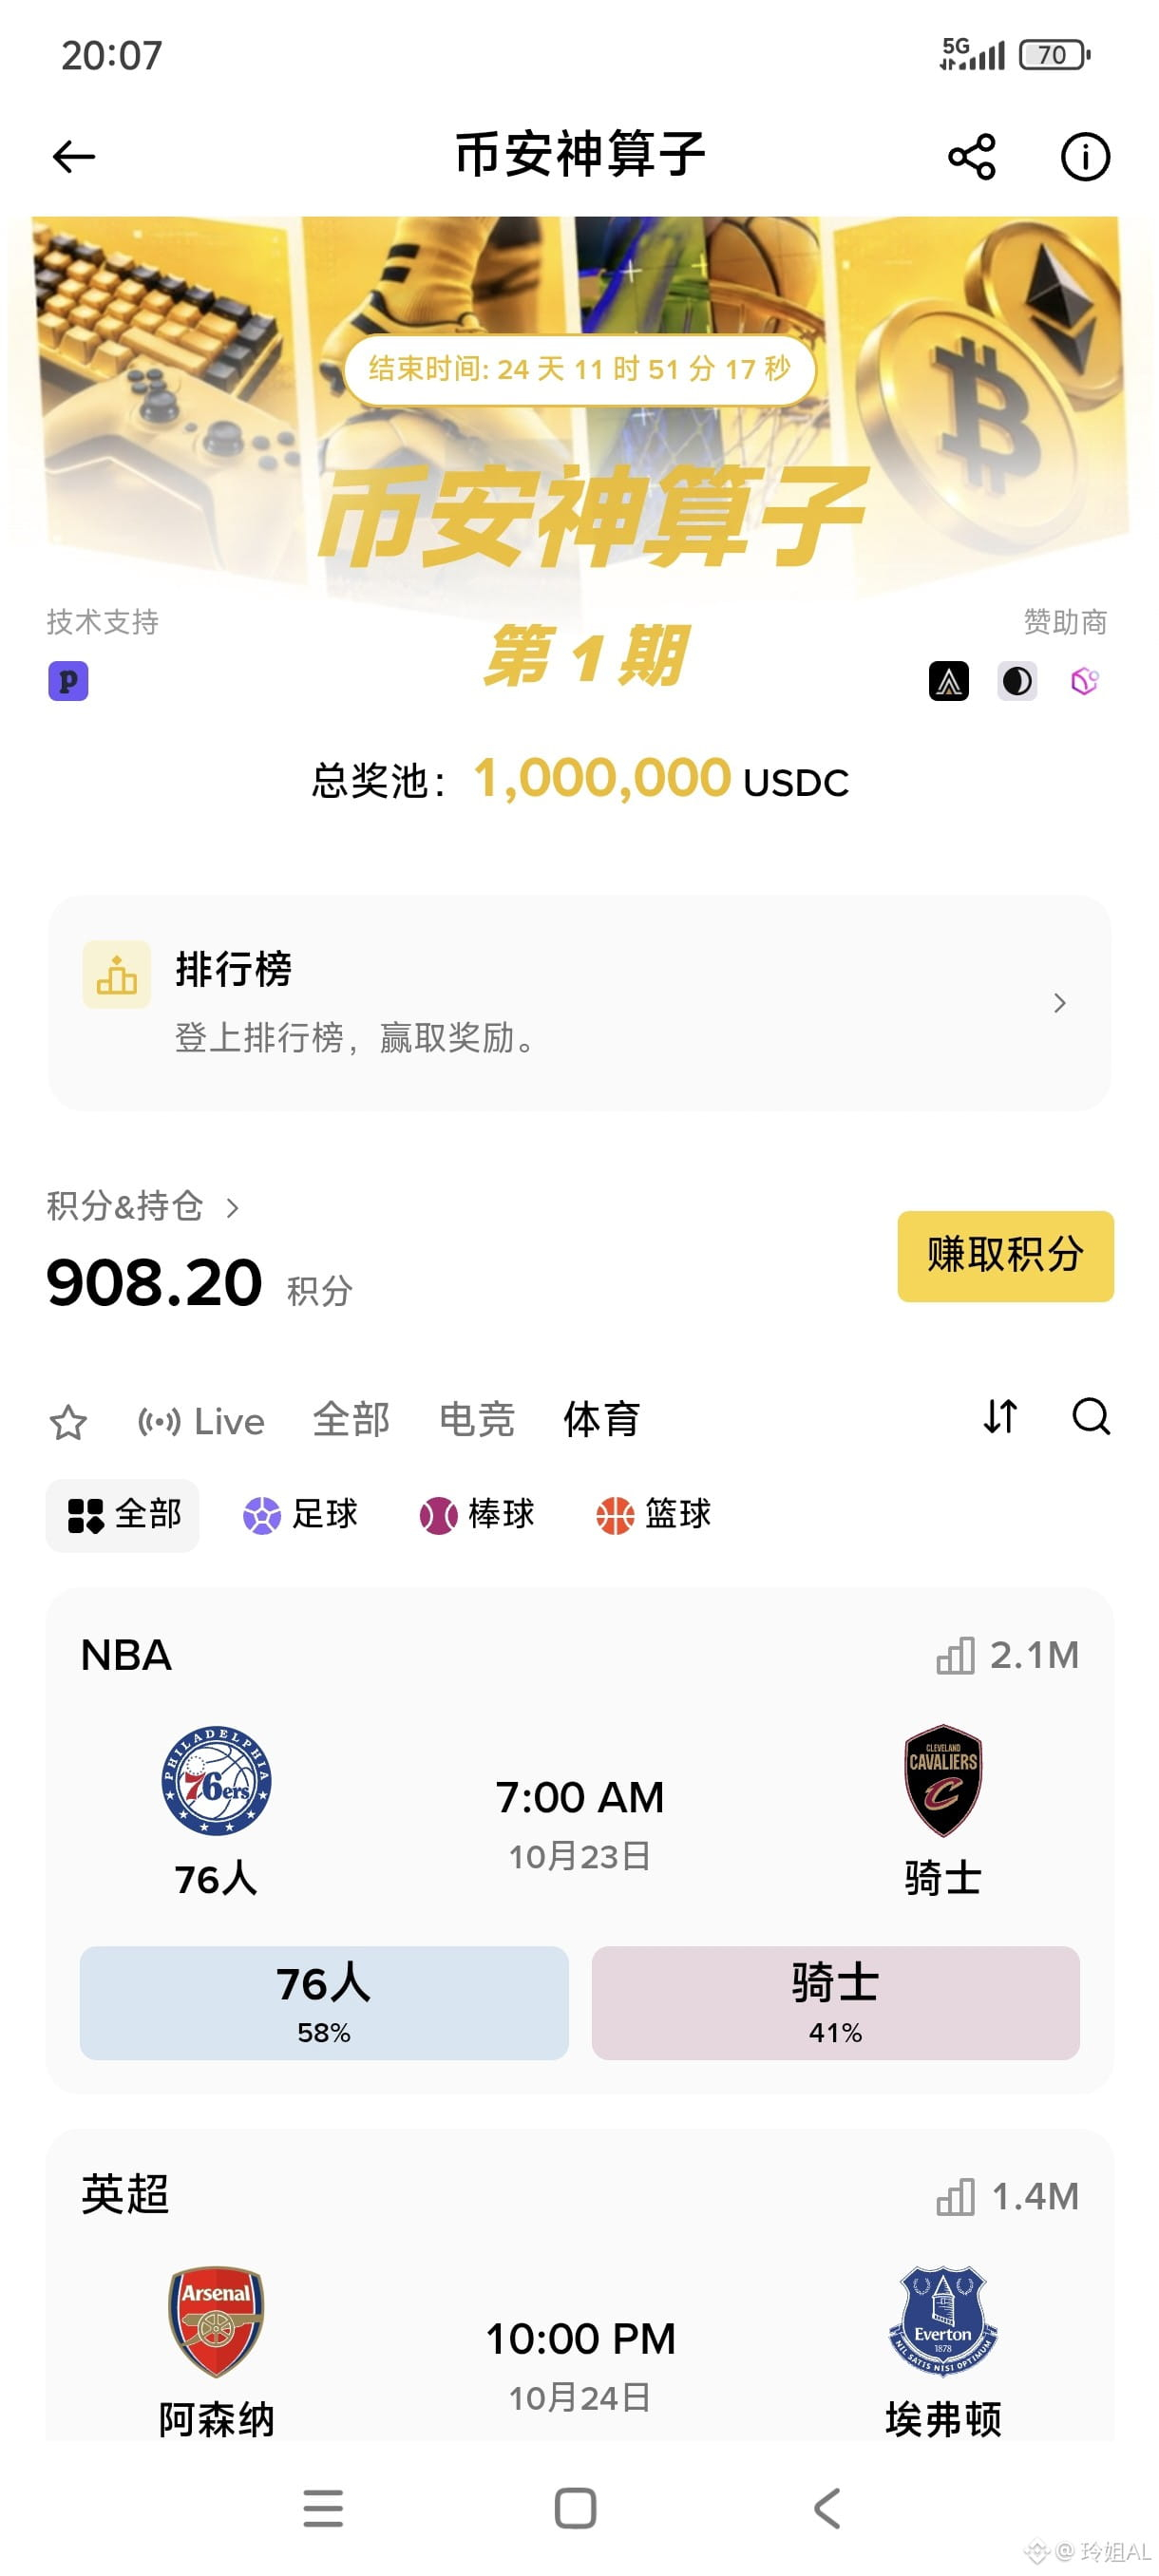
Binance oracle. Everyone can join the new event if they have time. There are freebies to claim. #币安神算子
Binance oracle. Everyone can join the new event if they have time. There are freebies to claim. #币安神算子
165
·
--
Verified
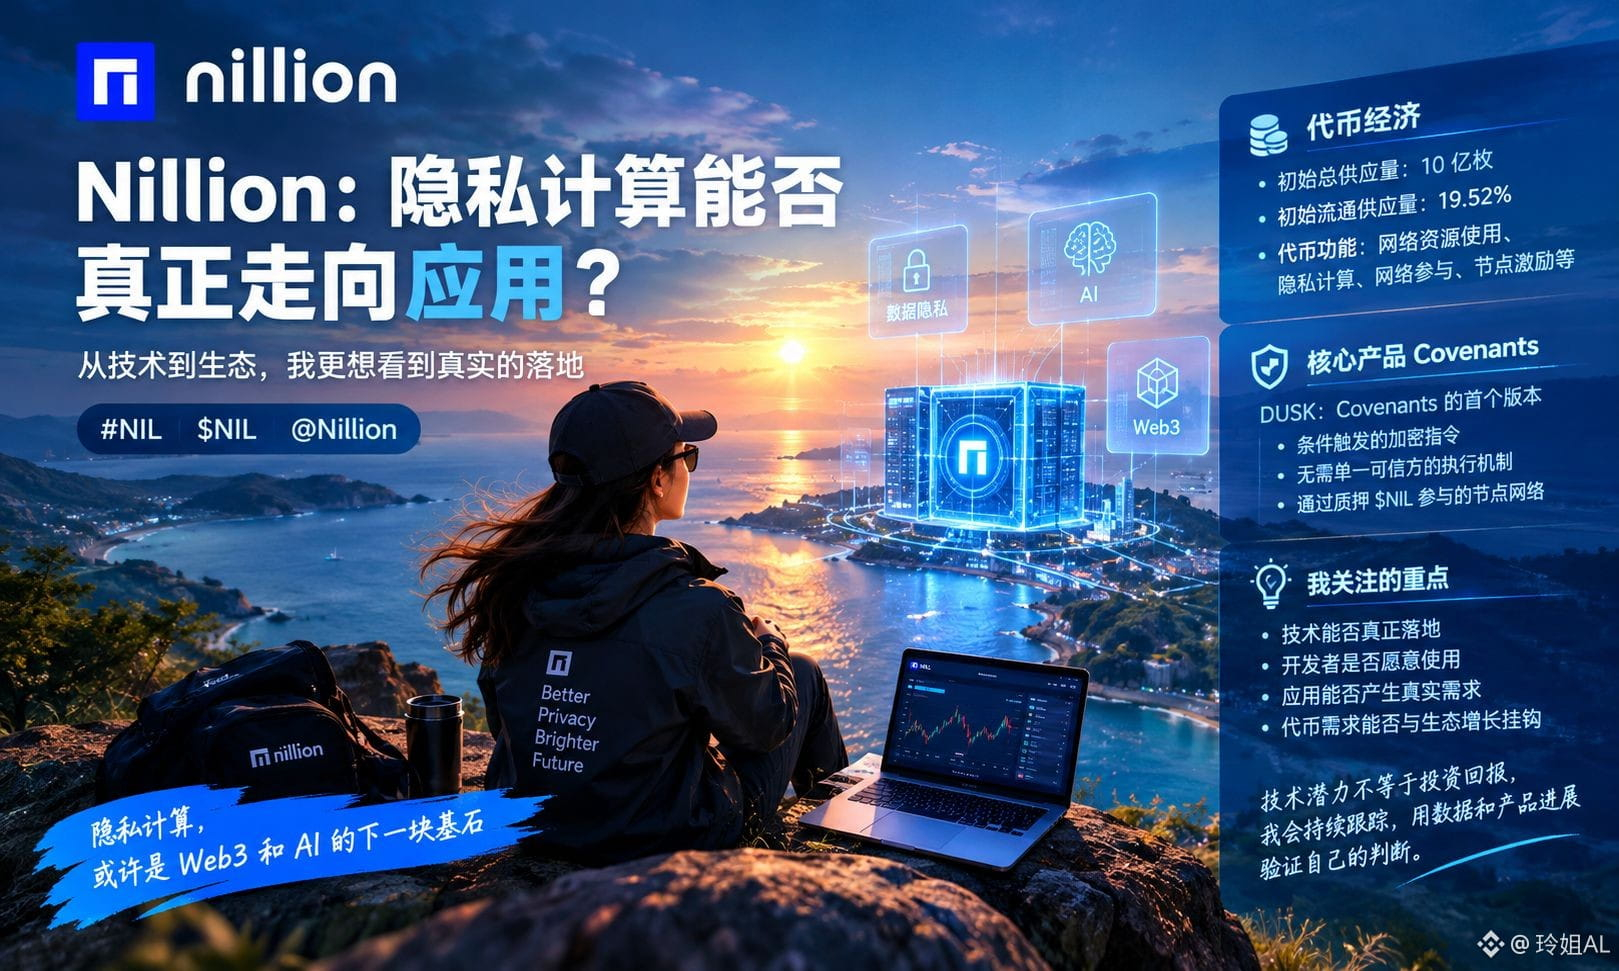
Recently, I’ve started taking a serious look at @Nillion. Honestly, rather than watching $NIL go up and down every day, I’d rather understand one thing: can privacy computing solve the problem of sensitive data being impossible to use securely as Web3 and AI develop?
I’ve bought some $NIL, but I don’t want my holdings to make me blindly bullish on a project. What’s really worth researching, in my view, is whether the technology can be put into practice and whether the token can generate real demand as the ecosystem grows.
📊 First, let’s look at nil’s tokenomics
According to the token information released by the project, the initial total supply is 1 billion tokens, with an initial circulating supply of about 19.52%. This means that researching the project isn’t just about looking at the current price—we also need to pay attention to future unlocks, changes in circulating supply, and whether ecosystem growth can absorb the additional supply.
In terms of utility, it is connected to mechanisms such as network resource usage, privacy computing, and node incentives. But there’s a key question: will increased network usage really translate into sustained demand for the token? That needs to be verified against actual product usage and the token mechanism.
What I find most compelling is its exploration of privacy computing. In the past, when we talked about Web3, we focused more on whether assets could be transferred securely. But as AI and data applications continue to develop,
Nillion’s Covenants is one product direction I’ve been paying close attention to recently. DUSK, in particular, is positioned as the first phase of Covenants, involving condition-triggered encrypted instructions, execution mechanisms, and a node system for participating in the network through staking.
If these mechanisms can gradually be brought to life, they could open up opportunities for more privacy-focused data collaboration and application scenarios. However, designing the technology is one thing; whether developers are willing to use it and applications can keep running is another.
I believe that assessing Nillion requires more than just listening to what the project says. We also need to keep an eye on Covenants’ actual progress, developer participation, network usage data, and the connection between these activities and demand for the token.
I currently hold some, and I’ll continue following the project. Holding a position doesn’t mean I’ve reached a conclusion, and technological potential certainly doesn’t guarantee investment returns. I’d rather keep researching and observing, and use real progress to test my judgment.
#nil $NIL @nillionnetwork
Recently, I’ve started taking a serious look at @Nillion. Honestly, rather than watching $NIL go up and down every day, I’d rather understand one thing: can privacy computing solve the problem of sensitive data being impossible to use securely as Web3 and AI develop?
I’ve bought some $NIL , but I don’t want my holdings to make me blindly bullish on a project. What’s really worth researching, in my view, is whether the technology can be put into practice and whether the token can generate real demand as the ecosystem grows.
📊 First, let’s look at nil’s tokenomics
According to the token information released by the project, the initial total supply is 1 billion tokens, with an initial circulating supply of about 19.52%. This means that researching the project isn’t just about looking at the current price—we also need to pay attention to future unlocks, changes in circulating supply, and whether ecosystem growth can absorb the additional supply.
In terms of utility, it is connected to mechanisms such as network resource usage, privacy computing, and node incentives. But there’s a key question: will increased network usage really translate into sustained demand for the token? That needs to be verified against actual product usage and the token mechanism.
What I find most compelling is its exploration of privacy computing. In the past, when we talked about Web3, we focused more on whether assets could be transferred securely. But as AI and data applications continue to develop,
Nillion’s Covenants is one product direction I’ve been paying close attention to recently. DUSK, in particular, is positioned as the first phase of Covenants, involving condition-triggered encrypted instructions, execution mechanisms, and a node system for participating in the network through staking.
If these mechanisms can gradually be brought to life, they could open up opportunities for more privacy-focused data collaboration and application scenarios. However, designing the technology is one thing; whether developers are willing to use it and applications can keep running is another.
I believe that assessing Nillion requires more than just listening to what the project says. We also need to keep an eye on Covenants’ actual progress, developer participation, network usage data, and the connection between these activities and demand for the token.
I currently hold some, and I’ll continue following the project. Holding a position doesn’t mean I’ve reached a conclusion, and technological potential certainly doesn’t guarantee investment returns. I’d rather keep researching and observing, and use real progress to test my judgment.
#nil $NIL @Nillion
2
3
491
·
--
Claim your red envelopes
Claim your red envelopes
玲姐AL
·
--
Red packets are ready 🧧 Get your fingers moving!
We’ve prepared 100u in red packets. Happy summer vacation, everyone!
May you receive both good fortune and great returns. Wishing everyone a market that keeps soaring 📈
We’ve prepared 100u in red packets. Happy summer vacation, everyone!
May you receive both good fortune and great returns. Wishing everyone a market that keeps soaring 📈
148
·
--
Red packets are ready 🧧 Get your fingers moving!
We’ve prepared 100u in red packets. Happy summer vacation, everyone!
May you receive both good fortune and great returns. Wishing everyone a market that keeps soaring 📈
Red packets are ready 🧧 Get your fingers moving!
We’ve prepared 100u in red packets. Happy summer vacation, everyone!
May you receive both good fortune and great returns. Wishing everyone a market that keeps soaring 📈
We’ve prepared 100u in red packets. Happy summer vacation, everyone!
May you receive both good fortune and great returns. Wishing everyone a market that keeps soaring 📈
44
1
3
202
·
--
Hi everyone! Creator tasks have been gone for almost two months. @heyi , can you still arrange something for the top creator? The tasks I did recently earned about 300 USDT in rewards! I contributed it all to $ZEC ! I'm so sad and heartbroken.
Hi everyone! Creator tasks have been gone for almost two months. @Yi He , can you still arrange something for the top creator? The tasks I did recently earned about 300 USDT in rewards! I contributed it all to $ZEC ! I'm so sad and heartbroken.
2
339
·
--
Red envelopes are all set 🧧 Time to team up your lightning-fast fingers!
We prepared 100u red envelopes—wishing everyone a happy summer vacation.
May both good luck and earnings be delivered to your hands at the same time. Wishing you a strong, one-way upward market 📈
Red envelopes are all set 🧧 Time to team up your lightning-fast fingers!
We prepared 100u red envelopes—wishing everyone a happy summer vacation.
May both good luck and earnings be delivered to your hands at the same time. Wishing you a strong, one-way upward market 📈
We prepared 100u red envelopes—wishing everyone a happy summer vacation.
May both good luck and earnings be delivered to your hands at the same time. Wishing you a strong, one-way upward market 📈
3.3k
8
172
3.3k
·
--
Bullish
Partly True
#termmax @termmax
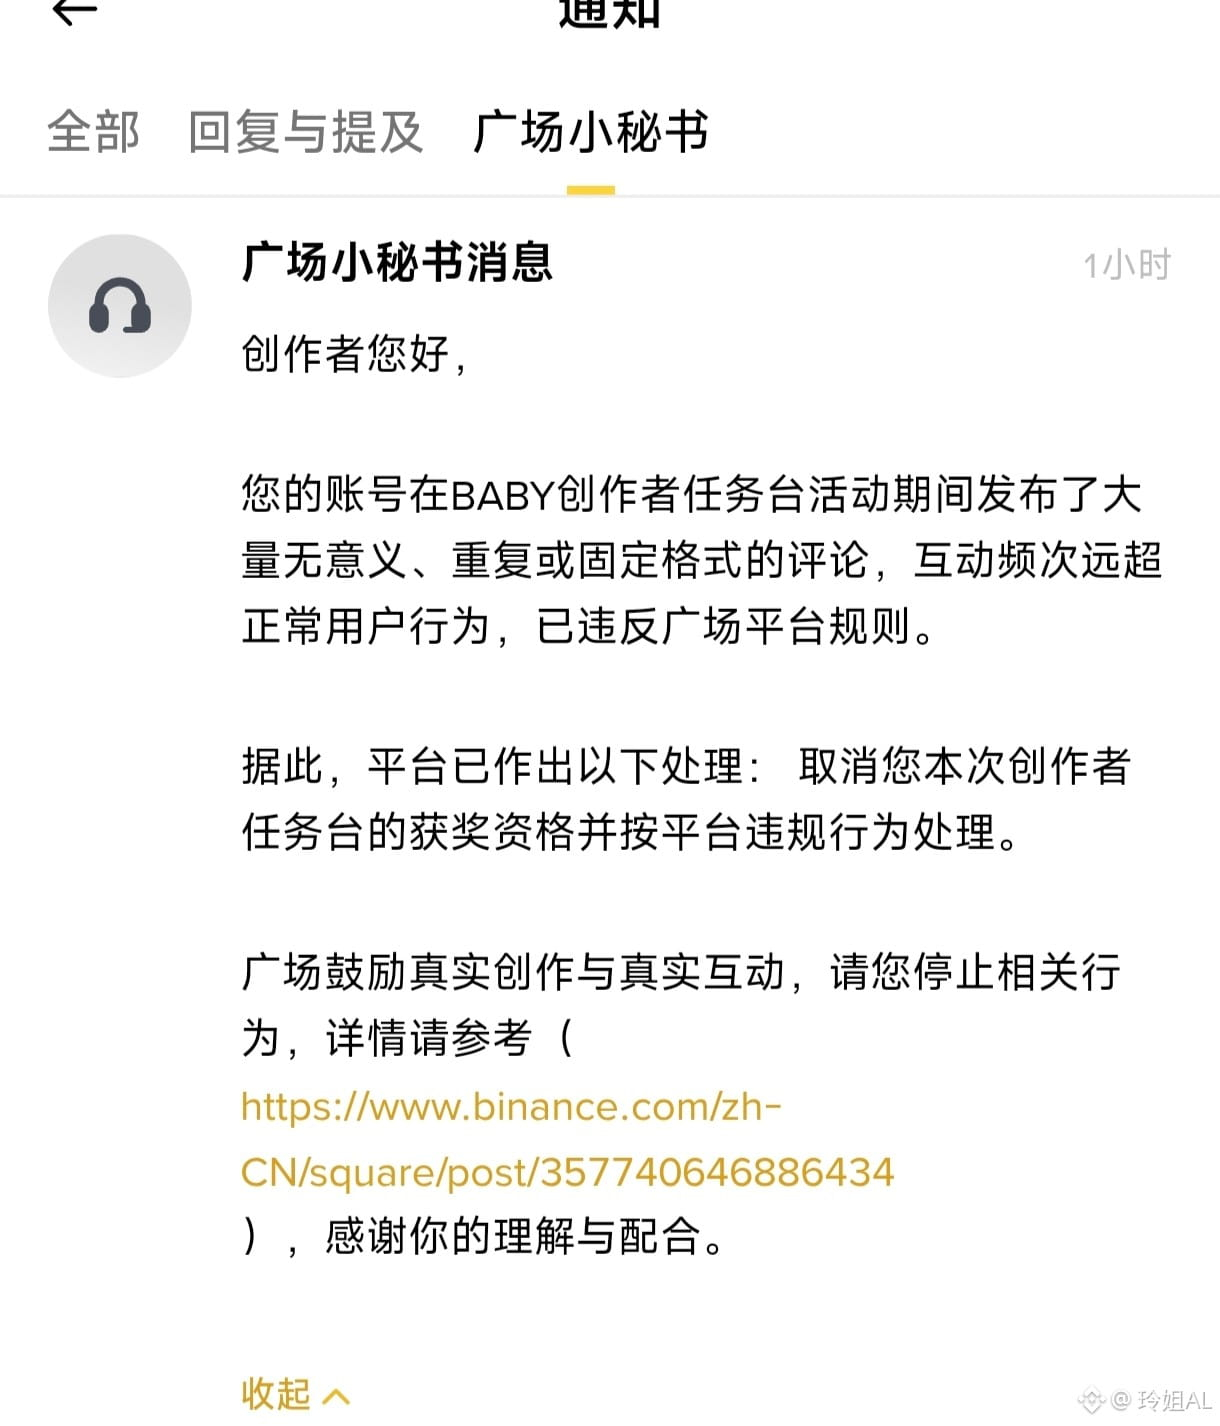
Brothers! Just now, my little secretary sent a message that the #2 spot was canceled due to $BABY . I can’t stand seeing others do well! They reported it. The top spots are really not easy to hold—there are just too many cold arrows underneath!
#ALPHA The market isn’t great either; every month it’s low, saving lives. It’s so uncomfortable.
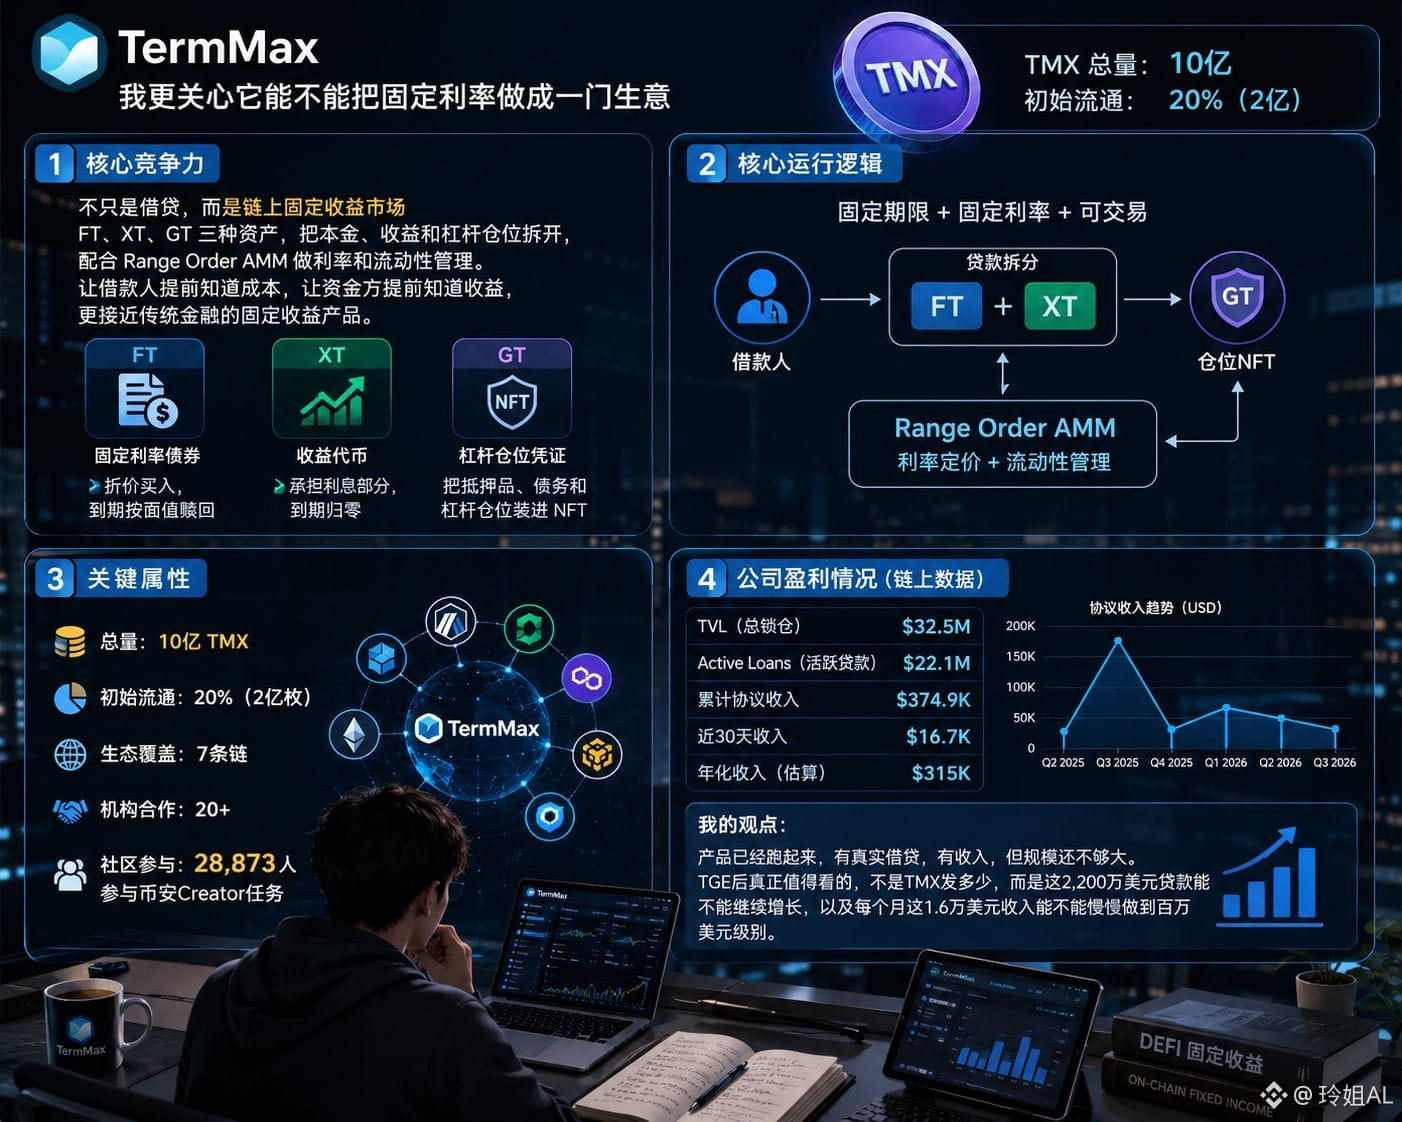
I’ve been studying TermMax recently, and I actually haven’t paid much attention to the 300,000 TMX reward. What truly interests me is whether it has the ability to turn “fixed interest rates” into a long-term business. I break my judgment into four points.
1. Core competitiveness:
I think the biggest difference between TermMax and ordinary lending protocols is that it’s not just about borrowing money—it’s building an on-chain fixed income market. There are three types of assets, FT, XT, and GT. They split principal, yield, and leveraged positions, and then combine with a Range Order AMM to manage interest rates and liquidity. Put simply: it lets borrowers know the cost in advance, and it lets liquidity providers know the yield in advance. This is much closer to traditional fixed-income products.
2. Core operating logic:
Once a loan enters the protocol, it’s split into FT and XT. GT is responsible for packaging the collateral, the debt, and the leveraged position into NFTs. That way, fixed term and fixed interest rates can be traded on-chain. I believe what’s truly hard here isn’t “lending,” but the following liquidity and pricing.
3. Key attributes:
Current total supply is 1 billion TMX, with an initial circulating supply of about 20%. The project has moved from the test stage into multi-chain expansion and the TGE phase. Official disclosures cover 7 chains and 20+ institutional partnerships. At the moment, the Chinese Creator tasks already have 28,873 participants, and community heat really has picked up.
4. Company profitability:
Here I’m more cautious. Term Structure Labs hasn’t publicly released a complete annual report in the traditional sense, so we can’t directly say “how much the company earns in a year.” On-chain data shows TermMax TVL is about $32.5 million, Active Loans about $22.1 million, and cumulative protocol revenue around $375,000, with the last 30 days about $16.7k.
So in my view, TermMax isn’t without revenue now—it already has a business closed loop, but the scale still isn’t big enough. After the TGE, what’s really worth watching isn’t how many TMX are emitted, but whether those $22.1 million in loans can keep growing, and whether this $16.7k revenue each month can gradually reach the million-dollar level.
#termmax @TermMax
Brothers! Just now, my little secretary sent a message that the #2 spot was canceled due to $BABY . I can’t stand seeing others do well! They reported it. The top spots are really not easy to hold—there are just too many cold arrows underneath!
#ALPHA The market isn’t great either; every month it’s low, saving lives. It’s so uncomfortable.
I’ve been studying TermMax recently, and I actually haven’t paid much attention to the 300,000 TMX reward. What truly interests me is whether it has the ability to turn “fixed interest rates” into a long-term business. I break my judgment into four points.
1. Core competitiveness:
I think the biggest difference between TermMax and ordinary lending protocols is that it’s not just about borrowing money—it’s building an on-chain fixed income market. There are three types of assets, FT, XT, and GT. They split principal, yield, and leveraged positions, and then combine with a Range Order AMM to manage interest rates and liquidity. Put simply: it lets borrowers know the cost in advance, and it lets liquidity providers know the yield in advance. This is much closer to traditional fixed-income products.
2. Core operating logic:
Once a loan enters the protocol, it’s split into FT and XT. GT is responsible for packaging the collateral, the debt, and the leveraged position into NFTs. That way, fixed term and fixed interest rates can be traded on-chain. I believe what’s truly hard here isn’t “lending,” but the following liquidity and pricing.
3. Key attributes:
Current total supply is 1 billion TMX, with an initial circulating supply of about 20%. The project has moved from the test stage into multi-chain expansion and the TGE phase. Official disclosures cover 7 chains and 20+ institutional partnerships. At the moment, the Chinese Creator tasks already have 28,873 participants, and community heat really has picked up.
4. Company profitability:
Here I’m more cautious. Term Structure Labs hasn’t publicly released a complete annual report in the traditional sense, so we can’t directly say “how much the company earns in a year.” On-chain data shows TermMax TVL is about $32.5 million, Active Loans about $22.1 million, and cumulative protocol revenue around $375,000, with the last 30 days about $16.7k.
So in my view, TermMax isn’t without revenue now—it already has a business closed loop, but the scale still isn’t big enough. After the TGE, what’s really worth watching isn’t how many TMX are emitted, but whether those $22.1 million in loans can keep growing, and whether this $16.7k revenue each month can gradually reach the million-dollar level.
9
10
827
·
--
Bullish
Verified
#dusk $DUSK @Dusk_Foundation
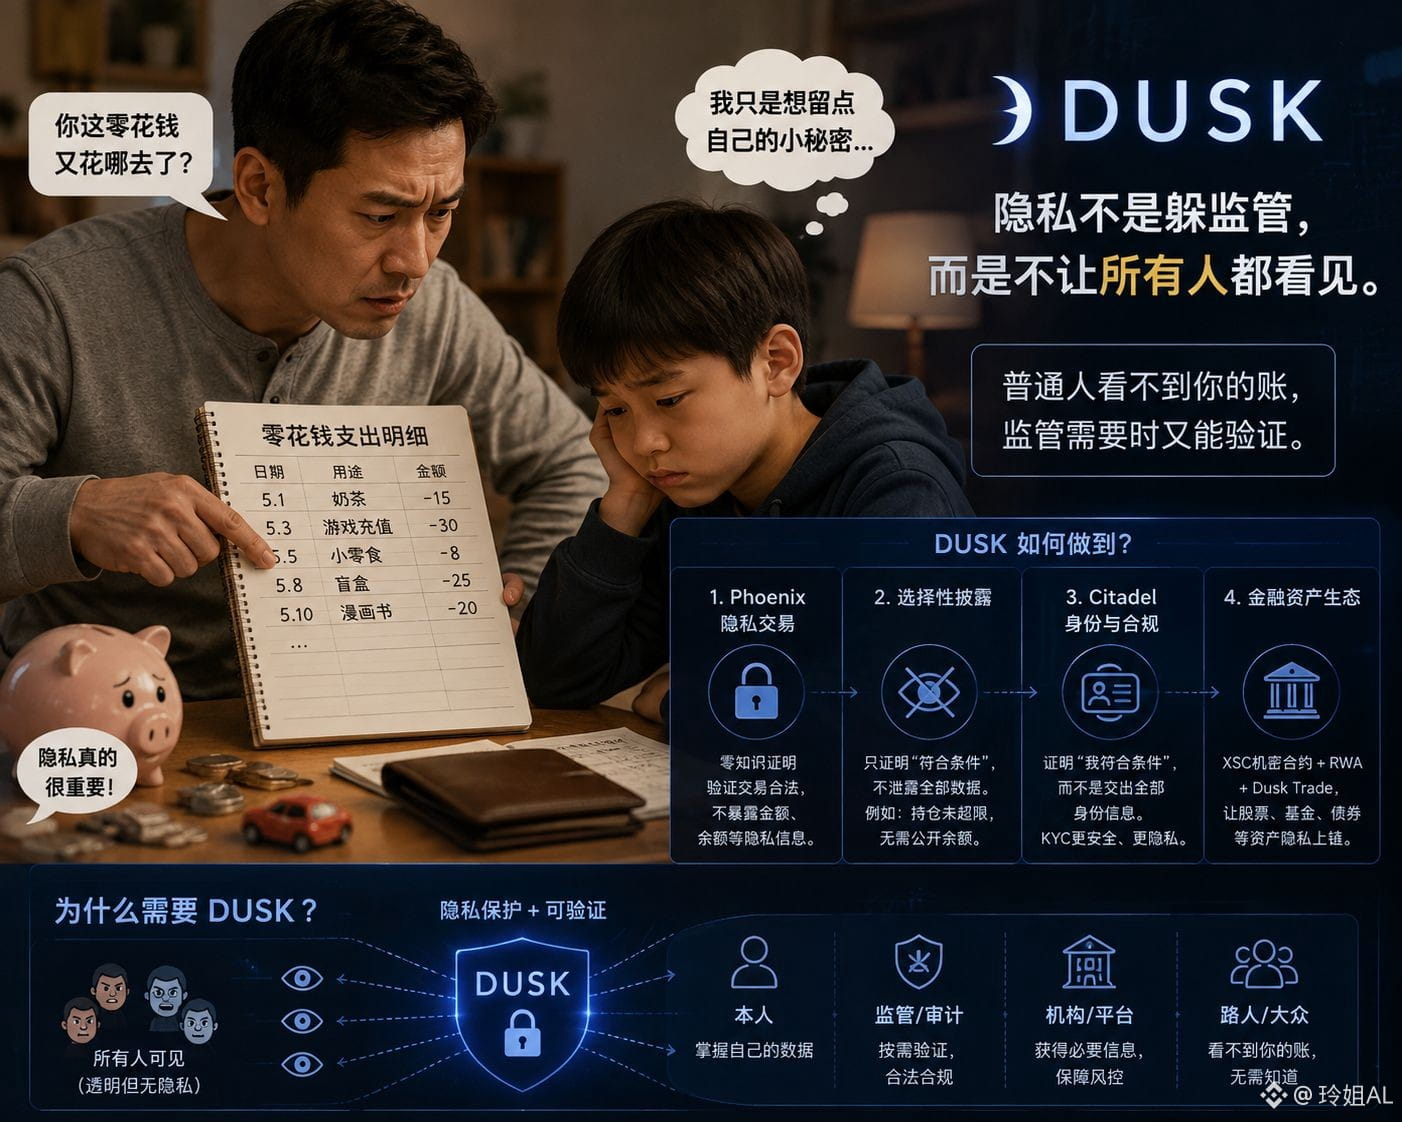
Brothers, has your pocket money ever been discovered? You work hard to save up a little money—then when your family asks, “Why have you been spending so much lately?”
That’s when I realized privacy really matters.
Back then, when I looked at blockchain too, it was the same—I thought transparency on-chain was great. Everyone can check it, and it feels fair.
But later I thought: if in the future stocks, funds, bonds, and RWA are all moved onto the chain, then whatever you bought, how much is in your account, and who you traded with—all of it becomes publicly visible to everyone. Would institutions really dare to put large amounts of capital in?
That’s also what I found interesting after re-researching DUSK recently.
What I care about isn’t just the two words “privacy,” but how it can still prove things after privacy.
First, Phoenix.
DUSK uses UTXOs and zero-knowledge proofs so that sensitive information like transaction amounts and balances isn’t directly revealed, but the network can still verify the transaction is valid and there’s no double-spending.
Second, selective disclosure.
For example, an audit asks: “Does your holdings exceed 1,000,000?” Traditional approaches might require handing over all account transaction records. What DUSK aims to do is prove only that “it does not exceed,” instead of exposing all financial data to others.
Third, Citadel.
KYC doesn’t necessarily mean handing over your entire ID and address. It emphasizes proving “I meet a certain requirement” while reducing unnecessary exposure of identity information.
Fourth, financial assets.
Phoenix handles transaction privacy, Citadel handles identity, and XSC handles confidential security contracts—then higher up it connects to RWA and Dusk Trade.
So now I think the real story of DUSK isn’t “I want to evade regulation.”
On the contrary, it’s this: ordinary people don’t need to look at your account, but when regulators need to, they can verify.
That’s what makes DUSK special in my view.
After all, as more and more assets move on-chain, the true scarce resource might not be transparency, but rather: who has the right to see what.
#dusk $DUSK @Dusk
Brothers, has your pocket money ever been discovered? You work hard to save up a little money—then when your family asks, “Why have you been spending so much lately?”
That’s when I realized privacy really matters.
Back then, when I looked at blockchain too, it was the same—I thought transparency on-chain was great. Everyone can check it, and it feels fair.
But later I thought: if in the future stocks, funds, bonds, and RWA are all moved onto the chain, then whatever you bought, how much is in your account, and who you traded with—all of it becomes publicly visible to everyone. Would institutions really dare to put large amounts of capital in?
That’s also what I found interesting after re-researching DUSK recently.
What I care about isn’t just the two words “privacy,” but how it can still prove things after privacy.
First, Phoenix.
DUSK uses UTXOs and zero-knowledge proofs so that sensitive information like transaction amounts and balances isn’t directly revealed, but the network can still verify the transaction is valid and there’s no double-spending.
Second, selective disclosure.
For example, an audit asks: “Does your holdings exceed 1,000,000?” Traditional approaches might require handing over all account transaction records. What DUSK aims to do is prove only that “it does not exceed,” instead of exposing all financial data to others.
Third, Citadel.
KYC doesn’t necessarily mean handing over your entire ID and address. It emphasizes proving “I meet a certain requirement” while reducing unnecessary exposure of identity information.
Fourth, financial assets.
Phoenix handles transaction privacy, Citadel handles identity, and XSC handles confidential security contracts—then higher up it connects to RWA and Dusk Trade.
So now I think the real story of DUSK isn’t “I want to evade regulation.”
On the contrary, it’s this: ordinary people don’t need to look at your account, but when regulators need to, they can verify.
That’s what makes DUSK special in my view.
After all, as more and more assets move on-chain, the true scarce resource might not be transparency, but rather: who has the right to see what.
13
12
885
·
--
Bullish
Verified
#termmax @termmax
Recently I went through TermMax again, and now I feel that the most worth watching in this project isn’t the words “fixed-rate lending and borrowing,” but the fact that it’s increasingly turning fixed-rate lending into a complete on-chain financial market.
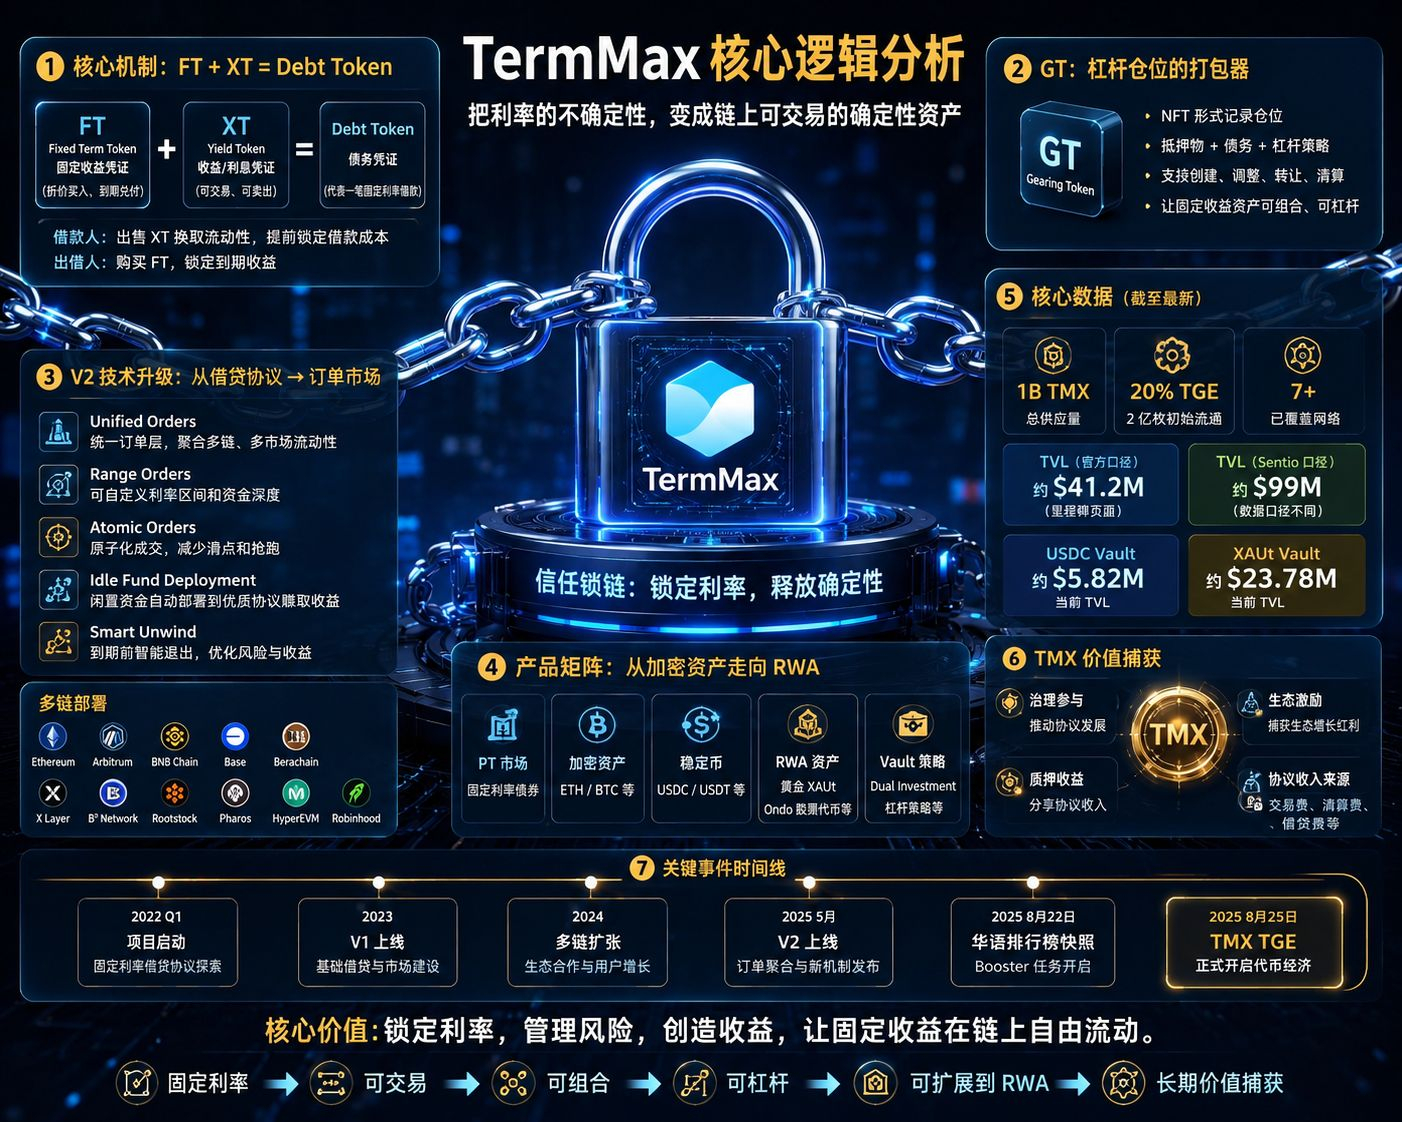
The whitepaper’s core is really three things:
FT, XT, and GT.
To put it simply, FT is like a zero-coupon bond that gets redeemed at maturity: you buy it below face value and get the face value back when it matures. XT is responsible for splitting principal and interest. GT then packages the collateral, the debt, and the leverage position into an NFT. The most critical point is:
1 FT + 1 XT = 1 Debt Token.
This way, both the borrower’s cost and the lender’s yield can be directly locked in at the moment of the transaction, without having to watch floating rates every day.
But what I’ve been noticing lately is that the real change is V2.
TermMax is no longer satisfied with “just creating a fixed-rate lending pool.” Instead, it’s expanding toward order aggregation, range orders, atomic orders, idle fund deployment, and smart unwind**.
Now the curve isn’t simply giving you an APR. Instead, it lets the Curator set the interest-rate range and the liquidity depth, then aggregates different orders together. Any funds that haven’t been borrowed can be temporarily deployed into Aave, Morpho, or Venus to earn floating yields, and then be rebalanced back when the orders are filled.
The latest product page has placed PT, ETH, BTC, Stable, and RWA into a unified market, and it has already launched lending/borrowing scenarios related to Ondo stock tokens.
Even gold XAUt has entered the Vault. The current Vault shows TVL of about $23.78 million; the USDC Vault is about $5.82 million.
So when I look at TermMax now, the biggest gap in my understanding isn’t whether it can “fix interest rates.”
This functionality has already been explained. What’s truly worth observing is:
whether it can turn fixed-rate lending into foundational infrastructure that is tradable, combinable, leverage-able, and finally able to support RWA assets.
And with the August 25 TMX TGE already confirmed, it makes me want to look at the data even more than at the marketing.
After TGE, what really needs to be validated is:
Has trading volume picked up? Is there real demand in the fixed-rate market? Is Vault capital continuing to grow? Can protocol fees grow alongside the asset scale?
#termmax @TermMax
Recently I went through TermMax again, and now I feel that the most worth watching in this project isn’t the words “fixed-rate lending and borrowing,” but the fact that it’s increasingly turning fixed-rate lending into a complete on-chain financial market.
The whitepaper’s core is really three things:
FT, XT, and GT.
To put it simply, FT is like a zero-coupon bond that gets redeemed at maturity: you buy it below face value and get the face value back when it matures. XT is responsible for splitting principal and interest. GT then packages the collateral, the debt, and the leverage position into an NFT. The most critical point is:
1 FT + 1 XT = 1 Debt Token.
This way, both the borrower’s cost and the lender’s yield can be directly locked in at the moment of the transaction, without having to watch floating rates every day.
But what I’ve been noticing lately is that the real change is V2.
TermMax is no longer satisfied with “just creating a fixed-rate lending pool.” Instead, it’s expanding toward order aggregation, range orders, atomic orders, idle fund deployment, and smart unwind**.
Now the curve isn’t simply giving you an APR. Instead, it lets the Curator set the interest-rate range and the liquidity depth, then aggregates different orders together. Any funds that haven’t been borrowed can be temporarily deployed into Aave, Morpho, or Venus to earn floating yields, and then be rebalanced back when the orders are filled.
The latest product page has placed PT, ETH, BTC, Stable, and RWA into a unified market, and it has already launched lending/borrowing scenarios related to Ondo stock tokens.
Even gold XAUt has entered the Vault. The current Vault shows TVL of about $23.78 million; the USDC Vault is about $5.82 million.
So when I look at TermMax now, the biggest gap in my understanding isn’t whether it can “fix interest rates.”
This functionality has already been explained. What’s truly worth observing is:
whether it can turn fixed-rate lending into foundational infrastructure that is tradable, combinable, leverage-able, and finally able to support RWA assets.
And with the August 25 TMX TGE already confirmed, it makes me want to look at the data even more than at the marketing.
After TGE, what really needs to be validated is:
Has trading volume picked up? Is there real demand in the fixed-rate market? Is Vault capital continuing to grow? Can protocol fees grow alongside the asset scale?
40
34
1.1k
·
--
Bullish
Verified
#dusk $DUSK @Dusk_Foundation
Brothers! Over these past few days I’ve been digging through DUSK one after another. The more I look ahead, the more I feel that the word “privacy” isn’t as important as people think.
Earlier, when we talked about Phoenix, what I understood was this: how to hide transactions.
Then as we go further to Zedger and XSC, it addresses: how financial assets can be issued, transferred, and operated while remaining in a privacy state.
But here’s the problem.
If all the data is hidden, how can others believe you? That’s the real hurdle financial institutions can’t get around. The logic of ordinary privacy coins is simple: I won’t let you see. But the financial market can’t work like that.
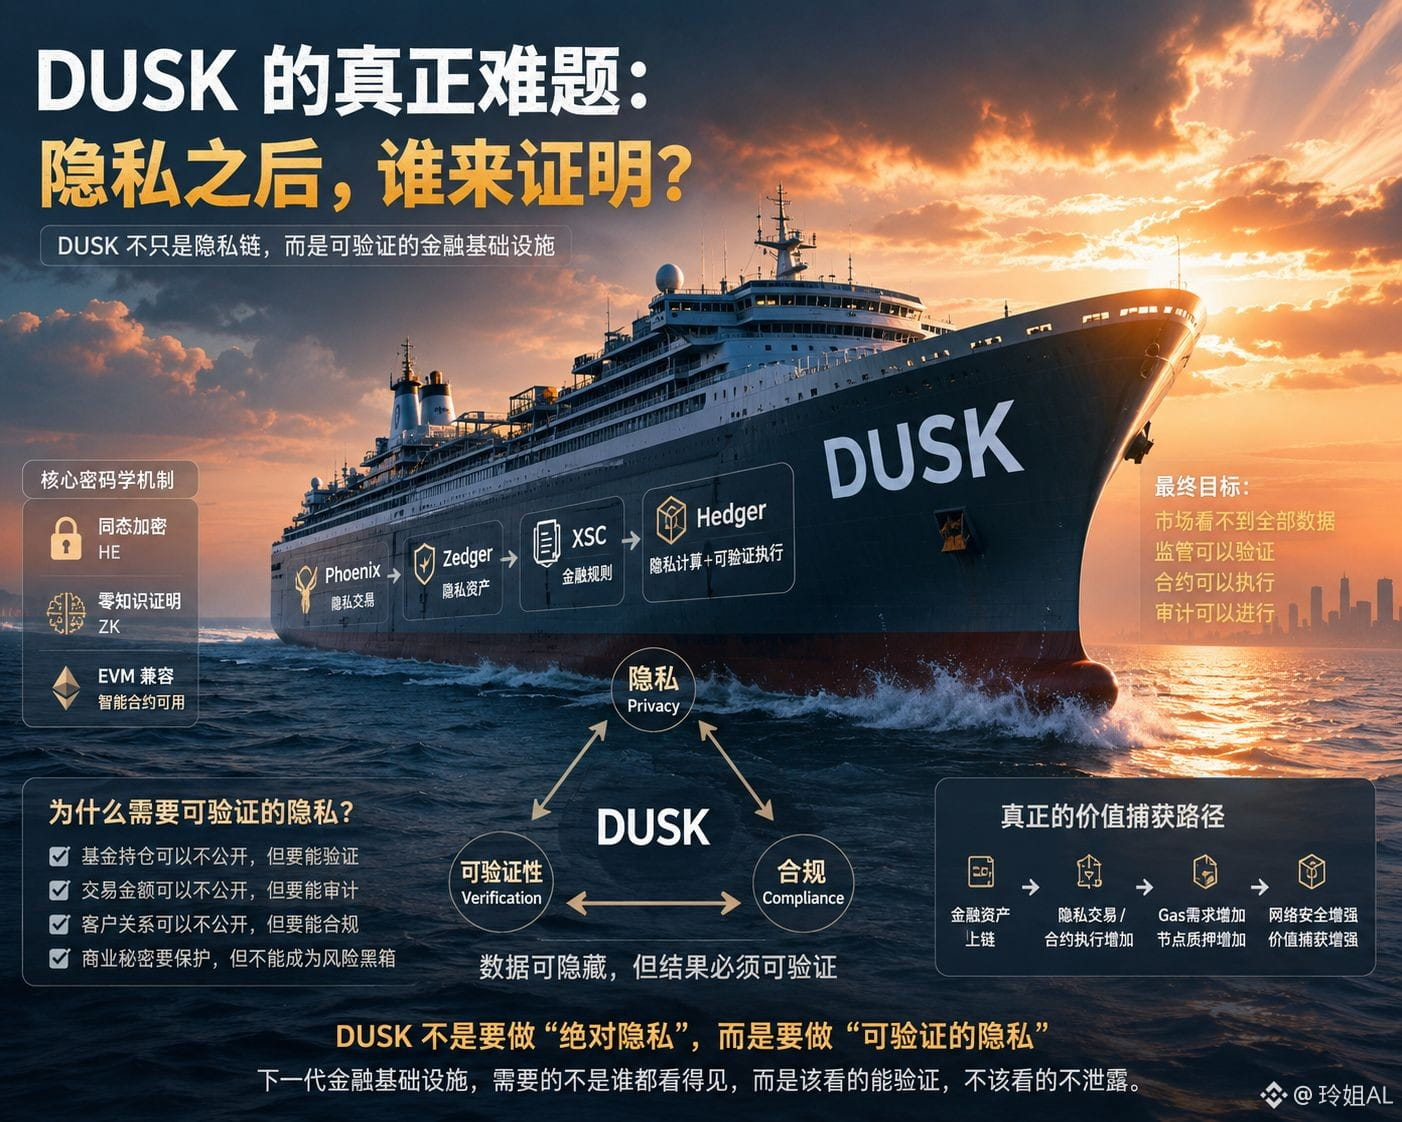
Fund holdings can be hidden. Transaction amounts can be hidden. Client relationships can be hidden. But regulation still needs to verify, audits still need to verify, and counterparties still need to confirm that you meet the rules.
So what’s truly interesting about DUSK’s architecture is that it reframes the question from: “How do you hide data?”
And then we push it further into: after hiding the data, how do you prove the result is real?
That’s where Phoenix’s ZK mechanism becomes crucial.
It doesn’t hide the verification along with everything else. Instead, it lets the network verify a proof: you don’t have to tell me all the raw data, but you must prove that this transaction follows the rules—no double-spending, and the asset source is valid.
By the time we reach the later DuskEVM, Hedger takes this idea even further into smart-contract computation—starting to explore cryptographic data involvement in computation, and then completing result verification through ZK.
At this point, the whole logic connects:
Phoenix: private transactions ↓ Zedger: private assets ↓ XSC: financial rules ↓ Hedger: private computation + verifiable execution
This is the biggest cognitive gap I see in DUSK right now.
What it truly wants to solve isn’t “making it so nobody can see anything.”
Instead, it creates a state that a financial institution might truly need:
The market can’t see all the data, regulators can verify, contracts can execute, and audits can be performed.
So I think the real “triangle relationship” of DUSK is actually:
Privacy × Verification × Compliance
Privacy is too strong, and yet it can’t be regulated.
Only by achieving “data can be hidden, but the result must be verifiable” does this chain have a chance to move from the privacy track into real financial infrastructure.
#dusk $DUSK @Dusk
Brothers! Over these past few days I’ve been digging through DUSK one after another. The more I look ahead, the more I feel that the word “privacy” isn’t as important as people think.
Earlier, when we talked about Phoenix, what I understood was this: how to hide transactions.
Then as we go further to Zedger and XSC, it addresses: how financial assets can be issued, transferred, and operated while remaining in a privacy state.
But here’s the problem.
If all the data is hidden, how can others believe you? That’s the real hurdle financial institutions can’t get around. The logic of ordinary privacy coins is simple: I won’t let you see. But the financial market can’t work like that.
Fund holdings can be hidden. Transaction amounts can be hidden. Client relationships can be hidden. But regulation still needs to verify, audits still need to verify, and counterparties still need to confirm that you meet the rules.
So what’s truly interesting about DUSK’s architecture is that it reframes the question from: “How do you hide data?”
And then we push it further into: after hiding the data, how do you prove the result is real?
That’s where Phoenix’s ZK mechanism becomes crucial.
It doesn’t hide the verification along with everything else. Instead, it lets the network verify a proof: you don’t have to tell me all the raw data, but you must prove that this transaction follows the rules—no double-spending, and the asset source is valid.
By the time we reach the later DuskEVM, Hedger takes this idea even further into smart-contract computation—starting to explore cryptographic data involvement in computation, and then completing result verification through ZK.
At this point, the whole logic connects:
Phoenix: private transactions ↓ Zedger: private assets ↓ XSC: financial rules ↓ Hedger: private computation + verifiable execution
This is the biggest cognitive gap I see in DUSK right now.
What it truly wants to solve isn’t “making it so nobody can see anything.”
Instead, it creates a state that a financial institution might truly need:
The market can’t see all the data, regulators can verify, contracts can execute, and audits can be performed.
So I think the real “triangle relationship” of DUSK is actually:
Privacy × Verification × Compliance
Privacy is too strong, and yet it can’t be regulated.
Only by achieving “data can be hidden, but the result must be verifiable” does this chain have a chance to move from the privacy track into real financial infrastructure.
36
26
1k
·
--
Bullish
Verified
#termmax @termmax
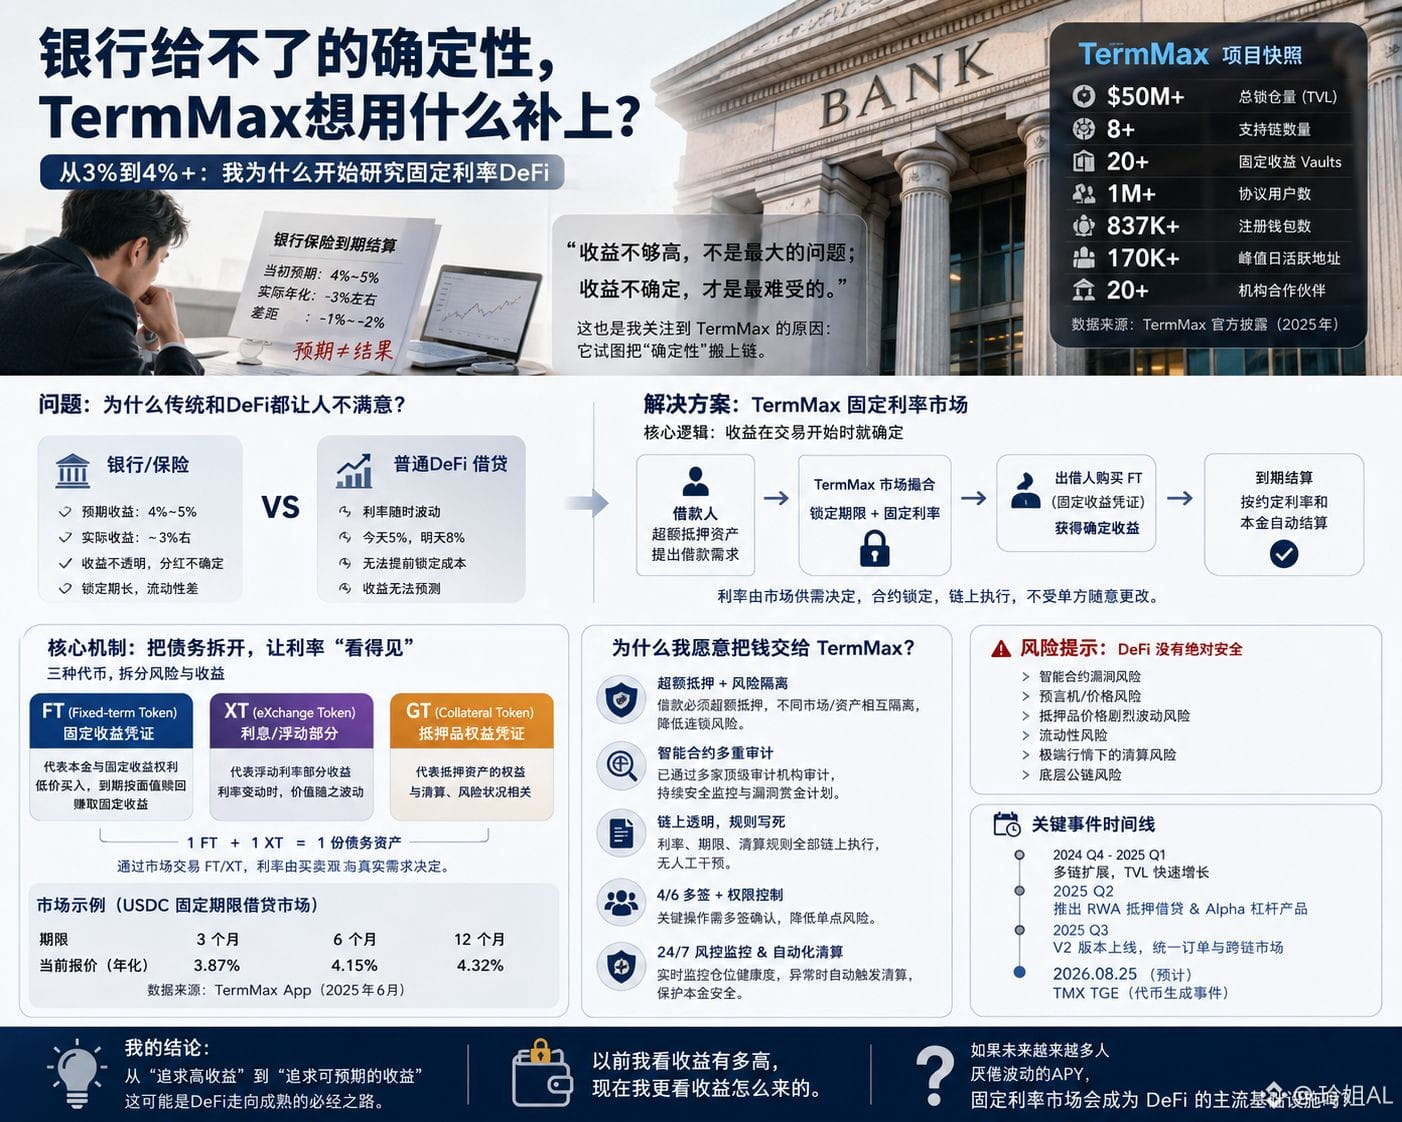
A few days ago, I came across something that really hit me. After watching a movie and $牛来 , I found that my bank insurance policy I’d bought earlier had matured. Back then, I was looking at “2.8% fixed interest rate + dividends,” thinking that under normal circumstances I should still be able to get around 4%-5%. But when the numbers were actually calculated, the annual rate was only about 3%.
The amount of money didn’t decrease, but the “return I saw back then” and the money I ultimately received aren’t the same thing. It honestly feels a bit unsettling.
It wasn’t until I started seeing TermMax on my feed these past few days that I suddenly paused and read it more carefully.
What attracts me most isn’t the high APY they advertise—it’s four words: “figure out returns first.”
One of the biggest problems with traditional DeFi is that interest rates keep fluctuating. If it’s 5% today, tomorrow it might be 8%. When the market gets tense, borrowing costs jump immediately. You basically have no idea how much you’ll actually be able to take home a few months from now.
TermMax takes a different approach.
It turns borrowing into a market with fixed terms and fixed interest rates.
Borrowers take loans using over-collateralized assets, with the term and interest rate determined when trading begins;
Lenders, meanwhile, earn the corresponding returns through the fixed-term market.
The official team has now expanded this model across multiple chains, including Ethereum, Arbitrum, BNB Chain, and Base. The website shows that TVL is over $50 million.
As I dug further into the whitepaper and mechanisms, I realized what’s truly interesting about it. TermMax isn’t the kind of logic where the project team comes out and says:
“Don’t worry, I guarantee you 5% annualized.”
That’s not the way it works.
It breaks a fixed-term debt into different Tokens, then uses market pricing to set the interest rate.
In simple terms: the principal and future returns are separated and traded.
So the 4% and 5% you see aren’t just slogans—they’re market prices that are re-determined based on the term, the assets, supply and demand, and risk.
On-chain, you can even already see specific markets. For example, in some USDC fixed-term markets, the current quote is around 4%; and there are also RWA-related assets used as collateral.
But what makes me more confident is that it doesn’t only focus on “how to make returns higher.” Borrowing requires over-collateralization, the Vault has a limit on borrowing capacity, and different markets are isolated from each other. The official team also discloses smart contract audits and ongoing security monitoring. $BR $GRVT
#termmax @TermMax
A few days ago, I came across something that really hit me. After watching a movie and $牛来 , I found that my bank insurance policy I’d bought earlier had matured. Back then, I was looking at “2.8% fixed interest rate + dividends,” thinking that under normal circumstances I should still be able to get around 4%-5%. But when the numbers were actually calculated, the annual rate was only about 3%.
The amount of money didn’t decrease, but the “return I saw back then” and the money I ultimately received aren’t the same thing. It honestly feels a bit unsettling.
It wasn’t until I started seeing TermMax on my feed these past few days that I suddenly paused and read it more carefully.
What attracts me most isn’t the high APY they advertise—it’s four words: “figure out returns first.”
One of the biggest problems with traditional DeFi is that interest rates keep fluctuating. If it’s 5% today, tomorrow it might be 8%. When the market gets tense, borrowing costs jump immediately. You basically have no idea how much you’ll actually be able to take home a few months from now.
TermMax takes a different approach.
It turns borrowing into a market with fixed terms and fixed interest rates.
Borrowers take loans using over-collateralized assets, with the term and interest rate determined when trading begins;
Lenders, meanwhile, earn the corresponding returns through the fixed-term market.
The official team has now expanded this model across multiple chains, including Ethereum, Arbitrum, BNB Chain, and Base. The website shows that TVL is over $50 million.
As I dug further into the whitepaper and mechanisms, I realized what’s truly interesting about it. TermMax isn’t the kind of logic where the project team comes out and says:
“Don’t worry, I guarantee you 5% annualized.”
That’s not the way it works.
It breaks a fixed-term debt into different Tokens, then uses market pricing to set the interest rate.
In simple terms: the principal and future returns are separated and traded.
So the 4% and 5% you see aren’t just slogans—they’re market prices that are re-determined based on the term, the assets, supply and demand, and risk.
On-chain, you can even already see specific markets. For example, in some USDC fixed-term markets, the current quote is around 4%; and there are also RWA-related assets used as collateral.
But what makes me more confident is that it doesn’t only focus on “how to make returns higher.” Borrowing requires over-collateralization, the Vault has a limit on borrowing capacity, and different markets are isolated from each other. The official team also discloses smart contract audits and ongoing security monitoring. $BR $GRVT
36
35
736
·
--
Bearish
Verified
#dusk $DUSK @Dusk_Foundation
Sometime past 3 a.m., I was just lying there scrolling Twitter. Lately I’ve been a bit numb to all the airdrops and various projects.
One minute it’s AI, the next it’s RWA, and then there’s some “revolutionary privacy protocol.” After seeing so much, it’s really easy to just let it slide.
Then I came across DUSK, and I actually paused.
To be honest, on first glance it didn’t feel that explosive. There wasn’t that full-screen “changing finance” or “redefining the public chain” kind of hype. Instead, it kept talking about privacy, compliance, and tokenized financial assets—kinda old-school topics.
But the more I looked, the more I felt this might not be meant to tell a story to retail investors.
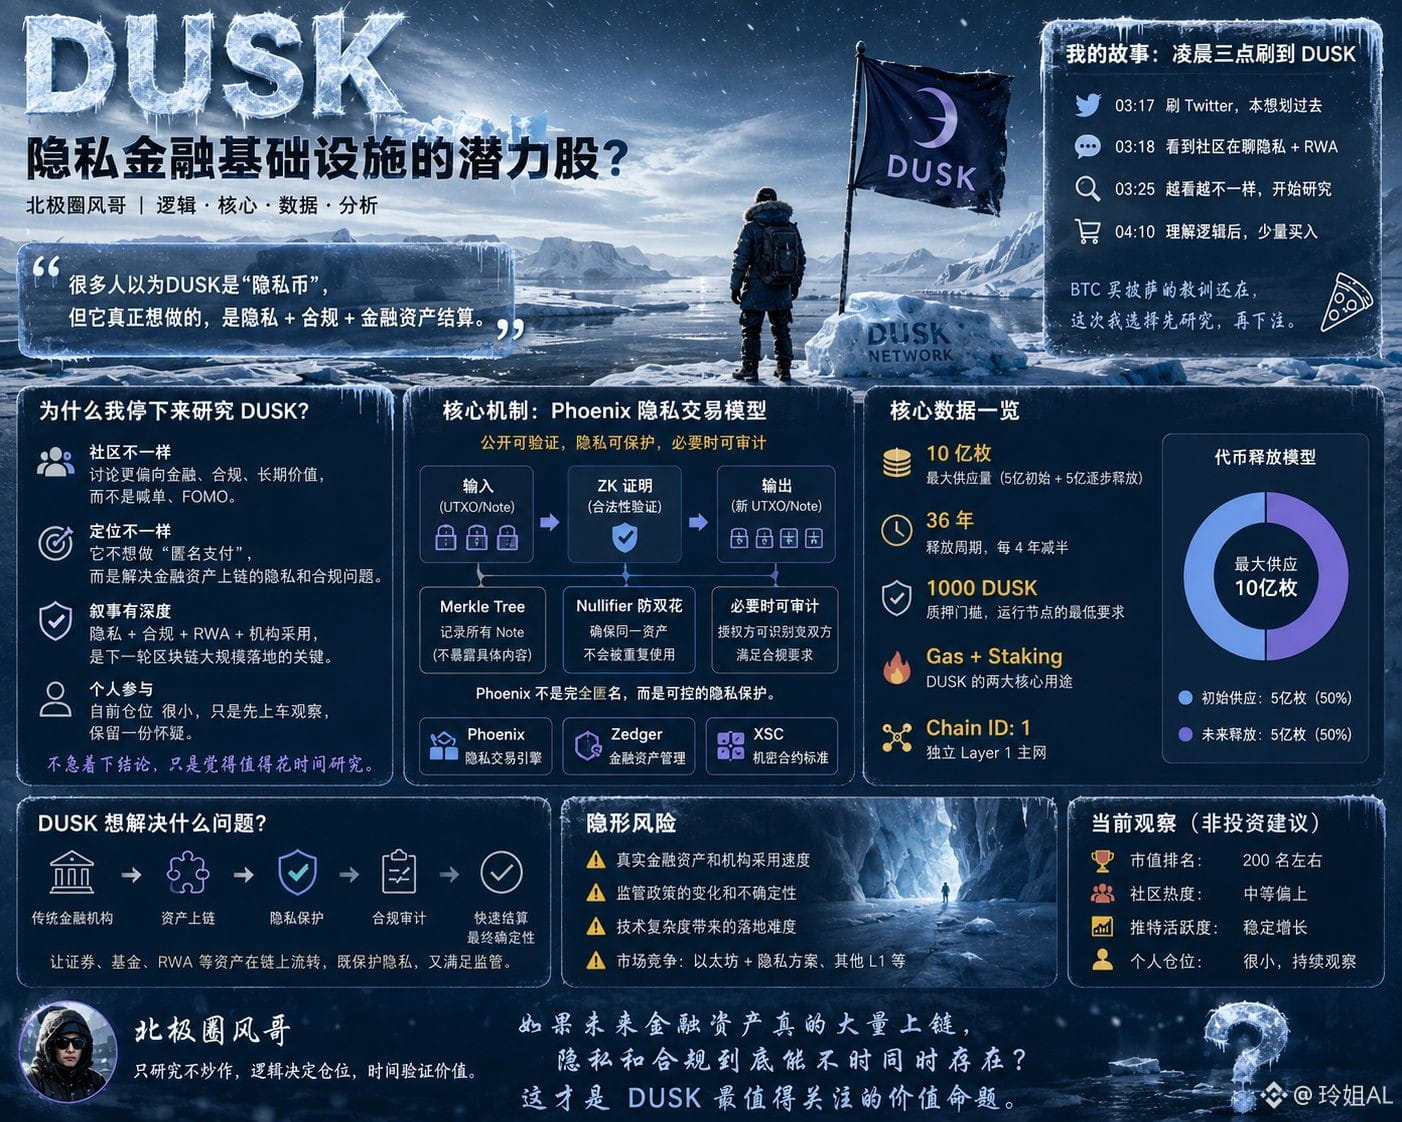
DUSK itself is an independent Layer 1.
And it isn’t really trying to solve the simple “anonymize transfers” problem. What it’s really focused on is a headache that comes up once securities, funds, and RWA assets are put on-chain:
Assets can be publicly verifiable, but privacy can’t be completely thrown out in the open.
That’s kind of interesting.
The logic of ordinary public chains is simple: the more transparent the data, the easier it is to verify.
But financial institutions are different.
If you force them to make their holdings, trading counterparties, and asset balances fully public, they probably won’t want to put anything on-chain at all. But if you hide everything, regulators obviously won’t accept it either.
What DUSK is doing is finding room in that gap.
Phoenix handles privacy transactions, Zedger leans toward the financial-asset side, and XSC tries to embed privacy and compliance rules into smart contracts.
Right now, I’m not in a hurry to add more.
After so many years in crypto, I’ve heard too many “next-generation financial infrastructure” pitches.
Whether the tech can run is one thing.
Whether real securities, funds, and RWAs are willing to move their assets over is another.
So for me, I’m more like observing an experiment by watching DUSK.
If, in the future, financial assets really do get put on-chain at scale, can privacy and compliance truly coexist at the same time?
That question may be worth watching more than whether DUSK itself goes up.
I’m already out of DUSK—let’s see if it will pump!
#dusk $DUSK @Dusk
Sometime past 3 a.m., I was just lying there scrolling Twitter. Lately I’ve been a bit numb to all the airdrops and various projects.
One minute it’s AI, the next it’s RWA, and then there’s some “revolutionary privacy protocol.” After seeing so much, it’s really easy to just let it slide.
Then I came across DUSK, and I actually paused.
To be honest, on first glance it didn’t feel that explosive. There wasn’t that full-screen “changing finance” or “redefining the public chain” kind of hype. Instead, it kept talking about privacy, compliance, and tokenized financial assets—kinda old-school topics.
But the more I looked, the more I felt this might not be meant to tell a story to retail investors.
DUSK itself is an independent Layer 1.
And it isn’t really trying to solve the simple “anonymize transfers” problem. What it’s really focused on is a headache that comes up once securities, funds, and RWA assets are put on-chain:
Assets can be publicly verifiable, but privacy can’t be completely thrown out in the open.
That’s kind of interesting.
The logic of ordinary public chains is simple: the more transparent the data, the easier it is to verify.
But financial institutions are different.
If you force them to make their holdings, trading counterparties, and asset balances fully public, they probably won’t want to put anything on-chain at all. But if you hide everything, regulators obviously won’t accept it either.
What DUSK is doing is finding room in that gap.
Phoenix handles privacy transactions, Zedger leans toward the financial-asset side, and XSC tries to embed privacy and compliance rules into smart contracts.
Right now, I’m not in a hurry to add more.
After so many years in crypto, I’ve heard too many “next-generation financial infrastructure” pitches.
Whether the tech can run is one thing.
Whether real securities, funds, and RWAs are willing to move their assets over is another.
So for me, I’m more like observing an experiment by watching DUSK.
If, in the future, financial assets really do get put on-chain at scale, can privacy and compliance truly coexist at the same time?
That question may be worth watching more than whether DUSK itself goes up.
I’m already out of DUSK—let’s see if it will pump!
55
36
946
·
--
Bullish
Red packets are ready🧧 Put your speed together!
I’ve prepared 100u red packets—wishing everyone a happy summer vacation
May good fortune and profits come to you both—wishing you a great run of行情📈
Red packets are ready🧧 Put your speed together!
I’ve prepared 100u red packets—wishing everyone a happy summer vacation
May good fortune and profits come to you both—wishing you a great run of行情📈
I’ve prepared 100u red packets—wishing everyone a happy summer vacation
May good fortune and profits come to you both—wishing you a great run of行情📈
3.9k
11
223
3.9k
·
--
Bullish
Partly True
TermMax, I just want to figure out 3 things
I recently dug back into TermMax.
In the end, there are really only 3 questions worth looking at.
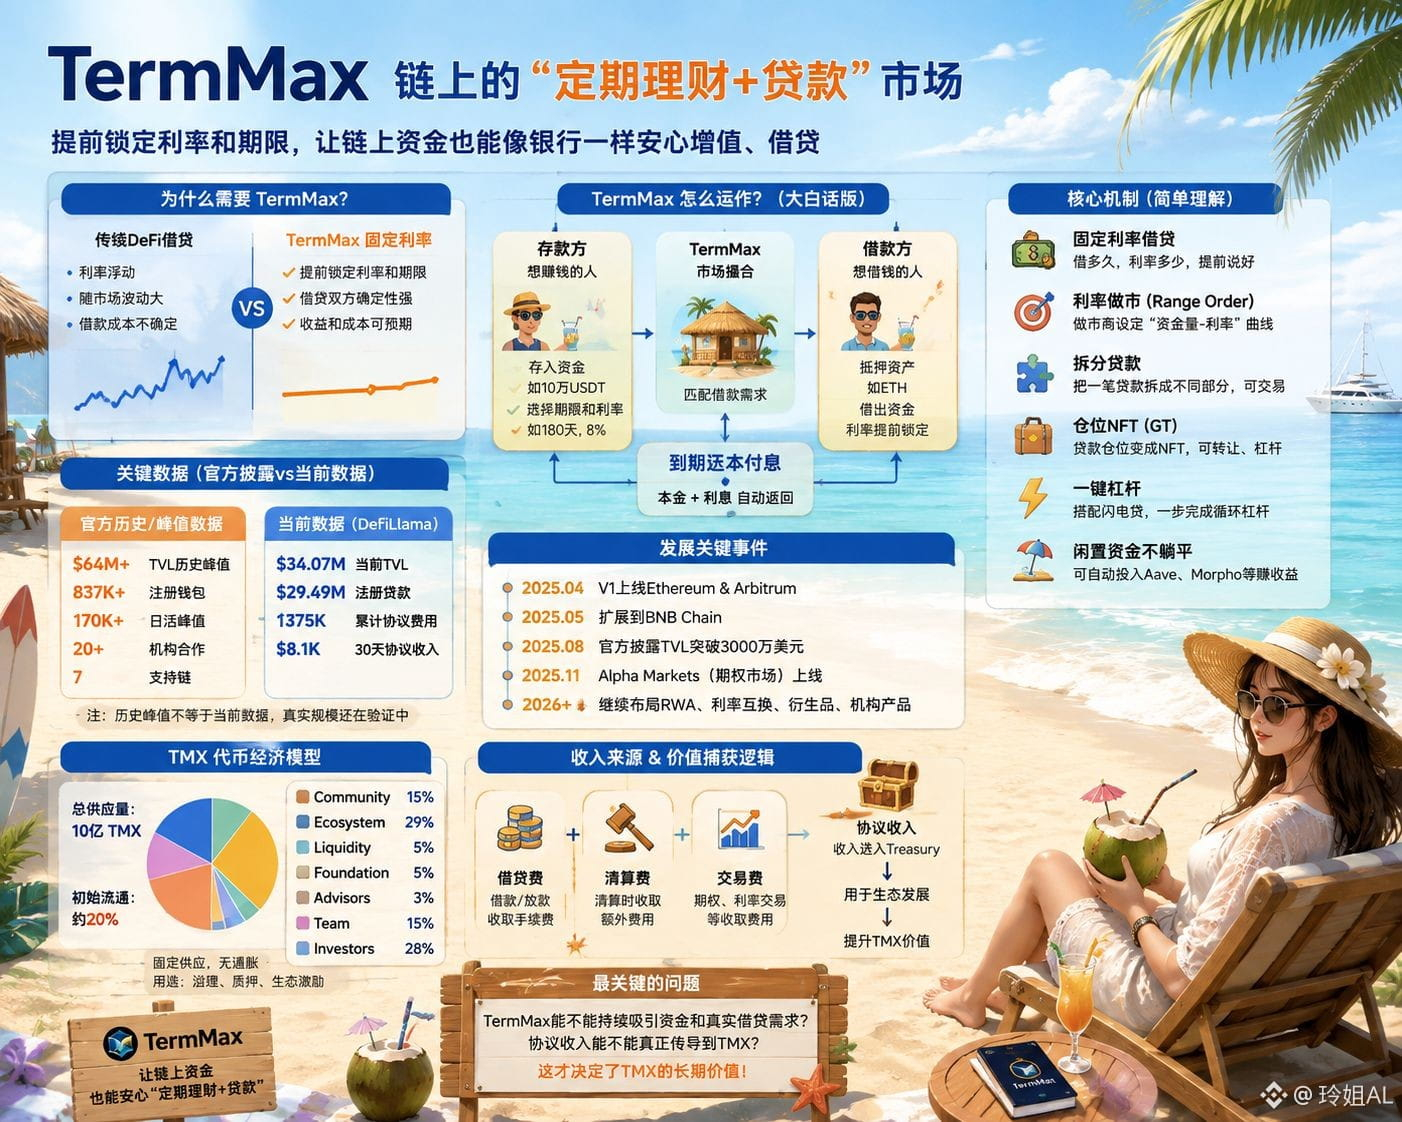
First: what problem does it actually solve?
Simply put, it lets the money on the blockchain “lock in interest in advance.”
In many DeFi lending markets, interest rates move with the market chaos. If you borrow today at, say, 5%, then after a market fluctuation it might jump to 10% a few days later—your borrowing cost can’t be calculated ahead of time.
TermMax’s idea is very straightforward: lock in the borrowing duration, the amount borrowed, and the interest rate—up front.
Lenders know exactly how much they will earn, and borrowers know how much they must repay at maturity.
So it’s not just another Aave. It aims to make on-chain lending work more like traditional finance: term deposits + bonds + a lending market. The official whitepaper’s core is fixed interest rates and fixed terms, then it splits this setup into tradable components using FT, XT, and an AMM.
Second: is there truly real capital being used?
You can’t just look at project marketing here.
TermMax did, in the past, produce solid historical performance. The official whitepaper disclosed more than $64 million in TVL, 837,000 registered wallets, and a peak of 170,000 daily active users.
But those are historical highs—you can’t treat them as today’s numbers.
According to DeFiLlama, TermMax’s TVL is around $31.25 million, active loans about $27.2 million, protocol revenue over the last 30 days about $199,000, and cumulative revenue about $379,000. Also, the TVL over the past 30 days has dropped by roughly 7.1%.
Third: once TermMax grows big, how much can TMX actually capture?
That’s the part I’m most focused on right now.
TermMax has already gone beyond just lending.
The timeline is pretty clear: V1 launched on Ethereum and Arbitrum in April 2025, expanded to BNB in May, TVL broke $30 million in August, and Alpha Markets launched in November. In 2026, its roadmap continues toward RWA, interest-rate swaps, options, derivatives, and institutional structured products.
In other words, it’s imagining an ever-bigger market.
But TMX has a fixed supply of only 1 billion tokens, with initial circulating supply around 20%. In the whitepaper’s design, Treasury revenue mainly comes from FT/XT transaction fees, borrowing protocol fees, settlement fees, and so on; TMX takes on governance, staking, and ecosystem incentive roles, and part of the Treasury funds can also be used for staking rewards.
Only if all three questions can be proven to work out does the TermMax story truly hold.
#termmax @termmax
TermMax, I just want to figure out 3 things
I recently dug back into TermMax.
In the end, there are really only 3 questions worth looking at.
First: what problem does it actually solve?
Simply put, it lets the money on the blockchain “lock in interest in advance.”
In many DeFi lending markets, interest rates move with the market chaos. If you borrow today at, say, 5%, then after a market fluctuation it might jump to 10% a few days later—your borrowing cost can’t be calculated ahead of time.
TermMax’s idea is very straightforward: lock in the borrowing duration, the amount borrowed, and the interest rate—up front.
Lenders know exactly how much they will earn, and borrowers know how much they must repay at maturity.
So it’s not just another Aave. It aims to make on-chain lending work more like traditional finance: term deposits + bonds + a lending market. The official whitepaper’s core is fixed interest rates and fixed terms, then it splits this setup into tradable components using FT, XT, and an AMM.
Second: is there truly real capital being used?
You can’t just look at project marketing here.
TermMax did, in the past, produce solid historical performance. The official whitepaper disclosed more than $64 million in TVL, 837,000 registered wallets, and a peak of 170,000 daily active users.
But those are historical highs—you can’t treat them as today’s numbers.
According to DeFiLlama, TermMax’s TVL is around $31.25 million, active loans about $27.2 million, protocol revenue over the last 30 days about $199,000, and cumulative revenue about $379,000. Also, the TVL over the past 30 days has dropped by roughly 7.1%.
Third: once TermMax grows big, how much can TMX actually capture?
That’s the part I’m most focused on right now.
TermMax has already gone beyond just lending.
The timeline is pretty clear: V1 launched on Ethereum and Arbitrum in April 2025, expanded to BNB in May, TVL broke $30 million in August, and Alpha Markets launched in November. In 2026, its roadmap continues toward RWA, interest-rate swaps, options, derivatives, and institutional structured products.
In other words, it’s imagining an ever-bigger market.
But TMX has a fixed supply of only 1 billion tokens, with initial circulating supply around 20%. In the whitepaper’s design, Treasury revenue mainly comes from FT/XT transaction fees, borrowing protocol fees, settlement fees, and so on; TMX takes on governance, staking, and ecosystem incentive roles, and part of the Treasury funds can also be used for staking rewards.
Only if all three questions can be proven to work out does the TermMax story truly hold.
#termmax @TermMax
42
33
668
·
--
Bearish
Verified
Brothers! Figure out the drop for the 25th—#tge —then farm more points. It might be a big furry bear (a whale). Don’t miss out, everyone.
The hedged trades have already been reverse-rugged. Everyone, tell me—should we cut our losses and sell!
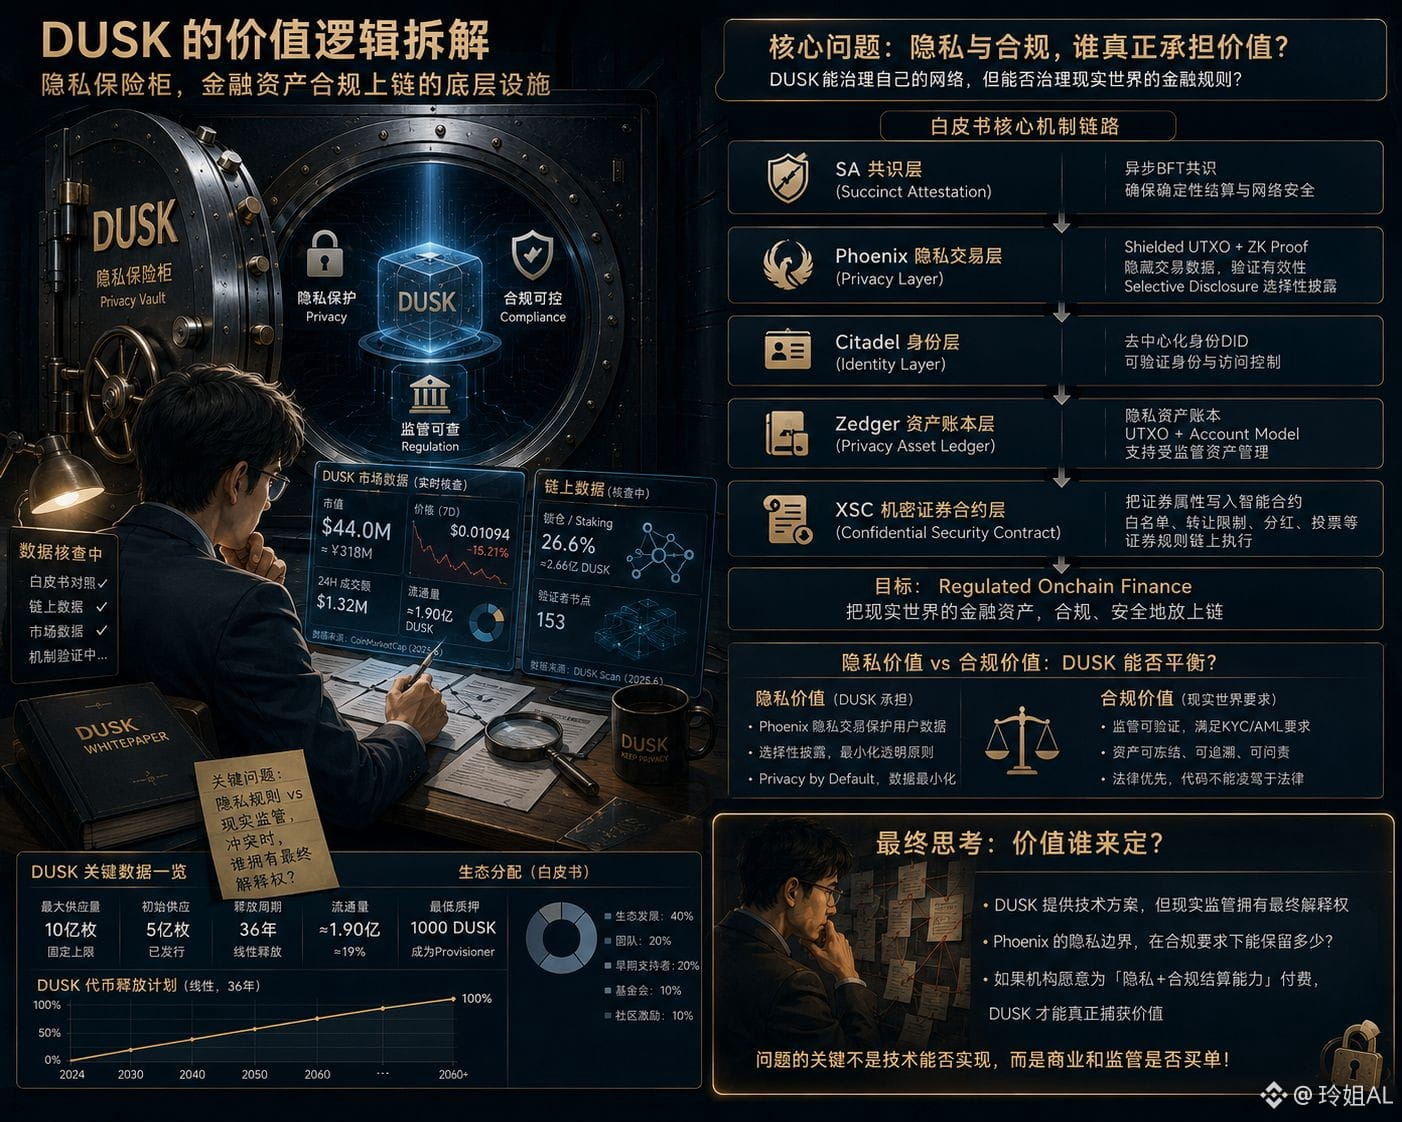
For these past two days I’ve been repeatedly going through the DUSK whitepaper. At first, I also treated it like a normal privacy-track project.
But the more I break it down, the more I feel this project is kind of interesting—and also kind of awkward.
Right now DUSK’s market cap is only in the tens of millions USD range.
With a billion tokens issued, half the initial supply is given, and the other half is planned to be released over 36 years. DUSK isn’t just a Governance Token; it also handles Gas + Staking, becoming the Provisioner’s minimum required stake of 1000 DUSK.
With a token worth only a few tens of millions, what value is it truly carrying?
Continuing to dig through the whitepaper, I found that DUSK’s core isn’t “anonymity,” but financial privacy.
Phoenix uses Shielded UTXO + ZK Proof. Verifiers can confirm that a transaction is valid, but they don’t need to see the full transaction details. Combined with Selective Disclosure, when needed it can prove identity and the relationship between the assets.
Now that’s where it gets interesting.
Because what financial institutions need is never “nobody can see anything.” It’s that unrelated people can’t see, while regulators and authorized parties can see when they’re supposed to.
Digging further, Zedger is actually more like a Privacy Asset Ledger, and XSC—that is, Confidential Security Contract—puts securities-like attributes into smart contracts: whitelists, holding limits, transfer rules, dividends, voting, and so on.
Only then did I realize: what DUSK really wants to do isn’t a privacy coin, but a Regulated Asset + Privacy Settlement.
But this is exactly where I’m most torn.
DUSK has its own Consensus, Staking, and Execution Layer, so it can govern on-chain rules.
However, in the real world there’s another layer called Jurisdiction.
If regulators require disclosure, freeze assets, or even require specific assets to execute compliance restrictions, then how much can on-chain Governance actually decide?
So when I look at DUSK now, I’m not really concerned whether it can still talk about “privacy.”
What I really want to know is:
Can the privacy protected by Phoenix ultimately turn into a Settlement Premium that institutions are willing to pay for?
If it can, then a market cap of a few tens of millions might genuinely be not expensive.
If it can’t, then all these beautiful cryptography mechanisms may ultimately just be “technical assets” mentioned in the whitepaper.
#dusk $DUSK @Dusk_Foundation
Brothers! Figure out the drop for the 25th—#tge —then farm more points. It might be a big furry bear (a whale). Don’t miss out, everyone.
The hedged trades have already been reverse-rugged. Everyone, tell me—should we cut our losses and sell!
For these past two days I’ve been repeatedly going through the DUSK whitepaper. At first, I also treated it like a normal privacy-track project.
But the more I break it down, the more I feel this project is kind of interesting—and also kind of awkward.
Right now DUSK’s market cap is only in the tens of millions USD range.
With a billion tokens issued, half the initial supply is given, and the other half is planned to be released over 36 years. DUSK isn’t just a Governance Token; it also handles Gas + Staking, becoming the Provisioner’s minimum required stake of 1000 DUSK.
With a token worth only a few tens of millions, what value is it truly carrying?
Continuing to dig through the whitepaper, I found that DUSK’s core isn’t “anonymity,” but financial privacy.
Phoenix uses Shielded UTXO + ZK Proof. Verifiers can confirm that a transaction is valid, but they don’t need to see the full transaction details. Combined with Selective Disclosure, when needed it can prove identity and the relationship between the assets.
Now that’s where it gets interesting.
Because what financial institutions need is never “nobody can see anything.” It’s that unrelated people can’t see, while regulators and authorized parties can see when they’re supposed to.
Digging further, Zedger is actually more like a Privacy Asset Ledger, and XSC—that is, Confidential Security Contract—puts securities-like attributes into smart contracts: whitelists, holding limits, transfer rules, dividends, voting, and so on.
Only then did I realize: what DUSK really wants to do isn’t a privacy coin, but a Regulated Asset + Privacy Settlement.
But this is exactly where I’m most torn.
DUSK has its own Consensus, Staking, and Execution Layer, so it can govern on-chain rules.
However, in the real world there’s another layer called Jurisdiction.
If regulators require disclosure, freeze assets, or even require specific assets to execute compliance restrictions, then how much can on-chain Governance actually decide?
So when I look at DUSK now, I’m not really concerned whether it can still talk about “privacy.”
What I really want to know is:
Can the privacy protected by Phoenix ultimately turn into a Settlement Premium that institutions are willing to pay for?
If it can, then a market cap of a few tens of millions might genuinely be not expensive.
If it can’t, then all these beautiful cryptography mechanisms may ultimately just be “technical assets” mentioned in the whitepaper.
#dusk $DUSK @Dusk
50
32
668
·
--
Bullish
Verified
Damn it! Brothers, the $DUSK that was hedged in advance got rug-pulled. Now I’m a bit scared. I wonder if it will blow up! The airdrop $KII that I grabbed from #ALPHA a couple of days ago was a miss—my mindset was wrong. Now I only have 15u left!
Lately I’ve been digging into DUSK again, and I think the biggest place this project can be misread by the market isn’t about whether it has privacy tech. It’s whether what’s in the whitepaper matches what’s actually implemented in the publicity.
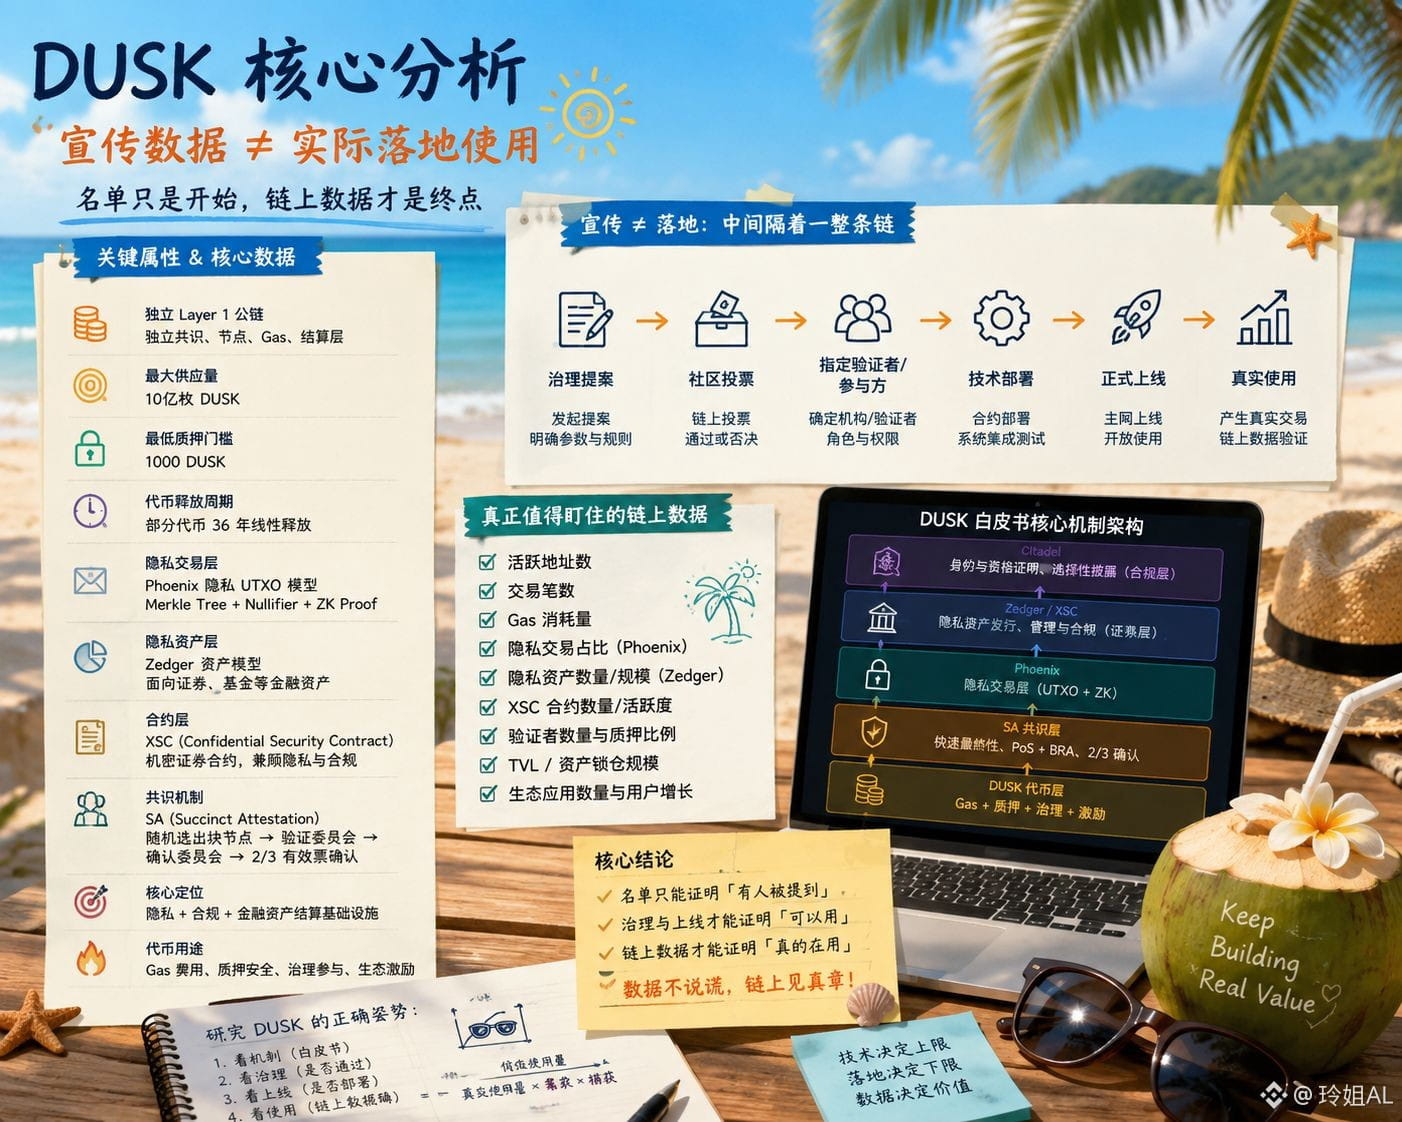
First, let’s look at hard data: DUSK is an independent Layer 1, with a maximum supply of 1 billion coins. The minimum staking threshold is 1000 DUSK, and part of the token release schedule lasts up to 36 years.
Technically, it really does have something.
The core of the whitepaper isn’t just simple anonymity—it’s Phoenix + Zedger + XSC.
Phoenix uses privacy UTXOs, Merkle Trees, Nullifiers, and zero-knowledge proofs to hide sensitive information like transaction amounts and asset ownership, while also proving that the assets truly exist and haven’t been double-spent.
Zedger pushes further into financial assets, putting the logic for issuing, transferring, redeeming, and other operations of security-type assets into a privacy model.
And what XSC solves is a more practical problem: once security assets are put on-chain, how to satisfy both privacy and regulation at the same time.
So what DUSK truly wants to do isn’t “another ZEC.” It’s a privacy-focused financial settlement infrastructure.
But this is exactly where the biggest knowledge gap shows up.
Just because the technology can do it ≠ the financial business is already live.
The institutions, asset lists, and partnership rosters from the project’s promotion—I won’t treat them as real usage numbers directly.
Actual deployment still needs to move forward:
Governance proposals → community voting → designated validators/participants → technical deployment—official go-live—real transactions.
And even going live isn’t enough.
In the end, you still have to look at whether there are active addresses on-chain: number of transactions, Gas consumption, asset size, and validator participation.
That’s what I care about most with DUSK right now.
The whitepaper answers “can it be built.” Governance answers “can it be launched.” And only on-chain data answers “is anyone actually using it.”
So the list ≠ usage, partnerships ≠ revenue, and technical completion ≠ a commercial closed loop.
If in the future Phoenix, Zedger, and XSC are truly used heavily by financial assets, then DUSK’s Gas and staking demand might form real value capture.
By then, it won’t just be a “privacy concept coin.”
#dusk @Dusk_Foundation
Damn it! Brothers, the $DUSK that was hedged in advance got rug-pulled. Now I’m a bit scared. I wonder if it will blow up! The airdrop $KII that I grabbed from #ALPHA a couple of days ago was a miss—my mindset was wrong. Now I only have 15u left!
Lately I’ve been digging into DUSK again, and I think the biggest place this project can be misread by the market isn’t about whether it has privacy tech. It’s whether what’s in the whitepaper matches what’s actually implemented in the publicity.
First, let’s look at hard data: DUSK is an independent Layer 1, with a maximum supply of 1 billion coins. The minimum staking threshold is 1000 DUSK, and part of the token release schedule lasts up to 36 years.
Technically, it really does have something.
The core of the whitepaper isn’t just simple anonymity—it’s Phoenix + Zedger + XSC.
Phoenix uses privacy UTXOs, Merkle Trees, Nullifiers, and zero-knowledge proofs to hide sensitive information like transaction amounts and asset ownership, while also proving that the assets truly exist and haven’t been double-spent.
Zedger pushes further into financial assets, putting the logic for issuing, transferring, redeeming, and other operations of security-type assets into a privacy model.
And what XSC solves is a more practical problem: once security assets are put on-chain, how to satisfy both privacy and regulation at the same time.
So what DUSK truly wants to do isn’t “another ZEC.” It’s a privacy-focused financial settlement infrastructure.
But this is exactly where the biggest knowledge gap shows up.
Just because the technology can do it ≠ the financial business is already live.
The institutions, asset lists, and partnership rosters from the project’s promotion—I won’t treat them as real usage numbers directly.
Actual deployment still needs to move forward:
Governance proposals → community voting → designated validators/participants → technical deployment—official go-live—real transactions.
And even going live isn’t enough.
In the end, you still have to look at whether there are active addresses on-chain: number of transactions, Gas consumption, asset size, and validator participation.
That’s what I care about most with DUSK right now.
The whitepaper answers “can it be built.” Governance answers “can it be launched.” And only on-chain data answers “is anyone actually using it.”
So the list ≠ usage, partnerships ≠ revenue, and technical completion ≠ a commercial closed loop.
If in the future Phoenix, Zedger, and XSC are truly used heavily by financial assets, then DUSK’s Gas and staking demand might form real value capture.
By then, it won’t just be a “privacy concept coin.”
#dusk @Dusk
100
70
1.9k
·
--
Bullish
Yu Jie is actually pretty good, really!
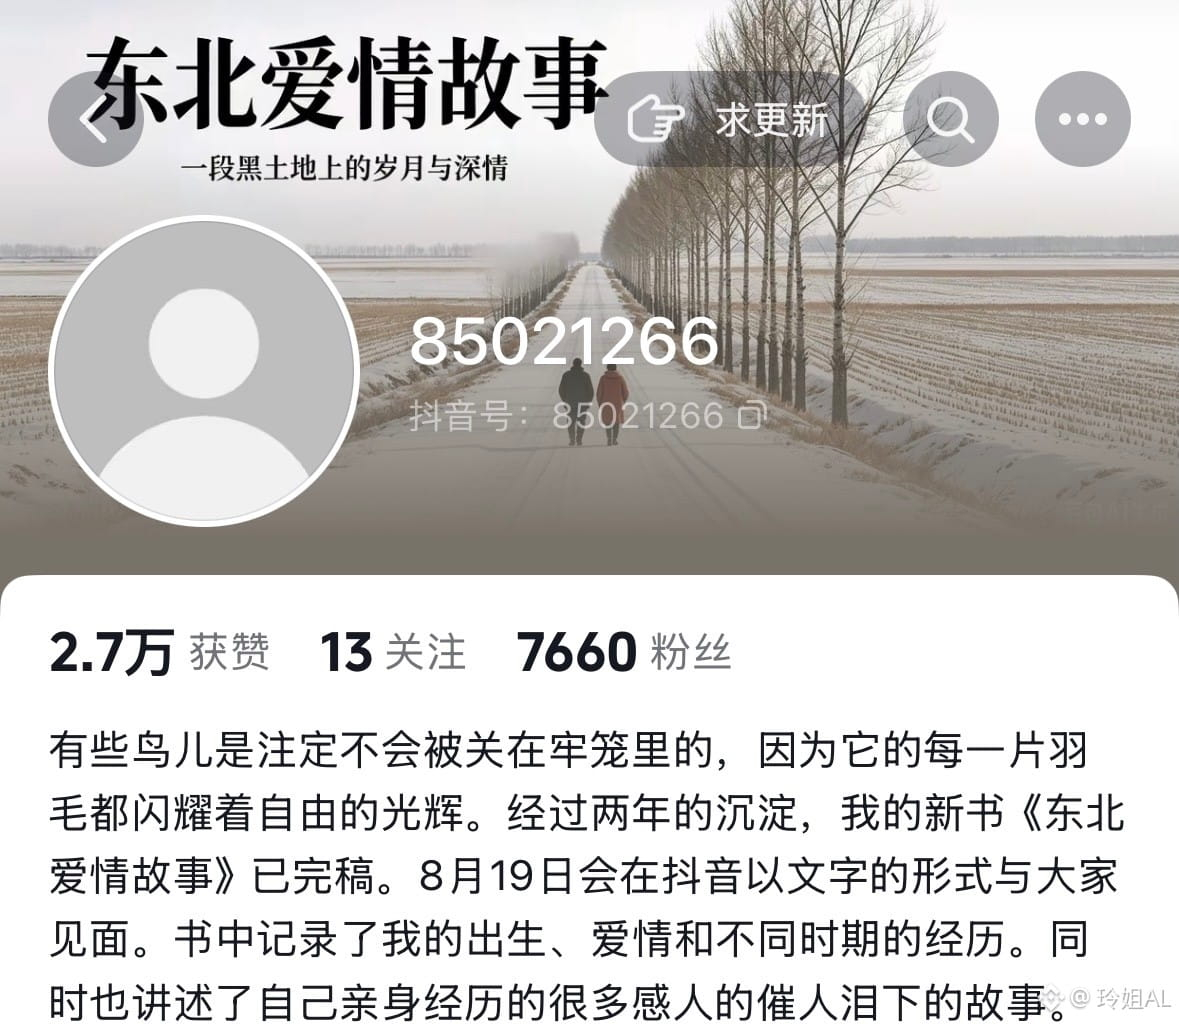
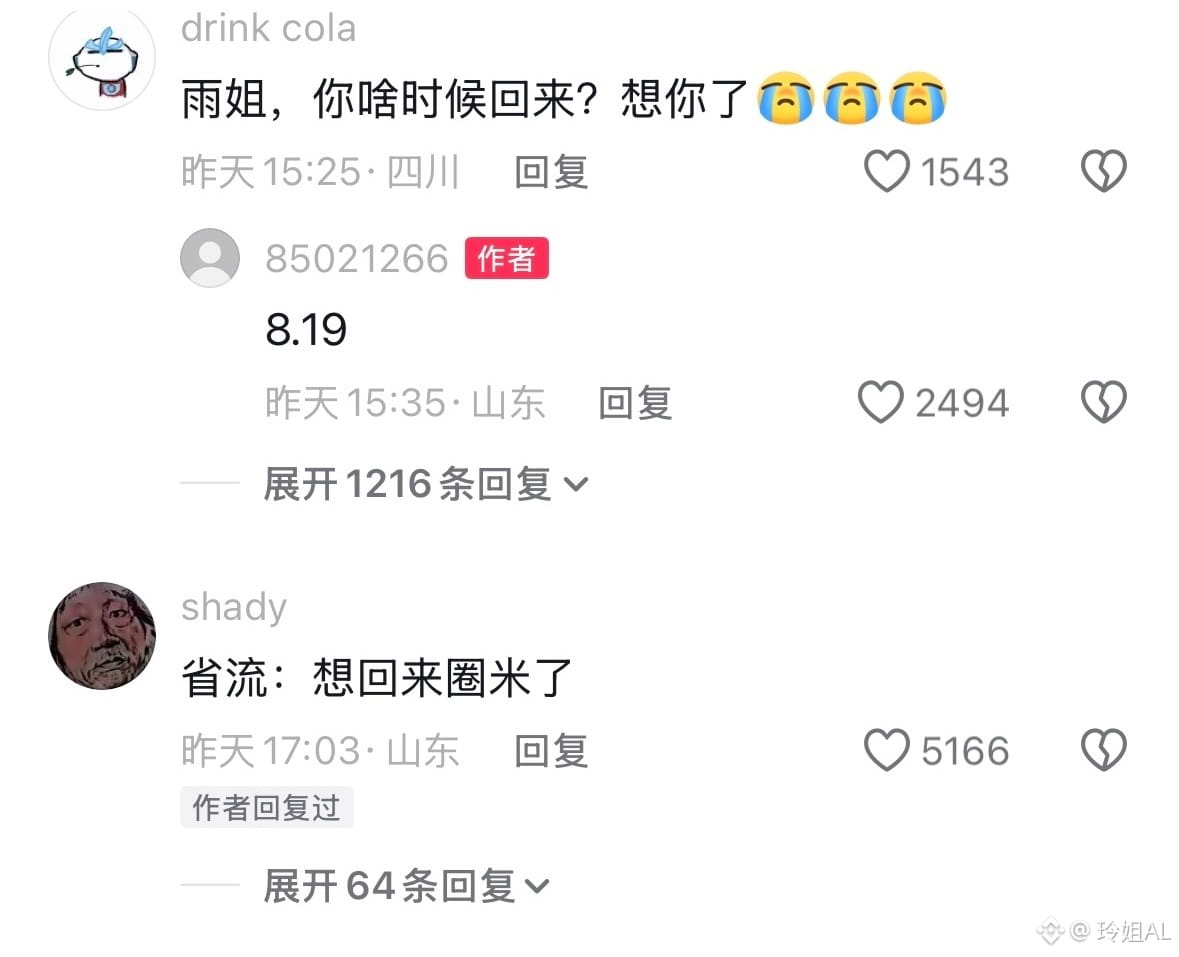
Northeast Yu Jie has been permanently banned for good.
Yesterday, Yu Jie herself returned to social media in the name of her new book, *Northeast Love Stories*, carrying the new book—only to have all platforms block her again overnight within less than 48 hours. $BTC $ETH $SOL
Northeast Yu Jie has been permanently banned for good.
Yesterday, Yu Jie herself returned to social media in the name of her new book, *Northeast Love Stories*, carrying the new book—only to have all platforms block her again overnight within less than 48 hours. $BTC $ETH $SOL
1
6
465
·
--
Bullish
Always presenting an image of being honest and plainspoken, yet secretly he’s so霸气. I really didn’t expect that…#COW24小时上涨55.77% #BNB链将激活Pasteur硬分叉 #沙特PIF披露持有1.541亿股SpaceX $BTC $ETH $SOL
Always presenting an image of being honest and plainspoken, yet secretly he’s so霸气. I really didn’t expect that…#COW24小时上涨55.77% #BNB链将激活Pasteur硬分叉 #沙特PIF披露持有1.541亿股SpaceX $BTC $ETH $SOL
1
2
371
·
--
Bullish
Brothers! We’re screwed. The #ALPHA that was grabbed yesterday for $KII 40 blades didn’t run, and now we only have 25 blades left. The bigger-picture mindset failed, huh!
Brothers, is there still hope? The dusk used for hedging was also reverse-rugged—now I’m a bit scared.
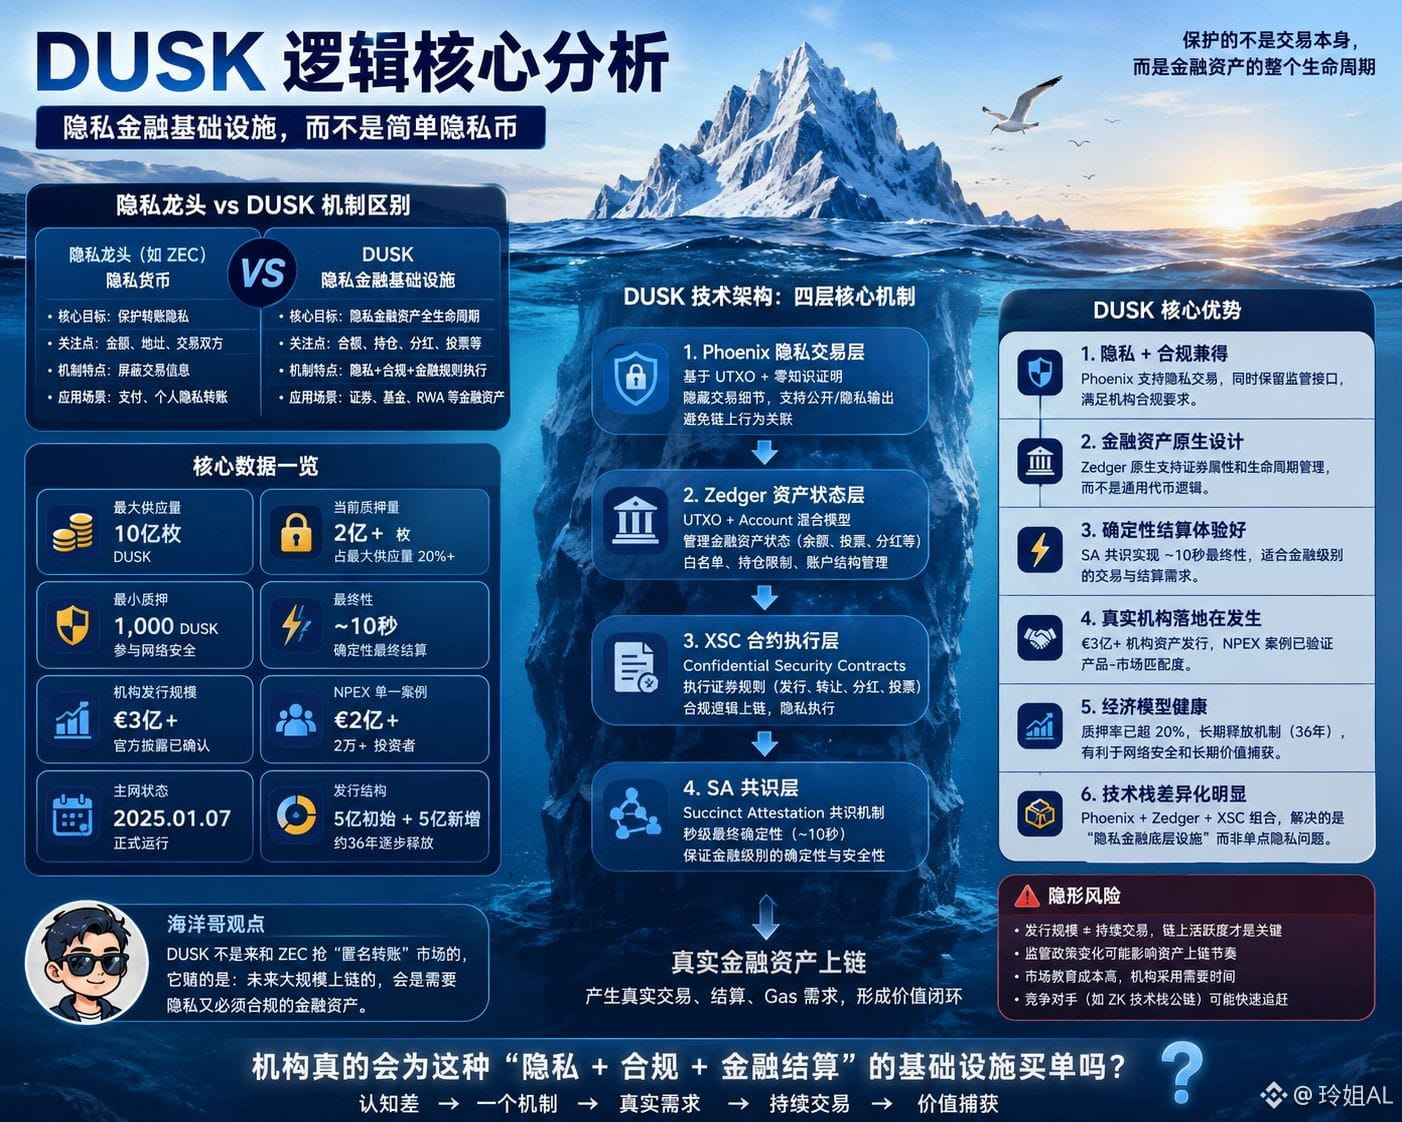
Recently I dug back into DUSK, and I found a place that’s pretty easy for the market to be misled: once you see Phoenix and zero-knowledge proofs, people immediately lump it together with privacy “blue chips” like ZEC.
But I think this comparison is only half right.
ZEC’s core value is “privacy coin”—it mainly focuses on hiding transaction information when users transfer, such as the amount and addresses. DUSK, on the other hand, is clearly more like “privacy financial infrastructure.” It aims to enable privacy transactions after securities, funds, and RWA are put on-chain—while still supporting financial rules like whitelists, holding limits, dividends, and voting.
That’s the biggest mechanism difference.
DUSK isn’t just hiding transactions. It processes privacy transactions with Phoenix, manages the state of financial assets via Zedger, and finally executes securities rules with XSC. In plain terms: ZEC is more like protecting the “privacy of money,” while DUSK is protecting the “privacy of the entire lifecycle of financial assets.”
The data is also interesting.
DUSK’s maximum supply is 1 billion coins. Currently, more than 200 million DUSK are already participating in staking—about 20%+ of the max supply. The official disclosed issuance size of institutional assets has exceeded 300 million euros, a single NPEX case is over 200 million euros, and there are more than 20,000 investors.
So I think DUSK’s real advantage isn’t “being more anonymous than the privacy leader.” It’s that it puts privacy, compliance, securities issuance, and on-chain settlement into a single underlying mechanism.
Of course, the risks are obvious too: 300 million euros in issuance sounds big, but issuance ≠ ongoing trading, and it also doesn’t mean DUSK will generate Gas revenue at the same scale.
So when I look at DUSK now, I’m actually less concerned about whether it can become the next ZEC.
What I really want to know is: when will these real financial assets truly form continuous on-chain trading and fee generation?
Once this step runs, then the DUSK story can really be said to begin.
#dusk $DUSK @Dusk_Foundation
Brothers! We’re screwed. The #ALPHA that was grabbed yesterday for $KII 40 blades didn’t run, and now we only have 25 blades left. The bigger-picture mindset failed, huh!
Brothers, is there still hope? The dusk used for hedging was also reverse-rugged—now I’m a bit scared.
Recently I dug back into DUSK, and I found a place that’s pretty easy for the market to be misled: once you see Phoenix and zero-knowledge proofs, people immediately lump it together with privacy “blue chips” like ZEC.
But I think this comparison is only half right.
ZEC’s core value is “privacy coin”—it mainly focuses on hiding transaction information when users transfer, such as the amount and addresses. DUSK, on the other hand, is clearly more like “privacy financial infrastructure.” It aims to enable privacy transactions after securities, funds, and RWA are put on-chain—while still supporting financial rules like whitelists, holding limits, dividends, and voting.
That’s the biggest mechanism difference.
DUSK isn’t just hiding transactions. It processes privacy transactions with Phoenix, manages the state of financial assets via Zedger, and finally executes securities rules with XSC. In plain terms: ZEC is more like protecting the “privacy of money,” while DUSK is protecting the “privacy of the entire lifecycle of financial assets.”
The data is also interesting.
DUSK’s maximum supply is 1 billion coins. Currently, more than 200 million DUSK are already participating in staking—about 20%+ of the max supply. The official disclosed issuance size of institutional assets has exceeded 300 million euros, a single NPEX case is over 200 million euros, and there are more than 20,000 investors.
So I think DUSK’s real advantage isn’t “being more anonymous than the privacy leader.” It’s that it puts privacy, compliance, securities issuance, and on-chain settlement into a single underlying mechanism.
Of course, the risks are obvious too: 300 million euros in issuance sounds big, but issuance ≠ ongoing trading, and it also doesn’t mean DUSK will generate Gas revenue at the same scale.
So when I look at DUSK now, I’m actually less concerned about whether it can become the next ZEC.
What I really want to know is: when will these real financial assets truly form continuous on-chain trading and fee generation?
Once this step runs, then the DUSK story can really be said to begin.
#dusk $DUSK @Dusk
83
54
691
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BinanceHadAlreadyCovered$6BofHackLoss
381 views
8 Discussing
Binance Says It Has Already Covered $6 Billion of Hack Loss
Binance News
·37 Likes
·18.6k views
FBIConfirmsNorthKoreaIsResponsibleForBinanceCryptoHack
1,011 views
23 Discussing
BinanceSAFUFundTransferCompleted7499BTC
57,235 views
1,042 Discussing