
Polymarket’s $200M trades allegedly suspected of insider trading
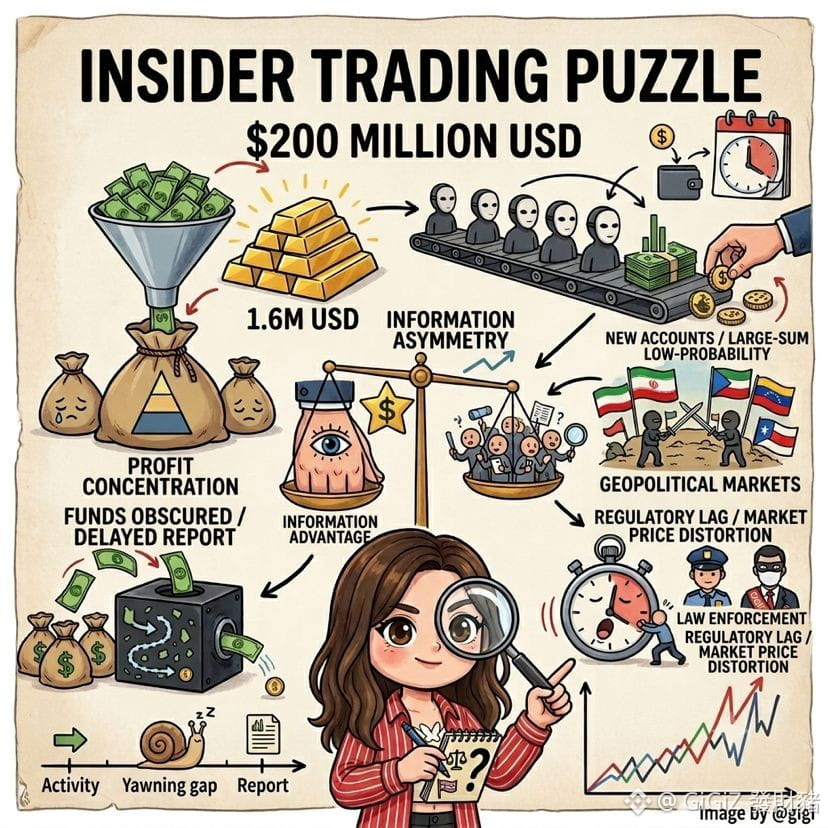
Polysights marked around 34,000 potential insider-trading transactions from August 2025 to June 2026. In the first half of this year, the suspicious amount was about $200 million. The most noticeable abnormal growth was in markets related to geopolitics and war.
The patterns are extremely consistent: newly created accounts, low-probability entries, large bets. In 57% of the related wallets, the accounts were created less than 24 hours before the trades.
Across 38 linked addresses, bets were placed in 90 geopolitics markets related to Iran and Venezuela. The win rate was 98%, for total profits of $1.6 million. All withdrawals went to the same充值 address.
A 98% win rate is statistically almost impossible to be luck. This isn’t a difference in analytical ability—it’s information asymmetry.
Yesterday I wrote about the World Cup with 31 BTC—where I said the transparency of prediction markets is selective. This dataset makes the issue clearer. On-chain activity can be traced, but after funds are mixed, the source of the money is obscured. By the time institutions like Polysights flag it, the whole cycle may already be over—months have passed.
The concentration of profits also tells a story: the top 1% of wallets take more than half of the returns. A healthy prediction market should be the “wisdom of the crowd” competing through a dispersed structure. Once it becomes this kind of setup, fundamentally it’s a small group with an information advantage extracting money from retail traders.
Polymarket has turned nearly 100 wallets over to law enforcement. Kalshi strengthened identity checks and restricted political candidates and athletes from participating in related markets. This direction is right, but the timing is clearly lagging behind the problem. Insider trading appears to have started as early as August 2025, while the data report was released in 2026—an entire one-year window.
The core value proposition of prediction markets is aggregating real information into price signals. Information advantages are reasonable, but information from public analysis and from insider information are two different things. If this line gets blurred, the purpose of market pricing itself is lost.
Regulatory gaps won’t be solved simply because platforms voluntarily cooperate with law enforcement. $200 million is only what has been flagged—how much more hasn’t been flagged is anyone’s guess.
DYOR Not investment advice
Polysights marked around 34,000 potential insider-trading transactions from August 2025 to June 2026. In the first half of this year, the suspicious amount was about $200 million. The most noticeable abnormal growth was in markets related to geopolitics and war.
The patterns are extremely consistent: newly created accounts, low-probability entries, large bets. In 57% of the related wallets, the accounts were created less than 24 hours before the trades.
Across 38 linked addresses, bets were placed in 90 geopolitics markets related to Iran and Venezuela. The win rate was 98%, for total profits of $1.6 million. All withdrawals went to the same充值 address.
A 98% win rate is statistically almost impossible to be luck. This isn’t a difference in analytical ability—it’s information asymmetry.
Yesterday I wrote about the World Cup with 31 BTC—where I said the transparency of prediction markets is selective. This dataset makes the issue clearer. On-chain activity can be traced, but after funds are mixed, the source of the money is obscured. By the time institutions like Polysights flag it, the whole cycle may already be over—months have passed.
The concentration of profits also tells a story: the top 1% of wallets take more than half of the returns. A healthy prediction market should be the “wisdom of the crowd” competing through a dispersed structure. Once it becomes this kind of setup, fundamentally it’s a small group with an information advantage extracting money from retail traders.
Polymarket has turned nearly 100 wallets over to law enforcement. Kalshi strengthened identity checks and restricted political candidates and athletes from participating in related markets. This direction is right, but the timing is clearly lagging behind the problem. Insider trading appears to have started as early as August 2025, while the data report was released in 2026—an entire one-year window.
The core value proposition of prediction markets is aggregating real information into price signals. Information advantages are reasonable, but information from public analysis and from insider information are two different things. If this line gets blurred, the purpose of market pricing itself is lost.
Regulatory gaps won’t be solved simply because platforms voluntarily cooperate with law enforcement. $200 million is only what has been flagged—how much more hasn’t been flagged is anyone’s guess.
DYOR Not investment advice