
Bullish on $MU : The memory supercycle isn’t peaking — it’s just getting stronger.
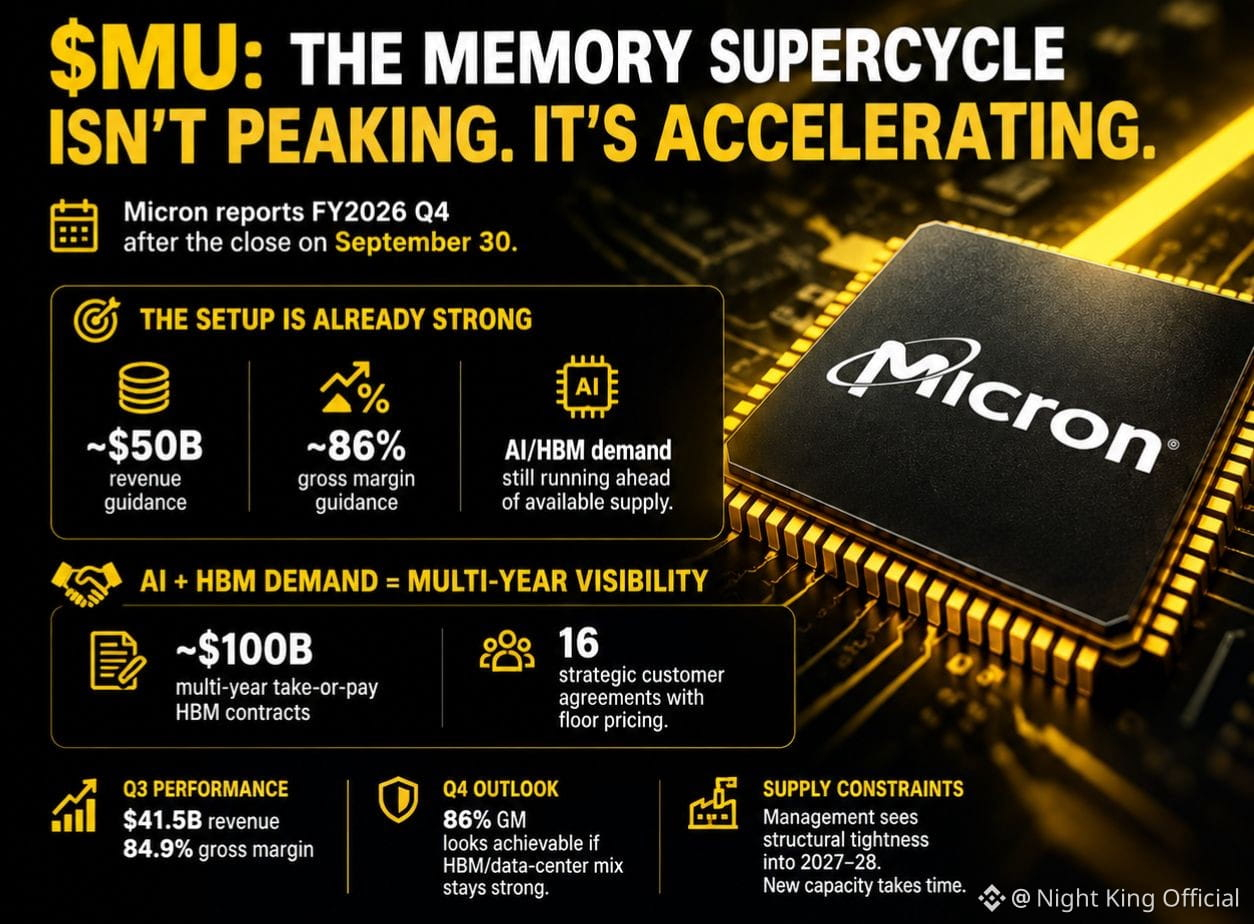
MU drops FY2026 Q4 numbers after close on Sep 30. Guidance already sits at $50B revenue and 86% gross margin. Street is pricing in a beat, and the setup looks solid.
Why I’m still bullish:
AI + HBM demand continues to outrun supply. Micron has locked in roughly $100B of multi-year take-or-pay HBM contracts plus 16 strategic customer agreements with floor pricing. That shifts the story from pure cycle pricing to contracted visibility.
Q3 already printed 84.9% gross margin on $41.5B revenue. Clearing 86% in Q4 looks very achievable if the mix stays HBM/data-center heavy and pricing holds.
Management keeps saying supply constraints look structural into 2027–28. New capacity doesn’t appear overnight.
The real question isn’t whether Q4 prints strong. It’s how much longer this supercycle can actually run before capacity finally catches up.
Where are you guys targeting MU after the report? Still adding on dips or taking some chips off?
#EarningsSeason #MU