Last cycle everyone said liquid staking would run DeFi. Stake native asset, get LST, keep earning while deploying that capital elsewhere. Clean thesis.
Then restaking ate the spotlight. Points programs pulled harder than base yield. Capital rotated into perps, stables, RWAs, revenue apps.
LSTs stopped being the narrative. But they kept building.
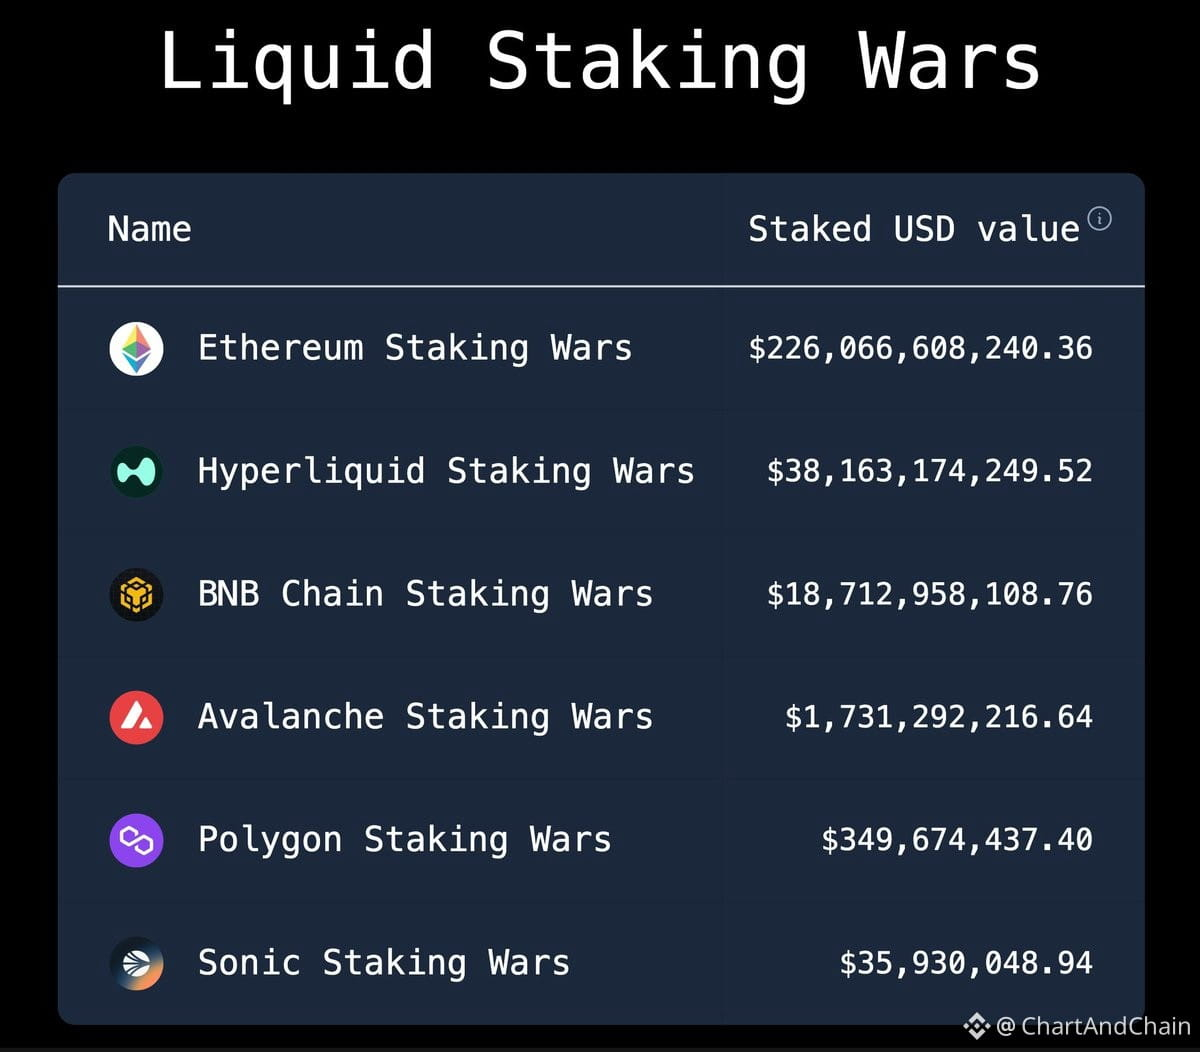
Current staked value across five chains sits near $285B:
$ETH: $226B
Hyperliquid: $38.2B
$BNB: $18.7B
$AVAX: $1.73B
$POL: $350M
Liquid staking protocols still hold ~$52.6B TVL, generating ~$28.8M weekly fees. Lido alone manages over $24B.
What shifted is the eval framework. Used to just compare APY, fees, withdrawal depth. Now I check lending market support, collateral efficiency, DEX liquidity, Pendle integration, custody options, validator spread, contract and slashing risk.
Sector's also expanding past Ethereum. Solana crossed $6.2B in LST TVL. Hyperliquid already staked $38B+. Ethereum still leads, but newer ecosystems have enough native stake to spawn real LST competition.
Institutions moving in. Anchorage added Lido support. Sharplink allocated $200M $ETH through the protocol.
LSTs becoming core collateral for onchain finance. Less hype, stronger infra. Expect wide acceptance across lending, trading, structured yield, institutional products.
Quiet build phase. That's usually when foundation gets laid.