

#semiconductors
semiconductors
587,945 vues
3,661 mentions
Populaire
Récents

Article
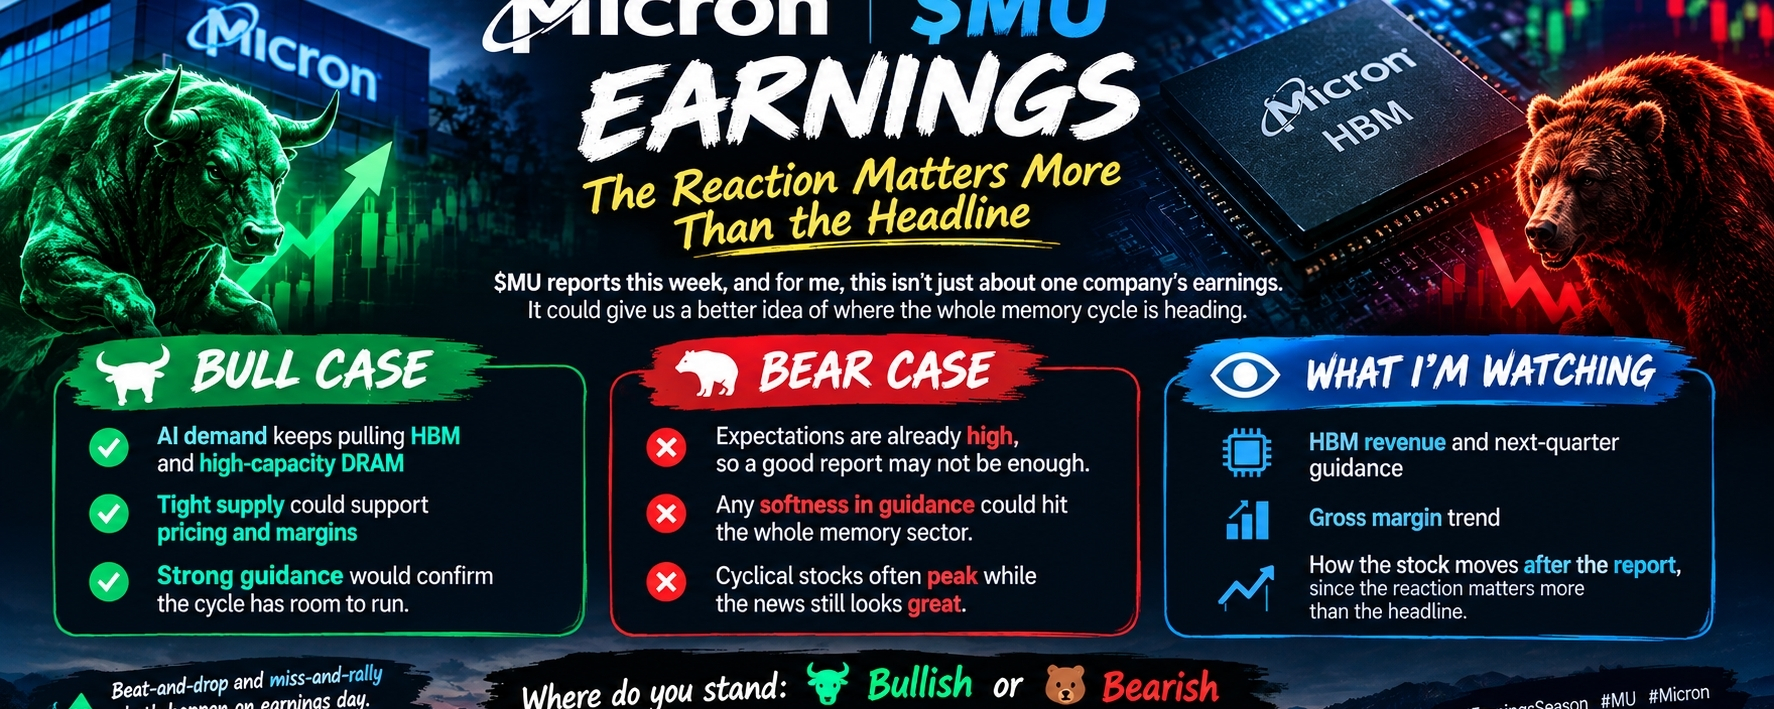
$MU Earnings: The Reaction Matters More Than the Headline 📊$MU $ETH reports this week, and for me, this isn’t just about one company’s earnings. It could give us a better idea of where the whole memory cycle is heading.
🐂 Bull case • AI demand continues driving HBM and high-capacity DRAM
• Tight supply could keep pricing and margins strong
• Strong guidance could support the current bullish trend
🐻 Bear case • Expectations are already high, so a good report might not be enough
• Weak guidance could pressure the broader memory sector
• Sometimes cyclical stocks peak even when the news still looks great
👀 What I’m watching • HBM revenue and next-quarter guidance
• Gross margin trend
• Most importantly, how $MU reacts after earnings
A beat can still lead to a drop, and a miss can sometimes lead to a rally. That's why I’ll be watching the price reaction before making any move.
I’m staying focused on the setup and waiting for the market to show its hand.
🐂 Bullish or 🐻 Bearish on $MU? What’s your take?
#EarningsSeason #MU #Micron #Stocks #AI #Semiconductors
$MU Earnings: The Reaction Matters More Than the Headline 📊
$MU $ETH reports this week, and for me, this isn’t just about one company’s earnings. It could give us a better idea of where the whole memory cycle is heading.
🐂 Bull case • AI demand continues driving HBM and high-capacity DRAM
• Tight supply could keep pricing and margins strong
• Strong guidance could support the current bullish trend
🐻 Bear case • Expectations are already high, so a good report might not be enough
• Weak guidance could pressure the broader memory sector
• Sometimes cyclical stocks peak even when the news still looks great
👀 What I’m watching • HBM revenue and next-quarter guidance
• Gross margin trend
• Most importantly, how $MU reacts after earnings
A beat can still lead to a drop, and a miss can sometimes lead to a rally. That's why I’ll be watching the price reaction before making any move.
I’m staying focused on the setup and waiting for the market to show its hand.
🐂 Bullish or 🐻 Bearish on $MU ? What’s your take?
#EarningsSeason #MU #Micron #Stocks #AI #Semiconductors
242
Vérifié
Article
ONE QUARTER CAN MOVE $MU.
MULTI-YEAR COMMITMENTS BUILD THE THESIS.$MU: ONE QUARTER CAN MOVE THE STOCK. CAN IT BREAK THE THESIS?
Micron reports FY2026 Q4 today.
Most people will watch one thing:
Did $MU beat or miss?
I think the more important question is different:
Is Micron building a business that can remain strong AFTER this earnings report?
Before Q4 even lands, Micron was already guiding for:
$50B ± $1B revenue
~86% gross margin
~$31 non-GAAP EPS
Those numbers are huge.
But a great quarter alone doesn't create long-term confidence.
The real signal is what sits behind the quarter.
Micron has signed 16 Strategic Customer Agreements.
14 of those agreements represent approximately $100B of cumulative minimum-price revenue over their remaining terms.
Micron also expects around $22B in cash deposits and related financial commitments from signed agreements.
And these aren't one-quarter commitments.
Most agreements have five-year terms, with binding take-or-pay commitments for specific volumes.
That changes how I look at $MU.
This isn't simply:
AI hype → earnings beat → stock pumps.
The bigger story is:
AI infrastructure demand
↓
HBM / DRAM demand
↓
customers securing long-term supply
↓
Micron expanding capacity + technology investment
↓
greater revenue visibility
Micron itself says these agreements are intended to improve the durability, stability and predictability of its financial performance.
And the recent numbers already show how dramatically the business has changed.
Q3 FY2026 revenue reached $41.46B, versus $23.86B in Q2.
GAAP gross margin jumped from 74.4% → 84.6%.
Operating cash flow increased from $11.90B → $25.39B.
So here's the question I actually want to debate:
Is this just another memory-cycle peak — or is AI fundamentally changing the economics of memory?
Because these are two completely different theses.
If it's just a cycle, extraordinary margins eventually normalize.
If AI has structurally increased the value of high-performance memory, then today's numbers could be part of a much longer transformation.
That's why I don't think one earnings report should decide your entire view of $MU.
One quarter can change the price.
Multiple years of demand, customer commitments, technology leadership and disciplined capacity investment are what determine whether the thesis survives.
My question for #EarningsSeason:
Can Micron sustain this memory supercycle beyond the next few quarters?
🟢 BULL: AI demand + HBM + long-term contracts can support a multi-year cycle.
🔴 BEAR: Today's margins are cyclical and expectations are already too high.
Don't just tell me BULL or BEAR.
Tell me what breaks your thesis first.
#EarningsSeason #Micron #AI #Semiconductors
Nguồn: Micron Investor Relations — Q3 FY2026 results & Strategic Customer Agreements.
ONE QUARTER CAN MOVE $MU. MULTI-YEAR COMMITMENTS BUILD THE THESIS.
$MU : ONE QUARTER CAN MOVE THE STOCK. CAN IT BREAK THE THESIS?
Micron reports FY2026 Q4 today.
Most people will watch one thing:
Did $MU beat or miss?
I think the more important question is different:
Is Micron building a business that can remain strong AFTER this earnings report?
Before Q4 even lands, Micron was already guiding for:
$50B ± $1B revenue
~86% gross margin
~$31 non-GAAP EPS
Those numbers are huge.
But a great quarter alone doesn't create long-term confidence.
The real signal is what sits behind the quarter.
Micron has signed 16 Strategic Customer Agreements.
14 of those agreements represent approximately $100B of cumulative minimum-price revenue over their remaining terms.
Micron also expects around $22B in cash deposits and related financial commitments from signed agreements.
And these aren't one-quarter commitments.
Most agreements have five-year terms, with binding take-or-pay commitments for specific volumes.
That changes how I look at $MU .
This isn't simply:
AI hype → earnings beat → stock pumps.
The bigger story is:
AI infrastructure demand
↓
HBM / DRAM demand
↓
customers securing long-term supply
↓
Micron expanding capacity + technology investment
↓
greater revenue visibility
Micron itself says these agreements are intended to improve the durability, stability and predictability of its financial performance.
And the recent numbers already show how dramatically the business has changed.
Q3 FY2026 revenue reached $41.46B, versus $23.86B in Q2.
GAAP gross margin jumped from 74.4% → 84.6%.
Operating cash flow increased from $11.90B → $25.39B.
So here's the question I actually want to debate:
Is this just another memory-cycle peak — or is AI fundamentally changing the economics of memory?
Because these are two completely different theses.
If it's just a cycle, extraordinary margins eventually normalize.
If AI has structurally increased the value of high-performance memory, then today's numbers could be part of a much longer transformation.
That's why I don't think one earnings report should decide your entire view of $MU .
One quarter can change the price.
Multiple years of demand, customer commitments, technology leadership and disciplined capacity investment are what determine whether the thesis survives.
My question for #EarningsSeason:
Can Micron sustain this memory supercycle beyond the next few quarters?
🟢 BULL: AI demand + HBM + long-term contracts can support a multi-year cycle.
🔴 BEAR: Today's margins are cyclical and expectations are already too high.
Don't just tell me BULL or BEAR.
Tell me what breaks your thesis first.
#EarningsSeason #Micron #AI #Semiconductors
Nguồn: Micron Investor Relations — Q3 FY2026 results & Strategic Customer Agreements.
Fualnguyen:
$MU delivers strong earnings but weak guidance—does the dip still look cheap? 👀 Which matters more for your next trade: this quarter’s beat or next quarter’s outlook? 👇
4
7
1.5k
·
--
🚨 Micron Q4 Earnings — Bullish or Bearish on $MUB ?
Micron is heading into a major earnings event, with the AI-driven memory cycle under the spotlight. 📊
What I'm watching:
🔹 Gross margin — Can Micron deliver around 86%?
🔹 HBM demand — Is AI demand still accelerating?
🔹 FY2027 guidance — Can strong memory pricing continue?
🔹 Memory super cycle — Temporary upcycle or a longer AI-driven trend?
📈 My view: Cautiously Bullish
A strong earnings beat plus bullish FY2027 guidance could support $MUB .
But if results beat expectations while forward guidance disappoints, we could see a “good earnings, bad reaction” setup.
For me, FY2027 guidance matters more than the headline EPS beat.
🟢 Bullish or 🔴 Bearish?
What’s your view on $MU ?
#EarningsSeason #Micron #MU #AI #HBM #Semiconductors
685
·
--
🤖 AI DOESN'T RUN ON GPUs ALONE.
Everyone talks about NVDA
But there’s another piece of the AI infrastructure that the market can’t ignore:
🧠 MEMORY.
AI models are getting bigger.
Data centers need more bandwidth.
HBM demand keeps becoming a bigger part of the story.
And that puts #MU Micron directly in the conversation.
The interesting question isn't:
“Will AI keep growing?”
It’s this:
👉 How much of that AI spending eventually flows into memory?
If HBM demand keeps surprising to the upside, $MU could remain one of the names traders are watching closely.
👀 Would you hold $MU for the AI-memory cycle?
{stock_us}(MU.US)
{future}(NVDAUSDT)
#Micron #AI #Semiconductors $MU
🤖 AI DOESN'T RUN ON GPUs ALONE.
Everyone talks about NVDA
But there’s another piece of the AI infrastructure that the market can’t ignore:
🧠 MEMORY.
AI models are getting bigger.
Data centers need more bandwidth.
HBM demand keeps becoming a bigger part of the story.
And that puts #MU Micron directly in the conversation.
The interesting question isn't:
“Will AI keep growing?”
It’s this:
👉 How much of that AI spending eventually flows into memory?
If HBM demand keeps surprising to the upside, $MU could remain one of the names traders are watching closely.
👀 Would you hold $MU for the AI-memory cycle?
#Micron #AI #Semiconductors $MU
Yes
No
19 heure(s) restante(s)
4.5k
·
--
🚨 $MU — THE FINAL CHECK BEFORE EARNINGS 👀
Micron reports TODAY after the U.S. market close.
The market already knows the headline numbers:
💰 Q4 Revenue Guide: ~$50B
📊 Gross Margin: ~86%
💵 EPS Guide: $31 ± $1
But the real test is what comes NEXT:
🔥 Does management keep HBM/AI demand strong?
🔥 Can margins stay above ~86%?
🔥 What does FY2027 guidance say about memory pricing?
A beat alone may not be enough.
I’m watching the guidance + margin commentary more closely than the headline EPS.
Would you hold $MU through earnings or wait for the numbers first? 👇
#EarningsSeason #TechStocks #StockMarket #AIStocks #MarketAnalysis #BinanceSquare #MU #Micron #Aİ #Semiconductors
161
·
--
Vérifié
🚨 $MU EARNINGS: WHAT MATTERS BEYOND THE HEADLINE NUMBER?
Micron reports its FY2026 Q4 results on September 30 after the U.S. market close.
Micron Investors
The key question isn’t only whether $MU beats estimates.
I’m watching 3 things:
📊 1. Revenue & EPS
Micron’s own Q4 guidance is $50B ± $1B revenue and $31 ± $1 adjusted EPS.
Micron Investors
🏭 2. AI / HBM demand
Will management show that AI-driven memory demand is continuing to support pricing and margins?
📈 3. Forward guidance
For me, the biggest market reaction could come from what Micron says about the next quarter—not just tonight’s numbers.
How would you manage your $MU position around earnings?
Drop your view below 👇
#EarningsSeason #AI #Semiconductors
🟢 Hold through the report
🔴 Reduce before earnings
⚪ Wait for the post-earnings
16 heure(s) restante(s)
884
·
--
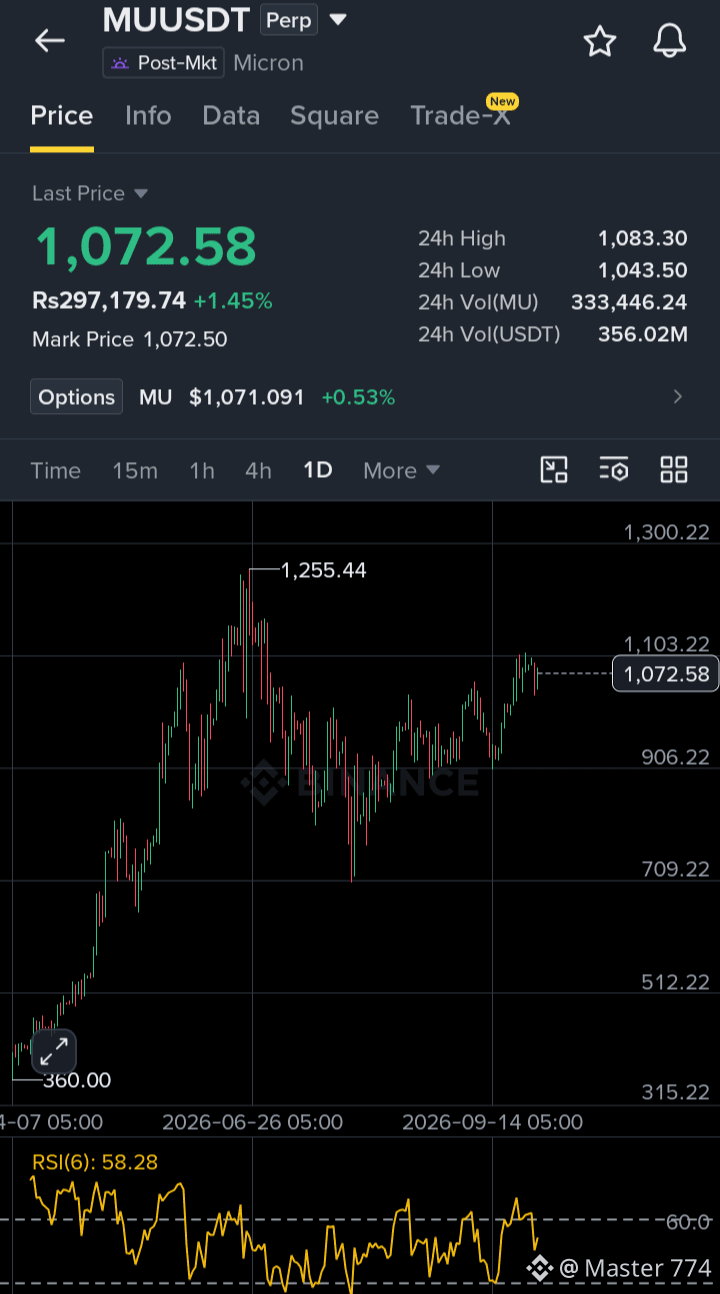
#EarningsSeason 🚗⚡ MU Daily Chart — AI Memory Story
Micron is sitting near $1,073, with the daily chart showing strong recovery momentum.
The bigger story is AI infrastructure: autonomous vehicles need ultra-fast memory to process camera, LiDAR and radar data in real time.
📈 If MU holds the current momentum, $1,103 is the first key area to watch, followed by the previous high zone around $1,255.
AI demand isn’t only about GPUs — memory is becoming a major part of the AI hardware race. 👀
$MUB #Micron #AI #Semiconductors
31

⚡ MIXED US TECH OPEN REVEALS INSTITUTIONAL ROTATION INTO $NVDA AND SEMIS! 📊
Institutional order flow shows a selective bid across core semiconductor leaders as $NVDA climbs 1.72% and $INTC gains 2.50% at the US open, absorbing immediate supply. 🔍 However, risk appetite remains fragmented across broader tech hardware.
💡 The sharp divergence is most evident in neocloud infrastructure, where $HUT drops 5.86% alongside weakness in optical communication. Smart money appears to be tightening capital allocation toward primary chipmakers while liquidating secondary computing plays. 🤔 Are institutional buyers building order blocks in core tech before the next leg, or is this early distribution? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #NVDA #Semiconductors #MarketStructure #Crypto
🎯 🦈
176
·
--
I think the memory super cycle could run for another 12–24 months, driven by AI and data-center demand. But supply growth and slowing AI spending remain key risks.
I’m cautiously bullish on $MU , but expectations are already high.
What do you think? Are we still early, or near the top?
$MU #Micron #Semiconductors #EarningsSeason
I’m cautiously bullish on $MU , but expectations are already high.
What do you think? Are we still early, or near the top?
$MU #Micron #Semiconductors #EarningsSeason
193
·
--
As Micron Technology ($MU) prepares to roll out its FY2026 Q4 earnings report, the entire semiconductor and AI market is watching closely. This report is more than just about one stock—it's a high-stakes stress test for the ongoing Memory Supercycle.
📈 My Take: Strongly Bullish with Caution on Margins
1️⃣ AI Demand & HBM Dominance: Demand for High Bandwidth Memory (HBM) driven by AI infrastructure, enterprise servers, and data centers remains at record levels. Supply for 2026/2027 is largely locked in, giving Micron strong pricing power.
2️⃣ Gross Margin Target (86% Challenge): Crossing an 86% gross margin in Q4 is an ambitious target. While DRAM and NAND ASPs (Average Selling Prices) have surged, rising supply chain and production scaling costs might keep margins slightly below the extreme 86% peak. However, even a margin hovering around 80%+ will confirm massive profitability.
3️⃣ How Long Will the Memory Supercycle Last? Driven by generative AI scaling and hardware upgrades across cloud giants, this memory supercycle easily has momentum through mid-2027 before any significant supply-demand rebalancing occurs.
💡 My Strategy:
Pre-Earnings: Holding core long position in $MU with structured risk management.
Post-Earnings: Looking to add on any immediate post-earning volatility/dips if guidance for FY2027 remains strong.
What's your stance before the numbers drop? Are you bullish or bearish on $MU? Let’s discuss in the comments! 👇
#EarningsSeason #Micron #MU #Crypto #Semiconductors #MarketAnalysis
$MU
{future}(MUUSDT)
As Micron Technology ($MU ) prepares to roll out its FY2026 Q4 earnings report, the entire semiconductor and AI market is watching closely. This report is more than just about one stock—it's a high-stakes stress test for the ongoing Memory Supercycle.
📈 My Take: Strongly Bullish with Caution on Margins
1️⃣ AI Demand & HBM Dominance: Demand for High Bandwidth Memory (HBM) driven by AI infrastructure, enterprise servers, and data centers remains at record levels. Supply for 2026/2027 is largely locked in, giving Micron strong pricing power.
2️⃣ Gross Margin Target (86% Challenge): Crossing an 86% gross margin in Q4 is an ambitious target. While DRAM and NAND ASPs (Average Selling Prices) have surged, rising supply chain and production scaling costs might keep margins slightly below the extreme 86% peak. However, even a margin hovering around 80%+ will confirm massive profitability.
3️⃣ How Long Will the Memory Supercycle Last? Driven by generative AI scaling and hardware upgrades across cloud giants, this memory supercycle easily has momentum through mid-2027 before any significant supply-demand rebalancing occurs.
💡 My Strategy:
Pre-Earnings: Holding core long position in $MU with structured risk management.
Post-Earnings: Looking to add on any immediate post-earning volatility/dips if guidance for FY2027 remains strong.
What's your stance before the numbers drop? Are you bullish or bearish on $MU ? Let’s discuss in the comments! 👇
#EarningsSeason #Micron #MU #Crypto #Semiconductors #MarketAnalysis
$MU
1
210
·
--
Article
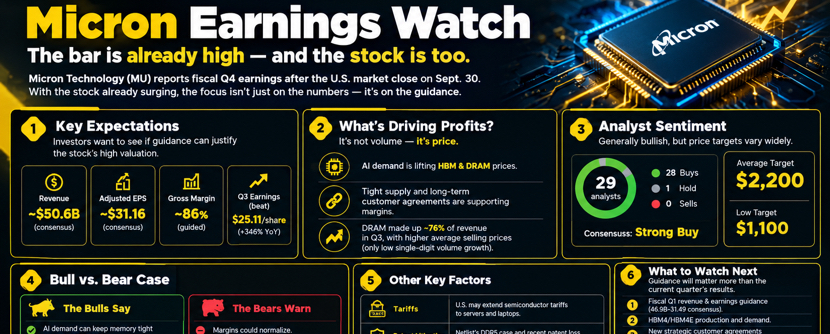
🚨 Micron $MU Earnings: The Bar Is Already HighMicron Technology reports fiscal Q4 earnings after the U.S. market close today, Sept. 30. With the stock already surging, investors are watching guidance more closely than the headline earnings beat.
📊 What matters:
• AI-driven demand continues to lift HBM and DRAM prices.
• Tight supply and long-term customer agreements are supporting margins.
• Analysts expect another strong quarter, but price targets vary widely.
• Bulls see AI demand keeping memory supply tight into 2027 and beyond.
• Bears warn that new capacity could eventually push prices and margins lower.
🔑 Tonight’s key signals:
• Fiscal Q1 revenue and earnings guidance
• HBM4/HBM4E production and demand
• DRAM/NAND pricing trends
• Gross-margin outlook
• New long-term customer agreements
• Management’s view on how long the supply shortage can last
⚠️ Bottom line: Micron doesn’t just need strong numbers—the guidance needs to show that the AI-driven memory boom can continue to justify the stock’s elevated valuation.
$MU #Aİ #HBM #DRAM #Semiconductors
{future}(MUUSDT)
{spot}(MUBUSDT)
🚨 Micron $MU Earnings: The Bar Is Already High
Micron Technology reports fiscal Q4 earnings after the U.S. market close today, Sept. 30. With the stock already surging, investors are watching guidance more closely than the headline earnings beat.
📊 What matters:
• AI-driven demand continues to lift HBM and DRAM prices.
• Tight supply and long-term customer agreements are supporting margins.
• Analysts expect another strong quarter, but price targets vary widely.
• Bulls see AI demand keeping memory supply tight into 2027 and beyond.
• Bears warn that new capacity could eventually push prices and margins lower.
🔑 Tonight’s key signals:
• Fiscal Q1 revenue and earnings guidance
• HBM4/HBM4E production and demand
• DRAM/NAND pricing trends
• Gross-margin outlook
• New long-term customer agreements
• Management’s view on how long the supply shortage can last
⚠️ Bottom line: Micron doesn’t just need strong numbers—the guidance needs to show that the AI-driven memory boom can continue to justify the stock’s elevated valuation.
$MU #Aİ #HBM #DRAM #Semiconductors
201
#EarningsSeason 👀
$MU earnings could tell us whether the AI memory boom is actually sustainable — or whether expectations have simply gone too far.
Micron has guided for around $50B revenue for FY2026 Q4, while the market is watching whether gross margin can push above 86%.
My biggest question isn't just “Will MU beat earnings?”
It's this:
Can Micron maintain this level of profitability if AI memory demand stays strong?
If margins surprise higher → the memory supercycle narrative gets stronger.
If margins disappoint → the market may start questioning how much of the AI boom is already priced in.
🔥 Bullish or bearish on $MU after earnings?
#MU #Micron #AI #Semiconductors
1
139
·
--
Haussier
#EarningsSeason 🔥
$MU earnings are about to become a BIG test for the AI + semiconductor story.
Micron is heading into FY2026 Q4 earnings with the market watching one thing closely:
👉 Is AI demand actually translating into sustainable profits?
Micron has guided around $50B revenue, while the market is looking for even more. The other number I'm watching is gross margin — can Micron push it beyond 86%?
If the numbers beat expectations, the impact may go beyond $MU. It could tell us a lot about the strength of the entire memory + AI semiconductor cycle.
But if expectations are already too high, even a strong report could trigger a sell-the-news reaction.
🔥 My question:
Bullish or bearish on $MU after earnings?
And more importantly — how long can this memory supercycle really last? 👀
#MU #Micron #AI #Semiconductors
#EarningsSeason 🔥
$MU earnings are about to become a BIG test for the AI + semiconductor story.
Micron is heading into FY2026 Q4 earnings with the market watching one thing closely:
👉 Is AI demand actually translating into sustainable profits?
Micron has guided around $50B revenue, while the market is looking for even more. The other number I'm watching is gross margin — can Micron push it beyond 86%?
If the numbers beat expectations, the impact may go beyond $MU . It could tell us a lot about the strength of the entire memory + AI semiconductor cycle.
But if expectations are already too high, even a strong report could trigger a sell-the-news reaction.
🔥 My question:
Bullish or bearish on $MU after earnings?
And more importantly — how long can this memory supercycle really last? 👀
#MU #Micron #AI #Semiconductors
1
128

Chips Rebound as Yields Hit 24Y High
Semiconductors clawed back losses today as Treasury yields spiked to a 24-year high, with $AMAT
{future}(AMATUSDT)
leading the rebound, up +5.19%.
Funds rotated into oversold chip stocks even as bond yields surged, suggesting investors see AI-driven semiconductor demand outweighing rate concerns for now.
Micron's Q4 earnings drop today too — a strong print could add fuel to this chip sector bounce.
Bullish signal for tech, or just a dead-cat bounce before more pressure? 👇
#Semiconductors #AMAT #TechStocks
Chips Rebound as Yields Hit 24Y High
Semiconductors clawed back losses today as Treasury yields spiked to a 24-year high, with $AMAT
leading the rebound, up +5.19%.
Funds rotated into oversold chip stocks even as bond yields surged, suggesting investors see AI-driven semiconductor demand outweighing rate concerns for now.
Micron's Q4 earnings drop today too — a strong print could add fuel to this chip sector bounce.
Bullish signal for tech, or just a dead-cat bounce before more pressure? 👇
#Semiconductors #AMAT #TechStocks
1
67
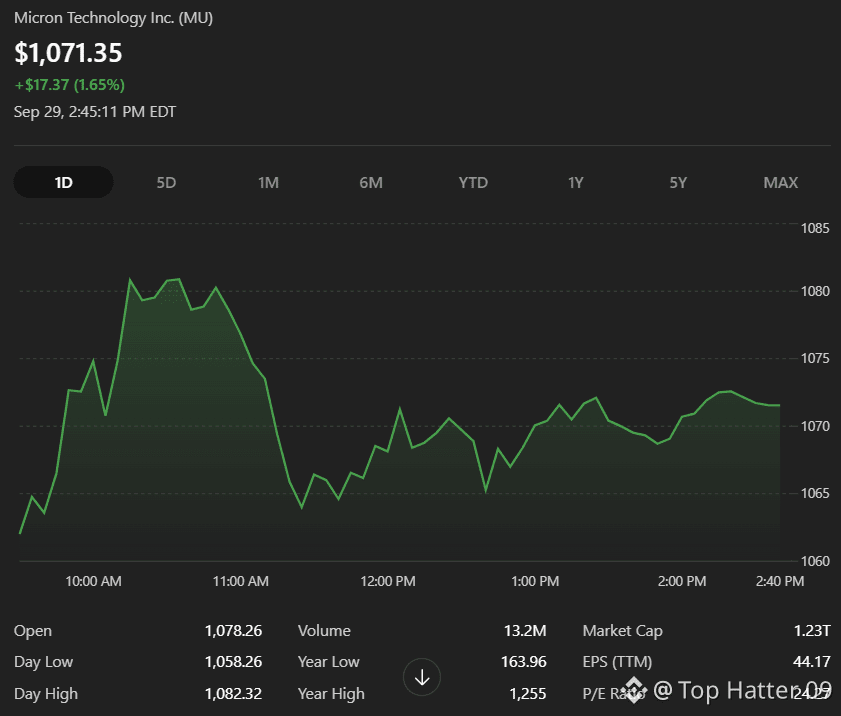
$MU EARNINGS IN FOCUS 👀
$MU is sitting around $1,073 ahead of tomorrow’s earnings, with the chart still holding well above the 25D MA at $1,018.58.
The level I’m watching is $1,080–$1,100. A clean break above that zone could bring the previous $1,200–$1,255 area back into focus.
But earnings are the real test. Micron is guiding for roughly $50B revenue, ~86% gross margin and $31 non-GAAP EPS for Q4.
For me, the key question isn't just whether MU
{future}(MUUSDT)
beats. What matters is the FY2027 guidance and the outlook for memory/HBM demand.
I’m watching $1,100 above and $1,020–$1,040 below.
$MU #EarningsSeason #Micron #Semiconductors #BinanceSquare
$MU EARNINGS IN FOCUS 👀
$MU is sitting around $1,073 ahead of tomorrow’s earnings, with the chart still holding well above the 25D MA at $1,018.58.
The level I’m watching is $1,080–$1,100. A clean break above that zone could bring the previous $1,200–$1,255 area back into focus.
But earnings are the real test. Micron is guiding for roughly $50B revenue, ~86% gross margin and $31 non-GAAP EPS for Q4.
For me, the key question isn't just whether MU
beats. What matters is the FY2027 guidance and the outlook for memory/HBM demand.
I’m watching $1,100 above and $1,020–$1,040 below.
$MU #EarningsSeason #Micron #Semiconductors #BinanceSquare
101
·
--
Haussier
#Semiconductors 🔥 SEMICONDUCTORS: The Hidden Engine Behind AI
AI may be the headline, but semiconductors are the engine powering the revolution. 🤖⚡
From AI data centres and GPUs to smartphones, EVs and advanced computing, demand for powerful chips continues to shape the technology market.
📈 Key question:
Will the semiconductor sector continue to benefit from the global AI boom?
Bullish 🟢 or Bearish 🔴?
Vote below 👇
#SemiconductorTakeover #USJobOpeningsFallToFiveMonthLow #ECBToTestAIAgentsInDigitalEuroPayments #BitgetHackerFailsToMoveStolenFunds
1
48

·
--
Picture this: Wall Street holds its breath for a legacy semiconductor report, while decentralized compute traders quietly scramble to adjust their positions before the bell.
Most crypto investors get blindsided by macro tech earnings because they treat digital assets like an isolated sandbox, only to watch their AI portfolio dump after misreading supply chain momentum.
When Micron drops its FY2026 Q4 earnings this week, the numbers will reveal much more than the immediate trajectory of $MU shares. It is the ultimate litmus test for the global memory supercycle, serving as the foundational backbone for high-bandwidth AI infrastructure. If traditional hardware giants show margin compression or slowing data center demand, high-flying AI compute plays like $RNDR and intelligence networks like $NEAR usually feel the spillover within hours.
We saw a similar dynamic play out during previous semiconductor cycles, where early hardware bottlenecks dictated entire liquidity rotations across tech and crypto alike. High expectations leave razor-thin margins for error, especially when valuation multiples have already priced in aggressive AI scaling through next year.
Do you think the memory supercycle has enough gas to fuel the next leg of AI infrastructure tokens, or are we heading into a reality check?
#CryptoAI #Semiconductors #MarketAnalysis
94

·
--
🚨 $MU Q4 EARNINGS: HERE’S MY BULL CASE
I’m bullish on MU into/after earnings, but my thesis isn’t simply “AI is booming.”
Here’s what I’m watching:
📈 1. $50B revenue target Micron guided Q4 revenue to $50B ± $1B. That would be a huge step up from the prior quarter’s $33.5B guidance. If Micron beats this and raises the next-quarter outlook, I think the market will focus on the durability of the cycle.
💰 2. 86% gross margin is the key Micron is already guiding for approximately 86% gross margin. Management said this outlook assumes a moderation in the rate of price increases, so holding or exceeding 86% would be an important signal that pricing + product mix are still extremely strong.
🤖 3. HBM is becoming a bigger part of the story Micron says HBM4 is already in high-volume shipments for its lead customer, with qualification samples sent to multiple other customers. That gives MU exposure to the AI infrastructure buildout beyond traditional memory demand.
🔥 4. The real catalyst = guidance For me, the biggest number tonight isn’t just EPS.
I want to see: • Revenue above/around $50B
• Gross margin ≥86%
• Strong HBM commentary
• Evidence that pricing remains firm
• Constructive FY2027 outlook
If those pieces line up, my bullish thesis gets stronger.
I’m not chasing the first earnings candle. I’d rather see the numbers, guidance and price action confirm the thesis before adding risk.
Is the memory super cycle still in the early innings, or are we getting close to peak margins? 👇
#EarningsSeason #MU #Semiconductors
Usman_Miankhel:
📦✔️
2
2
46
·
--
Haussier
Vérifié
#EarningsSeason $MU
Micron earnings are coming and honestly,I think the main thing to watch is the gross margin.
Micron is already guiding for around 86% gross margin in Q4.That is a very high number so I think the reaction after earnings will depend a lot on whether they can actually deliver it.
If they beat the revenue and margin expectations and the FY2027 outlook is also strong,I would be more comfortable holding a bullish position, however if margin comes below expectations or management gives a weaker outlook,I would be careful.I would not try to fight the market just because I am bullish on memory stocks.
For my trade I would rather wait for the earnings reaction instead of taking a big position before the report. The first move can be very misleading.
The bigger question for me is how long this memory super cycle can continue.AI demand is still very strong but eventually more supply will come into the market therefore $MU I am watching two things closely.
1/Q4 gross margin and
2/FY2027 guidance.
#Micron #AI #Semiconductors #MicronTechnology $MUB
1
1
201
·
--
MICRON EARNINGS TOMORROW — I’M NOT JUST WATCHING REVENUE 👀
Micron reports tomorrow, and honestly, the $50B revenue number is not the part I’m most interested in.
The number I keep coming back to is 86%.
That’s Micron’s Q4 gross-margin guidance. In Q3, it already reached 84.9% non-GAAP gross margin, so the company is basically asking the market to believe margins can move even higher.
And there’s a catch.
Micron itself said its Q4 margin outlook assumes a meaningful moderation in the rate of price increases.
That’s what makes tomorrow interesting.
If memory prices aren't rising as fast, but Micron can still deliver around 86% margins, then this starts looking less like a temporary pricing spike and more like a much stronger memory cycle.
But if margins come in weaker and management starts talking about pricing pressure, supply or demand differently, then the market has something new to think about.
That’s why I’m not asking only:
“Will Micron beat earnings?”
I’m watching what management says about FY2027.
Because the real test of this memory supercycle isn't whether Micron can have one massive quarter.
It’s whether these margins and AI-driven memory demand can stay elevated after this quarter.
Tomorrow should give us a much clearer answer.
$MU
#EarningsSeason #Micron #MU #Semiconductors
242
Connectez-vous pour découvrir plus de contenu
Rejoignez la communauté mondiale des adeptes de cryptomonnaies sur Binance Square
⚡️ Suviez les dernières informations importantes sur les cryptomonnaies.
💬 Jugé digne de confiance par la plus grande plateforme d’échange de cryptomonnaies au monde.
👍 Découvrez les connaissances que partagent les créateurs vérifiés.
Adresse e-mail/Nº de téléphone
Sujets d’actualité
1
#BitcoinClears$85200
14,805 vues
232 mentions
2
#AltcoinSeasonIndexHoldsAbove60For5Days
71,192 vues
1,244 mentions
3
#USADPAdds90000JobsInSeptember
32,471 vues
699 mentions
4
#USCorePCEEasesTo3%InAugust
23,169 vues
523 mentions
5
#KospiPostsWorstQuarterSince2020
15,993 vues
500 mentions
6
#SECToClarifyOnChainFundraisingRules
39,704 vues
675 mentions
7
#UKFCAOpensCryptoFirmAuthorization
38,753 vues
565 mentions
8
#JapanMOFStudyGroupOnTokenizedGovtBonds
22,351 vues
426 mentions
9
#QNTRises287%
108,128 vues
931 mentions
10
#TrumpRejectsAIRulesForVoluntaryAudits
61,839 vues
807 mentions