

#googl
googl
224,731 views
1,864 Discussing
Hot
Latest
·
--
📊 #BinancePick — Will Google Beat Quarterly Earnings Expectations? 🚀
I’m leaning toward a potential earnings beat from $GOOGL (Alphabet) 📈
Here’s why I’m watching Google closely:
🔹 AI Growth: Google’s AI investments could strengthen Search, Gemini, and its overall competitive position.
🔹 Cloud Demand: Continued demand for cloud computing and AI infrastructure could support Google Cloud revenue growth.
🔹 Advertising Power: Google’s advertising business remains a key earnings driver, and resilient digital ad spending could support its results.
🔹 What Could Go Wrong? Rising AI infrastructure costs, intense competition, and weaker-than-expected advertising growth could put pressure on margins.
🎯 My prediction: I’m leaning toward Google beating quarterly earnings expectations, but I’ll be watching revenue growth, earnings per share (EPS), and forward guidance before drawing a firm conclusion.
Remember, even a strong earnings beat doesn't guarantee a stock price rally. Expectations and market sentiment matter too!
What’s your call — GOOGLE BEAT 📈 or MISS 📉?
$GOOGL
#BinancePick #Google #GOOGL
24
·
--
Article
Google vs Microsoft: The AI Earnings Showdown — Who Will Turn AI Spending Into Real Profits? 🔥Billions of dollars are flowing into artificial intelligence, but investors are asking a tougher question: Who will turn that spending into sustainable profits?
On October 28, Alphabet (GOOGL) and Microsoft (MSFT) are set to report earnings after the US market closes. These results could offer an important signal about the future of the AI trade. The key is not just revenue growth, but whether AI investments can generate lasting returns.
🟢 $GOOGL — Can Google Protect Its Search Business?
Google's biggest strength is its established business. Search advertising, YouTube and Google Cloud provide multiple sources of revenue.
In Q2 2026, Alphabet's revenue grew 24% year over year. Search and Other revenue increased 17%, while Google Cloud revenue surged 82%. Those numbers show that Google is already generating growth from both its core business and its cloud operations.
But there is a real challenge ahead.
AI-powered search tools are changing how people find information. If users increasingly rely on AI assistants instead of traditional search results, Google's advertising model could face pressure.
Investors should watch three things:
Search revenue: Can Google defend its advertising business?
Google Cloud: Can AI demand continue driving growth?
AI spending: Can higher investment translate into stronger profits and cash flow?
Bullish case: Search remains resilient, Cloud continues expanding, and AI features create new revenue opportunities.
Bearish case: AI infrastructure costs rise faster than profits, while competition puts pressure on Search.
🔵 MSFT — Can Microsoft Monetize the AI Boom?
Microsoft has a different advantage. Its Azure cloud platform and Copilot AI tools give it opportunities to sell AI services to businesses that already rely on its software.
In its fiscal Q4 2026 results, Microsoft reported $90 billion in quarterly revenue, up 18% year over year. Azure and other cloud services revenue grew 43%, while Microsoft Cloud revenue increased 27%.
These are strong growth figures. However, investors need to know whether that momentum can continue without putting excessive pressure on margins.
My focus is on three areas:
Azure growth: Is demand for cloud and AI computing accelerating?
Copilot adoption: Are businesses willing to pay for AI tools at scale?
Capital expenditure: Is Microsoft generating enough returns to justify its growing investment in AI infrastructure?
Bullish case: Azure demand remains strong, Copilot subscriptions expand, and AI revenue supports future earnings.
Bearish case: Infrastructure spending rises too quickly, operating costs increase, and AI monetization falls short of expectations.
Microsoft's latest earnings also showed how important margins are: its cloud gross margin percentage declined year over year as the business invested in AI infrastructure and served a growing mix of Azure workloads.
⚖️ The Bigger Picture: Why This Matters Beyond Tech Stocks
This competition is about more than two companies.
AI infrastructure requires enormous investment in data centers, computing chips, electricity and network capacity. That spending creates opportunities for technology suppliers, but it also introduces financial risks.
Government policies matter here. Interest rates influence the cost of financing, while energy policy, competition rules, data protection laws and AI regulation can affect how quickly companies expand.
For ordinary people, the outcome could influence job opportunities, productivity, business costs and access to AI-powered services.
For investors, the lesson is straightforward: a company can lead in AI technology without necessarily delivering the best stock-market returns.
📊 My Trading and Investment View
I'm cautiously bullish on both $GOOGL and $MSFT , but I would not buy either stock simply because AI is attracting attention.
Here's what I would watch when the earnings reports arrive:
1. Revenue versus expectations: Beating analysts' forecasts matters, but the size and quality of the beat matter too.
2. Forward guidance: Management's outlook can have more influence on the stock than the latest quarter's results.
3. AI profitability: Look for evidence that AI revenue is growing fast enough to justify infrastructure spending.
4. Market reaction: Even strong earnings can trigger a sell-off if investors expected something better.
Avoid chasing a sudden price spike. Wait for the market to digest the results, assess price action and identify a sensible risk-to-reward setup.
Remember, these are stocks, not cryptocurrencies. Their prices can still move sharply around earnings, and neither a bullish business outlook nor strong revenue guarantees a positive market reaction.
🎯 Final Verdict: Which Company Has the Edge?
Google offers a compelling combination of advertising strength, AI development and rapidly growing cloud revenue. Microsoft offers a strong enterprise ecosystem, Azure and multiple ways to monetize AI.
Both have opportunities. Both face execution risks.
My preference will depend on which company demonstrates the clearest path from AI investment to sustainable earnings and cash flow—not simply which one announces the most impressive technology.
Now it's your turn! 👇
❤️ GOOGL: Google will defend Search and deliver stronger-than-expected earnings.
🔥 MSFT: Microsoft will turn Azure and Copilot demand into stronger AI profits.
Which stock do you think will deliver the bigger earnings surprise—and why?
Share your analysis in the comments!
#GOOGL #MSFT #CanMicrosoftDeliverOnAI #AI #Geopolitics
{future}(GOOGLUSDT)
{future}(MSFTUSDT)
Google vs Microsoft: The AI Earnings Showdown — Who Will Turn AI Spending Into Real Profits? 🔥
Billions of dollars are flowing into artificial intelligence, but investors are asking a tougher question: Who will turn that spending into sustainable profits?
On October 28, Alphabet (GOOGL) and Microsoft (MSFT) are set to report earnings after the US market closes. These results could offer an important signal about the future of the AI trade. The key is not just revenue growth, but whether AI investments can generate lasting returns.
🟢 $GOOGL — Can Google Protect Its Search Business?
Google's biggest strength is its established business. Search advertising, YouTube and Google Cloud provide multiple sources of revenue.
In Q2 2026, Alphabet's revenue grew 24% year over year. Search and Other revenue increased 17%, while Google Cloud revenue surged 82%. Those numbers show that Google is already generating growth from both its core business and its cloud operations.
But there is a real challenge ahead.
AI-powered search tools are changing how people find information. If users increasingly rely on AI assistants instead of traditional search results, Google's advertising model could face pressure.
Investors should watch three things:
Search revenue: Can Google defend its advertising business?
Google Cloud: Can AI demand continue driving growth?
AI spending: Can higher investment translate into stronger profits and cash flow?
Bullish case: Search remains resilient, Cloud continues expanding, and AI features create new revenue opportunities.
Bearish case: AI infrastructure costs rise faster than profits, while competition puts pressure on Search.
🔵 MSFT — Can Microsoft Monetize the AI Boom?
Microsoft has a different advantage. Its Azure cloud platform and Copilot AI tools give it opportunities to sell AI services to businesses that already rely on its software.
In its fiscal Q4 2026 results, Microsoft reported $90 billion in quarterly revenue, up 18% year over year. Azure and other cloud services revenue grew 43%, while Microsoft Cloud revenue increased 27%.
These are strong growth figures. However, investors need to know whether that momentum can continue without putting excessive pressure on margins.
My focus is on three areas:
Azure growth: Is demand for cloud and AI computing accelerating?
Copilot adoption: Are businesses willing to pay for AI tools at scale?
Capital expenditure: Is Microsoft generating enough returns to justify its growing investment in AI infrastructure?
Bullish case: Azure demand remains strong, Copilot subscriptions expand, and AI revenue supports future earnings.
Bearish case: Infrastructure spending rises too quickly, operating costs increase, and AI monetization falls short of expectations.
Microsoft's latest earnings also showed how important margins are: its cloud gross margin percentage declined year over year as the business invested in AI infrastructure and served a growing mix of Azure workloads.
⚖️ The Bigger Picture: Why This Matters Beyond Tech Stocks
This competition is about more than two companies.
AI infrastructure requires enormous investment in data centers, computing chips, electricity and network capacity. That spending creates opportunities for technology suppliers, but it also introduces financial risks.
Government policies matter here. Interest rates influence the cost of financing, while energy policy, competition rules, data protection laws and AI regulation can affect how quickly companies expand.
For ordinary people, the outcome could influence job opportunities, productivity, business costs and access to AI-powered services.
For investors, the lesson is straightforward: a company can lead in AI technology without necessarily delivering the best stock-market returns.
📊 My Trading and Investment View
I'm cautiously bullish on both $GOOGL and $MSFT , but I would not buy either stock simply because AI is attracting attention.
Here's what I would watch when the earnings reports arrive:
1. Revenue versus expectations: Beating analysts' forecasts matters, but the size and quality of the beat matter too.
2. Forward guidance: Management's outlook can have more influence on the stock than the latest quarter's results.
3. AI profitability: Look for evidence that AI revenue is growing fast enough to justify infrastructure spending.
4. Market reaction: Even strong earnings can trigger a sell-off if investors expected something better.
Avoid chasing a sudden price spike. Wait for the market to digest the results, assess price action and identify a sensible risk-to-reward setup.
Remember, these are stocks, not cryptocurrencies. Their prices can still move sharply around earnings, and neither a bullish business outlook nor strong revenue guarantees a positive market reaction.
🎯 Final Verdict: Which Company Has the Edge?
Google offers a compelling combination of advertising strength, AI development and rapidly growing cloud revenue. Microsoft offers a strong enterprise ecosystem, Azure and multiple ways to monetize AI.
Both have opportunities. Both face execution risks.
My preference will depend on which company demonstrates the clearest path from AI investment to sustainable earnings and cash flow—not simply which one announces the most impressive technology.
Now it's your turn! 👇
❤️ GOOGL: Google will defend Search and deliver stronger-than-expected earnings.
🔥 MSFT: Microsoft will turn Azure and Copilot demand into stronger AI profits.
Which stock do you think will deliver the bigger earnings surprise—and why?
Share your analysis in the comments!
#GOOGL #MSFT #CanMicrosoftDeliverOnAI #AI #Geopolitics
1
199
Verified
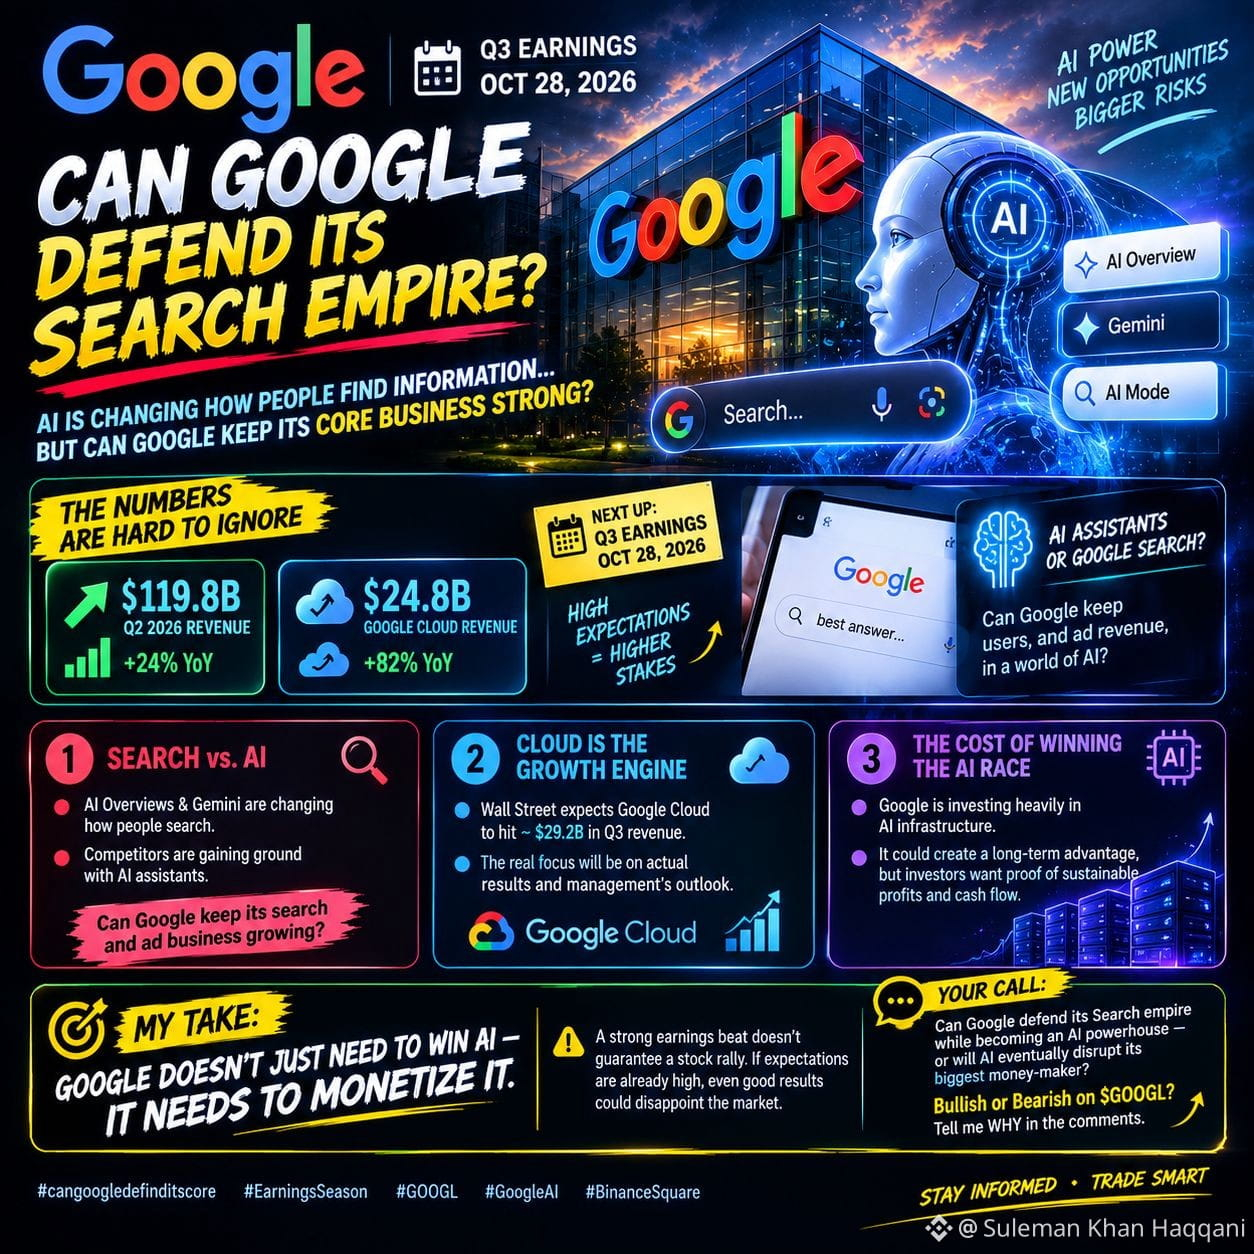
#cangoogledefinditscore 🚨 GOOGLE FACES ITS BIGGEST AI QUESTION: CAN IT PROTECT THE BUSINESS THAT MADE IT A GIANT? 👀
Tomorrow’s $GOOGL earnings could reveal something important: Is AI making Google stronger — or slowly changing the business model behind its success?
📊 THE NUMBERS ARE HARD TO IGNORE
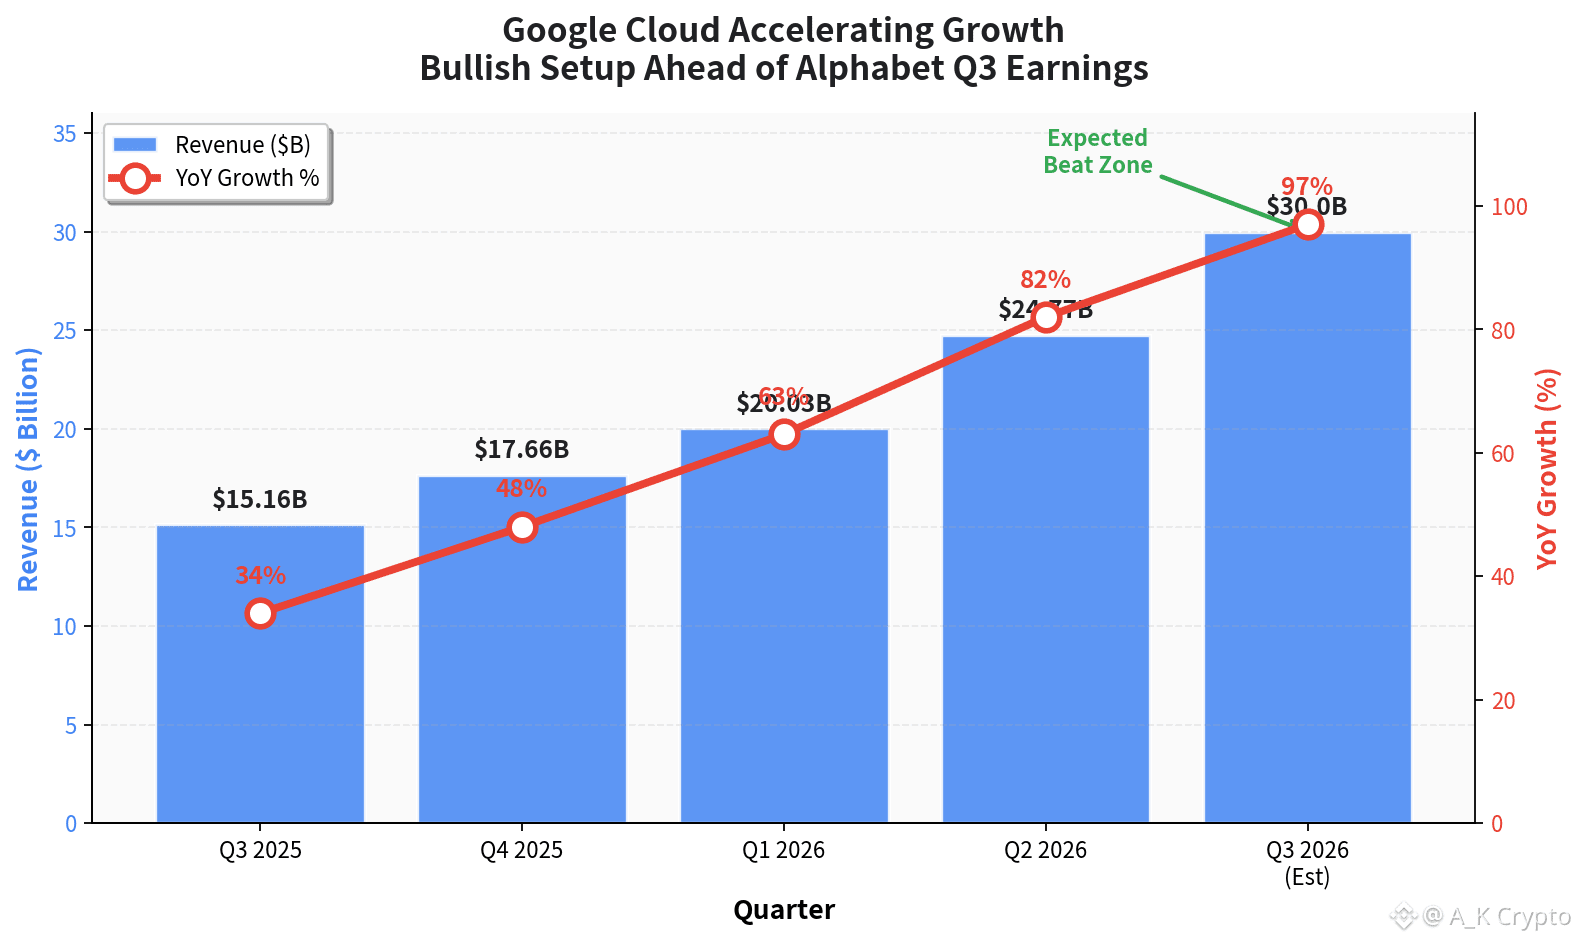
In Q2 2026, Alphabet generated $119.8B in revenue, up 24% year over year. Even more impressive, Google Cloud revenue surged 82% to $24.8B.
But the next report brings a different test. 🔍
🤖 1. SEARCH vs. AI
Google is adding AI to Search, but competitors are changing how people find information. Can Google keep its advertising business growing while users increasingly turn to AI assistants?
☁️ 2. CLOUD IS THE GROWTH ENGINE
Wall Street expects Google Cloud to deliver another powerful quarter, with analysts forecasting roughly $29.2B in revenue. The actual result — and management’s outlook — will matter more than the headline alone.
💸 3. THE COST OF WINNING THE AI RACE
Google is investing heavily in AI infrastructure. That could create a powerful long-term advantage, but investors also want evidence that this spending will generate sustainable profits and cash flow.
🎯 MY TAKE: GOOGLE DOESN’T JUST NEED TO WIN AI — IT NEEDS TO MONETIZE IT.
A strong earnings beat doesn’t guarantee a stock rally. If expectations are already high, even good results could disappoint the market.
💬 YOUR CALL: Can Google defend its Search empire while becoming an AI powerhouse — or will AI eventually disrupt its biggest money-maker?
Bullish or bearish on $GOOGL after earnings? Tell me WHY in the comments. 👇
#cangoogledefinditscore #EarningsSeason #GOOGL #GoogleAI
{future}(GOOGLUSDT)
#cangoogledefinditscore 🚨 GOOGLE FACES ITS BIGGEST AI QUESTION: CAN IT PROTECT THE BUSINESS THAT MADE IT A GIANT? 👀
Tomorrow’s $GOOGL earnings could reveal something important: Is AI making Google stronger — or slowly changing the business model behind its success?
📊 THE NUMBERS ARE HARD TO IGNORE
In Q2 2026, Alphabet generated $119.8B in revenue, up 24% year over year. Even more impressive, Google Cloud revenue surged 82% to $24.8B.
But the next report brings a different test. 🔍
🤖 1. SEARCH vs. AI
Google is adding AI to Search, but competitors are changing how people find information. Can Google keep its advertising business growing while users increasingly turn to AI assistants?
☁️ 2. CLOUD IS THE GROWTH ENGINE
Wall Street expects Google Cloud to deliver another powerful quarter, with analysts forecasting roughly $29.2B in revenue. The actual result — and management’s outlook — will matter more than the headline alone.
💸 3. THE COST OF WINNING THE AI RACE
Google is investing heavily in AI infrastructure. That could create a powerful long-term advantage, but investors also want evidence that this spending will generate sustainable profits and cash flow.
🎯 MY TAKE: GOOGLE DOESN’T JUST NEED TO WIN AI — IT NEEDS TO MONETIZE IT.
A strong earnings beat doesn’t guarantee a stock rally. If expectations are already high, even good results could disappoint the market.
💬 YOUR CALL: Can Google defend its Search empire while becoming an AI powerhouse — or will AI eventually disrupt its biggest money-maker?
Bullish or bearish on $GOOGL after earnings? Tell me WHY in the comments. 👇
#cangoogledefinditscore #EarningsSeason #GOOGL #GoogleAI
1
109
·
--
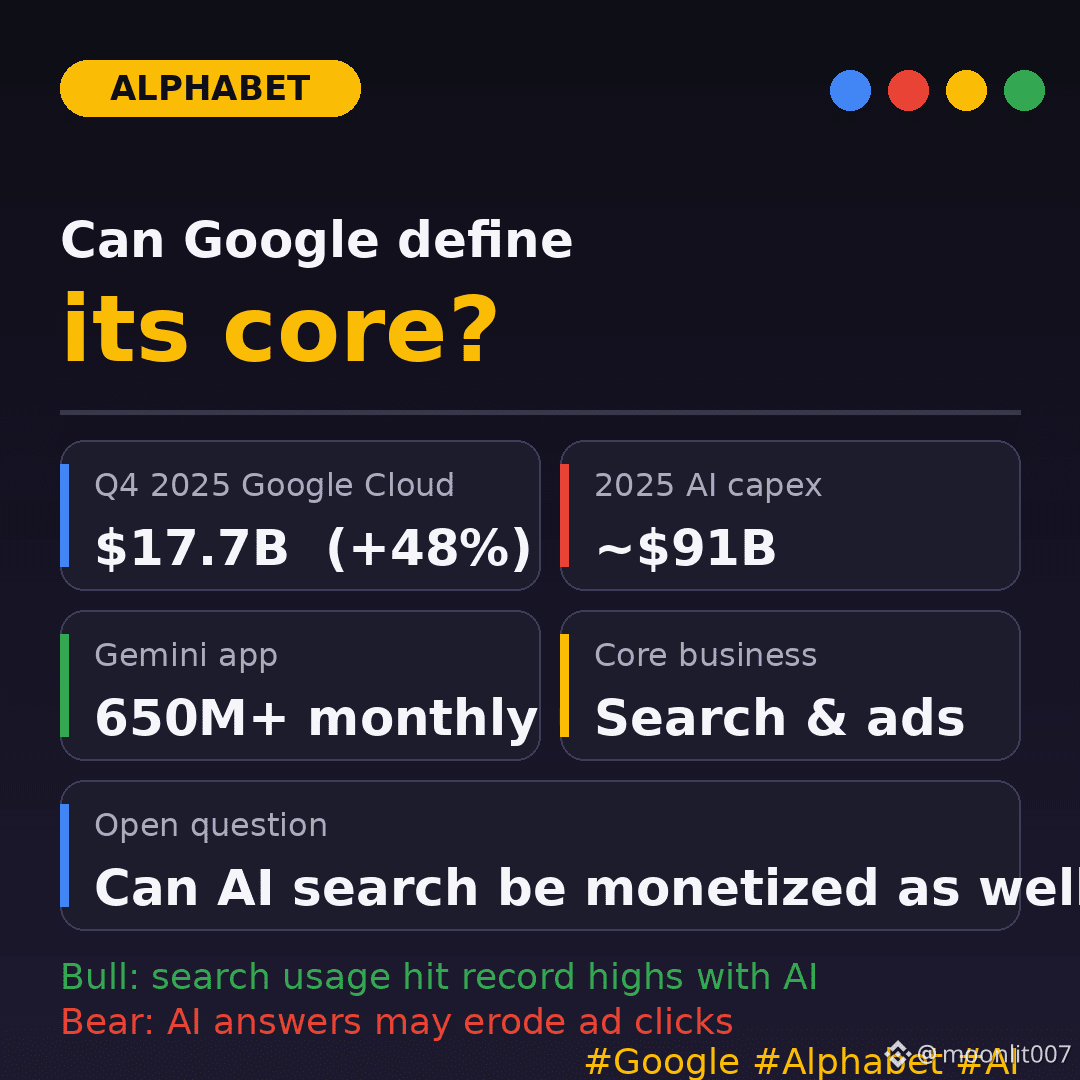
🔍 Can Google define its core?
Search is still Google’s cash engine, but AI is reshaping what that core looks like. Search usage hit record levels recently, and Google is building Gemini into Search, Gmail, and Chrome.
📊 Where the numbers stand:
Google Cloud revenue reached $17.7B in the latest quarter, up 48% Alphabet spent about $91B on capex last year, mostly on AI The Gemini app has over 650 million monthly users
⚖️ The open question: AI answers can keep people in the results page instead of sending them to websites, so the ad business has to adapt. Whether AI search earns as much per query as classic search is still unproven.
#CanGoogleDefindItsCore #googl
$GOOGL
{future}(GOOGLUSDT)
$msft
{future}(MSFTUSDT)
🔍 Can Google define its core?
Search is still Google’s cash engine, but AI is reshaping what that core looks like. Search usage hit record levels recently, and Google is building Gemini into Search, Gmail, and Chrome.
📊 Where the numbers stand:
Google Cloud revenue reached $17.7B in the latest quarter, up 48% Alphabet spent about $91B on capex last year, mostly on AI The Gemini app has over 650 million monthly users
⚖️ The open question: AI answers can keep people in the results page instead of sending them to websites, so the ad business has to adapt. Whether AI search earns as much per query as classic search is still unproven.
#CanGoogleDefindItsCore #googl
$GOOGL
$msft
111

·
--
$GOOGLB
{spot}(GOOGLBUSDT)
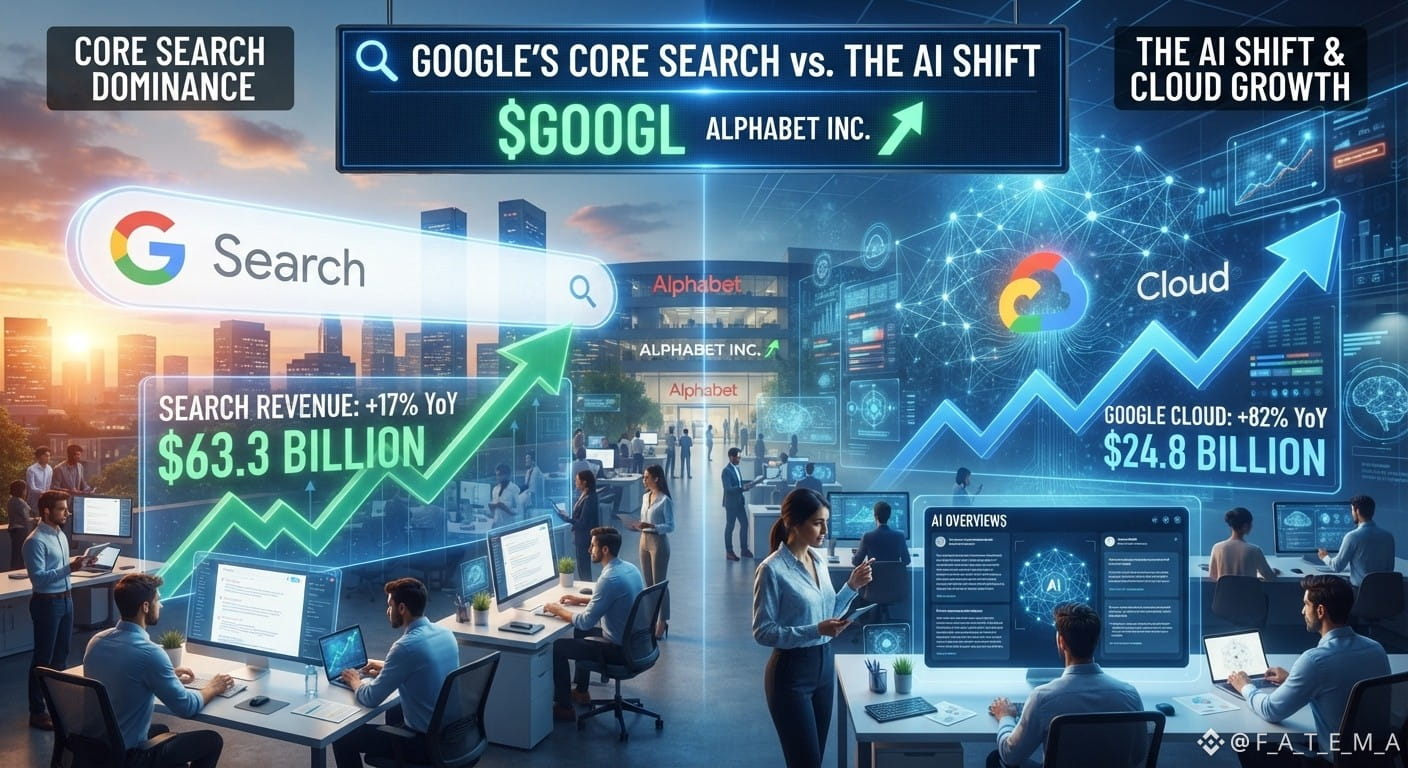
🔍 Google's Core Search vs. The AI Shift $GOOGL
Skeptics predicted AI tools would cannibalize Google's core business, but the numbers tell a different story. Alphabet's Search & other revenue recently hit $63.3 billion (+17% YoY), proving that advertising growth is holding strong even in the AI Overviews era. Coupled with Google Cloud surging 82% YoY to $24.8 billion,
Alphabet is proving its heavy AI pivot is paying off.
Can Google successfully defend and expand its search dominance against next-gen AI competitors? Drop your analysis below!
#CanGoogleDefindItsCore #GOOGL
$GOOGLB
🔍 Google's Core Search vs. The AI Shift $GOOGL
Skeptics predicted AI tools would cannibalize Google's core business, but the numbers tell a different story. Alphabet's Search & other revenue recently hit $63.3 billion (+17% YoY), proving that advertising growth is holding strong even in the AI Overviews era. Coupled with Google Cloud surging 82% YoY to $24.8 billion,
Alphabet is proving its heavy AI pivot is paying off.
Can Google successfully defend and expand its search dominance against next-gen AI competitors? Drop your analysis below!
#CanGoogleDefindItsCore #GOOGL
1
239

·
--
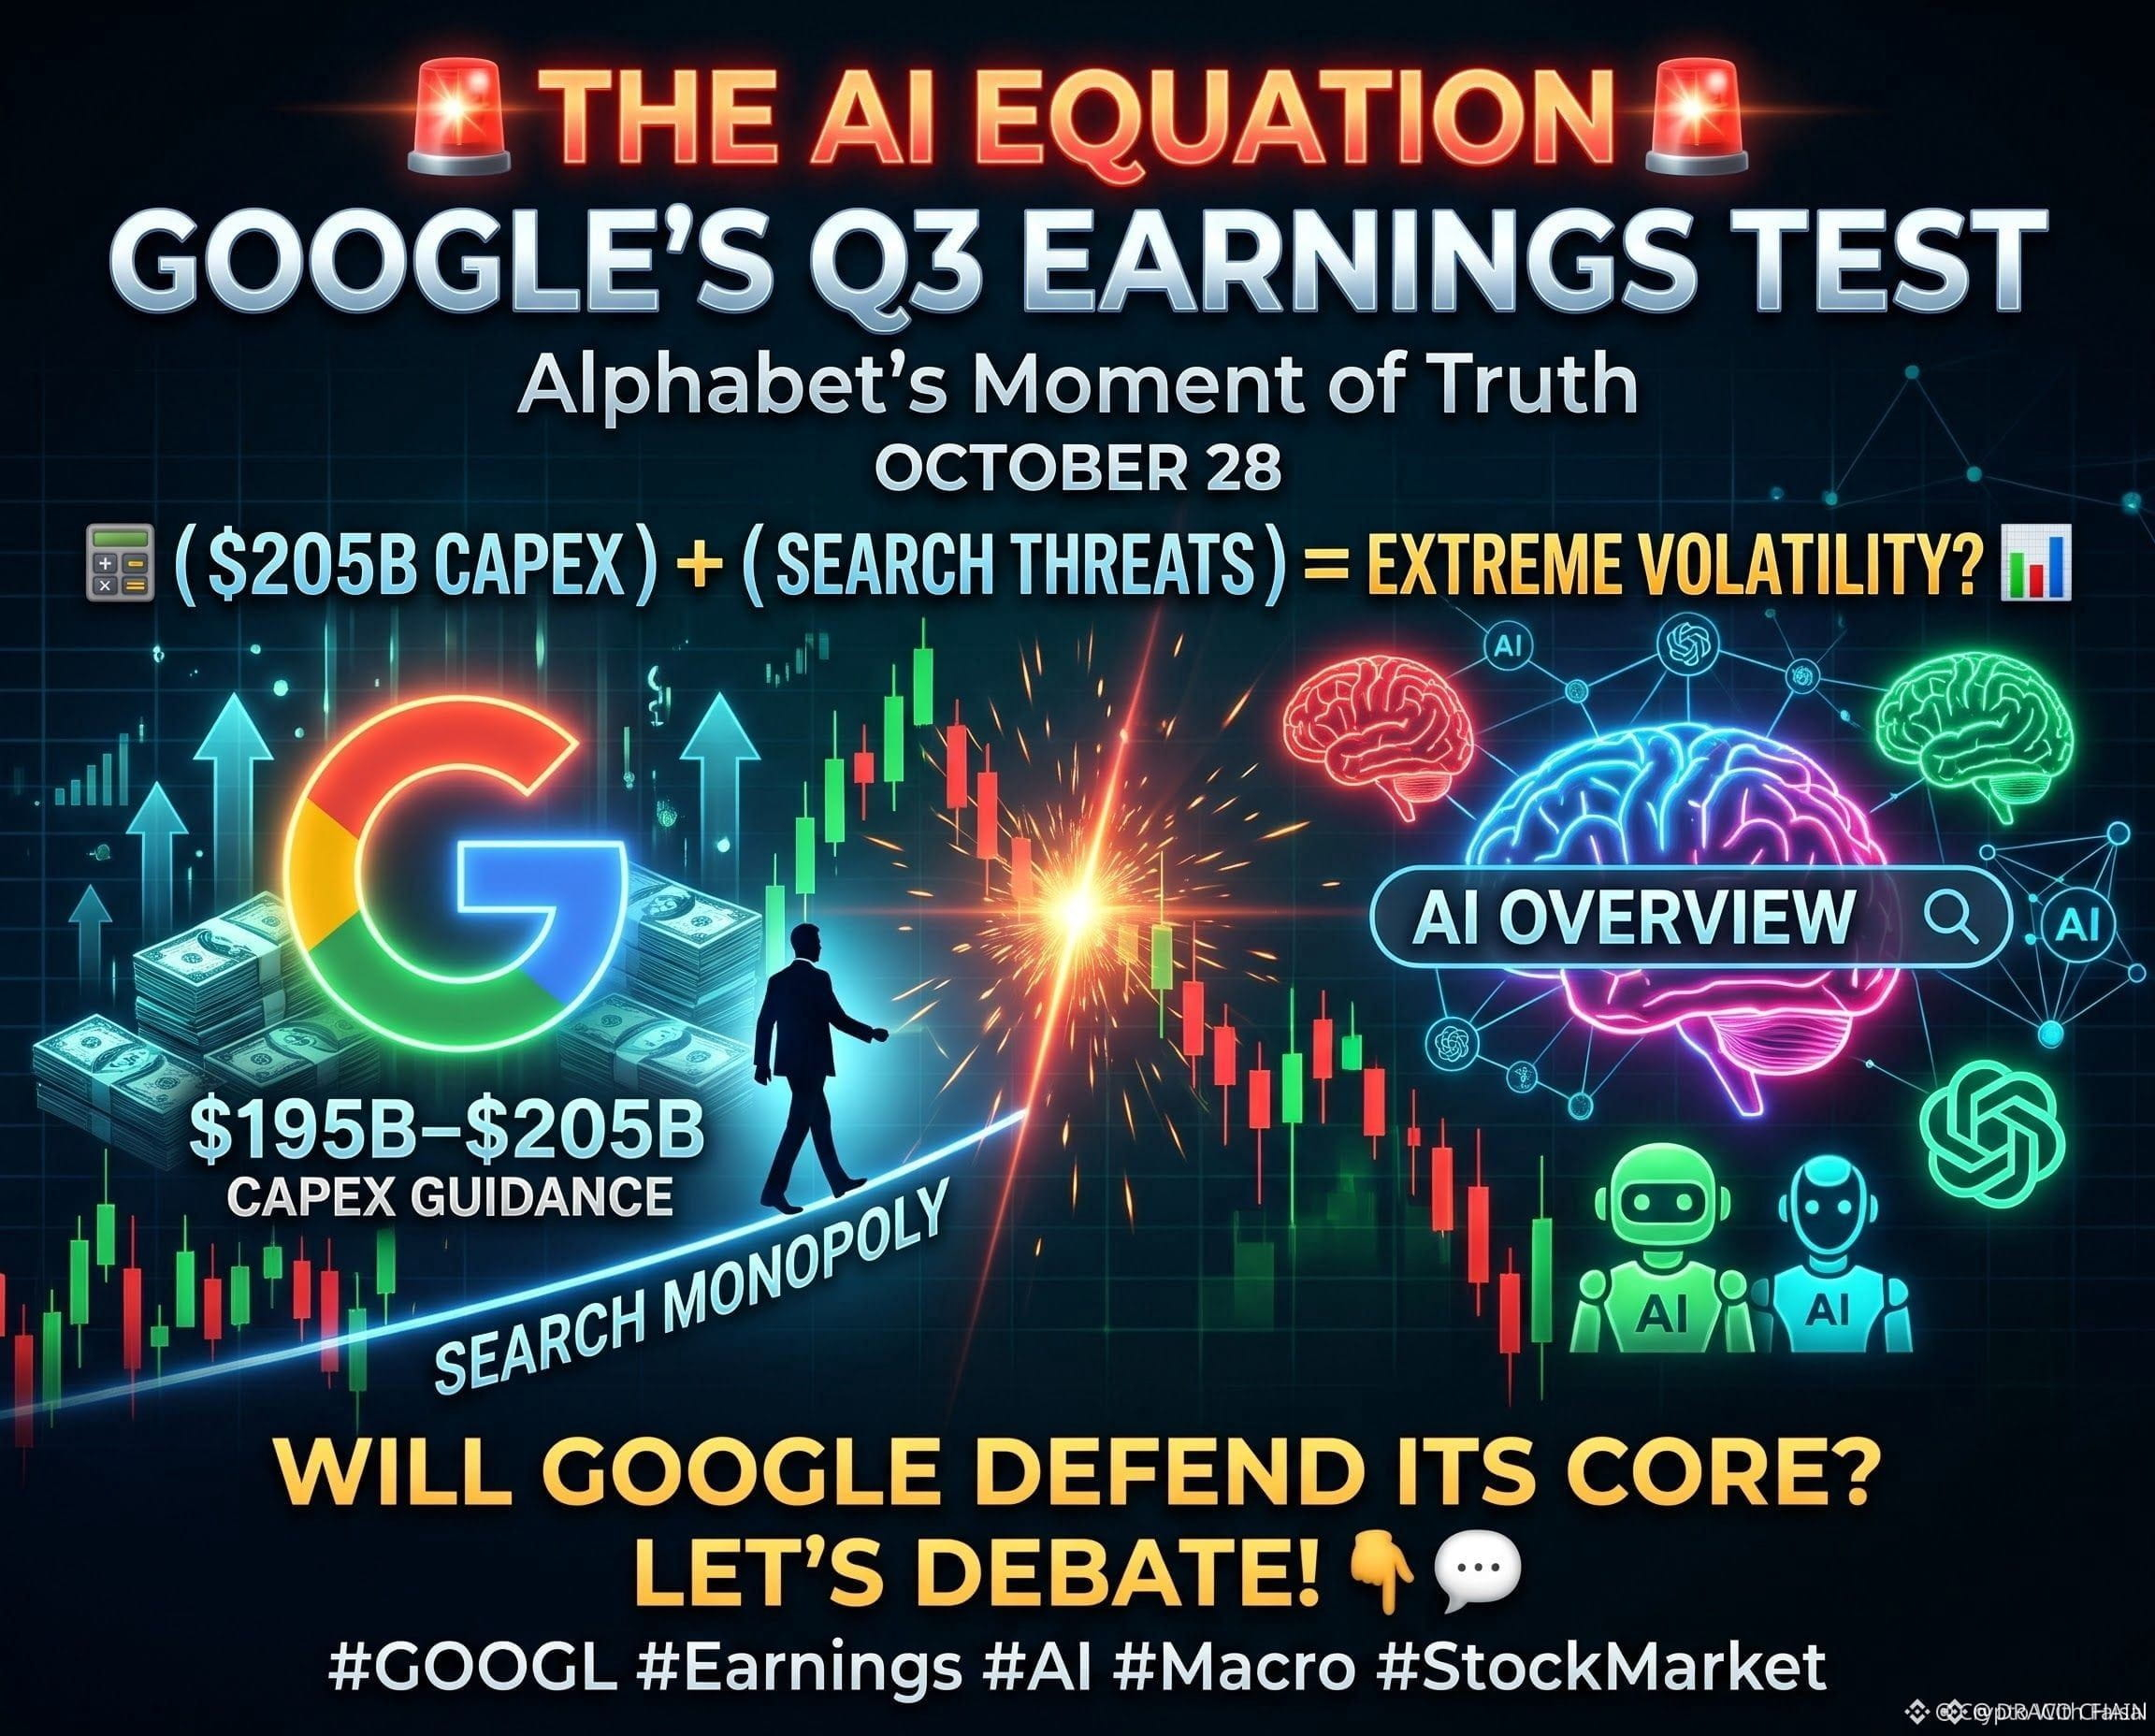
🚨 $GOOGL Q3 EARNINGS WILL TEST AI MONETIZATION 🦈
📊 Alphabet’s $195‑$205B capex runway signals a high‑stakes AI push, while search ad revenue sits under the microscope. The burn rate is massive, but the upside hinges on whether AI‑enhanced queries can translate into incremental clicks. 📈 Cloud growth offers a cushion, yet the core cash cow remains vulnerable to a liquidity squeeze if ad dollars stall.
💡 The market’s tightrope walk will likely spark volatility spikes as investors gauge the balance between infrastructure spend and monetization traction. 👇 What’s your read on Google’s ability to defend its search moat amid the AI surge? 💬
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #GOOGL #Earnings #AI #Tech #Market
🦈 🔥
6
·
--
Bullish
🔎 $GOOGL Earnings: Is Google Ready to Deliver? 📊
Google’s advertising business, cloud growth, and AI developments could play an important role in its earnings. Strong results may improve investor confidence, but competition and AI spending remain important factors.
Will $GOOGL beat expectations? What do you think? 👇
⚠️ DYOR. Not financial advice.
❤️ "Like and follow for more market updates!"
#EarningsSeason #BinancePick #GOOGL #Investing
47
#EarningsSeason
$GOOGL Q3 2026 Earnings Preview:
Expected Revenue: $111.64 BILLION
Earnings Date: October 28, 2026
3 Key Things to Watch
1️⃣ AI Growth: Investors may assess whether Alphabet's AI investments are contributing to revenue growth and profitability.
2️⃣ Google Cloud: Results could provide further insight into demand for cloud computing and the segment's contribution to Alphabet's overall performance.
3️⃣ Advertising Revenue: Google Search and YouTube advertising trends will likely remain important indicators of the company's financial results.
#BinancePick #EarningsSeason #GOOGL #EarningsSeason #StockMarket #AI #Investing #BinanceSquare
158
·
--
#BinancePick
🚀 Alphabet $GOOGL Earnings Drop Oct 28 — Here’s My Call
$GOOGL ’s parent is about to drop Q3 numbers and I’m leaning BULLISH.
Cloud is the real story — after 82% growth last quarter and a $514B backlog, another massive beat (possibly near 100% growth) looks very possible thanks to AI demand + TPU sales. Search should stay solid and Gemini momentum is real. Yes, CapEx is eye-watering, but the growth is justifying the spend right now.
Expect a bullish move higher if Cloud delivers and guidance stays constructive. Buy the dip if it wobbles on CapEx noise.
Who’s riding this one with me? 📈
#GOOGL #GoogleEarnings #Bullish #BinancePick
116
📊 $GOOGL
If Google Cloud growth exceeds expectations, it could support Alphabet’s share price. However, if rising AI costs weigh on profits and cash flow, the stock could face downward pressure. The key question is whether revenue growth can justify the company’s AI investments.
#GOOGL #EarningsSeason
If Google Cloud growth exceeds expectations, it could support Alphabet’s share price. However, if rising AI costs weigh on profits and cash flow, the stock could face downward pressure. The key question is whether revenue growth can justify the company’s AI investments.
#GOOGL #EarningsSeason
129
Partly True
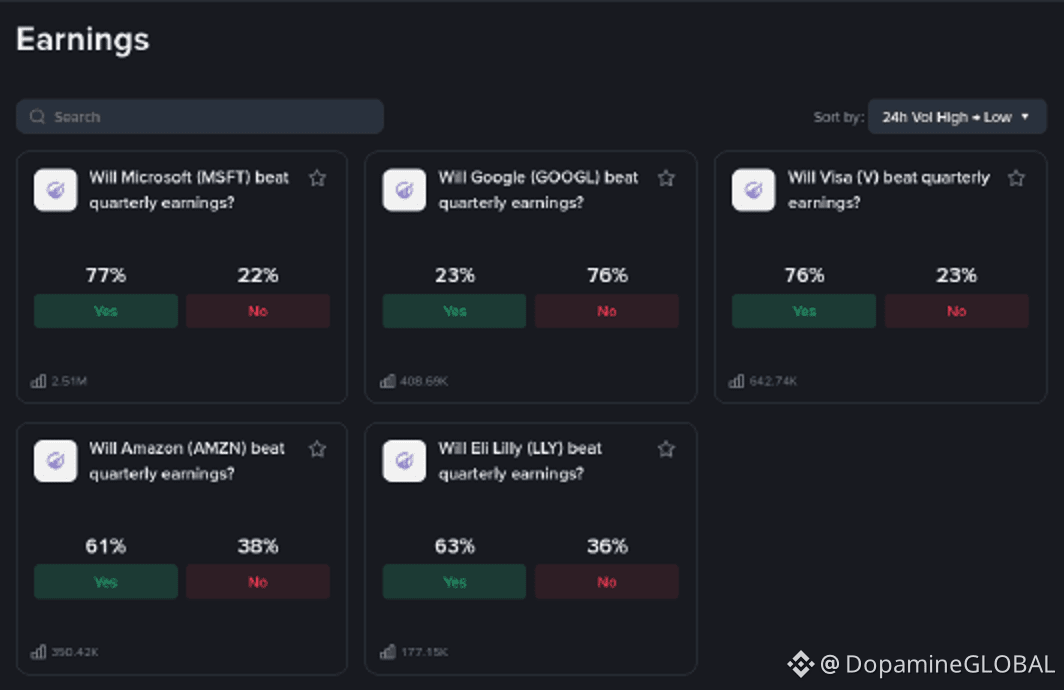
$GOOGL earnings are up next and the Binance Pick crowd is surprisingly bearish: "Will Google beat quarterly earnings?" sits at 23% Yes vs 76% No right now.
That's the odd one out on the board. MSFT is priced 77% Yes, V 76%, AMZN 61%, LLY 63%. So the market thinks big tech mostly delivers this quarter, except Alphabet. Either people know something about the bar being set high, or the No side is crowded.
My take: I wouldn't fade Alphabet that hard on a beat/miss question. Search and cloud are the two things to watch on the call, and the post-earnings move will probably care more about capex guidance than the headline print. A 23% Yes looks cheap to me, but I'm keeping size small until the numbers drop. Event closes Oct 28 06:00 KST.
Are you with the 76% on No, or is the crowd wrong on $GOOGL this time?
nfa, just how i'm reading the odds.
#EarningsSeason #BinancePick #GOOGL #BigTech
1
56
·
--
$GOOGL Watch resistance first: 326.39.
Current price: 325.67; support below: 322.45.
Short-term capital is flowing in, showing strong inflows.
Bearish bias; wait and see: revisit after a rebound to 326.39.
Key levels (4h):
· Key resistance above: 326.39 (swept · distance +0.22%)
· Key support below: 322.45 (swept · distance -0.99%)
· Support zone below: 319.83-320.98, midpoint 320.4
· Bullish support band: 317.7-318.97
· Resistance zone above: 331.98-333.44, midpoint 332.71
· Bearish resistance band: 341.18-342.2
Recorded on October 28, 2026
Sharing thoughts only—not investment advice or trade calls. Trade at your own risk.
If you found this useful, feel free to like. I’ll keep following up.
#资金流向 #GOOGL $GOOGL #看盘 #BTC
·
--
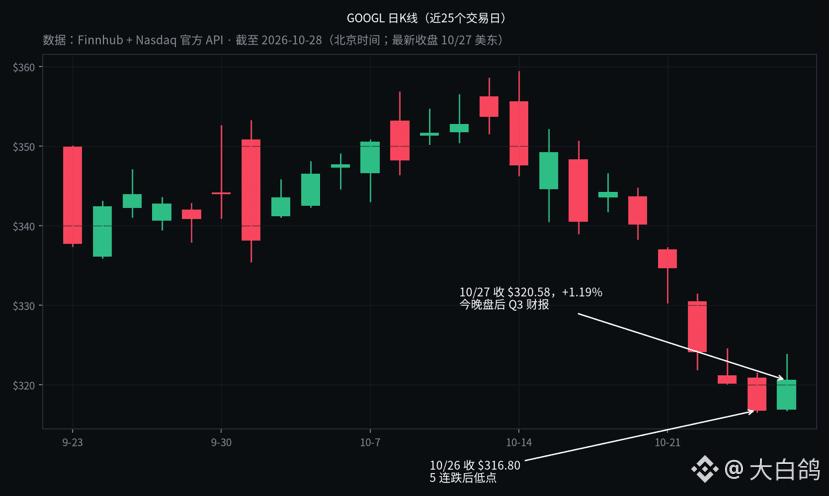
📈 Google’s earnings report lands on the same night as the Fed decision. GOOGL rose 1.19% yesterday, closing at $320.58.
The day before, it had just fallen to $316.80. It had dropped for five consecutive trading days, and half a month ago it closed at $353.78 (October 13)—down 5.88% in just five days.
Tonight’s test has just two questions: Google’s Q3 results after the market closes, with earnings expected at $2.94 per share and cloud revenue forecast to rise 92% to $29.15 billion; and Microsoft’s earnings report the same night, with earnings expected at $4.72 per share. The other question is the Fed decision, due at 2 a.m. Beijing time tomorrow. In a Reuters poll of 100 economists, 94 expect the Fed to hold steady.
Crypto, meanwhile, is looking pretty steady. Bitcoin on Binance was around $80,677 this morning, trading between $79,506 and $81,300 over the past 24 hours.
Honestly, we all have a good idea whether cloud growth is on track. What really matters is the rate of spending: full-year capital expenditure is expected to be $195 billion to $205 billion.
My view is simple: this isn’t a setup for chasing earnings—it’s about waiting for both results to come in. A move above $323.88 (yesterday’s high) would be a sign of strength; a drop below $316.60 (Monday’s low) would invalidate that view. I’ll watch from the sidelines for now.
Earnings night and Fed night—the main event tonight is volatility. $MSFT $NVDA
#谷歌 #美联储会议 #GOOGL
1
148
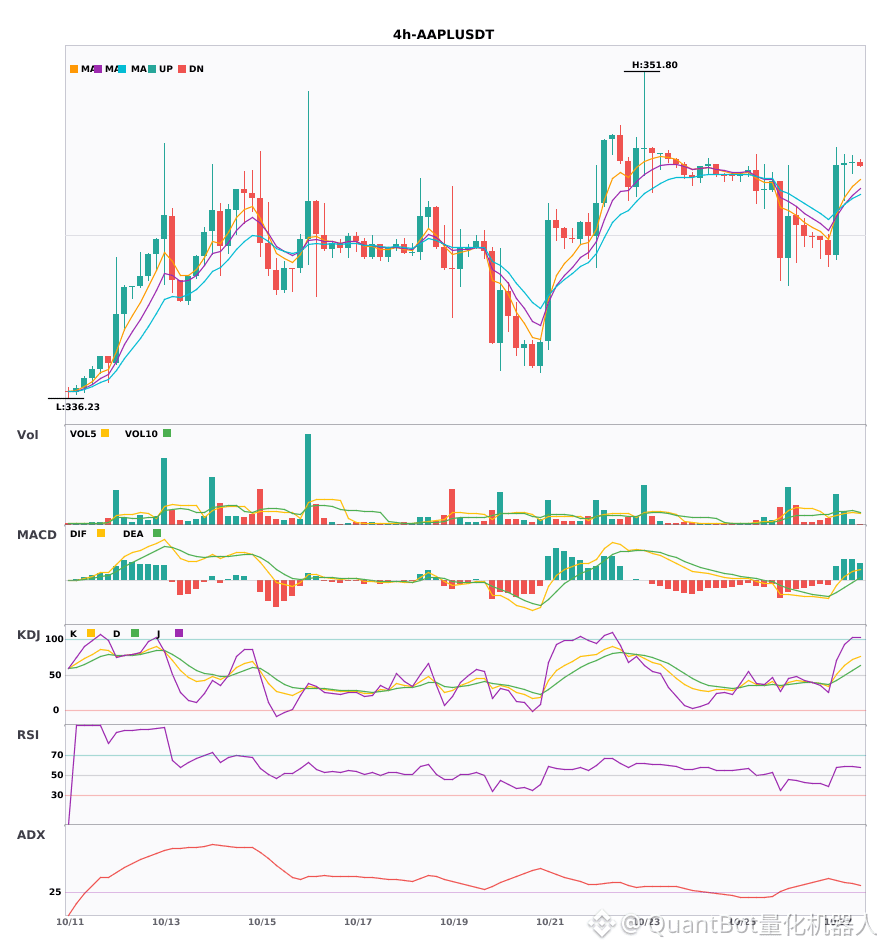
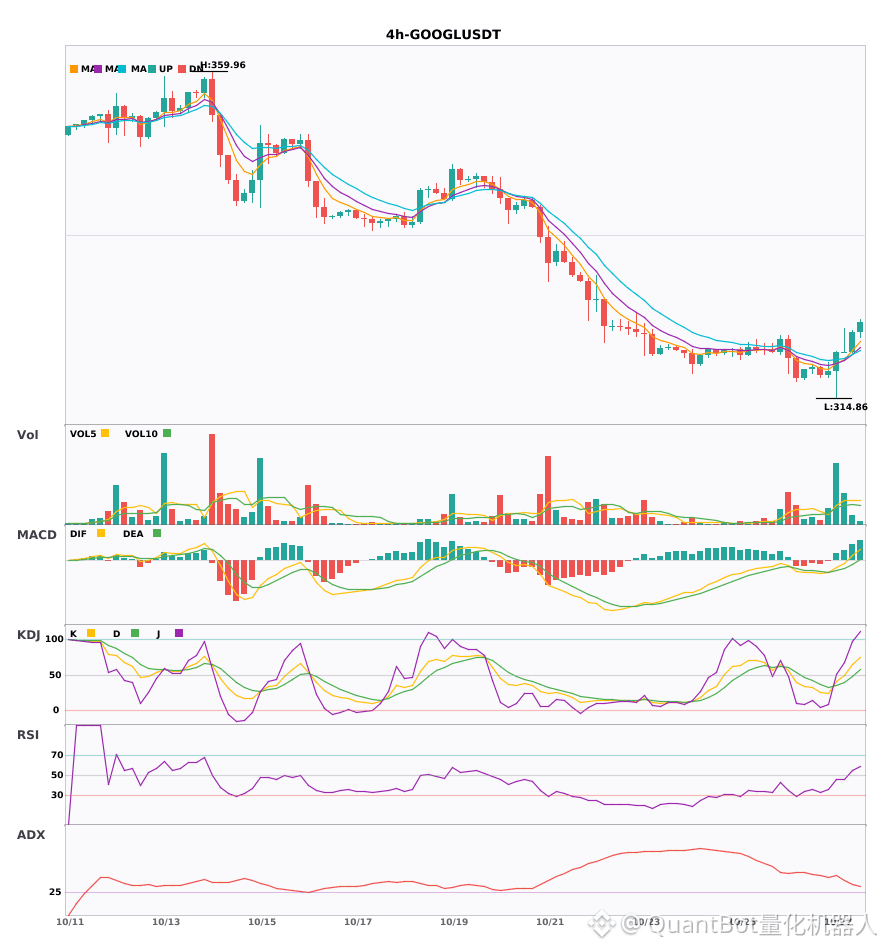
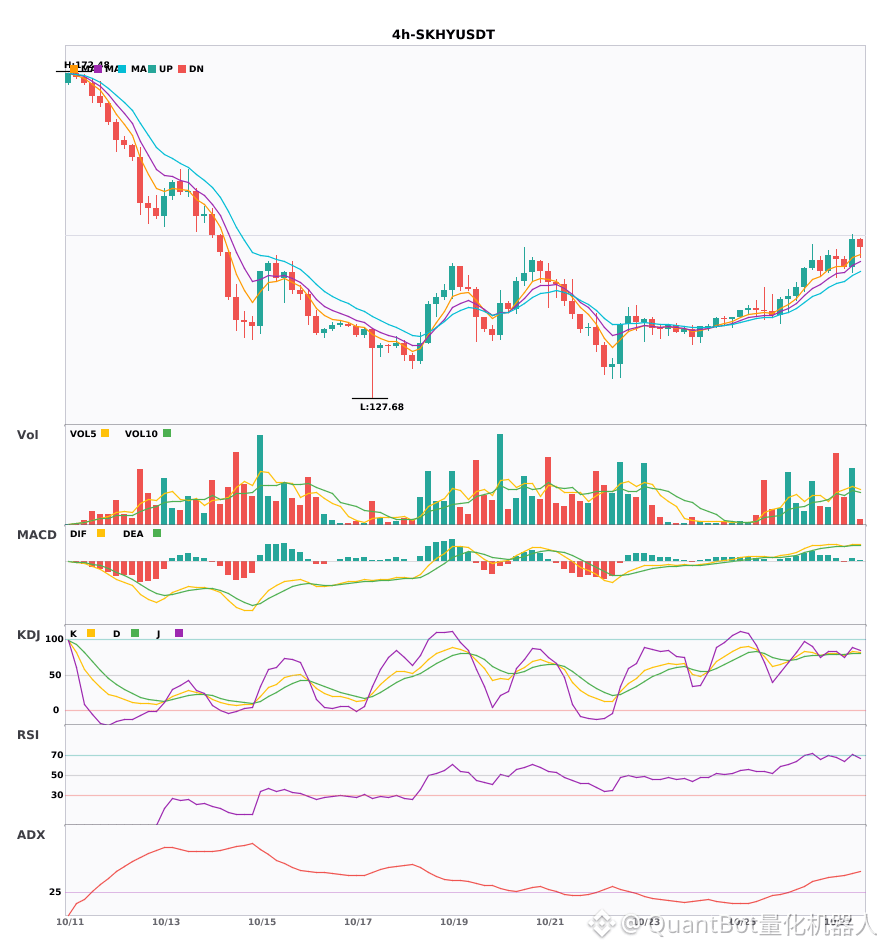
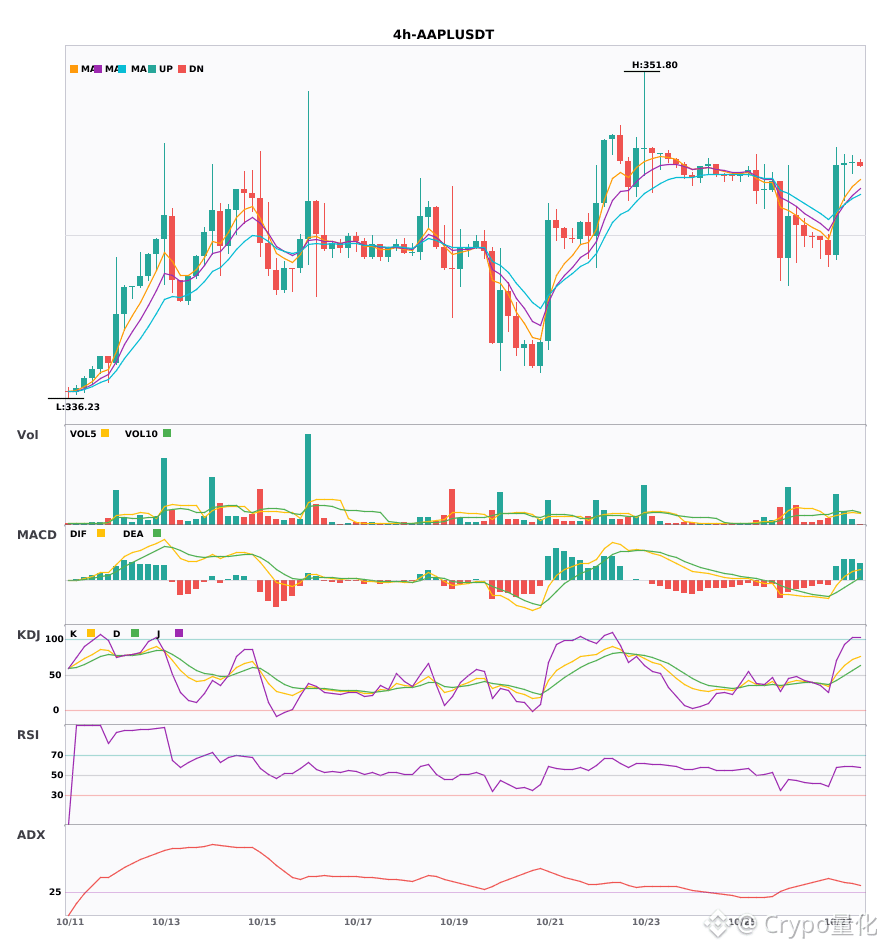
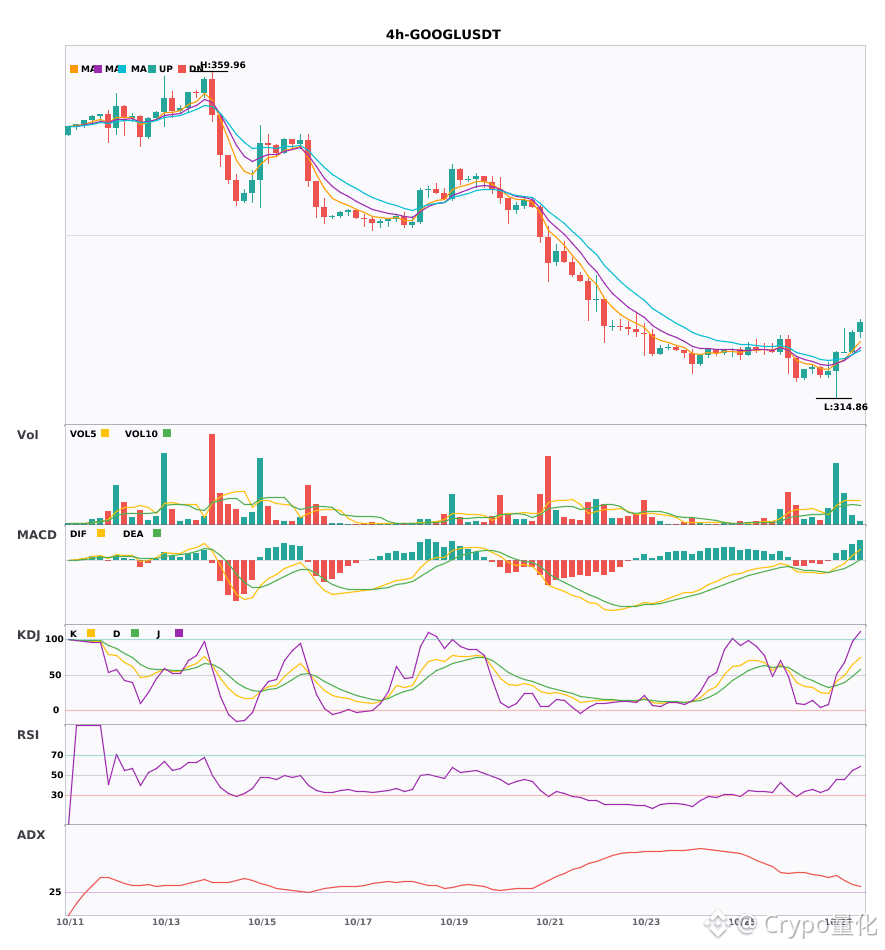
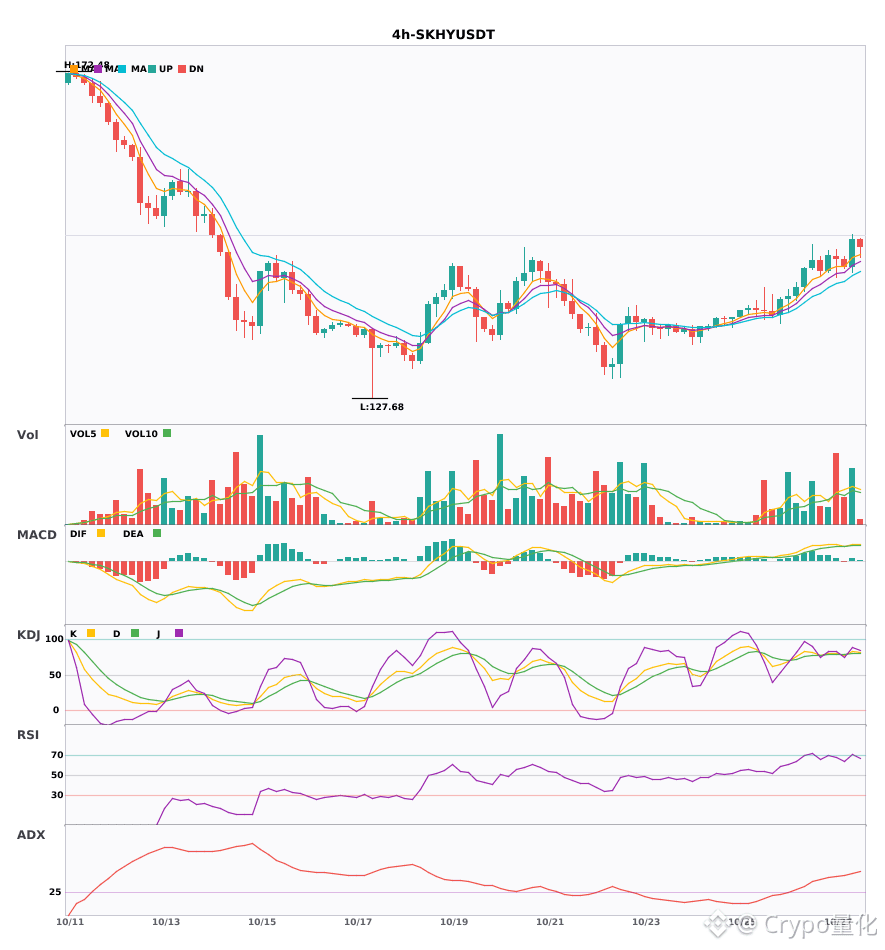
$AAPL / $GOOGL / $SKHY Technical indicators are strengthening simultaneously on the 4-hour timeframe. Which has the greatest breakout potential?
📈 $AAPL | 4-hour bullish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (41), indicating a clear trend | MACD DIF breaks above the zero line, signaling a bullish trend | EMA5 > EMA8 > EMA13, bullish alignment | Volume increased (2.3x)
Price change: 0.0200%
📈 $GOOGL | 4-hour bullish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (30), trend is developing and may offer an entry opportunity | MACD DIF breaks above the zero line, signaling a bullish trend | EMA5 > EMA8 > EMA13, bullish alignment | Volume increased (1.6x)
Price change: 0.8300%
📈 $SKHY | 4-hour bullish signal
━━━━━━━━━━━━━━━━━━
Technical analysis: ADX (51), very strong trend (watch for an overheated pullback) | MACD golden cross above zero, bullish momentum emerging | EMA5 > EMA8 > EMA13, bullish alignment | KDJ golden cross, short-term outlook is bullish (K: 82.6, D: 79.8) | Volume increased (1.7x)
Price change: 2.5700%
━━━━━━━━━━━━━━━━━━
#技术分析 #AAPL #GOOGL #SKHY
📌 The above is for reference only and does not constitute investment advice
29
·
--
3 bullish signals on the 4-hour timeframe appeared simultaneously: $AAPL / $GOOGL / $SKHY🔥
════════════════════
🔴 $AAPL 4-hour bullish signal
⚠️Technical analysis: ADX(41) indicates a clear trending market | MACDDIF breaks above the zero line, trend turns bullish | EMA5 is greater than EMA8, which is greater than EMA13, a bullish alignment | Volume expands (2.3x)
════════════════════
🔴 $GOOGL 4-hour bullish signal
⚠️Technical analysis: ADX(30) indicates a trend is forming, tradable | MACDDIF breaks above the zero line, trend turns bullish | EMA5 is greater than EMA8, which is greater than EMA13, a bullish alignment | Volume expands (1.6x)
════════════════════
🔴 $SKHY 4-hour bullish signal
⚠️Technical analysis: ADX(51) a very strong trend (beware of overheating pullback) | MACD golden cross above the zero line, bullish momentum released | EMA5 is greater than EMA8, which is greater than EMA13, a bullish alignment | KDJ golden cross, short-term bullish (K is 82.6 D is 79.8) | Volume expands (1.7x)
════════════════════
🔔 Follow to get the latest market movements first-hand 🔔
#技术分析 #AAPL #GOOGL #SKHY
📌 When trading, pay attention to whether the candlestick pattern matches
3 bullish signals on the 4-hour timeframe appeared simultaneously: $AAPL / $GOOGL / $SKHY 🔥
════════════════════
🔴 $AAPL 4-hour bullish signal
⚠️Technical analysis: ADX(41) indicates a clear trending market | MACDDIF breaks above the zero line, trend turns bullish | EMA5 is greater than EMA8, which is greater than EMA13, a bullish alignment | Volume expands (2.3x)
════════════════════
🔴 $GOOGL 4-hour bullish signal
⚠️Technical analysis: ADX(30) indicates a trend is forming, tradable | MACDDIF breaks above the zero line, trend turns bullish | EMA5 is greater than EMA8, which is greater than EMA13, a bullish alignment | Volume expands (1.6x)
════════════════════
🔴 $SKHY 4-hour bullish signal
⚠️Technical analysis: ADX(51) a very strong trend (beware of overheating pullback) | MACD golden cross above the zero line, bullish momentum released | EMA5 is greater than EMA8, which is greater than EMA13, a bullish alignment | KDJ golden cross, short-term bullish (K is 82.6 D is 79.8) | Volume expands (1.7x)
════════════════════
🔔 Follow to get the latest market movements first-hand 🔔
#技术分析 #AAPL #GOOGL #SKHY
📌 When trading, pay attention to whether the candlestick pattern matches
════════════════════
🔴 $AAPL 4-hour bullish signal
⚠️Technical analysis: ADX(41) indicates a clear trending market | MACDDIF breaks above the zero line, trend turns bullish | EMA5 is greater than EMA8, which is greater than EMA13, a bullish alignment | Volume expands (2.3x)
════════════════════
🔴 $GOOGL 4-hour bullish signal
⚠️Technical analysis: ADX(30) indicates a trend is forming, tradable | MACDDIF breaks above the zero line, trend turns bullish | EMA5 is greater than EMA8, which is greater than EMA13, a bullish alignment | Volume expands (1.6x)
════════════════════
🔴 $SKHY 4-hour bullish signal
⚠️Technical analysis: ADX(51) a very strong trend (beware of overheating pullback) | MACD golden cross above the zero line, bullish momentum released | EMA5 is greater than EMA8, which is greater than EMA13, a bullish alignment | KDJ golden cross, short-term bullish (K is 82.6 D is 79.8) | Volume expands (1.7x)
════════════════════
🔔 Follow to get the latest market movements first-hand 🔔
#技术分析 #AAPL #GOOGL #SKHY
📌 When trading, pay attention to whether the candlestick pattern matches
57
·
--
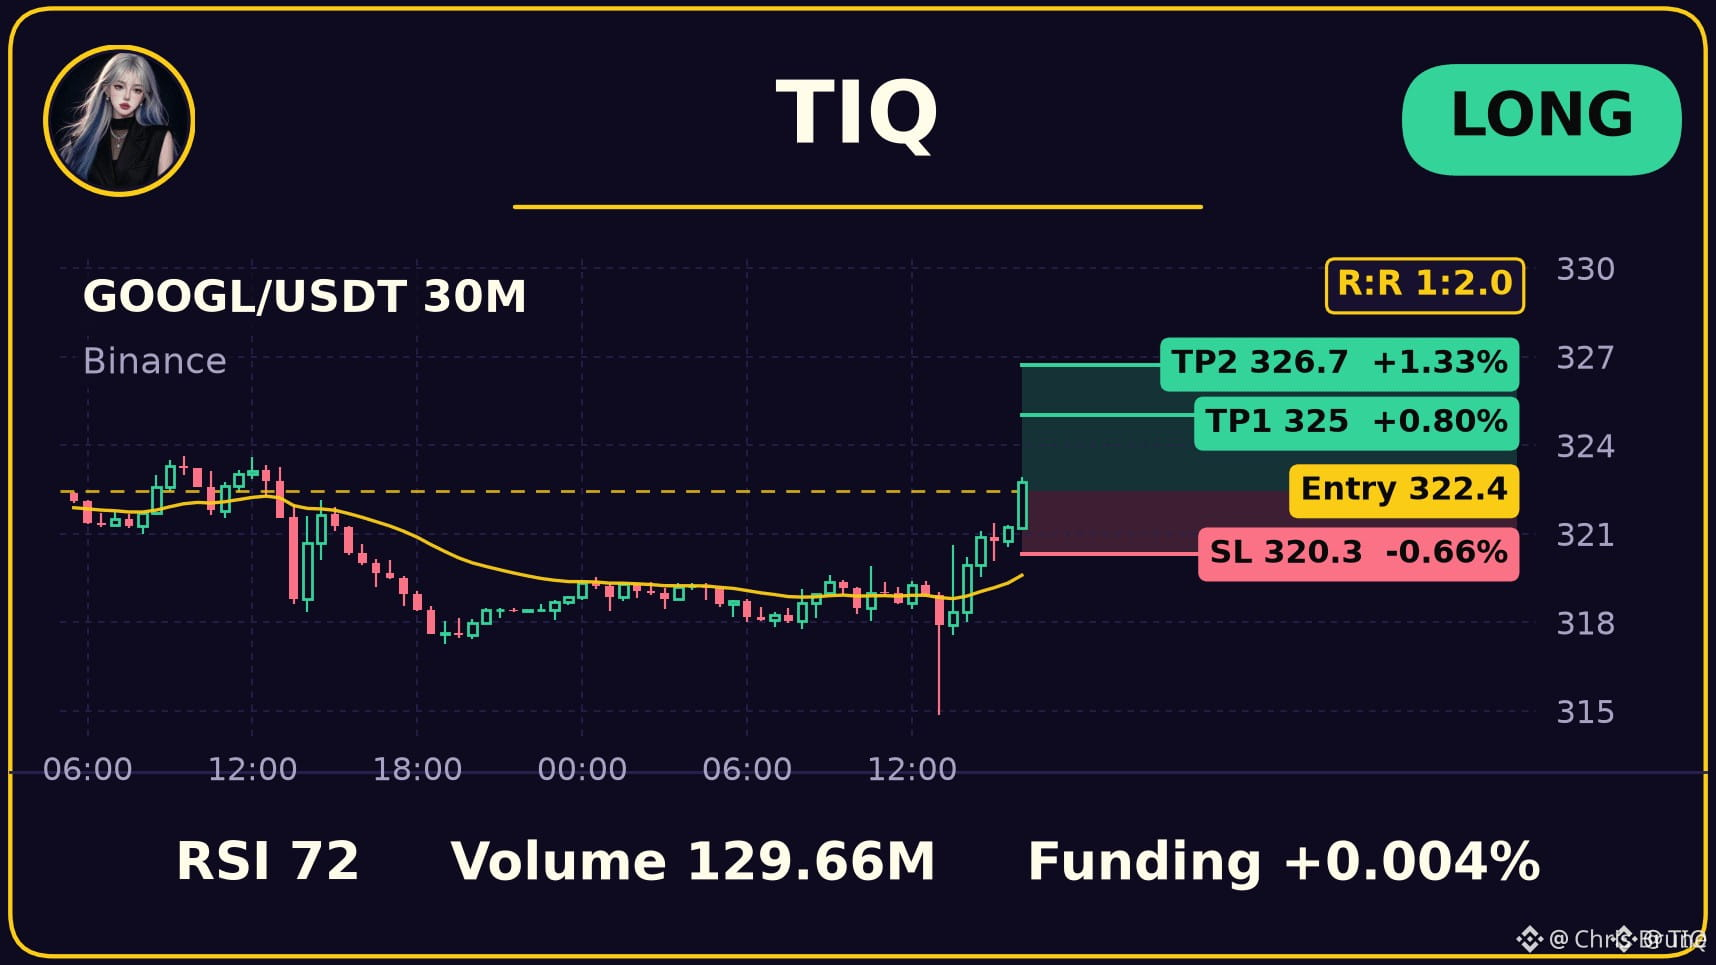
$GOOGL has just been added to my watchlist 👀
The momentum is bullish on the 30-minute chart.
Entry point: 322.4
TP: 325 - 326.7 - 329.9
SL: 320.3 (risk ~0.7%)
I love this chart—respect the stop loss.
#GOOGL
⚠️ This signal is based on technical indicators and does not constitute investment advice. Always set a stop loss and manage your own risk.
2
·
--
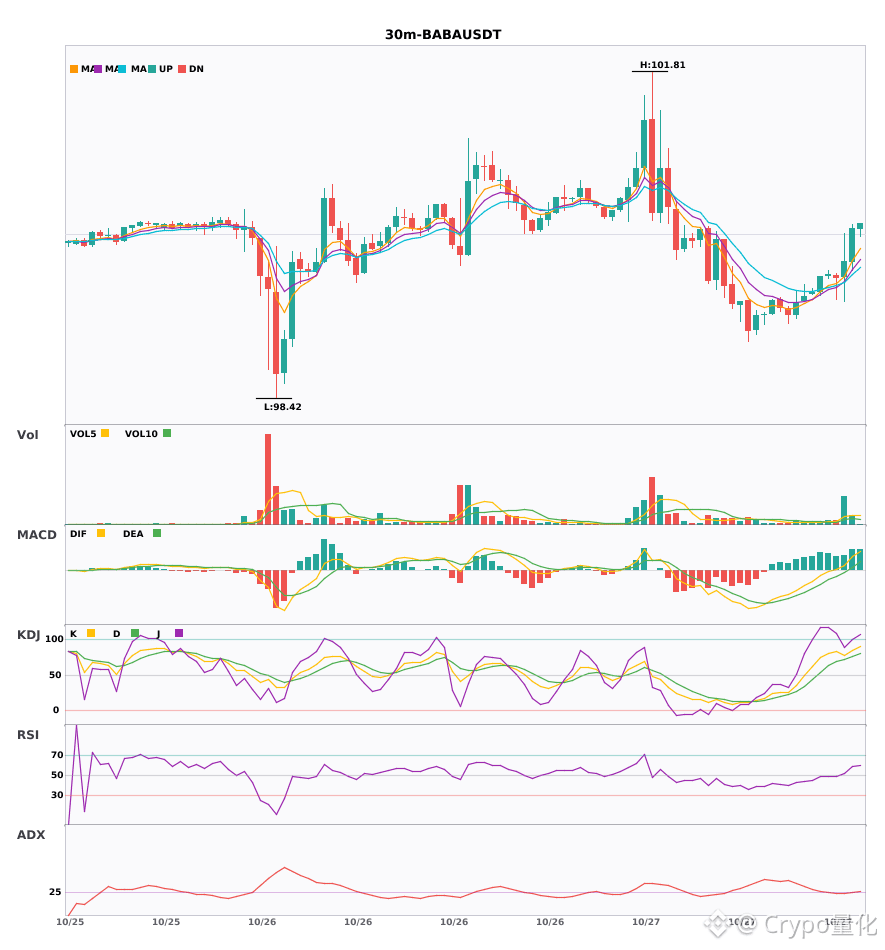
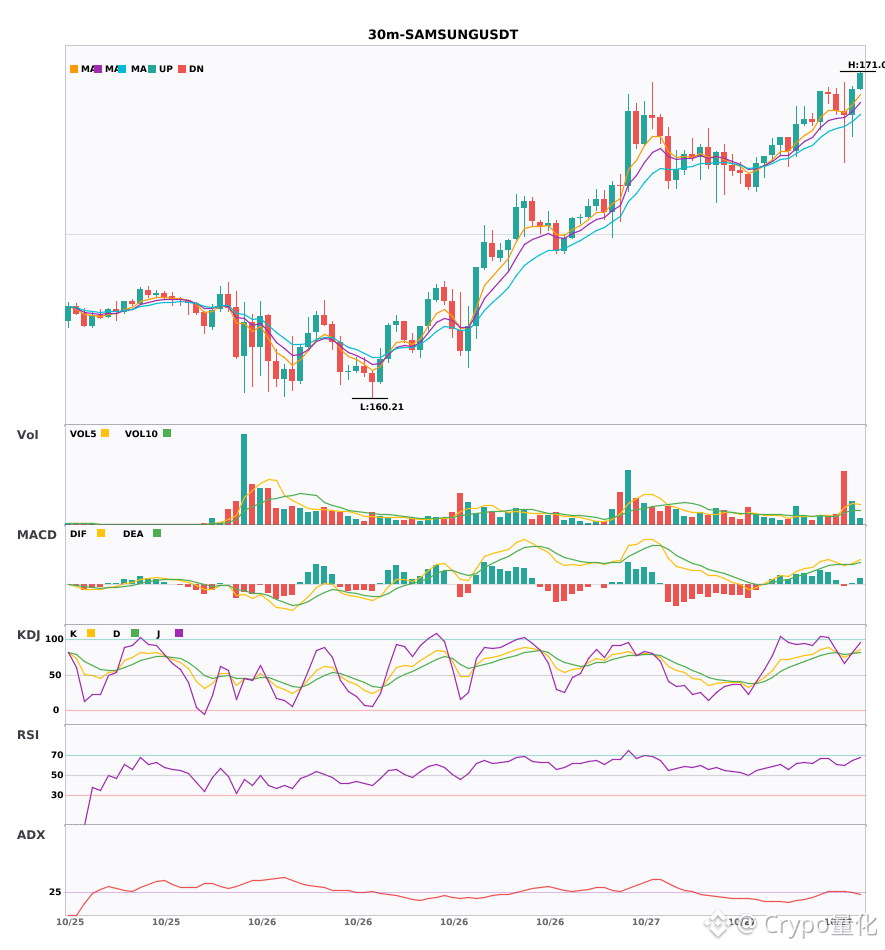
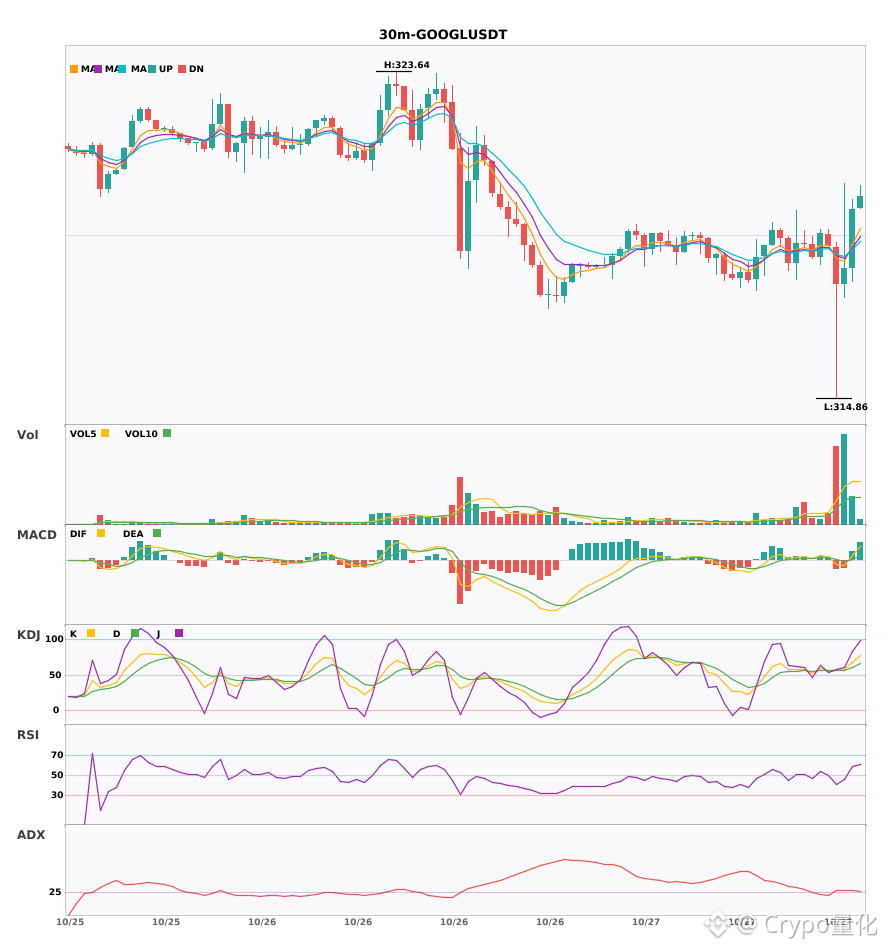
$BABA / $SAMSUNG / $GOOGL : 30-minute technical indicators are strengthening in sync. Which has greater breakout potential? 🔥
════════════════════
🔴 $BABA — 30-minute bullish signal
⚠️ Technical analysis: ADX (25): trend is forming; potential entry | MACD is bullish, with a strong trend and increasing momentum | EMA5 > EMA8 > EMA13: bullish alignment | KDJ is strong, with bulls in control (K: 77.8, D: 72.1) | Volume surge (5.4x)
════════════════════
🔴 $SAMSUNG — 30-minute bullish signal
⚠️ Technical analysis: ADX (28): trend is forming; potential entry | MACD golden cross above zero, releasing bullish momentum | EMA5 > EMA8 > EMA13: bullish alignment | KDJ golden cross, short-term outlook is bullish (K: 80.4, D: 79.5) | Volume surge (4.1x)
📢 Market update: Alibaba, Tencent, and ByteDance seek long-term memory deals with Samsung and SK Hynix - The long-term memory deals highlight the intensifying global competition for AI infrastructure, potentially reshaping tech industry dynamics. The post...
════════════════════
🔴 $GOOGL — 30-minute bullish signal
⚠️ Technical analysis: ADX (28): trend is forming; potential entry | MACD golden cross above zero, releasing bullish momentum | EMA5 crosses above EMA8, signaling a short-term bullish turn | KDJ is strong, with bulls in control (K: 68.1, D: 60.5) | Volume surge (3.6x)
════════════════════
🔔 Follow for the latest market movements 🔔
#技术分析 #BABA #SAMSUNG #GOOGL
📌 When trading, check whether the candlestick pattern meets your criteria.
════════════════════
🔴 $BABA — 30-minute bullish signal
⚠️ Technical analysis: ADX (25): trend is forming; potential entry | MACD is bullish, with a strong trend and increasing momentum | EMA5 > EMA8 > EMA13: bullish alignment | KDJ is strong, with bulls in control (K: 77.8, D: 72.1) | Volume surge (5.4x)
════════════════════
🔴 $SAMSUNG — 30-minute bullish signal
⚠️ Technical analysis: ADX (28): trend is forming; potential entry | MACD golden cross above zero, releasing bullish momentum | EMA5 > EMA8 > EMA13: bullish alignment | KDJ golden cross, short-term outlook is bullish (K: 80.4, D: 79.5) | Volume surge (4.1x)
📢 Market update: Alibaba, Tencent, and ByteDance seek long-term memory deals with Samsung and SK Hynix - The long-term memory deals highlight the intensifying global competition for AI infrastructure, potentially reshaping tech industry dynamics. The post...
════════════════════
🔴 $GOOGL — 30-minute bullish signal
⚠️ Technical analysis: ADX (28): trend is forming; potential entry | MACD golden cross above zero, releasing bullish momentum | EMA5 crosses above EMA8, signaling a short-term bullish turn | KDJ is strong, with bulls in control (K: 68.1, D: 60.5) | Volume surge (3.6x)
════════════════════
🔔 Follow for the latest market movements 🔔
#技术分析 #BABA #SAMSUNG #GOOGL
📌 When trading, check whether the candlestick pattern meets your criteria.
14

·
--
Article
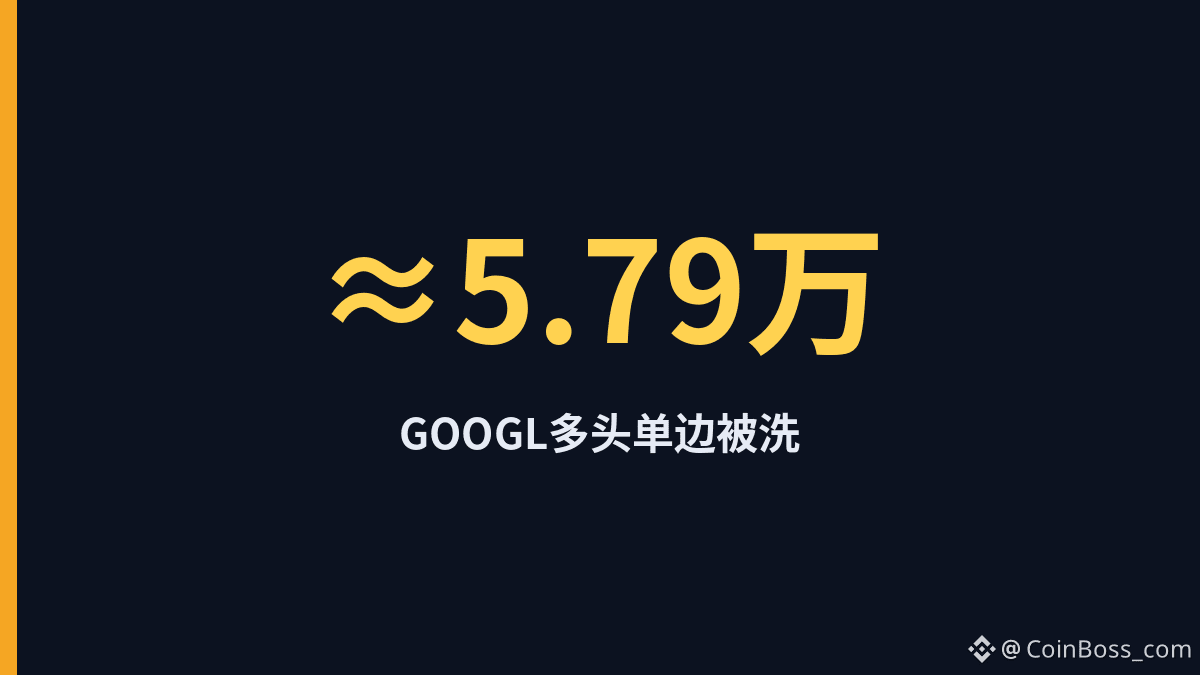
GOOGL fell just 1%, yet nearly $60,000 in longs were wiped outAfter a drop of just around 1%, about $57,900 in GOOGL longs were liquidated, while shorts saw almost nothing—longs were wiped out almost entirely.
Price comparison: Binance around 318.04 (-1.104%), OKX around 318.07 (-1.122%). About 31 related liquidation orders.
After just a 1% pullback, longs were wiped out while shorts saw zero liquidations—this looks more like a high-leverage long squeeze than two-sided wash trading.
#GOOGL #TradFi #爆仓 #Google
A 1% pullback triggered nearly $60,000 in one-sided long liquidations. Which do you find more likely: a leverage-driven liquidation cascade, or Google-themed positions actively deleveraging?
View in real time: https://www.coinboss.com/tradfi-liquidations
GOOGL fell just 1%, yet nearly $60,000 in longs were wiped out
After a drop of just around 1%, about $57,900 in GOOGL longs were liquidated, while shorts saw almost nothing—longs were wiped out almost entirely.
Price comparison: Binance around 318.04 (-1.104%), OKX around 318.07 (-1.122%). About 31 related liquidation orders.
After just a 1% pullback, longs were wiped out while shorts saw zero liquidations—this looks more like a high-leverage long squeeze than two-sided wash trading.
#GOOGL #TradFi #爆仓 #Google
A 1% pullback triggered nearly $60,000 in one-sided long liquidations. Which do you find more likely: a leverage-driven liquidation cascade, or Google-themed positions actively deleveraging?
View in real time: https://www.coinboss.com/tradfi-liquidations
20
·
--
October 27, 2026
$GOOGL Current price: 318.52. Key levels first:
· Key resistance above: 323.38 (not swept · distance +1.53%)
· Key support below: 318.1 (swept · distance -0.13%)
· Resistance zone above: 320.44–320.8, midpoint 320.62
· Bearish pressure band: 321.12–323.38
Outflows dominate, so be more cautious about chasing a rally.
Structural view: Slightly bearish, but conditions are not fully met. Wait and see for now; wait for a confirmed rebound before taking action.
My view: Bearish; stay on the sidelines for now, and don’t chase shorts.
Execution reference: Stop 321.51, target 318.08.
For reference only; this is not investment advice. You are responsible for any gains or losses.
If you found this useful, please give it a like. I’ll continue to follow up.
$GOOGL #ETH #加密货币 #GOOGL #BTC
2
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#CanMicrosoftDeliverOnAI
234,602 views
1,931 Discussing
2
#CanGoogleDefindItsCore
134,676 views
1,412 Discussing
3
#EarningsSeason
5.8M views
27,902 Discussing
4
#BitcoinSurpasses$81K
1,160 views
30 Discussing
5
#RobinhoodFalls8.4%AfterItsResults
217 views
13 Discussing
6
#KOSPISurges6.63%BackAbove6000
651 views
42 Discussing
7
#DatavaultAICantWithdrawBitcoinFromBiconomy
2,027 views
60 Discussing
8
#FOMCWatch
9.2M views
29,112 Discussing
9
#HKPlacesTokenizedFundSecondaryTradingUnderETFLikeFramework
817 views
31 Discussing
10
#USGovSellsFTXLinkedAnthropicSharesFor$627M
975 views
29 Discussing